Small Cap Value Report (24 Sep 2015) - RM2, TUNG, WYG, NWF, PNA

Good morning!
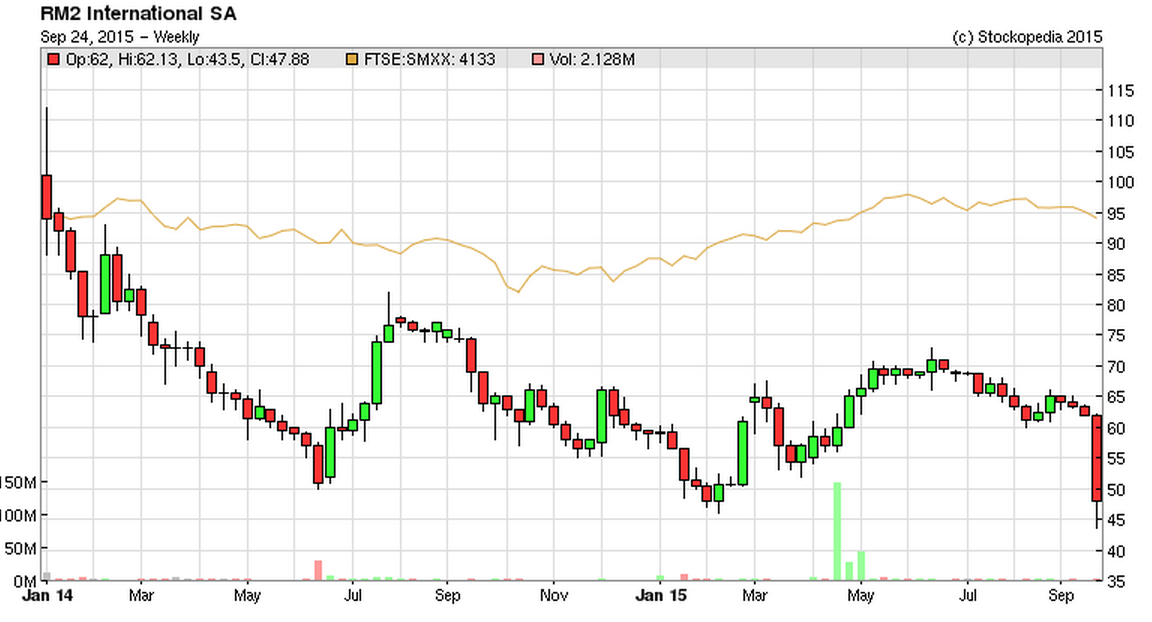
RM2 International SA (LON:RM2)
Share price: 44.6p (down 23% today)
No. shares: 322.7m
Market cap: £143.9m
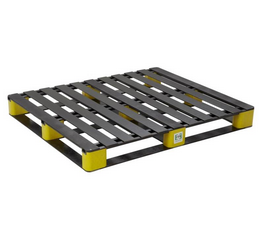 Profit warning - this is a new company for me. It listed in Jan 2014, raising $218m, to fund its plans for creating a business manufacturing and selling/leasing a new type of pallet (clicking on the picture on the right will take you through to the company's website).
Advantages claimed (over conventional wooden pallets) are durability, strength, suited for automated warehouses, etc.
The trouble is, it's a blue sky share - so inevitably things go wrong - as per the update today - which explains a technical problem (with a friction coating) has necessitated changing to a gel-based coating. This means delays & reduced sales/profits:
As a result primarily of the decision to change to gel coating, the Company will not achieve the substantial upswing in production that had been expected to begin in Q3 this year and accelerate through Q4. This means that revenue and production numbers for the full year will be significantly below previous guidance. Production is expected to be not less than 2.5 million pallets in 2016, with a production run rate at the end of the fourth quarter of 2016 of c. 300,000 pallets per month. Based on current contracts and trials as well as discussions underway, the Company is confident of being able to deploy profitably all the pallets produced.
More detail is given. It sounds like a delay, rather than a disaster.
So what's the financial position like?
2014 results - these look scary! $2.0m revenue, and a $37.9m operating loss before IPO costs, which are obviously one-off in nature, and a $42.4m operating loss after IPO costs.
So the only thing that really matters, is how much cash is left? Unrestricted cash was $80.9m at end of 2014, which might sound a lot, but given that the cash burn is extremely high, and it sounds as if material revenues are still some way off, then the cash position could now be looking wobbly - it depends on how much they've burned through this year - will there be enough cash to support things through to large-scale production in 2016? What if more problems emerge & further delays?
Alarmingly, the company didn't release its calendar 2014 results until 15 June 2015 - that's a very sloppy reporting schedule, and late results is a big red flag to me - if things are going well, companies are keen to get the figures & narrative out. 5.5 months is ridiculous, especially as it's essentially a start-up business, so the figures should not be difficult to prepare.
The 2014 results contain these comments about cash burn, and the need for additional financing (presumably to fund leasing deals for end users of the pallets);
During the year under review, as previously reported, there was very limited production due to the factory move and other changes associated with a transition to a mass production facility and processes. During this period we have paid for all the plant and machinery and whilst there is some further capital expenditure being incurred in 2015, this is largely focused on areas in which the new production facility management have identified significant efficiency opportunities. Building a mass production facility with such production levels also led to very high operating costs relative to production which are expected to become much lower in the future with increased production.
Although the Company retains strong cash balances ($82.8 million at 31 December 2015), as actual production levels build up, capital requirements increase. As a result, we are reviewing financing proposals and are confident of putting satisfactory facilities in place to fund expanded production against contracts.
My opinion - I challenge anyone to show me a single blue sky company listed in the UK where things have gone smoothly, and in accordance with the original forecasts. It just doesn't happen! This is why investing in blue sky stuff is such a disaster area in nearly every case - people buy the story, then things go wrong, and before you know it, you've lost over half your money (if you're lucky - often far worse). Yet we're still suckers for a good story - not just PIs, the Institutions if anything are even worse at lapping up these blue sky things.
Forecasts are always far too optimistic, and for some bizarre reason, few blue sky companies which float seem to build in contingency reserves for problems & delays - surely such a requirement is a basic principle they should all follow?
Current market forecasts show a $18.8m loss for 2015, which presumably now will be revised down to a considerably bigger loss. Production figures are given above for 2016, but I don't know what the product sells for, or what the gross margin is - that is essential info in assessing whether this is a viable business or not.
It looks much too high risk to me, to consider dabbling. I'd want to see comfort that cash levels are adequate, and that an emergency Placing is not needed. Although I note that Directors have been repeated, heavy buyers of shares (well into 7-figures of £) which gives confidence that they seem to believe this project will work out well.
So it could be quite interesting, but it would need properly researching, to understand the economics of making these pallets, what margins can be achieved, the market size, barriers to entry for competitors - how easy is it to copy?, how much overheads will be, what customers think of the product, and what the financing arrangements will be, credibility & track record of management, are just a few things needing researching off the top of my head.
The trouble is, broker notes which give us this type of information are all too often essentially sales puff trying to induce us to buy the shares, rather than realistic forecasts.
Overall then, it's not yet clear to me whether this is a viable business or not, so I'll let other people take the risk. My portfolio returns greatly improve when I steer completely clear of blue sky stocks. It's usually best to hold fire until all the problems have been ironed out, and sales are underway & building strongly. The shares can often be cheaper at that stage too, since repeated disappointments & difficult fundraisings can leave bulls disillusioned, and unwilling to buy any more shares when they're at rock bottom, just at the point things are actually starting to work.
Tungsten (LON:TUNG)
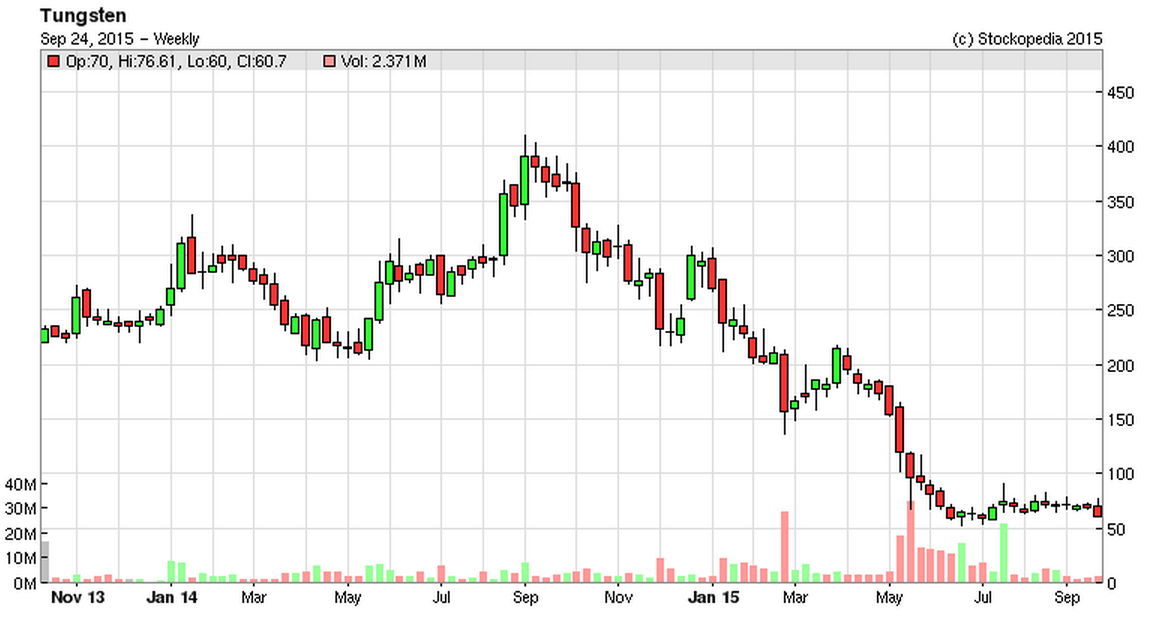
Share price: 61.2p (down 7.3% today)
No. shares: 125.4m
Market cap: £76.7m
Trading update - this company follows on rather well from RM2, as it's another jam tomorrow thing that has gone wrong - not least because Mr "billions & trillions" Truell ramped investor expectations & the share price into the stratosphere, and has failed to deliver anything like the original forecasts so far. So what does the company say today?
The e-invoicing business is heavily loss-making, but should act as a feeder for the Tungsten Early Payment service - so I'm looking for progress on early payment primarily. It doesn't look like much has happened there - the figures are still tiny;
We now have 238 suppliers registered to use Tungsten Early Payment with 89 live who have financed £62 million of invoices.
The numbers need to be running well into the £billions before this business starts to look interesting, so they've only really scratched the surface so far. I'm concerned that it's taking so long.
To meet our growth plans we need to increase the pace of bringing suppliers onto the Network, sign-up more new buyers to join the network, secure further buyer renewals at enhanced pricing and new suppliers to Early Payment. We have strong buyer and supplier pipelines and excellent relationships with our buyers who want to work more closely with us. We need to ensure each of these are fully leveraged over the remainder of the financial year to meet our targets.
This concerns me, as it's a list of the things they need to do, rather than what is actually happening!
Mention is made of revenues being 20% higher this year in May-Aug 2015 (the company has a 30 Apr year end), but for a heavily loss-making company, it's guidance on profit/(loss) that investors want, and there doesn't seem to be any steer given on that front in today's statement. I'll read it again, just to double-check. This bit does indicate cost-reduction measures are at least on the agenda;
We have further changes to make, notably in supplementing the new leadership team to accelerate supplier on-boarding and our Early Payment offering. In addition, we are undertaking a detailed review of our operating cost base to help us meet our growth plans in an efficient manner. We will provide a further update on the expected outcomes from this process when we report our 2016 Interim Results in mid-December.
Outlook - referring investors back to a previous announcement, without repeating it, is a bit annoying.
The Board remains optimistic about prospects for the current financial year and reiterates the outlook provided at the time of our full year results in July. We are grateful to shareholders for the £17.5 million equity raised at the start of the financial year and the Board continues to believe that the Company has sufficient cash resources to be able to deliver its current strategy.
It's good that they think cash resources are sufficient, but given that this has been misjudged in the past, and proven incorrect, then I personally am placing (geddit?!) little reliance on this.
Looking back at the Jul 2015 outlook statement, the key points seem to be;
- Revenue is expected to grow in 2015
- Revised pricing should increase margins
- Some one-off costs have now been paid for (implying cost reductions)
- More spending on sales & marketing
My opinion - I made the classic investing mistake last year, of getting too excited about the story here, and then over-paying for hyped-up shares, before successful delivery of the potential had even begun.
It seems to me that Tungsten management is executing very badly, and that the huge potential for the early payment product seems to be largely fizzling out. So really that just leaves a loss-making e-invoicing business, and a shell of a bank which doesn't seem to serve much purpose (although presumably could be sold to bolster cash reserves, if needed), other than providing regulatory licences in some countries possibly.
In my view, they might need to come back to the market for more cash next year, and the whole thing now looks nothing like the tremendously exciting story that was told to us with such enthusiasm, great gravity & self-importance by Mr Truell last year. Or at any rate, progress is costing a lot more, and going much more slowly than planned.
Will it ever reach profitability? Personally I doubt it now, but I'll keep an eye on the results every six months for signs of tangible progress.
Sorry this one hasn't worked out, and in particular I'm sorry if any readers were influenced by my former enthusiasm for this share. I got it wrong.
Sorry, I ran out of time, got side-tracked today. So here are just a few quick snippets of other announcements;
WYG (LON:WYG) - update on six months to 30 Sep 2015 from this building consultant. The key point is;
the Board expects profit before tax for the full year to be in line with recent market guidance.
There is more detail - UK sounds strong (order book up 15%). EU not so good, but expected to be better in H2. Looks potentially interesting, as the fwd PER is reasonable, at 11.6.
NWF (LON:NWF) - update says in line for Q1, and full year outlook is also in line with expectations.
Penna Consulting (LON:PNA) - looks interesting. Today's update says YTD profits are up "more than 25%" versus a strong equivalent period last year. Valuation seems reasonable, and StockRank is high, at 96. Worth a deeper look methinks!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned.
NB. These reports are just Paul's personal opinions, nothing more. So please always DYOR)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Re RM2 it's worth going back to the Admissions document to see what they said about markets. I'm not a pallet expert, but there are some anomalies to me.
1 They state they are only competing in the upper part of the supply chain with one-off or there & back trips, which must be a small part of the overall market, but all the market figures only seem to cover the whole pallet market and not just the sector they are shooting for.
2 They then talk about pallet use in retail sector and shop floor, which isn't the upper part of the supply chain.
3 They think the upper end of the supply chain uses lower quality pallets, but they are building big production facilities for glass fibre pallets: are they intrinsically cheaper than wood or are they relying on the weight advantage making them use less fuel? And then they add on high end pallet tracking to a cheap product??
Enough queries in my mind: it would be good for someone with real market knowledge to pull this apart.
Hello Paul
You looked at the final results for Air Partner (LON:AIR) on 30 Jan and concluded they could be worth a look. Do you have any comments on today's interims? They have been hitting StockRank highs for several months
Thanks
Colin
SCISYS (LON:SSY) have released interims today, following their earlier profit warning. It looks as though they have set things up nicely for a strong recovery in the second half. I'm long, as I have met the management and believe they know what went wrong and that they have the business under control.
Hi Paul, any chance you could take a look at TTR interim results out today? Tricky one to fathom out due to the impact of the POCT
Ref the amount of time taken to publish results: RDS published unaudited 2014 results on 29th January.
If they can do it....
Paul, Applause are due for apologising for your previous enthusiasm for Tungsten - it's never easy to say "I was wrong".
Don't be too hard on yourself. We all get some wrong and you have never claimed to be a tipster.
Keep up the good work.
Hi TheWatchmaker,
Kind remarks, thank you.
Actually, I genuinely don't find it difficult any more to admit I was wrong, on the occasions when I get it wrong. All investors get things wrong, so why on earth would you not admit it, if you clearly were wrong? That would just be obstinate, and pretty stupid really.
Admitting that something is a mistake, and chucking it out, is a very important skill for investors to attain, as it's not something that comes naturally to some people. Humans seem to have a tendency to want to cover up mistakes - but how on earth are you going to improve at anything, unless you are self-critical?
I keep two little notebooks by my desk. One is called "Share ideas", where I jot down key points about interesting-looking shares. The other is called "Mistakes" - where I jot down the key points that I should have spotted & reacted to, but failed to, with investments that have gone wrong.
Re-reading and adding to the "Mistakes" book is very important - as it helps remind you of things to look out for with other investments. I'm not saying we should beat ourselves up over our mistakes - quite the opposite really - admitting a mistake to yourself & others, and apologising to anyone who followed you into the stock (their decision, but it's still nice to apologise to them anyway) - is cathartic, and helps you draw a line under that mistake, and then learn the lessons from it.
I still regularly replay all the things that went wrong in 2008 through my mind, not for self-flagellation, but instead to make damn sure that those mistakes are not repeated!
We can't properly learn lessons from books, you have to actually experience the pain of a big loss to learn from it. People who don't admit their mistakes often never learn from them - you only have to go onto advfn bulletin boards to see people still completely in denial about the terrible investments they made, and blaming everyone but themselves for their utter stupidity. It's common to read people blaming short sellers - which again is all about blame transfer, as they lack the emotional maturity and intelligence to recognise & admit their own investing mistakes.
This is why you can often still exit from failing companies at a reasonable price - because the dumbest holders of the stock are actually buying more, rather than admitting that they screwed up.
All fascinating stuff - it's as much about the psychology, as the figures! Probably more so actually, in the short term anyway.
Regards, Paul.
Paul, you used to be a fan of Zanaga LON:ZIOC but I haven't seen you mention it for a while. Would it be safe to assume that you gave up on it?
Hi Richard,
Yes, I sold Zanaga iron ore many moons ago, approx 16-18p from memory, once it became clear that the project wouldn't stack up, in the light of the collapsing price of iron ore.
We discussed it here in the comments, at the time. You must have missed that discussion.
I would never continue holding a share, once the economic viability of the company had disappeared. That was simple to track, by following the price of iron ore online.
Zanaga looked great at $130 iron ore, but at $60 iron ore, it's moribund. Option value now, plus it has cash. So prob too late to sell now, might even be a speculative buy, who knows?
Regards, Paul
Another company with poor results today is Brainjuicer (LON:BJU). Stockranking is quite high.
Thanks for the lesson on Blue Sky companies. I will remember it and avoid.
RM2 International SA (LON:RM2) "the company didn't release its calendar 2014 results until 15 June 2015" - Should all companies not be obliged to report say within two months or three months at the most as part of the listing rules?
In France where my small private business is also registered, I have to submit my accounts to the tax authorities within 3 months of the year end.
One could argue with a larger company with a dedicated accounts department and modern accounting software that accounts could be produced very very quickly - 1 month even.
Hi Paul,
Not sure if they're strictly blue sky as they already have a product selling, but haven't Seeing Machines (SEE) consistently delivered in line with forecasts as they build the business?
Oh! And may I mention FEVR as a blue sky s/u that seems to be well away. I hope so, as I'm long...
Jasper,
Fevertree Drinks (LON:FEVR) isn't blue sky though. It's a growth company that came to the stock market with an established, growing product.
Blue sky is things that are essentially start-ups, with little to no turnover. So a new product that is being developed & launched. Once it's launched, and is growing, and shown to be viable, then a company stops being blue sky, and becomes a growth company. That's how I look at it anyway.
Regards, Paul.
Paul,
Any thoughts on the recent slide in Stanley Gibbons (LON:SGI) and the trading statement issued earlier this week. Given that 2014 full year results were impacted by a large trade that was slated for the new financial year, this seems a repeat of jam tomorrow promises from directors. The trading statement appears to be setting up for a poor 1H result.
James
Hi james1n,
I didn't bother looking at Stanley Gibbons (LON:SGI) - I've never liked the concept of making money from rare stamps, as it seems such a ridiculous concept in the technology era - I doubt future generations will covet stamps in the way collectors do today.
Also the company is dependent on individual, high value transactions - so will always be vulnerable to profit warnings.
Regards, Paul.
Paul,
I assume this is a typo on their part. It confirms the sloppy approach to reporting.
'Although the Company retains strong cash balances ($82.8 million at 31 December 2015) -'
Neil Woodfords fund has a 21% stake in RM2 so it certainly has backing
billytk,
Good point re Woodford holding 21% of RM2. So that would make it much more likely that the company could raise more equity funding if it needs it.
Also, the obvious point that Woodford has a superb track record, so the stock could well be a long-term winner if he's checked it out & likes it.
Although I don't think that necessarily makes it a good investment now. I'm happy to let Woodford take the initial risk, we can always join the party later, and maybe on more favourable terms. Plus we can sell if we want to, if something goes wrong, whereas he can't (not without collapsing the share price anyway).
Regards, Paul.