Small Cap Value Report (25 Jun 2015) - NXR, ANP, COST

Good morning!
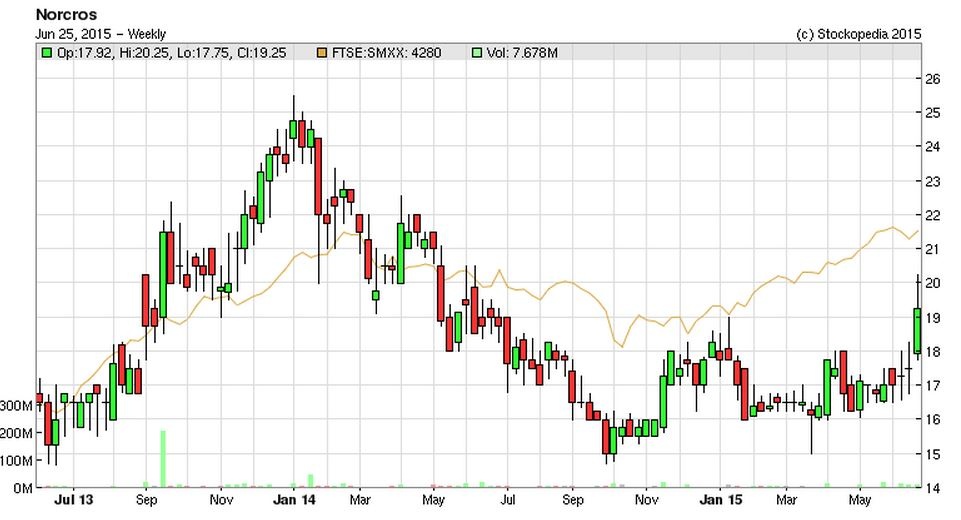
Norcros (LON:NXR)
Share price: 19.25p (up 6.2% today)
No. shares: 597.2m
Market Cap: £115.0m
(at the time of writing, I hold a long position in this share)
Croydex acquisition - Norcros made it clear in last week's results statement that it was on the acquisition trail, armed with a hefty bank facility, and today comes news of a deal to buy an Andover (Hampshire) based bathroom fittings company called Croydex Ltd. Please click here to recap on my article from last week which went through Norcros results for the y/e 31 Mar 2015 in some detail.
It looks a really good deal. Looking at their website, Croydex is a long-established (1919) company which designs & distributes a wide range of reasonably priced bathroom fittings and accessories. So this looks a good fit with Norcros's existing businesses.
I've had a look at Croydex's accounts at Companies House, and they look very good - nice clean accounts, a super balance sheet which includes a £2.3m long leasehold property. The company restructured (i.e. reduced costs) in 2013, and is now reaping the benefits. The Directors Report is positive, and speaks optimistically about the outlook.
Croydex reported a profit before tax of £2.1m for calendar 2014, on turnover of £19.9m.
The announcement from Norcros today refers to £2.6m profit before tax and shareholder costs, which I presume must mean Director salaries, which were £606k for the year. Croydex is currently owned by two families, the controlling one being the Browns - which reminds me of the joke about waving goodbye to the Browns, on their trip to the seaside! Rather fitting, given that one of the products that Croydex make is patented "Sit Tight" toilet seats. They look quite good actually.
I curse toilet seat makers every time I have to remove a wobbly or broken one with a hacksaw, as the bolts are all rusted tight, and aligning the hinges is so irksome! You think you've fitted it perfectly, then realise that it's at the wrong angle, and won't stay up. Anyway.
Croydex sell online though their website. and wholesale to both trade and retail buyers. It looks a nice business, and a good fit for Norcros, broadening the product range, and creating cross-selling opportunities.
The acquisition is being funded from Norcros bank facilities, with a cash cost of £20.8m initially, and a further £1.1m deferred for three years. This looks to be a retirement sale, as the majority shareholders are 64 and 66.
Forecasts - Numis have raised their EPS forecasts this morning, by 12% this year, and 14% next year. So that takes EPS to 2.3p (PER of 8.4) and EPS of 2.6p (PER of 7.4) next year. This seems an extremely pessimistic valuation to my mind, and the pressure for the shares to re-rate is only likely to increase after this sensible acquisition.
Net debt is forecast to increase to £29.7m by Mar 2016, but this is only 1.1x EBITDA, which is modest in my view.
My opinion - I like this deal. The price of Norcros has, in my opinion, been depressed by a constant seller in the market. So this overhang has also put off new buyers, and existing holders - you can sense the frustration with Norcros shareholders, and the less patient just drift away after a while, selling up when the shares refuse to re-rate.
However, in my view that's a mistake. A well-managed group, performing reasonably well (apart from UK retail) is not likely to stay on a single digit PER forever. So the overhang could be seen as an opportunity, for longer term investors to buy as much stock as we want, and then just sit back and collect in the divis while we wait to the overhang to eventually clear, and the stock to re-rate.
Numis have a target price of 30p, which I think is perfectly sensible. It won't happen overnight though, unless someone bids for Norcros. That seemed unlikely previously, but as we've seen with AGA Rangemaster (LON:AGA) and Thorntons (LON:THT) recently, it now seems that big pension deficits are not deterring takeover approaches any more. If you're an American company on a PER of 20+, where do you find more growth to justify that rating? The obvious answer is to come to the UK and buy up something on a PER of 8, and hope that the pension deficit will sort itself out in the long run.
Anyway, all good re today's announcement, as far as I'm concerned. Note that Croydex does not have a pension deficit itself. So as Norcros group grows, its legacy pension issues become a smaller part of the larger group, which is worth bearing in mind.
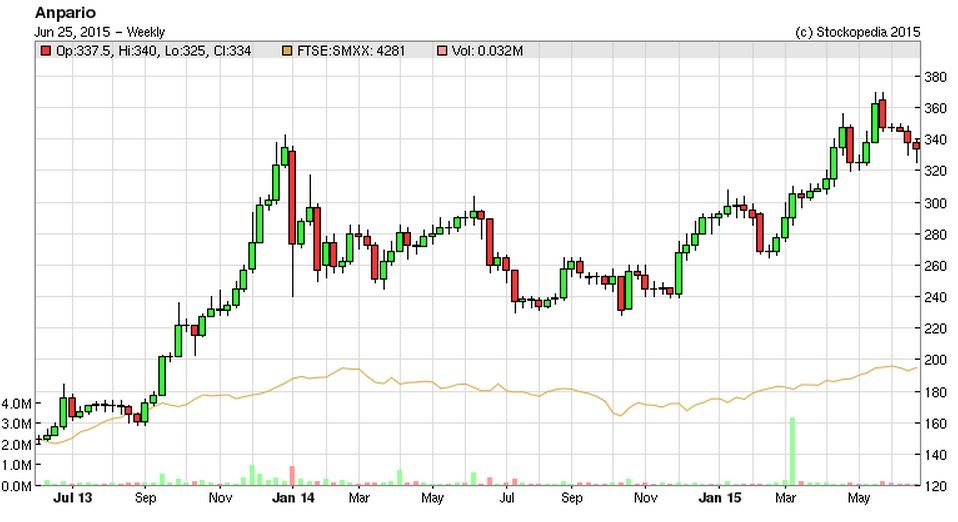
Anpario (LON:ANP)
Share price: 334p (up 0.5% today)
No. shares: 21.6m
Market Cap: £72.1m
AGM trading update - Chairman Richard Rose (same as Crawshaws) says that Anpario "continues to be on track to meet its profit expectations..." for calendar 2015.
The sale of the organic feed business has reduced turnover, but they are focusing on higher margin specialist feed additives.
There was £7.8m of cash at 24 Jun 2015.
Valuation - as you can see from the Stockopedia graphics, it's on a rolling forward PER of 20.1 times, and looks expensive on every other valuation metric too:
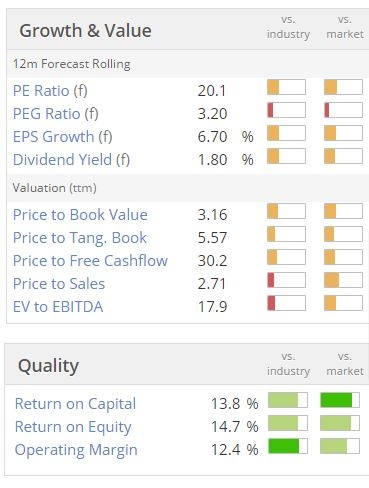
That's fine if the company has the potential to grow its earnings & cashflows considerably in the future. I'm not averse to paying a PER of 20, for companies with a competitive advantage, and excellent growth potential.
The historic graphs here look very good:
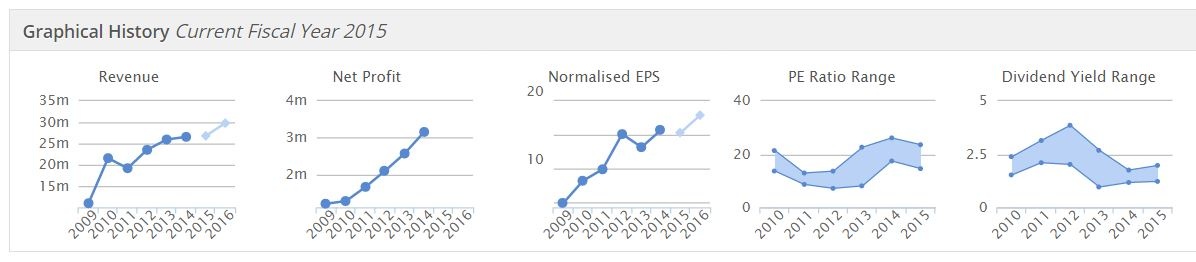
Although as you can see from the fourth graph, the PER rating range has risen a lot in recent years, so the market is now pricing in a lot more growth into the share price than before. That leaves it vulnerable to a sharp correction, if the growth in earnings disappoints at any stage.
My opinion - I'm not convinced risk:reward is necessarily attractive at this sort of valuation. There again, that's for investors to decide yourselves, by delving into the products & markets that Anpario supply. Clearly investors are feeling bullish about the company's prospects, which is why the shares are valued at 20 times forecast earnings.
It's got an excellent balance sheet too, with cash now representing nearly 11% of the market cap, so adjusting out cash would bring the PER down to about 18, which isn't quite so stretched.
Personally, I'd probably be top-slicing if I held this stock, after such a good run, and with a valuation that now looks pretty full. Equally, there's a lot to be said for just riding out the short term ups and downs, and holding for the long term, if you think the company will be a long term winner. There are merits in both strategies. Your money - your choice!
Costain (LON:COST)
Share price: 336p
No. shares: 102.0m
Market Cap: £342.7m
Trading update - a solid update today from this engineering contracting group, saying they are "on course to deliver a result for the year in line with the Board's expectations".
The order book has risen by £0.2bn to £3.7bn in the last six months. The group seems to be in a good position, as they fixed their balance sheet a little while ago with an equity fundraising, giving it a strong position as a preferred bidder.
My opinion - this looks a potentially interesting stock, although contracting businesses very often come unstuck at some point when eventually some contract(s) go wrong. It's also very low margin work, with Costain only delivering an operating margin of about 2-3%.
Overall the forward PER of 15.6 looks rich to me, given that this type of business can so easily come unstuck. I would say this type of business should probably be priced on a PER in single digits.
I suppose the shares are a bet that Costain can gain market share, and raise its margins. If they achieve higher margins, then the PER could drop considerably as profits potentially move up. I wonder how wage inflation might start to impact them, as certain technical skills are apparently already in short supply as the economy improves?
I've recorded a SCVR Extra video today to briefly review a few more company results & trading updates, as follows;
SkyePharma (LON:SKP) - in line half year trading update.
Daniel Stewart Securities (LON:DAN) - £1.2m fundraising looks contrived - designed to push up the share price?
Cohort (LON:CHRT) - good results, and strong order book. Looks priced about right.
Eckoh (LON:ECK) - good results, but very high valuation. Possible offer for Netcall.
Porta Communications (LON:PTCM) - strong trading update. More heavy Director buying - another £100k y'day.
Finally, Companies House have opened up their data, for free, hoorah! - here is the link - well worth bookmarking this if you like to look through company accounts.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in NXR, SKP, and PTCM, and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned.
Paul NEVER makes share recommendations. These reports give his personal opinions only, and readers are urged to do your own research & make your own investing decisions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
I'm glad that Norcos (LON-NXR) is finally moving away from the overhang.
It's a smashing company with genuine directors and business plan. (Of course that's my personal opinion)
I have just picked up some Norcros (LON:NXR) too because I like the sound of the Croydex acquisition. Croydex appears to have a useful bathroom products manufacturing base on a 5A site at Andover. In addition the Croydex profitability is greater: £2M profit on £20M sales vs. Norcros £8M on £220M sales. There must be some significant manufacturing, broader customer base and cross selling opportunities for both companies to lever which makes the current PE look too cheap.
Hi Paul.
I could do with one of those Sit Tight toilet seats right now....
Good deal for Norcros (LON:NXR) and nice bowl forming on the chart. What was most interesting to me is that Miton bought 12% of the company last week.
Cheers,
Ben
Hi Paul
I know it's not a small cap. But you have commented on Debenhams previously. They seem to be increasing their online sales nicely.
Paul, sorry to ask slightly out of date question but it’s driving me mad – understanding debt, using recent Hornby debacle as example. I have a debt aversion for my investments, and before investing in Hornby checked the long term debt on balance sheet going back several years. All looked good. Even net debt buried in the notes was only about 19% of total equity – well below FTSE average of 40%. Current ratio about 1.4. But then they announce that without raising cash this week they will go out of business! My questions are: what did I miss, what could have given a clue that this was on the cards? Has management made mistakes I should have spotted? It has shaken my faith somewhat because now I don’t trust that my other investments have the low debt I want, despite my checking their historic balance sheets.
Had a quick look at Hornby (LON:HRN), there were 2 loss making years, 2013/14, which was £6.95m net, cash also fell from £3.5m to £0.46, this year was a small loss. It seems the fund raising was mainly to repay the bank loan of £8m. So I would say the bank would not extend the loan maybe. So although the debt was not high, its the 3 years of losses and no cash. Its surprising the share price had not fallen more. My tip on any shares you hold or considering, click on the discuss button on the Stockranking screen and see if Paul has reviewed it.
Thankyou Herbie, very useful - kind of you to look as well.
Hi Paul
In the light of your comments about the quality and risk/reward profile of Anpario I would be very interested in your view of PHTM Photo-Me International full year results this morning. A strong moat, lots of opportunity, rising dividend but a lofty PE though attached to an inspiring ROCE of 33%?!
Keep up the good work!
I agree about Costain (LON:COST), I'm surprised at the Stockopedia rating VR 81, PE is 15.6, PEG is 13.6, Price to Book val. 3.11, Div 3.16%, EPS est is -8.8%, so I can't get too excited over this share.
If you look at the EPS for each year, it alternatives + and -.
Hi Paul
Re Norcros (LON:NXR). I liked the look of the acquisition and bought some first thing this morning. The new eps forecast of 2.3 makes it 21% above the current 1.9p which I suppose is slightly on the conservative side given that Croydex made £2.1m net profit in 2014.
ANP - worth riding out the bumps imo as the spread is a killer and as with all smaller, illiquid shares it can be painful trying to buy shares back in a firm market!
Hi Paul,
When you say "Numis have raised their EPS forecasts this morning" where do you obtain these updated broker forecasts from? I'm still new to investing and this is something that I'm struggling to lay my hands on. Is this a privilege reserved for those in the know? Institutions etc.?
Many thanks, Mark
Hi 00mrmark00,
I get broker notes direct from brokers, and also through my stockbroker, and various other contacts.
I'm classified as a professional investor, and also I work part-time in fund management, as a researcher, so it's relatively easy for me to get hold of broker research.
It's much harder for PIs to get hold of broker notes, because of the ridiculous rules that are supposed to "protect" PIs by not letting you be sent broker notes! Absolutely crazy rules - we should be lobbying Govt hard on this, as PIs need all the info available, to create a level playing field.
Some brokers don't want their notes distributed widely, as it's a service for their clients only, whereas others DO want their research to go out, as it's basically marketing material for the subject companies.
Hopefully one of the ways I add value in these reports is by letting you know about broker upgrades, etc, when I hear about them.
You do have access to the broker consensus figures, which are available on Stockopedia of course, and the very useful 12 month change in broker consensus chart.
I get a lot of emails from people, asking me if I have broker notes on particular companies, and would I mind emailing them, but regret that I can't do that, as it would get me into trouble with the brokers, and also it would take up too much time, when I'm already very time pressured.
Regards, Paul.
Hi Paul,
Many thanks for the reply which reinforces what I have seen to date.
Also, would just like to say, really appreciate all your hard work on the site educating us PI's.
Keep up the good work.
Cheers, Mark
I am reminded of the scene in Carry On At Your Convenience when the boss of W C Boggs & Sons (played by Kenneth Williams) suggests to designer Charles Coote (played by Charles Hawtrey) that his new toilet design didn't look very strong.
"I assure you, an elephant could sit on this toilet" replied Hawtrey, offended.
To which foreman Sid Plummer (played by Sid James) retorted: "Not without a bigger bowl, it couldn't".
Anyway, looks like a good acquisition for Norcros (LON:NXR). Not a holder myself but becoming more interested.
Steve