Small Cap Value Report (25 May 2016) - JDG, MKS, CSG

Good morning!
Placings
An issue arose yesterday, where a share I hold dropped 20% because Tom Winnifrith revealed that the company was conducting a discounted Placing.
I'm the first to agree that the whole system is bad. There's no way shares should remain trading whilst a discounted placing is being organised. What this means is that a considerable number of people are insiders, and theoretically are barred from trading the shares.
However, in the real world, the news leaks out, and unscrupulous insiders just trade through a third party - selling in advance, thereby locking in a guaranteed profit. It's illegal, but it's obvious from the trades that it happens. Such people should go to jail, but sadly the regulators only seem able to catch the occasional culprit. Thus the law seems little deterrent for the unscrupulous, who seem happy to take their chances, with such favourable odds.
So whenever a placing is being organised, there is clearly a false market in the shares. This has to be changed. I suggest that we need a new, accelerated fundraising process, where the shares are first suspended.
Then, a book build should be conducted online, with existing shareholders having precedence (to recognise pre-emption rights). The fundraising would then complete, with the price being set by an auction process. The company could set a minimum price at (say) a 20% discount to the current share price.
This would be fair to all, and completely transparent. Therefore there's no chance of it ever actually happening!
Revealing price sensitive information
I've taken part in a few placings over the years. The golden rule is that once you are made an insider, then you cannot trade the shares, nor reveal any information about the placing, to others. Not until the deal is announced anyway. Once it is announced, then you are free to trade the shares again.
I've always scrupulously respected these rules. Sometimes to my own disadvantage. I took part in a placing at Synety (LON:SNTY) and watched in dismay as the share price collapsed before the placing was announced. It was obvious that someone was insider dealing. However, as I was an insider, I had to sit tight, and watch the value of my existing shares roughly halve. With hindsight, it would have been far better if I'd not been told about the placing, and could have sold in the market - as it was obvious something was going wrong.
The golden rule is that, no matter how unfair the system, you must not reveal price sensitive information, nor trade the share.
Cyan
So along comes Tom Winnifrith, and says that he is breaking a great journalistic scoop, by revealing price sensitive information - that Cyan was conducting a placing. I think this is outrageous.
The impact is that the share price collapsed - down 20% yesterday, and it had been falling earlier. Therefore the company will now have to do the placing at a deeper discount, in order to get it away.
As an existing shareholder in Cyan, this has harmed my interests. I will now be diluted much more heavily by the placing, because Tom has publicly revealed confidential information. As a result, the City fat cats benefit (from owning more of the company post-placing), and small shareholders like me are shafted. Not a good days' work for Mr Winnifrith.
The system may be deeply flawed, but whilst we are stuck with the current placing system, its essence is confidentiality. If confidentiality is blown, then a downward spiral begins, where the placing has to be done at an increasingly lower price, in order to make it happen. Who suffers? Small shareholders like you & I, who normally won't even know a placing is happening until after it's done.
I accept that there is a false market in the shares when the placing is underway, and the only way to stop this is to reform the system to require that shares are suspended whilst a fundraising is being negotiated.
However, sabotaging placings by blurting out details in the press or on blogs, is just irresponsible. It only helps lower the placing price, thus harming existing small shareholders.
Inside information
Whenever I hear any inside information, even if only a rumour, I respect the law, and keep quiet. You will never hear any "scoops" or "rumours" in this blog. That's not my style. I deal in facts & figures, and I respect the rules (even though they're wrong). So should everyone else.
Judges Scientific (LON:JDG)
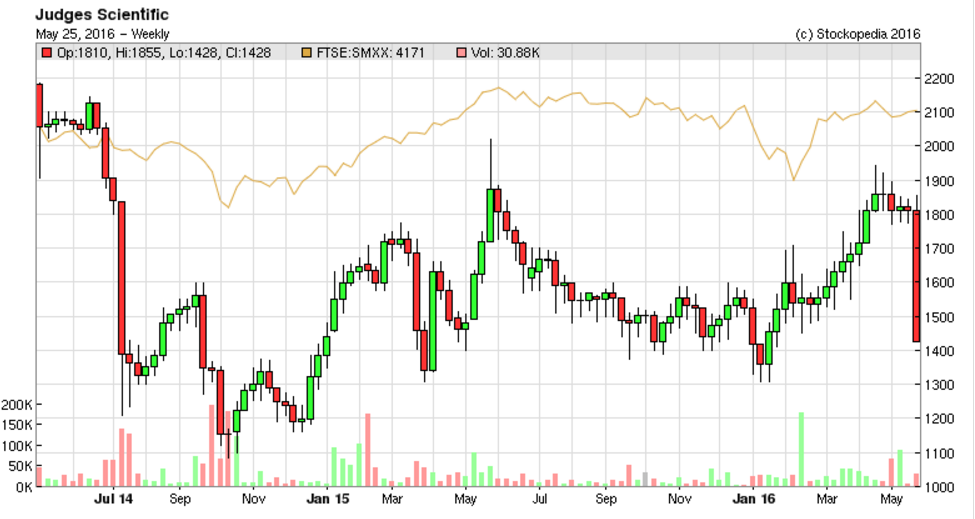
Share price: 1375p (down 24% today)
No. shares: 6.1m
Market cap: £83.9m
AGM statement (profit warning) - the outlook given with the 2015 results, announced in Mar 2016, didn't sound too bad. I reported on that here. Bookings were down, but the company attributed this to seasonal patterns.
Since then, things have got worse:
"At the time of the release of the 2015 annual results on 21st March 2016, we indicated that order bookings in the first ten weeks of 2016 had been low, which had been our experience over the previous two years.
However, as of today, 20 weeks into the current financial year, unlike the previous year we have not seen a pick-up in order bookings. This will negatively impact our interim results and, should the trend continue, has the potential to affect the Group's performance for the year as a whole."
It's a pity that the company has not been more specific. They could & should have given some numbers - e.g. saying that we expect full year profit to be down x% on last year. It infuriates me when companies leave us in the dark. Are they 5% down, or 20% down? We have no idea.
More specific guidance will no doubt be given to the house broker. We then have to wait for them to update, and assess the severity of the downturn.
WH Ireland said this morning that they're leaving forecasts unchanged for now, but recognise the downside risk. That seems an odd decision. Although it does perhaps signal that the situation is not too bad? They're currently forecasing 124.1p EPS for 2016. It might be safer to trim that by say 10% or more? So I personally would work on the basis of EPS for this year possibly being 100-110p?
Therefore, at 1375p the shares look reasonable value.
My opinion - a good company, with good management. In the past, it has had trading glitches which have turned out to be not too serious. Therefore, I'm looking at this as being a possible buying opportunity, once the dust has settled.
As you can see from the 2-year chart below, the shares often stumble on temporary bad news, but always seem to recover.
Retailers
This sector is very much out-of-favour at the moment. So is it a quagmire for investors, or are there opportunities out there? A bit of both, I think! We just have to find the good companies that will recover, and avoid the ones in structural decline.
I see that Marks and Spencer (LON:MKS) has put out a mild profit warning today, saying:
Overall, we expect the combination of difficult trading conditions, both in the UK and in our International markets, as well as our decision to invest in price and reduce our promotional activity, to have an adverse impact on profit in the short term. However, we're confident our actions will provide us with a more solid base from which to build long term sustainable growth.
I reckon MKS has a lot of home-grown problems. All too often its clothing is drab, and over-priced. There's a gulf now between the prices of similar items in Primark vs M+S. Sure, the M+S offering is better quality, but not enough to justify the sometimes huge price difference.
On the other hand, M+S is likely to be one of the biggest beneficiary of the (probably inevitable) demise of BHS. I can't see BHS surviving in its current form, thus opening up more market share for M+S.
Sweett (LON:CSG)
Recommended 35p cash bid - great news for risk-takers who were prepared to hold shares in this company - a cash bid from WSP at 35p has been announced today - this is a 52% premium to last night's close. Very nice indeed.
Personally, the corruption legal case against the company put me off. Whilst it may have been resolved, there was always the risk that more such issues might come out of the woodwork. My view is that, generally in life, wrong-doing is rarely an isolated incident.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
I don't see how a discounted placing could be in any way acceptable or fair. I don't think concealing it is right either.
And I certainly don't think it's acceptable to shaft existing shareholders by not offering them the same terms.
The whole thing should be made open and transparent, with existing shareholders offered the chance to participate first.
Could have easily missed this due to all the goings on:
Sweett Group has accepted no a rival bid of 42p from Currie & Brown, 20% higher than the offer accepted from WSP
http://www.sweettgroup.com/wp-content/uploads/2016/06/Rule-2.7-announcement-240616.pdf
JDG - Uncertainty is always a handicap to a share price, so I'm staying out for now.
Last time this happened the SP went from £24 to £12 in two main moves/gaps in under three months!
I still like the company, but "caveat emptor".
Blimey!
I've just come across all the above. My comment? It's all a load of bollox!
I've got better things to do with my time! ;-)
Cheese. Paul.
Depending upon the size of your position, dont think it as a simple 'Do I sell all or do I hold all?'
As a holder of Sweett before its worth noting that WSP were at advanced stages before in 2014 of taking over Sweett Group before the whole bribery case came about.
http://betaville123.blogspot.co.uk/2014/02/predator-circles-sweett-group.html
I am therefore continuing to hold - the interest from WSP has been for a long time and now that the bribery case has been settled is now the time have re-emerged.
That's what I was thinking. Any more thoughts from anyone?
Paul et all,
I'd really appreciate some advice. I have held Sweett for a couple of years now and weathered the storm instead of selling out when the price was declining and the bad news hit. Do you think there will be more recovery in the share price now from the takeover or would it be wiser to sell up with a small ish loss now?
Mich
Its hard to say but in my expeience its best to take the money when its first announced, some takeovers fall through or the share price declines until the takeover happens. You could hedge your bets by selling half but with the recovery I would take the money now.
The takeover of Sweett (LON:CSG) is already almost fully priced in (though it may still be worth waiting for the 35p to avoid the slight remaining discount and trading costs). It will only move above 35p if a competing bidder turns up.
Thanks, Roger. I am not aware of any group civil action other than an initial letter of claim by Your Legal Friend (YLF) representing a few hundred investors but I guess they will not be proceeding further until the SFO concludes its criminal investigations. Even YLF says this is a difficult area of civil law. Terry has ducked and dived here so let's just hope the SFO's deliberations bear fruit. I would like to see the civil matter go to trial and would of course hope he and his cohorts appear in criminal proceedings also. It would be a severe indictment of the system if Terry were never to be held to account for this scandal. But this is the UK, where white collar crime often goes unpunished.
The debate on placings is an important one and an unfair system that I do not see any fix for soon. However have we forgotten one thing in this saga that has spllied onto here and twitter?
CYAN has a StockRank 10. It has even been identified by Stockopedia screeners as a short seller. It is a 15m cap, tiny penny stock, negative free cash flows according to the stock report data.
It is extremely high risk. Shares issued increasing 10 fold past 5 years.
All the traits of a highly discussed and debated stock where everyone is looking at the mulitbag opportunities. Sure I have not researched this stock, but why on earth would I want to? I am often confused as a trader, who thinks he is an investor, but yet I would never forget my basic safe investing principles that helps my long term holdings.
I get annoyed when Tom Winnifrith critisises a stock that I am invested. I get annoyed too at Paul Scott when he finds wrongs in stocks that I am invested. But I consider their views seriously and with an open mind. However I never invest in the type of stock that Cyan is for my reasons above.
What of the golden rule. ' Never invest in a highly debated stock' seems to be forgotten in this occasion.
But something i also have not forgotten. Tom and Paul have helped both save me money from risks that I have not seen when 'a another' who claims to help private investors did the complete opposite. Tom and Paul also declare their interests which is to their credit. What ever cat fight they are having I am sure they will find common ground elsewhere as they always seem to do.
We mustn't confuse Winnifrith's eccentric and sometimes abusive literary style - and I use that word in the broadest sense - and his role as a whistleblower. If I am concerned when he disses a stock where I am invested, it is, as has been said, important to sit up and take notice of all opinion out there.
Popular small caps a la QPP with active and fanatical bulletin boards have their own dangers which need to be recognised, whether TW abuses their investors or not. Winnifrith was a voice in the wilderness when regularly libelling QPP CEO Rob Terry, who never wanted to take him on in court. Terry's unwillingness to engage was in itself a massive red flag and a sure sign that he had - and has - much to cover up. I now hold my hands up and admit I should have taken more notice of this (alleged) fraud before it was too late. I hope the SFO gets stuck in to this case - they do seem to be taking a long time on the file, which is probably a good sign for former investors.
As for CYAN, it might have been annoying for holders to have their placing blurted out prematurely but that is a risk run by any shareholder. On balance, Winnifrith did what any hack would do and published his scoop. As Paul says, the system is what needs changing, not the antics of a well-connected blogger who, I believe, has his heart in the right place. I have in the past loathed what he does but there is a place for it in a market riddled with greed and wrongdoing.
Ignoring all this unjustified mud slinging, a good example of news of a placing leaking out was in Pan African Resources yesterday. The share price fell substantially yesterday for no apparent reason, but the placing was announced this morning. The share price has recovered because the deal surrounding it is not really negative. The big problem as Paul pointed out is that once the book build starts, lots of people know about it and the market is full of gossips so the news leaks in an informal way, and in this way the specifics were not revealed it seems.
Roger, anyone, what happens if the SFO declines to take action against QPP and its successor, WTG? What then are the practical legal remedies in the criminal court for shareholders? Is a private prosecution funded by shareholders a practical proposition? Sorry if this is o/t.
RayG: Extremely unlikely that a private prosecution could be mounted in this kind of case. Simply no obvious way to finance such a case which would be enormously expensive. A civil action against the former directors (Terry et al presumably) might be possible but the company itself would have the priority in any such claim. From what I know about the affairs of Quindell, I doubt that it would be a clear cut case so I think the possibility is pretty remote. Even simple legal cases in commercial law where the claim might be straightforward are very difficult to mount in English law for a number of reasons. I don't think anyone has even considered setting up a shareholder group to mount such an action in the case of Quindell, at least to my knowledge,
On top of selective hearing, people should develop selective reading. This recent spat about Cyan is just noise, albeit the issue is real enough. It will not be solved any time soon.
I would not go entirely on Stockopedia rankings, one of my best shares is ranked 11 and also on a short sellers screen, I have sold it now, it was Castleton Technology (LON:CTP), made me over 80% in a year, when I bought it it was ranked at only 9. Some of the high ranked NAPS shares I bought have not done so well in fact some have halved in value over the same time, companies like Lakehouse (LON:LAKE) and Entu (UK) (LON:ENTU). Maybe Stockopedia favours some IPOs, but does not favour reverse takeovers?
My problem with Tom Winnifrith is he usually has a vested interest, thats my problem with a lot of shorters. He gets some right, although I think uses information from other people such as Paul. Trakm8 Holdings (LON:TRAK) is another one he was shorting. Jury is probably still out on that one.
Yes Roger has a rather odd view of companies, maybe he's a good guide for ones to short.
The point is the principal, Pauls right and it's wrong however you dress it up!
Roger Lawson has a complete cheek to criticise Tom Winnifrith after Rogers appalling attitude during Globo saga . Roger has been completely irresponsible . One reason that I can never.. Support Sharesoc until Roger departs
As regards Judges it was certainly a pity that more specific information was not included in the RNS. But there wasn't much more information provided at the Agm as you can see from reading my son's report for ShareSoc (I am on holiday at present).
In respect of placings I agree that suspending the shares first would be a good idea for all placings to thwart those who profit from market dynamics and inside information, although many people are concerned that markets should stay open in all circumstances. But discounted placings are a particular problem. I will add this to the list of things that might improve AIM that ShareSoc is compiling.
As regards Mr Winnifrith, he has a tendency to open his mouth without thinking first, or even to make sure he gets his facts straight. It might make for exciting journalistic articles, but it does not necessarily improve his reputation. He did however turn up at the LSE's AGM and said some useful words as did SharSoc's Mark Bentley about AIM. Could I suggest those who hold AIM shares buy a few shares in the LSE and go along next year and encourage the new owners to tackle the known issues regarding the AIM market and the numerous questionable companies that are listed on it (CYAN looks like one example).
Hello Roger
Pls. don't take offence but your post struck me as the perfect illustration of "pot calling kettle black" !
Fwliw I think forthright views are worth hearing and debating on their merits , in this case I'm convinced that TW got it wrong, but he mostly gets it right'ish.
Well I do take offence. Please spell out your allegations and I will refute them. Of course it's very easy to make snide comments anonymously on bulletin boards but it would have made more sense to comment constructively on the other things I talked about. And as you can see from the other comments made, TW has managed to annoy quite a number of people in the past for his cavalier approach and in this case, as Paul made clear, he has been very unwise so I don't think what I said was exceptional in any way.,
I took advantage of the partial recovery in Judges price during the day and have sold my shares. I'm not prepared to hold with that level of partial disclosure / concealment so I have voted with my feet. It's a pity as I want to be a supportive long term investor and I feel grown up enough to make a judgement based on the facts, but am not prepared to be kept in the dark.
I so much agree about Cyan. It's a serial fundraiser and has never been profitable, afaik. In the vernacular it's a massive piss-take on shareholders and I would be interested to know why all their business, such as it is, is in the developing world - none in Europe or UK.
Paul, I've become a regular reader of your excellent blog but why the devil are you bothering to support Cyan? Flabbergasted! None of my business, I know.
As for the odious Winnifrith, yes, his comeuppance is well overdue. A man with such a poor command of grammar and punctuation, let alone dubious ethics, should never have set foot in a newsroom. Happily, as a journalist he's marginalised but remains a dangerous, loose cannon. Nonetheless, he was right about Quindell and has to be credited for that.
Since my post had a quick skim of current annual report ... shocking corporate governance, not to mention Deloitte's EoM!! DYOR
Cyan is the type of company which has no place being listed on a stock market. The best thing a change in placing rules could achieve would be to rid the market of its junk, either because they never list in the first place, or because they die as soon as they run out of money. Funds raised at the arse end of the micro cap universe don't go into creating wealth, they go into the pockets of execs and directors. This materially hampers the economy. If Cyan has any prospect as a business it should be private or VC funded. Indeed If Cyan has any prospect as a business it would be private or VC funded. That it isn't means it likely has no prospects.
Cyan is the type of company which has no place being listed on a stock market. The best thing a change in placing rules could achieve would be to rid the market of its junk, either because they never list in the first place, or because they die as soon as they run out of money.
I couldn't agree more. However, some of us were saying this about Cyan on bulletin boards 10 years ago when it was more helpful to would-be investors :-). All I hope is that my past comments at least saved a few people from ever sailing in such a shoddily built ship!
All the best, Si
Andy,
I managed to find my comments from 10 years ago. Pretty accurate as it turned out!! Bear in mind the Cyan share price was 22p back then:
http://boards.fool.co.uk/hi-si-i-have-to-say-i-kno...
All the best, Si
Hardly a surprise that CYAN needs a sizeable cash injection to remain a going concern ...
Recent history of operating cash outflows,
Last BS (June '15) shows just over 600k cash/liquid assets
Only £450k raised post balance sheet
Disproportionately large orders recently secured
FY results ann. now 2w late vs last year
I can understand grumbles when management dissemble but this is just part of the rough and tumble of publicly traded equities.
I' ve been inside 4 times on Cyan [and indeed held pre-listing]. I know the rules. Yesterday I was made inside by one broker and another broker who knows I hold the shares and who I suspected might be inside, but I could not say nothing and he could say nothing to me because he was not the one who had insidered me. Frustrating.
Is TW not regulated by the PCA? He must have known that he was acting improperly and as has been said the discount is now going to be even bigger.
Cyan is frustrating because it has been a serial diluter as it has changed tack.
This is my favourite source of share information - so thank you very much for all the good work.
I'm also regular listener of Tom Winnifrith - mostly for entertainment value. I'm steering well clear of small oil exploration companies with unproven assets and negative cash flow. One wipe out is more than enough.
But I have some sympaty with the argument that jouranlists should be allowed to disclose placings - as long as they don't own or trade in the shares.
Anyone who is selling on insider information is selling to a buyer without that information. That buyer is effectively being robbed by the seller.
If I held the shares I'd obviously be upset by the disclosure - but more upset with the system. But if I had been planning to buy them on a "unexplained" dip I'd be very grateful to have been saved by the disclosure.
Whenever I see insider trading I report it. Paul, I hope you have and done so on this occasion?
Opinions?
Shares should be suspended from trading when a placing is in process as happens in Australia. it is too tempting for gossips to prattle privileged information. Winnifrith will get his comeuppance one day, he picks way too many fights to get away with it forever.
Absolutely agree with you regarding placings. The current situation is a legalised theft. Why dont you stand as an MP on a single issue platform ?
Hi Paul - Re. Judges Scientific (LON:JDG)
When I read about the profit warning this morning, I thought, wouldn't it be nice to read Paul's analysis along the lines of the 23 May post, Falling Knives.
Reading your commentary above, you have effectively done this but not in the systematic manner of your previous post.
So I will stick my neck out and have a go.
- Is this a story stock? Clearly no.
- Are the problems fixable within a reasonable period? The company has not given any indication of the severity of the impact. Your guess is between 10% - 20% drop in eps.
- Is the company financially stable? Clearly yes
- Is the management doing the right thing to fix the problems? You say there is some evidence of the company bouncing back in the past. Might be worth pointing out that JDG had a profit warning on 17/7/14, shortly followed by a further sp slide. One could argue that this is too long ago to matter now. Was it the same management? I don't know.
So on balance, I tend to agree that it could be a trading opportunity.
Regards, Ram
MKS
PS - I reckon MKS has a lot of home-grown problems.
I totally agree. My wife is what M&S think is their target market - 50+. BUT, my wife walks through the womens fashion section in 1 minute flat, shaking her head at the poor selection. Even if an item catches her attention, she will then search the internet for something similar at a lower price. Richard Hunter at Wilson King Investment believes the younger generation view a visit to M&S like a trip to the dentist, and looking at the demographics of the shoppers I think he is totally correct.
PS - On the other hand, M+S is likely to be one of the biggest beneficiary of the (probably inevitable) demise of BHS
I am not sure about this - more likely to be Primark etc M&S are clearly having their lunch eaten by more upscale and downscale rivals. Clearly they are stuck in the middle, with a rapidly dying off fanbase
I did spot a summer jacket that I liked last week - guess what, no sizer 40, and three weeks delivery. Forget it!!
To be fair to M&S, we do buy some of our food from them - the only reason why we now go into their stores.
Good Morning Paul,
Hope you might have time to look over results today from New River Retail (NRR). Previously one of your "favourite shares" I seem to remember but maybe doesn't count as a "smaller" company nowadays. RNS today looks very positive to me but share price hardly moved - so maybe I'm missing something??
Hi Laughton,
Sorry, Newriver Retail (LON:NRR) is out of my universe now, as the mkt cap has risen to £756m.
My usual maximum is c.£350m-ish. The only usual exception to that is retailers, where I often comment on larger ones, as that can help give guidance for what's happening overall in the sector - that being my sector specialism.
FWIW though, I feel the mgt of NRR are excellent - very shrewd, and good at actively adding value to properties they own - as opposed to passive managers who often do little to nothing.
The main attraction of NRR is the divi yield, so it's a nice income share I think.
Don't expect much capital appreciation though, as being a REIT (I think?), nearly all the earnings are paid out in divis. Therefore it has to constantly do placings to raise funds to expand.
Regards, Paul.
Hi Paul,
Can you please look into CNIC results please. Would be nice to read your views on it.
best regards,
zulfi.
Thanks for highlighting the results being out. I'm not much of an expert, but they look pretty good to me, NAV is now 295p up from 265p (presumably due to acquisitions following the large placing last year). Dividend yield is almost 6% at the current price... so way more than your average bank account. As Paul says, they are a REIT, although they have only paid out approx £29m in dividends compared to £49+m pre-disposals profit. I'm intending holding for the long haul... profit warnings excepting.
Waking up to Judges Scientific (LON:JDG) down 25% was a bad start to my day. You've trained me well because my first thought on reading the RNS was that it wasn't much use without some actual figures. I thought the price drop was probably overdone but there's no way to tell really is there? Maybe there will be more detail at the AGM today.
Anyway for now I'm breaking my rule of selling on the first bad news and holding tight.
Speaking of the retail sector. I’ve read that Joules £JOUL the outdoorsy, middle-class clothing retailer is listing on AIM tomorrow (Thursday 26th May). Market cap is £140m with the shares priced at 160p each. They have a certain Britishness which appeals overseas with international sales growing at 34% per annum. Might be worth an in-depth look.
Like you I bought into Cyan Holdings (LON:CYAN) after the RNS announcing the £10m order from Iran. However, it seemed pretty clear that a placing would be necessary to even begin to start to fufil an order like that. When I investigated the company's history it became clear that Tom's description of it as an 'uber jam tomorrow' outfit wasn't too far off the mark. Consequently, I sold when there was no real follow-through after the implications of the RNS had sunk in. I also cynically wondered if the RNS had been released with the sole intention of sucking people in before a placing as the company was, otherwise, seriously strapped for cash.
I hold your opinions about the fundamental value of companies in high regard. However, you do often confess that you also trade in stocks without a good balance sheet position and I imagine that this was one of those trades. Although it is obviously infuriating that the price has dropped, I think your ire should be reserved for the company rather than for Tom. The company is a serial diluter with little or no regard for you or any other private investor. If Tom hadn't released the information you would, like all the other PIs, just have found out when it was announced and the effect would have been the same.
I do buy the argument that the information has pushed the price down and so made the potential profit from flipping unattractive to the instis meaning that the raise will be at a still lower price. But as Tom has said in his bearcast it is what financial journalists do. The whole system is leaky, ever was and ever will be. And if everybody did have access to the same information then opportunities (and risks) would be fewer. What Tom does is attempt to make the playing field more level. Anything that he can do to achieve that should be applauded. I, for one, would never invest in a share that ShareProphets deemed to be worthy of serious negative attention. However, like you, I might trade in one.
I love the Director speak from Marks and Spencer (LON:MKS):
What does "invest in price" mean, for goodness sake!?
What does "invest in price" mean, for goodness sake!?
Lower margins! But they wouldn't want to say that would they? :-)
On Paul's other point, I don't think anyone here questions his integrity at all. I think we all realise there are people around for whom moral judgement is a moveable feast.
I have from time to time heard things about listed companies in the technology sector that has not been in the public domain. Only yesterday I heard of some worrying technical problems at a listed company that Paul has held and commented on here previously, and like Paul, you won't be hearing anything from me.
All the best, Si
Reduce margins?
What do you think of primarybid.com? It is an attempt at solving the "placings for small investors" problem.
Hi cig,
I think PrimaryBid is a good idea. However, it requires people to deposit funds with it, for speculative bids. I wouldn't be prepared to do that, would you?
To my mind, it would work better if they did "flash placings" - i.e. announce that a placing is happening, and then people can place bids on an order book. As with all such platforms, its getting the critical mass going that's the big challenge.
Also they seem to only work so far for tiny placings at highly speculative resource stocks.
It's a good idea though, and I hope it works.
Regards, Paul.
The deposit seems fair enough to me, you need some to avoid jokers placing bids they can't fulfil.
Also if I understood how it works correctly, you can leverage it considerably, because it operates in "one cancel all" mode so you only need 1 deposit for multiple bids, where the first accepted cancels the others -- which will work for them as they're unlikely to conclude multiple deals every day. So when you put 10K with them you can bid 40K on say 100 companies you like, which gives you "bidding power" of 4 million quid, a 400 times leverage on your deposit.
Getting critical mass is obviously an issue, though their procedure being low cost and not mutually exclusive with classic placings, the hurdle is not too high. From the punter point of view they just need enough critical mass that you've got a fair chance of some bids being hit, so as to justify having a deposit with them.
(I'm not currently using the service, but mainly because it would work better for me if they supported ISA/SIPPs, which they don't yet.)
ergo the self-proclaimed Sheriff of AIM is wayward of the law. Truly that market is the Wild West
dscollard,
I don't want to get into a general slanging match with TomW. I think he does some excellent work, and he's exposed numerous frauds & otherwise dodgy situations, so I support much of what he does (if not the style in which he does it, which is unnecessarily abrasive, I think).
However, I am obviously angry that his "scoop" about CYAN has cost me & other small shareholders thousands of pounds, and has only helped city fat cats dilute us even more, in the inevitably lower-priced placing. Totally counter-productive. I wish people would think through the consequences of their actions, and all the people who lose money as a result of this irresponsible intervention.
Regards, Paul.
Agreed, no doubt, he is a necessary part of the ecosystem and does fulfil a role, though as a journalist he has different metrics. As you say, tactics such as these stunts detract from the overall credibility of AIM ( though I assume they drive traffic and eyeballs).
I think you are back in his cross-wires : it does make for amusing distraction as you are both well able for each other
Morning Paul. Excellent report as always.
Quick question if I may? Is it your opinion that TW had inside information and made it public, or simply observed the market price action and deduced there was an imminent placing and spooked Cyan into confirming his story? He does seem to see and call expected placings or other market scoop news from time to time (I've been on the wrong end of a couple of these) which in the event don't always come about. Whereas the former is highly suspect (possibly to the extent of being criminal) the latter seems to be simply what journalists do. Personally, I get more annoyed when he cries wolf and his market moving rumour turns out to be unfounded.
Also, any views on the Solid State £SOLI RNS? They seem to have reached a positive sounding settlement with the MoJ on their outstanding contract dispute.
http://www.investegate.co.uk/solid-state-plc--soli...
Best,
Gus.