Small Cap Value Report (25 Nov 2016) - VCP, CHT, BRAM, FJET, MJW

Good morning!
I'm planning a bit of a catch up this afternoon, so intend looking at the following shares;
Victoria (LON:VCP) - results which I missed a couple of days ago
Majestic Wine (LON:WINE) - again, results from a few days ago
Fuller Smith & Turner (LON:FSTA) - have been meaning to look at this for ages
Then a few brief comments on other stocks.
Victoria (LON:VCP)
Share price: 327p (up 9.0% today)
No. shares: 91.0m
Market cap: £297.6m
(at the time of writing, I hold a long position in this share)
Interim results 26 weeks ended 1 Oct 2016 - these results were published 3 days ago, so I'm not sure what has caused the 9% share price rise today. It's possibly a delayed reaction to analyst & Institution meetings with management? Also, this share is surprisingly illiquid given its market cap - as shares are tightly held.
I met the charismatic Exec Chairman, Geoff Wilding, about 3 weeks ago, and reported on it here. It's a fairly straightforward buy & build - Mr Wilding is an experienced investment banker, who has done buy & builds before. So far he seems to have done an extraordinarily good job at Victoria - it almost looks too good to be true, but I can't see anything wrong with the figures.
The headline figures from the P&L for the half year look terrific;
- Total revenues up 45.3% to £153.4m - this is mainly driven by acquisitions
- Organic revenue growth of 8.0% (4.9% at constant currency)
- Underlying operating profit of £14.4m is up 82.3% - the adjustments don't look particularly aggressive to me, so I'm prepared to take this at face value.
Balance sheet - I'm less happy with this part of the accounts.
Working capital is absolutely fine - with a healthy current ratio of 1.76.
However, in my view the long-term creditors look too high, at a total of £120.6m - this figure includes a £9.7m pension deficit.
Overall, NAV is £73.4m, but this includes a lot (£91.1m) of intangibles. NTAV is negative -£17.7m. Normally I don't invest in companies with negative NTAV, however in this case I've made an exception because the business is performing so well, and strongly cash generative.
I raised this issue of the balance sheet directly with the Chairman at our meeting. His view is that debt is not at problem levels, and the Net Debt:EBITDA figure (reported today at 1.93 times) is not excessive, and that the business could even take on more debt. Cashflows are such that he believes net debt could be quickly repaid if required, just by stopping doing any more acquisitions (but that's not going to happen).
It's up to shareholders whether you are comfortable with this or not. Personally I'm not entirely comfortable with what to me seems a slightly stretched balance sheet, but I can live with it, given the fantastic growth on the P&L. Personally I'd like to see a modest equity fundraising to bolster the balance sheet, and provide more downside protection.
Comments today in the narrative do reassure on the seasonality of debt;
We have consistently demonstrated over the last four years that, while there is a significant seasonal profile in Victoria's net debt (our working capital levels peak in September each year due to the increase in demand during the pre-Christmas rush, plus the timing of our deferred consideration payments are substantially weighted to H1), overall cash generation is aligned to annual earnings.
Management across the entire Victoria Group is very focussed on cash generation, which gives the Board the confidence to appropriately deploy debt to fund acquisitions.
Outlook - the Chairman is upbeat. This is his summary today;
"During the last six months we remained focused on executing our plan, with the acquisition of Ezi Floor extending the Group's underlay offering and earnings.
The Board continues its effective cash management whilst at the same time being quick to identify and implement potential commercial and margin enhancing synergies across the Group as we gain market share both in the UK and Australia.
With no shortage of acquisition opportunities in the UK and Europe, the Board is confident it can continue to grow Victoria and create more wealth for shareholders."
So I think we can expect more of the same - sensible acquisitions, done at the right price, then costs & working capital reduced.
The narrative is well worth reading in full, as it provides lots of interesting information about the group. Here are some more excerpts from the outlook section. In particular note that Victoria is benefiting from weaker sterling;
Both markets in which Victoria trades - the UK and Australia - continue to perform well.
The Australian flooring market is experiencing very good demand from consumers. Although Australia housing stock is about one-third that of the UK, the houses themselves are about three times the size of the average UK house and therefore the addressable market is quite similar in size.
I have been delighted by the performance of both our historical business in Australia and Quest, the acquisition we made in August 2015.
The UK, which is about 75% of our business, also continues to trade well. Brexit has had no discernible impact on demand for product and, with some 60% of carpet sold in the UK imported - primarily from Europe - weaker Sterling has benefited us by making our main competitors product materially more expensive whilst less than 20% of our cost base is in Euros or US dollars.
This seems to augur well for the future, so I expect we'll see more decent organic growth.
I can't see any specific reference to performance versus full year market expectations, but this comes close;
Therefore, once again, I am pleased to say the Board faces the balance of the financial year with a positive outlook.
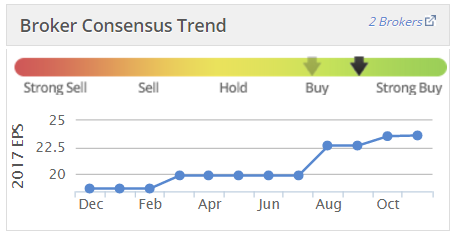
Note that broker expectations tend to be repeatedly increased here;
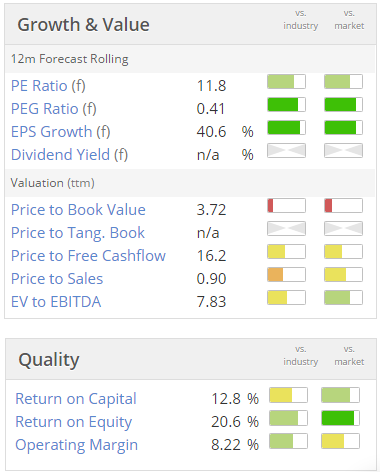
Valuation - the usual Stockopedia graphics are below. Note the strong PEG score, and a pretty modest PER given the growth being achieved. Quality scores look quite good too. Although note the "n/a" for Price to Tangible Book Value - which is always worth checking, as a n/a indicates negative NTAV, which I'm not keen on.
My opinion - I like it, hence why I hold a long position in it. Personally, where I'm not 100% comfortable with the balance sheet, then I tend to keep the position size at a low-medium level, which is the case for me here. That builds in more downside protection, as if something does go wrong, then it won't be a disaster.
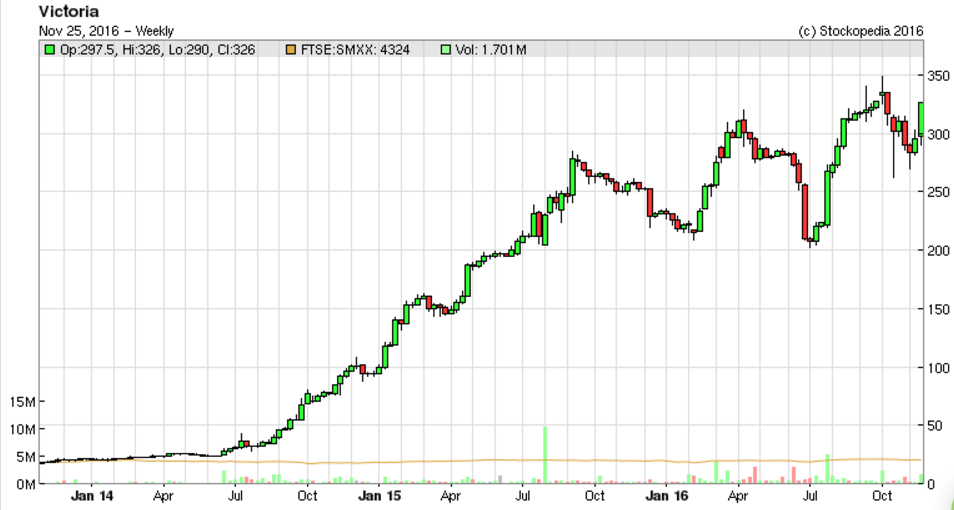
Overall though, this seems to have been a spectacularly successful buy & build. 6 good acquisitions have absolutely transformed the group, and look at what the share price has done! I don't suppose anyone is complaining.
Takeover frenzy
We're seeing a remarkable bout of takeovers for UK listed small caps at the moment, mostly from overseas buyers. Here's the latest one:
Constellation Healthcare Technologies Inc (LON:CHT)
Recommended takeover bid - I've only reported on this company once, here on 2 Sep 2016. It's an American company, listed on AIM, which seems to be an outsourcing company for healthcare invoicing.
I noted the shareholding structure (a dominant CEO controlling about 46% of the company) as being possibly one reason why the share price was languishing at the time about 149p, on an apparently cheap rating.
Anyway, this share has risen about 18% today to 220p, on news that the CEO wants to buy the whole company.
Terms - shareholders will get $2.93 in cash (about 236p) plus $0.43 in promissory notes - which frankly look like they're almost worthless - being unsecured, rolling up 5% PIK interest coupons, and being supposedly paid out in 7 years' time! So I would disregard the promissory notes, and treat the actual takeover price as being the 236p cash element.
This company floated in Dec 2014 at 135p, so to be bought out at 236p 2 years later, is a nice return for shareholders.
My opinion - this looked an odd company, and I didn't like the shareholding structure at all. So being bought out at a modest premium looks fair to me - as I doubt this share would have gained much traction on the UK stock market.
How many more companies (especially ones with dollar earnings) will be bought out in the future? This looks a very hot area for investors to potentially gain windfalls. Look at the remarkable premium achieved to sell Avesco (LON:AVS) - whose main profits come from its USA subsidiary. Exciting times!
Brammer (LON:BRAM)
Recommended offer - another one to receive a takeover approach, at 165p in cash, which was announced 2 days ago.
With the shares at 97.5p the day before, this is a lovely premium of just over 69%.
Fastjet (LON:FJET)
It's got the begging bowl out yet again! Unbelievable.
The Chairman is also resigning, considering it inappropriate for him to lead another fundraising so soon after the last one.
The CEO reckons the company can breakeven by Q4 2017, but needs more cash to get there. How many times have we heard that before? I wonder whether they can find fund managers prepared to throw away more of their clients' money, as has happened a number of times in the past?
Majestic Wine (LON:WINE)
Share price: 287.25p
No. shares: 70.8m
Market cap: £203.4m
Interim results, 6 months to 26 Sep 2016 - these figures came out on 17 Nov, so just over a week ago. This is such a difficult company to analyse at the moment, because the revised strategy under relatively new CEO Rowan Gormley has been to step up costs, in order to drive future growth. This has resulted in a short term plunge in profitability.
The CEO commentary starts off boldly with the words;
Our plan is working.
We said that we would deliver sustainable growth, not by opening more stores, but by investing in better customer service and better customer retention.
Both of these are working - sales are up over 10% and the projects driving that sales growth, like nationwide next day delivery, are on time and on budget.
Now that we have built a solid platform for future growth, future cost growth will be much lower.
That all sounds great, but the H1 figures tell a very different story.
- Revenue up 13.2% to £205.6m
- Adjusted EBIT (i.e. adj. operating profit) down 92.4% to just £0.7m
So an almost complete collapse in profitability in H1. This was planned though, and is part of the strategy to improve performance longer term, through "investing" in staff training, IT, etc. The trouble is, those are costs that go through the P&L, not capex.
This is the conundrum that all retailers face. Do you strip out costs to the bare bones, to eke out the best possible short term profit? Or do you spend more on training & staffing your shops, in order to give a better customer experience, and (hopefully) deliver a better long-term outcome? The trouble is, with so much competition from supermarkets and online, it's very difficult to predict which approach will be successful.
It is impressive that the retail outlets produced a strong +5.7% LFL sales growth. So if they can build on that further, with no more cost increases, then the strategy could work.
Dividends - a 1.5p interim dividend is announced, with a big fanfare about how this signifies management confidence, etc. The new policy on divis is to pay out 35% of full year adjusted earnings.
I'm not placing too much reliance on this. The new CEO seems a flamboyant marketing man, probably from his previous work at Virgin. So I'd rather see the profits first, then the divis on a sustainable basis, rather than jumping the gun with this 1.5p payout.
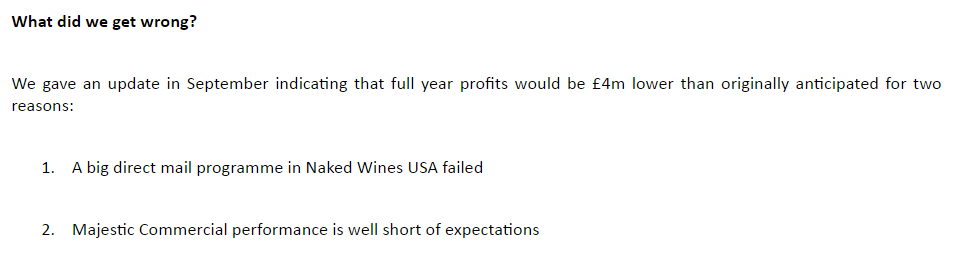
What we got wrong - I quite like this openness in the narrative. However, the mistakes made are somewhat alarming. Are management brilliant or reckless? I can't decide.
Naked Wines - I think the jury is out on this. Is it a good business or not? It's difficult to tell.
Outlook - there's lots of detail in the chatty narrative. There seems to be an in line with expectations comment for the full year;
Challenges remain, but we are comfortable with current consensus expectations(2)
(2) As of 16 November we believe the range of revenue expectations for FY17 is between £430.6m and £443.4m and PBT expectations for FY17 is between £11.9m and £12.4m
it's so good when companies include a footnote like this, to specify what market expectations actually are - it's incredibly helpful. All companies should do this.
Valuation - it's so difficult to value this company, as nobody really knows whether the new strategy is likely to work or not. So the forecasts for this year reflect the up-front additional costs, and the slip-ups which have occurred this year. It may therefore be unfair to value the company on a multiple of this year's profits, on which it looks quite expensive, as you can see below.
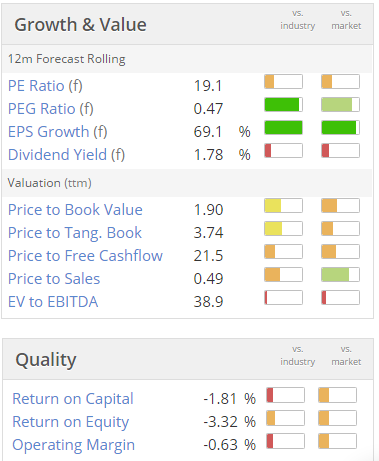
Balance sheet - overall it looks OK-ish to me. Note the cash benefit from receiving wine angel's money up-front, shown as deferred income creditors.
There's a bit of bank debt, but it doesn't look alarming.
My opinion - the only honest conclusion I can come to, is that I simply don't know whether this company is any good or not. If you like, and support the new management & strategy, then it might be worth a punt.
I think there's a heightened risk of an H2 profit warning, given that a big jump in performance has to happen in H2, but that should happen from seasonal factors I guess.
Overall, I wish the company well, but the direction it has taken is too speculative, and fraught with risk, for my taste.
Work-in-progress - article being updated gradually throughout this afternoon
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
I used to buy beer from Majestic -until I realised that it was cheaper to buy in the supermarkets which also offer greater range. However, I do like the ability to taste wines on offer at Majestic -the branch near me allows you to sample the wines it is promoting so you can try before you buy.
Re Majestic
Surely the big problem for Majestic Wine is that all of their product is imported. That means they are going to have to jack up prices next year, by about 15% I reckon. And that is going to hit demand.
They may be just about able to make money at current exchange rates, but they are very vulnerable to any future weakness in the GBP, which I think is likely.
On the positive side the company isn't worth very much. Only £208m market cap. So maybe next year's lower volumes and margins are already in the price.
Re Majestic
Mr Gormley refers to better customer service, well not in my experience. I think a good test of any company is how they react when something goes wrong. I had a problem last week with a delivery and spoke to their "Happiness team" ( can you think of anything so naff to call customer service?). Last Monday at 6pm I was promised a call back. Not had it yet!
Had Majestic on my watch list. Not anymore.
Paul,
Off-topic--
ASY--
Does the recent price increase represent a long term re-rating or possibly more in your view? Yield is good and SP increase is a bonus. I know its tightly held.
One point I would make about Majestic is that it has been around for about 35 years and has a proven ability to compete with the supermarkets so, even taking account of the change in strategy implemented by the (relatively) new CEO, I don't really think it can be described as a speculative business. Naked is hovering around profitability and the extent to which Naked can expand on an international basis will, I think, be a major determinant in how successful the company is in the future. My guess is that the Naked concept will go down quite well in the entrepreneurial culture of the USA. I think it also chimes well with the increasing consumer interest in artisan type foods and drinks. The CEO will just need to be careful how he spends the marketing money and I am expecting some hiccups along the way.
Majestic already had great staff and well trained. I think the real process that MAJ has undertaken is destroying the 12 and now the 6 bottle limit, but to make it work they now have crazy prices for just single bottles which quickly fall to reasonable prices for 2 bottles or more. I suspect this change has driven the T/O growth.
Naked wines was a disaster, with cheap wine being sold at high prices. I purchase a range on three seperate occasions and carried out detailed sampling, as we say in Yorkshire "they were rubbish" and I got my money back each time. Majestic's range is begining to weaken, wth some un-interesting wines being sold at above average prices. I see a bail out will be required in the future. A pity really as after Oddbins fell there are few brands left in good wine. I was amazed when NW reversed into Majestic with an unproven CEO leaping to the top job. I suspect someone had been sampling in the morning.
Paul, great article as ever - might be worth a look at Kainos (KNS) who released interim this morning? Richard
Hi Paul,
Wonder if you thought it might be worth a bit of praise for SOU whose placing was at nil discount but also gave PI's opportunity to partake on same terms as Institutions with on-line access. Their conference call today to PI.s had 600 attendees. Wish more Companies were as committed to their PIs.
On Fastjet (LON:FJET), the worry has to be that Stelios (the Easyjet founder) will put a spanner in the works of any fundraising with his 12% shareholding. He's already had a spat earlier this year, trying to oust the board. And he does have the upper hand - his vehicle is licensing the Fastjet brand to Fastjet.
One can imagine him playing hardball to back FJET management into a corner, unable to raise further funds, and then pick up the pieces cheaply. If FJET goes to administration, I presume the Fastjet licence goes back to him and he can pick up the remnants of the company for cheap and make it a go himself with 100% ownership.
The equity is therefore almost worthless in my view, with such a hostile major shareholder who is also the licence holder.
Hi Andrewdb,
Just to add to your interesting comments above on Naked Wines - I've tried to take up their "complimentary offer",received through the post, not once but twice now. Each attempt at checking out online has failed, the complimentary reference number not being accepted!
Not good enough really.
I see there are some discussions for a furtherpotential competing cash offer for Lavendon
On
"Naked Wines - I think the jury is out on this. Is it a good business or not? It's difficult to tell."
here is my attempt
From what I remember, as a customer it was excellent but there were early signs that the concept would not scale well - when you have 600 cases of something nice (600 being most of that small growers production) to sell, publicise it at 6pm, it is all sold out at 6.15. There are 600 happy people but 10,000 others unhappy on having missed out.
They do have a core listing with more depth of supply to be fair, but even those ran dry sometimes.
My point being that at a certain size of membership it all worked really well (I was a member 2010-14) and it was great in '10, left '14. my ex-oh is still a member.
At scale they need larger supply.
If the supply is larger, it is not supporting small growers anymore, it is just another Laithwaites.
The concept also makes v.v. good use of social media - that have a sort of facebook/linkedin for booze.
This also treads a fine balance between the room being empty and being too full of people, some of them a bit weird.
A good practical example is this site and the scvr comment thread, it seems to hover around 15-60. If it was consistently 5, it would drop further as no--one is watching, if it regularly went over 100 it would also suffer as we would start to want a mod system of some sort and you would start to see weird people (for whatever value of weird annoys you).
The point I am trying to convey is that some businesses have a 'natural optimal size' and NW has got past that imo, and that is to my sorrow.
I have the feeling WIV Wien International AG sold to Majestic at about the right time.
The fact that the owner - Wien International - is mentioned just once and Rowan Gormley was mentioned frequently illustrates the tension between the personal (that NW trades on) and the corporate that changes as companies grow, and how there is a disconnect.
oh, moving on to money :
31/05/15
"On a pro-forma basis for the 12 months to 31 March 2015, Naked Wines sales were £80 million and EBITDA loss reduced to c.£2 million."
31/03/16
"... Adjusted EBIT was £1.0m, representing a maiden profit for the division since the launch in the USA and Australia.
26/09/16
608k EBIT - but there are a lot of 'unallocated costs'
So, my answer is
It was a good business and yes, it is difficult to tell ('unallocated costs').
I agree fully about Naked Wines, they are now often "Out of stock" of many of the most popular lines and you have to wait for the next vintage, which may not be as good as the last one!
Personally, I think it should have remained as a niche player, not sure what the advantages are of being part of Majestic.
On a different subject, Rowan Gormley is reported as looking at ways to improve sales and profitability through the stores, I know personally that I have approached him with a good idea on how he could do that, but he is not interested and sticking to his guns!
not sure what the advantages are of being part of Majestic.
... well, the advantage for MJW is because MJW needed a USP - what does it do that the supermarkets don't?
In the case of NW it is the online community, I forgot to mention that the growers also post messages and answer queries. Waitrose/M&S etc make no attempt to do this and it is clearly important (to those who post).
From NW's pov, they never made a profit until owned by MJW (but mind the 'unallocated gap').
For me it is an interesting commentary on (dis)economies of scale and social media/the internet.
A supermarket buyer needs a min order of C cases to make it viable to stock (even if you only send the stock to some sites)
An MJW buyer needs a min order of B cases to make it viable to stock (even if you only send the stock to some sites) and as MJW has fewer sites, I presume B A NW buyer needed a min order of A cases to make it viable to stock, A
The thing that NW has found is that as the number of members grow, you need to order a lot more than A to meet demand (but the vineyard is a fixed size) and if you cannot, customers are upset.
Now they are owned by MJW, you can put those small batches in a few shops and if it runs out no-one notices.
Any thoughts on Norcros Paul or have I missed it
Hi Cleeve,
I only normally report on results & trading updates, not share price movements.
My last report on Norcros (LON:NXR) results was here: http://www.stockopedia.com/content/small-cap-value...
As a general reminder, please can people mention the ticker or company name in every post. Otherwise it's not clear what company your comments relate to. Many thanks!
Regards, Paul.
VCP chairman is certainly charismatic.
29/8/14
Dividend
"The very large dividend paid in July 2014 has led to the decision that a final dividend will not be paid this year. However the Board would like to send a clear signal to shareholders of the Company's commitment to paying dividends as part of its plan to create wealth for shareholders and it is intended to recommence dividends next year."
Next year (and to date):
30/7/15
"So, in the medium term, we expect Victoria to be capable of paying an attractive dividend. However in the short term, as mentioned earlier in this statement, it is the Board's view that we will create the most wealth for shareholders by deploying the free cash-flow generated by the existing businesses within the Group towards acquiring other high quality flooring manufacturers.
Therefore we have resolved not to pay a final dividend for FY15."
Yep a clear signal :)
Paul many apologises for the FCA comment! You are so right about your observations of exam qualified and then next to useless, seen and worked with a few. An irrelevance in any event as insight common sense and technical knowledge is working well for you (and me! ) so far . Hope to buy you a beer one day!
Hi Tanglands,
Paul many apologises for the FCA comment!
No apology necessary at all. People often assume that I must be an FCA (chartered accountant), so I always put them right & explain that I did the full training contract, but flunked my finals exams. It's not a problem at all, and has not held back my career in the slightest. I'm the lest "corporate" person imaginable, and hated paid employment, so being self-employed since 2002 has worked out great for me (with a few fairly major bumps in the road along the way! All part of life's rich pageant!!)
Regards, Paul.
Ensor Holdings (LON:ESR) Definitely not good for shareholders. No guarantee of a pay out and stuck with private shares. Pretty disgusting really. Sell and take the loss.
Ensor (ESR) bizarrely released an RNS at 10:39 today saying that they want to delist. They've been in wind-down mode for a while, selling off their assorted businesses and promising to return the cash to shareholders. Last mention of this was 13 Sep, when they said they had £10m in cash but were too confused by the tax implications to find a way of giving it to shareholders. This delisting doesn't sound promising to me, but I'd appreciate other opinions.
Crawshaw (LON:CRAW) touching new lows on some decent volume and no news.
Yes..completely unloved at the moment, although it is being reported that the shops are very busy and the CEO has been putting himself around. Numbers coming in January but some reassurance would be welcome in the mean time.
On the subject of UK listed companies with $ earnings being bought up it may be worth having a look at Quixant (QXT) which put out a 'significantly higher' trading statement yesterday. I ask if perhaps Paul can take a look? Its been on my watchlist for years and like a pleb i have never bought watching it instead move up from 80p to 330p.
It has always looked expensive and as you said in recent video the most expensive words in investing "ive missed the boat" i certinaly did here or is there more to come?
Hi Paul,
Could you look at the Triad (LON:TRD) Interims released today?
I've been watching the share for a while now and I wish I bought! Nice 30% rise today!
Numbers look good too!
Cheers,
Joe
Thanks for the superb write up Paul. The trading volume is certainly up today with about 1.2M compared with the average volume of 180K.
off topic, does it say the date a company is reporting anywhere on the stockrank screens or on this site?
cheers
Hi Mcfly,
Sometimes it says it at the bottom of the Stock Report, under the news announcements, where is says Upcoming [Company] Events.
If you have a share in your portfolio on Stockopedia it might also say it on the Events tab, in the portfolio screen.
For small caps it seems like the info provider (Reuters I think) doesn't always have dates.
Ta
Chris