Small Cap Value Report (25 Sep 2014) - TMMG, HYNS, TMZ

Good morning! A quick, and early report today, as I have a packed diary of meetings in London today! So I really hope just for once, the train will be on time.
Regenersis (LON:RGS)
I listened to the Webinar yesterday, and it struck me that the sell-off in these shares seemed overdone, so I bought a few as a trading punt at about 221p. Lucky timing, as the price rose nicely into the close yesterday afternoon.
An announcement this morning states that two Directors have bought shares. The FD bought 12,500 shares at 235p (splashing out £29k), but Hanover Investors (connected with two other Directors) bought a more meaningful 212,000 shares also at 235p (costing £498k). So two Directors spending £527k is a decent sized signal of confidence in my opinion, and I expect the share price will continue recovering today on the back of this news.
(Note that Hanover banked £17.5m by selling shares at 300p in Jan 2014!)
Mission Marketing (LON:TMMG)
Interim results to 30 Jun 2014 are issued this morning and look alright.
Headline operating profit is up 3% to £2.1m.
The Balance Sheet here is my main concern, as it is negative once you write off intangible assets. However, net debt has come down to £7.3m, although as the company states in the narrative today, H1 tends to see a stronger cash inflow than H2. I recall a meeting with the FD last year, when he explained that debt was under control again after a difficult patch, and that looks about right to me.
Outlook - positive, but they've given themself some wiggle room in case anything goes wrong in H2!
Our financial performance remains solid. As in previous years, our second half weighting creates challenges ahead but, as we stand, we are confident that our business remains on track to deliver against our year-end expectations.
Valuation - it looks good value on a PER basis, but once you adjust for net debt, the valuation increases to a level that I think looks about right, maybe slightly on the cheap side? Note that the quality measures are on the low side, so it should be on a relatively cheap valuation:
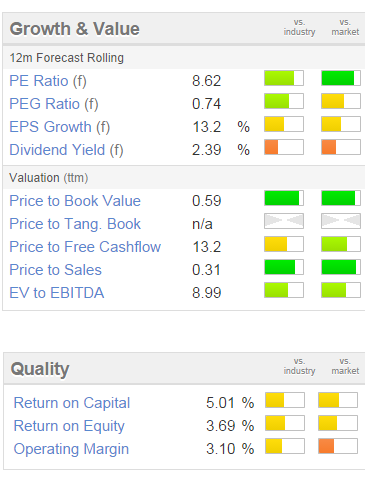
Dividends - the yield is nothing to write home about, and there are better yields in this sector, e.g. Creston (LON:CRE) and Centaur Media (LON:CAU).
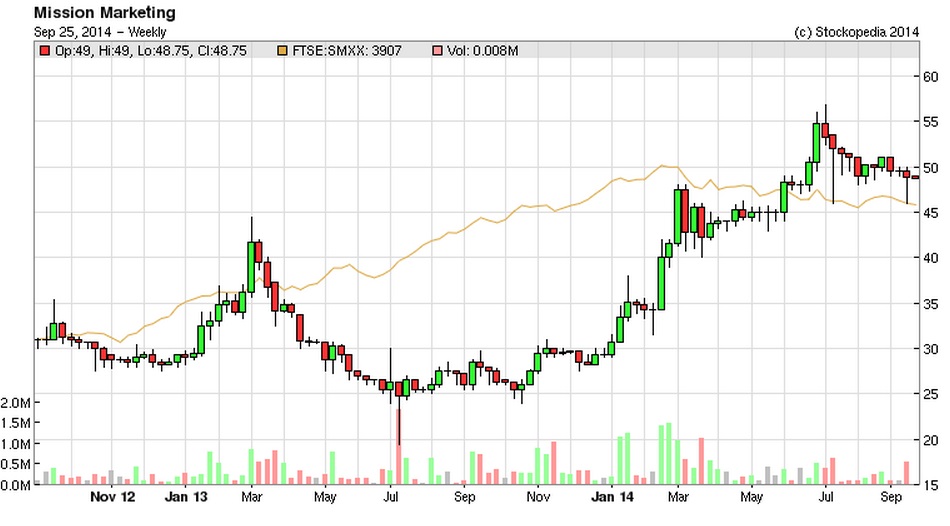
My opinion - I recall being bullish on TMMG shares last year, when they were about 26p, but they have almost doubled since then, so the big re-rating has already happened in my view. Given the still fairly high net debt, and the weak Bal Sheet, I'm not tempted to revisit this share at the moment.
With the UK economy now recovering quite strongly, but European economies weak, I wonder how sustainable the UK recovery is? For that reason I'm not prepared to assume that earnings will continue to rise at cyclical firms such as this. They may have already seen the bulk of any recovery that's likely to happen, at least in the short term anyway? So overall, the current valuation of these shares looks about right, or possibly with another 10% upside on it perhaps? That's not enough for me - I generally look for a clear 50%+ upside on the current valuation, as being sufficient reward to compensate me for taking on the downside risk.
Haynes Publishing (LON:HYNS)
Results look quite good, especially given that the share price has been weak of late.
Watch out for the pension deficit here. Also, there is something funny about share capital I think - are there 2 classes of shares? That needs double-checking, although I think it's OK if you base the valuation on EPS.
I quite like this company, as the march of technology will not affect the need for workshop manuals for DIY mechanics - it really isn't practical to use a tablet when you're taking apart a car engine. I know because I've done it, mind you tablets hadn't been invented then, so a Haynes manual was the only option! A battered, oil & brake fluid-splattered Haynes manual is a badge of honour for any young driver!! Long may that continue.
The dividend looks reasonable.
Overall, there's plenty of life left in this old-style publishing company, which is great to see. The shares are horribly illiquid though, so it's a long term position, if you can get hold of any shares at all.
Toumaz (LON:TMZ)
Interim results this morning show that it's still burning through cash like it's going out of fashion - cash at bank has dropped from £21.5m to £13.2m in the last six months. So the company will be back asking for more in the not-too-distant future, yet again.
That said, it has a great story to tell - their blue sky product is sticking plasters which wirelessly monitor patients vital signs, for use in hospitals. So it's a "this could be HUGE!!!" type of story stock, and that is reflected in a very racy valuation - nearly £100m market cap for a company hemorrhaging cash is not the type of thing I'd be comfortable with.
Sorry got to dash now. See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in RGS, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
the question re the mirror is will Piers Morgan get caught ? It sounds like he was involved, how else can he explain having heard Heather Mills voice mail?
http://edition.cnn.com/2012/02/09/world/europe/uk-phone-hacking/index.html
Still I suspect he has friends in high places and this might not be pushed.
shame you got out too soon, never mind, you probably did well on what you bought next anyway !
thanks for the column, really enjoy it, be lucky,
K
I did hold Haynes for a while, but got more bearish about it & sold.
I do all my own car repairs and have a Haynes manual for my current vehicle.
Bear points:
1 The younger people are used to downloading information for free. Many of them would get advice on how to do a repair or the necessary torque wrench settings on forums etc.
2 Electronic publications may be cracked or shared for free on forums. As stated in previous post.
3 I suspect their range of vehicle manuals is shrinking. e.g. Manuals for 306, 307 but not the 308 (launched 2007)
4 Mechanical parts have become more reliable, requiring fewer repairs. Additional electronic parts are fitted to cars, so there is more to go wrong on those. However, anyone doing their own electrical repairs may well be relying on home diagnostic equipment purchased on e-bay.
not sure I share your confidence re Hayes myself, firstly new cars are much harder to work on, so there is much less that an enthusiastic youngster can do (I appreciate that young people buy 7-10 year old cars, but even going back to that age there's a lot more, plug it into the diagnostics machine to find the problem required),
Secondly, I'm imagining that they'll download the book electronically, and then print off the few pages they need. Having done that, it will only take one person to crack it somehow and share it on bit torrent for sales to fall through the floor.
It would be really sad if this happens, if because people steal their books electronically, they are forced to stop publishing them, but that isn't really a factor in whether it will happen.
However they have a novelty range, the baby one, the starship enterpise one etc, which I guess is immune to this kind of piracy as it's generally bought as gifts. I have no idea what proportion of their business these products represent, but they could re invent themselves and grow this side of the business?
Having said all that, the decline may be slow, I would assume it has already started, but you say that the results are pretty good so maybe I'm wrong.
BTW I saw yesterday that trinity mirror have admitted to some counts of phone hacking, I guess the flood gates are about to open there, I recall you mentioning this as a risk when you got out of trinity some time back, good call,
K
Hi Kenobi,
Thanks.
I knew that TNI had hacked phones, because I made extensive enquiries at the time, through journalist friends, so me being paranoid about them hacking phones wasn't a misplaced paranoia, it was based on hard facts! So bloody annoying that I sold my TNI shares at whatever, 60p-ish, only to see them soar to 200p+. Never mind.
You could argue that the market ignored the risk because it thought that Murdoch would take the blame, and TNI would somehow limbo under the bar, which seems to be what has happened.
A good example of being right, but it costing you money!
I'm increasingly coming to the view that being right or wrong in the long term doesn't really matter. You just have to learn how to ride waves of stock market sentiment up & down, based on what the market thinks is correct, even though the market might be completely wrong.
Anyway.
PP.
Continuing yesterday's discussion on Tesco, Sports Direct have taken a stand:
http://www.investegate.co.uk/sports-direct-intl---spd-/rns/put-option-agreement-in-relation-to-tesco-plc/201409250700195546S/