Small Cap Value Report (26 Jan 2015) - FLYB, PRV, TMMG

Good morning.
The Greek election doesn't seem to be worrying markets unduly, with the FTSE100 down only 13 points at the time of writing. I suppose it will just mean more wrangling within the Eurozone, and eventually everything will muddle through somehow.
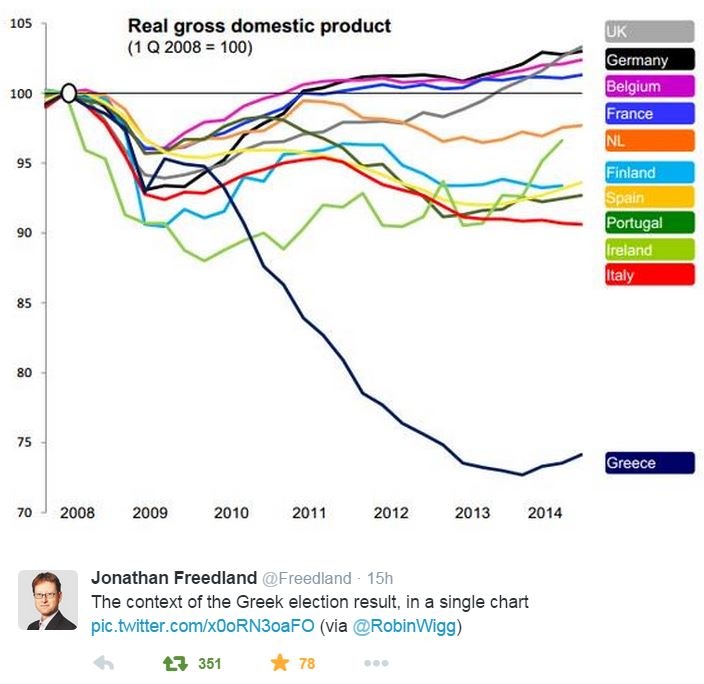
I spotted this interesting chart on Twitter (posted by Jonathan Friedland, of the Guardian - well, we all have our crosses to bear!) which is worth pondering. No wonder the Greek people are desperate for change. It remains to be seen whether change will be for the better or worse. In situations like this, getting in extreme socialists to sort it out is usually about as sensible as inviting a serial killer to babysit.
I can't help feeling Greece would be better off in the long run by defaulting & devaluing. Then see an economic recovery built on a tourist boom from low prices.
Anyway, let's look at some companies.
For anyone interested I recorded another audiocast yesterday, talking about small caps with expert investor/analyst Paul Hill. The link is here (it's long, so best to have a listen when you have spare time).
Flybe (LON:FLYB)
Share price: 67.6p (down 22% today)
No. shares: 223m
Market Cap: £150.7m
Trading update - bad news obviously leaked out last week, with the sudden share price plunge on Friday looking very much like some insider dealing was occurring. It might also have been stop loss orders just below 100p being triggered, possibly?
The market has done its usual thing today of shooting first, and asking questions later, with Flybe shares savaged this morning by 22%, coming on top of a c.10% fall on Friday:
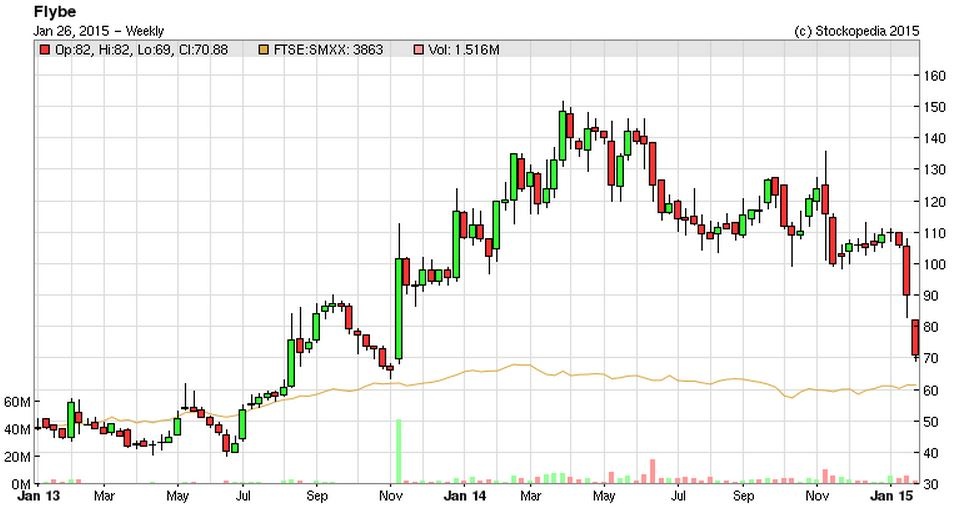
This seems a rather extreme reaction to me, given that Flybe is a turnaround situation, and the issues are already known about.
The headline points for Q3 show an improvement in key metrics such as average revenue per seat (up 2.4% against prior year), and the load factor is up 68.7% to 74.3%. Aircraft utilisation has improved from 7.3 hours to 8.0 hours (this is positive, because the problem with short haul flights is that the planes are not actually flying for much of the time).
Fuel hedging - unfortunately, as the company has forward hedged the majority of its fuel requirements, it will not benefit from lower fuel prices in the current year (ending 31 Mar 2015), and only "minimal" benefit in 2015/16.
I'm interested to find out if the company is taking advantage of current low prices to more aggressively forward hedge for future years - this seems a good opportunity to lock in that low fuel price.
Forward bookings - are up from 34% to 36% of capacity, but the average revenue is down 3%, which is disappointing.
Surplus planes - the biggest issue the company has, is the considerable cost, about £26m p.a. of 9 planes which are surplus to requirements. The company says it is making "solid progress" on this issue, but one wonders if there might be an exceptional charge in order to offload these planes to another airline(s) in future?
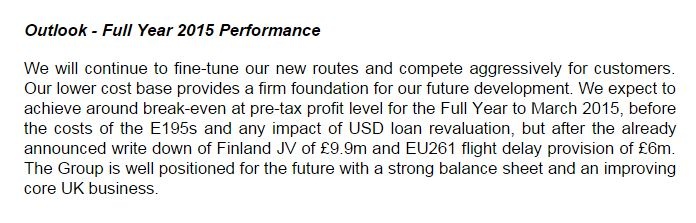
Outlook - if I'm reading this right (below), it seems to be saying that underlying profit will be c.£16m for the year ending 31 Mar 2015, but that one-offs (writing off Finland JV, and impact of EU ruling on passenger delay compensation) will take them to breakeven. However, there are then the grounded aircraft costs of about £26m, so the all in loss looks to be about £26m, which clearly is not good.
However, it also means that once they've disposed of the 9 surplus planes, the business should then be profitable.
My opinion - today's statement mentioned competitive pressures several times, and combined with ongoing issues (mainly the surplus planes) that are dragging on longer than expected, it's all rather disappointing.
Having said that, the share price has been absolutely savaged, so the only question is whether the bad news is already in the price, or not? In my opinion the share price has possibly over-shot on the downside, and I'm more inclined to be buying now, rather than selling.
The reason for that is that the business is sound, financially strong (remember it did a huge Placing at 110p last year, so looks fully funded), and once the surplus planes are gone, it should be reasonably profitable. Set against that, there is clearly stiff competition, and the fuel hedges have worked against the company.
The company seems to have dynamic management, who have stripped out a considerable amount of costs (c.20% of the workforce were let go last year), so as a low cost operator they should be able to build a decently profitable business over the next few years.
It's clearly disappointed in the short term, but not disastrously so. The issues are fixable in my opinion, and don't threaten the company's survival. Investor sentiment is likely to be negative for a while though, as it always is when shares under-perform. So traders will probably have sold up & moved on, whereas investors with a longer time horizon will probably be happy to sit and wait for the issues to be resolved, and a share price recovery. A case can be justified for either stance, in my view - it's a classic situation where you either see the glass half empty or half full.
UPDATE: Looking at a new broker note this morning, they have cut back earnings forecasts a lot. It's effectively pushed back the turnaround by a year. The main factors being the new routes from London City airport taking longer than expected to develop, and surplus aircraft being retained for longer than expected. Although the broker says that despite these setbacks, they see "significant turnaround potential", and the 140p price target means with patience this could be a two-bagger from here. Not much consolation for those of us who bought at double the current price, but there we go, these things happen sometimes.
I can't see any point in selling now, as that would just be locking in a low price/valuation after bad news, when there's actually a reasonable expectation that performance should further improve from here. It's just a question of whether you're prepared to wait or not.
Porvair (LON:PRV)
Share price: 306.5p
No. shares: 44.2m
Market Cap: £135.5m
Results - for the year ended 30 Nov 2014 are published today. The company has given them a heading, which says "Record results ahead of expectations", so let's have a dig into the numbers to see if that stacks up!
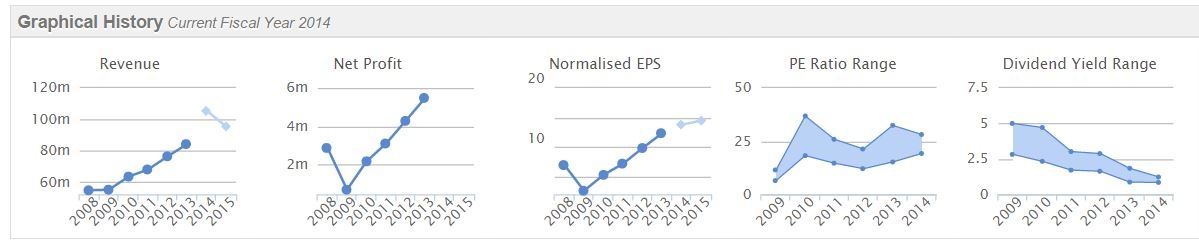
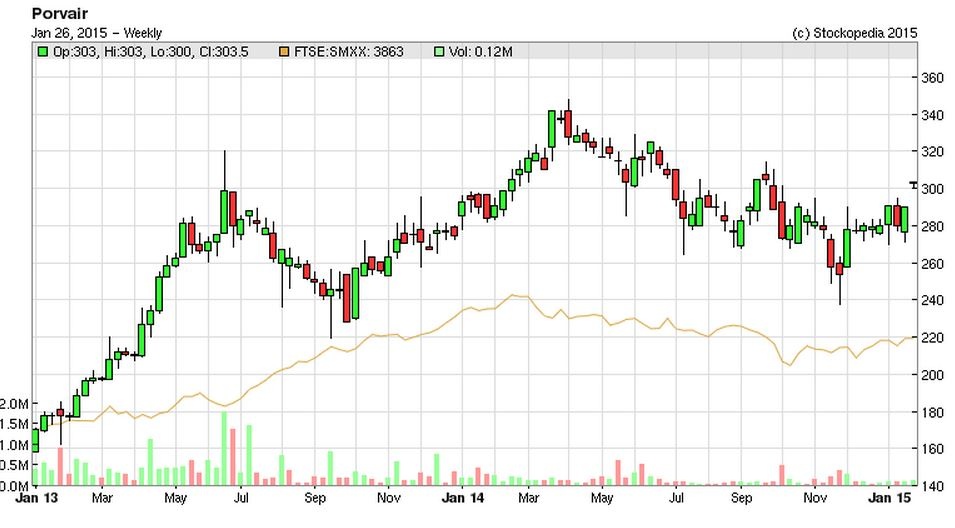
Basic EPS has risen from 12.3p to 14.4p, which is a little ahead of broker consensus of 13.8p. That puts the shares on a PER of 21.3, which seems a rather rich rating. That said, the track record in the last few years has been excellent, so there is a strong case for arguing that the rich PER is justified, if such good performance continues.
The current ratio looks reasonably healthy at 1.36, but note there is a £12.8m pension deficit in long term creditors. Again, not a huge issue, but worth factoring into your valuation of the company.
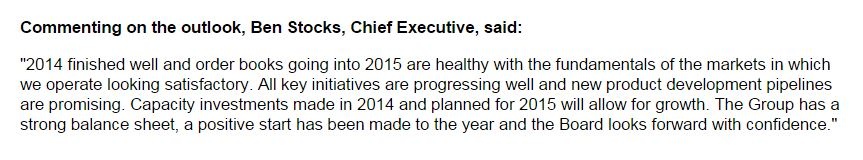
Outlook - this all sounds positive, although it sounds like I need to drop into the CEO's office and give him a brief tutorial on balance sheet strength (or lack of!)!
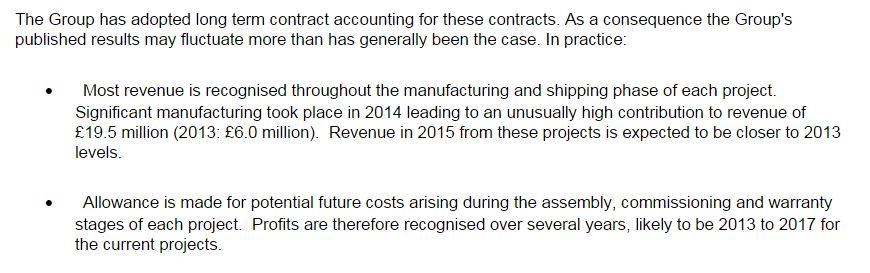
Large contracts - a bit more detail is given on the impact of some unusually large contracts, and this is reassuring, as it sounds as if profit is being fed into the accounts over a period of time, as warranty provisions are released. That should help smooth over any lumpiness in profit;
My opinion - it's a smashing company, but on a risk/reward basis, I'm struggling to see how it makes sense to buy (or hold) the shares at a PER of over 20. That is, unless you have reasons to believe that earnings are likely to grow considerably above forecasts - if that turns out to be the case, then the company's shares could continue going up.
There's no margin of safety though, so if something does go wrong, you could run into a double whammy of lower estimates, and a lower multiple.
I like the company, but the price is too rich for me. It could be a nice buy the dips type of share - to keep on my watch list, and then nip in and buy some on the next general market pullback perhaps?
Mission Marketing (LON:TMMG)
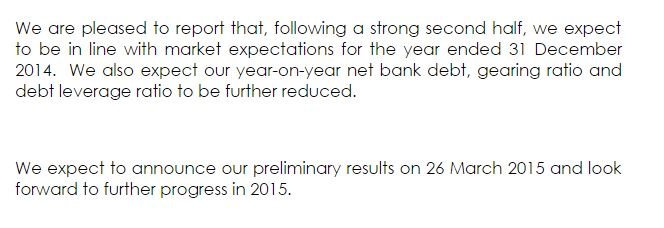
Trading update - this reads fairly well;
Stockopedia shows the company is on a low forward PER of 7.4, and has a high StockRank of 94. So I would say that's certainly a good starting point for doing a bit more research, especially after an in line trading update today. The bid/offer spread is rather nasty though.
All done for today, see you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in FLYB, and no short positions. A fund management company with which Paul is associated may hold positions in companies written about here)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
Where does one find out about pension deficits ? Are they always included in liabilities ?
I hold 30,000 shares in Flybe. Added 10,900 today. In my book it is a 3 year turnround. I hope I am right!!
Article very well informed. 3 weeks ago I wrote to Flybe about Fuel derivatives. They passed my email to a public relations firm who replied but did not answer my question.
New CEO knows the industry and I feel he will turn the business around given time.
That's a big investment. I assume you have several 100K in you portfolio!!
I must say it does look tempting at this level (now where's that 800 number). Looking at the cash and FA I am surprised the Valuerank is not higher.
But doesn't the fact that you wrote "3 weeks ago I wrote to Flybe (LON:FLYB) about Fuel derivatives. They passed my email to a public relations firm who replied but did not answer my question." put you off?
Correct.
Flybe Chairman bought a large holding yesterday which gives me confidence.
Flybe did not reply to me direct because I had spotted what they could not discuss at that time namely the fact that due to hedging the airline is not benefitting from the dramatic drop in the oil price.
Future hedging at much lower fuel prices is critical for profitability.
Obviously hope it works out for you but I am going to leave this one alone. I definitely think Dart (LON:DTG) offers a better investment case with less risk,pays a divi and has a record of dividend growth.
I will watch both with interest!!
Well you have missed out on making more than 4x your money in easyJet (LON:EZJ) over the last 3 years and that does not include dividends, both ordinary and special. Look at South Western Airways in the US, the pioneer of low cost airlines. easyjet and Ryannair have been great disruptors in an old protected market. The incumbents struggle to compete and new entrants also struggle because of the cost benefits of scale as easyjet gets larger. There will of course be a time to sell but I think not yet; benefits of lower fuel costs have not been priced in yet imo and more special divs to come! Trading statement tomorrow!
Hi John,
Indeed, easyJet (LON:EZJ) has done very well, we hold some in my local share club.
It's still quite reasonably priced even now too.
Flybe (LON:FLYB) emerged as a good possible turnaround last year, with new mgt - ex Easyjet - so the point is that they know how it's done, so are making Flybe more like Easyjet, but focussed on regional routes.
They've done a lot of positive things so far, but the turnaround is taking longer than expected, and as we saw today, some issues (such as surplus planes, fuel hedges, etc) have knocked the turnaround back by about a year. That's been reflected in the share price unfortunately! From here though, at this price, I think risk/reward looks good - the catalyst is the disposal of the surplus planes, as that's such a material excess cost, at £26m p.a. The figures should look good once that is resolved.
As I said before, it's not a regular investment, it's a special situation really.
Regards, Paul.
I've always operated a "no airline stocks" rule, but might just reconsider if a compelling opportunity comes along. This one has me thinking, but thinking is probably as far as it will get.
Have invested in airports, but never airlines. I even sold Planestation (the old Manston airport company) after they bought an airline. Sure enough, they eventually failed (if I remember correctly).
Thinking about HSBC and Flybe (LON:FLYB) again, can somebody explain how a neutral rating with a target price which is 10% higher be possible?! Broker targets seem quite insane at times - I have seen buy notes with target prices lower than the current price and I have seen sell notes with target prices much higher than current price!?! Surely if the target price is higher, it should be a BUY; If the target price is lower, it should be a sell and it should be neutral if it is say within 5% of the current price...
Delpher - you are welcome. I don't have a phone number but have had a sensible reply from the the email address investor.relations@flybe.com in the past.
PRV
"Strong balance sheet" can either be a boast or a smokescreen.
Current Assets £36m
Current Liabilities £26m
Net cash up by x10
I can't get too worried about intangibles with this company.
apad
Hi Paul,
Re. the Porvair Chief Exec's comment that "The Group has a strong Balance Sheet" this reminded me of the rule, which you yourself formulated I think (at least I read it here first), that if any company feels the need to assert that it has a strong Balance Sheet then you can be sure it has a weak Balance Sheet. It's not 100% infallible, but whenever I see that statement it rings a warning bell.
I would say the same if a company states that it is "well within its banking covenants". Mention of bank covenants means they are a concern; for most companies these shouldn't be an issue.
Francis
To my mind the aspect of PRV that distinguishes it is that it's products are safety and value critical (and patent protected) so they are not potentially subject to cheaper competition. Also their customers are regular buyers. This is what justifies PER of this order. In other words they are in that set of companies that includes the likes of ROR and RSW. Their small size does make them more vulnerable, however.
I had picked up the conservative booking policy (such a change from some software companies). Nice point about the intangibles - but their technology is protected and valuable……….
apad
Disclosure: 6% of my portfolio.
The problem with Flybe (LON:FLYB) is that it seems to be constitutionally incapable of generating profits.
Comapre and contast: easyJet (LON:EZJ): operating profits from £49m to £581m over the last decade. Dart (LON:DTG) 14m to 31m, Ryanair Holdings (LON:RYA) 227m to £540m. International Consolidated Airlines SA (LON:IAG), not so good, from £540m to £631m, but at least it's making a profit.
Maybe short haul domestic flights is just not the place to be.
I would have thought, they were expanding in Aberdeen, at completely the wrong time, considering the price of oil.
Probably not a time for crass quotes... but when airlines warn I can't help but be reminded of Warren Buffett's classic line...
I'm biased, but I can't help though think that there have been safer, better bets amongst UK airline industry stocks in recent years - all with far higher StockRanks... Dart (LON:DTG) , easyJet (LON:EZJ) , Ryanair Holdings (LON:RYA)
Ed,
Yes that's true. The attraction with Flybe (LON:FLYB) shares was specifically that it's a turnaround.
So the company had problems in the past, which it is gradually resolving. So the investing case was that it had multi-bagger potential, once new mgt (ex Easyjet) had stripped out costs & legacy issues. So it should be seen as a special situation, rather than a regular investment - higher risk, but higher reward.
So far obviously it's not exactly been a rip-roaring success, but once the surplus aircraft have gone, then we could be looking at a share price of double where we are now, in my oipinion - so it's not one where I would throw out the baby with the bathwater.
Regards, Paul.
Yes but I think that is pinched from the man who said "How do you make a small fortune producing wine? Start with a large one".
I prefer his quote where he says "I have a 800 number that I call whenever I think about buying an airline and I call it and I say my names Warren and I'm airolic.......and finally I get over it" at 3m 50 at http://goo.gl/oAvzeg.
I love it. I would be at least £1,100 richer if I had followed his advice but still Air Partner (LON:AIP) might turn around!
I hold Dart (LON:DTG) and Air Partner (LON:AIP) and both have been rollercoasters which I would rather not have experienced. I much prefer boring stocks.
Hi Paul
The bit I picked up from Flybe was:
"Competitor activity has increased on some London City routes since our launch, with incremental seat deployment, price matching and significant loyalty scheme offers evident from legacy incumbents. While our increased frequency, competitive lead in fares and heightened presence continue to appeal to business travellers, we believe that this competitive pressure will extend the period of time that these routes take to reach maturity and deliver the full contribution we expect"
In other words BA have improved their offering. Speaking as someone who takes the EDI-London City route, I like Flybe to be running the route to keep BA's fare's low, but I would choose BA 9 times out of 10.
Flybe (LON:FLYB) Interesting. At the time of writing the share price 69p has dropped below book value of 77.6p
According to the stock report for Flybe (LON:FLYB) it says the company is projected to have £50m in cash for 2014-15. Looking back at the interims (issued in Nov for the end of Sept) there was £149m of cash on the balance sheet. Is the stock report for Flyb therefore out of date? Or am I missing something. At £149m cash equates to most of the current market cap?
Best wishes,
Imran.
Hi Paul
Excellent report as always.
Greece should have been allowed to leave in back in 2009 and things would have been a whole lot less painful than they are going to be when they leave in 2015 or 2016.
Though interestingly Warren Buffet (I think in this video at http://goo.gl/oAvzeg) says he does not look at Macro when making investment decisions.
Flybe (LON:FLYB) I cant get excited (looks like jam tomorrow) about and Dart (LON:DTG) (which I hold) looks much more attractive on the numbers including a Stockrank of 100.
Will the price movement in Flybe (LON:FLYB) on Friday definitely be investigated?
Delpher - the £26m liability for the E195s has been in the public domain for a good while now - from memory first referred to in an IMS last July and then mentioned in each presentation thereafter.
Thanks Glaws2 for putting me straight. You are quite right. I still want clarification and am waiting for that phone call. You don't happen to have the CFO's number?
FLYB
Hi Paul thanks for your excellent blog. Unless I've missed something this is the first time we've heard about the E195s since the last annual report in which it was said 5 were to be returned to the lessors and negotiations were under way for 3 more to go. Now we're told there is a £26m continuing liability. I've tried to speak to their CFO or CEO but without success because their website directs Investors to their registrars, Capita, who don't have a phone number for their head office. The RNS announcement only contains the phone number of Maitland a PR firm who promised to give me phone number. This is beginning to get smelly.
Paul, yes, Greece would be better off out of the eurozone, have a sharp devaluation which would boost tourism, property purchases by foreigners, receipts from shipping, food exports, etc. Yesterday, I was watching France24 as the Greek exit polls were made known, then I switched to Bloomberg for a moment and there was the inept ex-politician Lagarde with three or four bankers, including Ana Botin who inherited the Santander CEO role from her Daddy, all pontificating at Davos on how to remake the world. The contrast between those two worlds was striking. You remark on the Greeks electing "extreme socialists to sort it out" but, really, will the EU/Eurozone establishment and their banking cronies "sort it out", ever? The Greeks have taken the prescribed medecine but their country is not getting better. The medecine has failed. People are desperate, their own life hopes are destroyed. Their children's life hopes are destroyed. Give Syriza a chance, give Podemos a chance in Spain, to do better than the six years of unremitting failure of the EU/Eurozone with their "no end in sight" message. Perhaps the lower euro will provide an economic boost but, for God's sake, it's taken them six years to realise that?
Morning. What I can't understand about Flybe (LON:FLYB) is that HSBC downgraded them to neutral on Friday (with a £1.15 price target) and the shares fell about 10%. Am I naive in thinking that the company must have been speaking to HSBC and releasing information not publicly available which resulted in the downgrade - one trading day before the update? Otherwise why wouldn't HSBC have waited until today? This seems strange.
The drop of 17% on Friday to an intraday low of 84p stinks to high heaven,
a good enough reason not to invest in this company.