Small Cap Value Report (27 May 2014) - RNO, PUB, ZZZ, ACSO

Good morning! I trust everyone had an enjoyable long weekend, and are not suffering too much from adrenalin withdrawal symptoms with the market being closed for the extra day!
Renold (LON:RNO)
This is the industrial chains manufacturer which I always reject because of its weak Balance Sheet, which has too much debt, and a horrible pension fund deficit.
The company issues results for the year ended 31 Mar 2014 this morning. These show a good turnaround underway at the underlying operating profit level, which has risen 54% to £11.1m (but this strips out £11.8m of exceptional items, and £0.6m of admin costs for the pension fund).
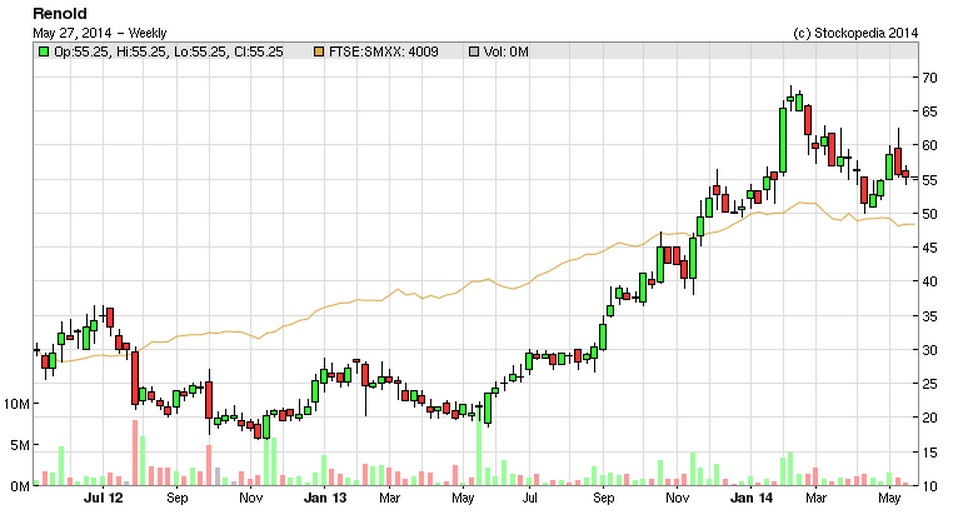
Adjusted EPS rises from 1.4p to 3.2p, so a big increase, so at 55p per share that values these shares on a PER of 17.2. The 3.2p figure looks to be about 10% ahead of broker consensus, so it's a decent result. However, the valuation looks very rich to me. I could accept a PER of 17.2 if the company had net cash, and a rock solid Balance Sheet, but it's the opposite - there's a lot of debt (£24.8m), and a very big pension deficit (£64.9m before tax). Those are highly material to a company with a market cap of £123m, and together mean that these shares are looking significantly over-priced in my opinion. I certainly wouldn't pay anything approaching this valuation, given that there is no dividend, and in all likelihood the business will be directing perhaps about half of its profits over the next five years to reducing debt & plugging the pension fund deficit (£2.5m p.a. + RPI + admin costs).
I feel that investors generally are being far too sanguine about pension deficits at the moment. You can't just ignore them, they are cash outflows from the business, and hence the valuation must be adjusted downwards accordingly. I would only be interested in this this company at under half the current share price. The PER should be in single digits to reflect the debt & pension deficit, in my opinion.
Although it depends what the future earnings progression is like. It seems a mature business to me, so strong growth in turnover looks unlikely, therefore it's a question of what level of operating profit margin can they reach? Broker consensus is for further growth in EPS to 4.16p this year (ending 31 Mar 2015), so bulls would really need it to significantly beat that number in order to justify the current share price, in my opinion. I might look at it again if the price comes down a lot, and they start paying divis, which is not on the cards at the moment.
The share price & valuation say to me that investors have probably got carried away with the turnaround in trading, whilst forgetting to look at the Balance Sheet perhaps? There's a lot of that about at the moment.
Punch Taverns (LON:PUB)
It looks as if a resolution of this massively over-indebted pubs group might be coming. An announcement today gives details of a proposed debt for equity swap, which will leave existing shareholders with only 15% of the enlarged share capital. The trouble is, that will only reduce debt by £0.6bn, and still leave them with debt of £1.6bn, with a very high net debt to EBITDA ratio of 7.7. So it probably won't be the last debt for equity swap, and in the meantime interest payments of 7.9% are likely to suck out cashflow.
This is a good example of how allowing zombie companies to continue trading is detrimental to economic recovery. It would have been far better all round if this company had gone bust years ago, been restructured, then all those pubs could have thrived under new ownership, especially if they had been sold off as freehouses. Instead they are being milked for cashflow to pay interest to debt holders.
It's also a good example of how damaging financial engineering, and heavily debt-laden dealmaking can be to the real world. I'm sure a few people got rich setting up Punch Taverns the way it is now, but it's been a disaster for everyone else. Why do we have to go through the same cycles of boom & bust every few years? Why does nobody say, hang on if we load the company up with this much debt, then it will probably go bust in the next recession?
I'm not tempted to dabble in Punch shares, since they are just a gamble on equity holders being left with something at the end of the restructuring. After this level of dilution that is coming, with more in the pipeline, existing shareholders are likely to end up with very little, and there's always the risk that it could go under if the creditors decide to play hard ball and move it into insolvency, which of course creditors can do when the original lending terms have been breached.
Snoozebox Holdings (LON:ZZZ)
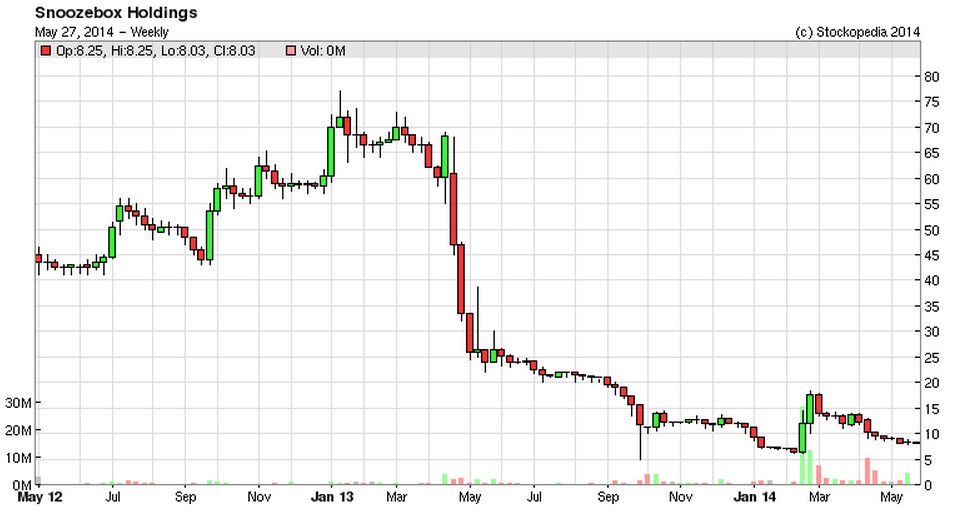
I had a dabble on this share when it was originally floated by Panmure Gordon in May 2012 at 40p. It sounded a great idea - converting standard metal shipping containers into mobile accommodation units that could provide small, but good quality temporary hotel rooms at events such as festivals, sporting events, etc.
It was a good idea, but very badly executed. It quickly became apparent that things were not going well, so at the first sign of trouble I dumped my shares, for a modest profit. It rarely pays to fall in love with a story stock. Things go wrong, and implementing a new business plan nearly always takes far longer, and costs far more money, than originally planned.
New management has been brought in, and they have completely re-worked the business model. It has become apparent that the v1 accommodation units, whilst popular with customers, are not viable for short term installations. This is because they can take up to a week to set up, involving multiple contractors to do the various jobs required. Hence the cost of set-up, and the considerable down time when they are not generating any income, more than offsets the sales revenue for the few days when they are occupied, at a festival for example.
Therefore the new business model will involve the v1 units being placed in semi-permanent installations, e.g. building sites in remote locations, military, and some other places where Planning Permission has been granted to use them semi-permanently (e.g. Silverstone). This should generate enough cashflow to cover the central costs from 2015 onwards.
Newly designed v2 units are a big improvement, being self-contained, and only needing 1 day to set up. Combined with strong demand & much higher pricing being achieved, this should dramatically transform the economics of the business from 2015 onwards.
A recent Placing raised £ 10m which is being used to finance the first batch of v2 units. Today's RNS from Snoozebox confirms that the order has been placed for manufacture of the new units. I'll stick my neck out, and say that I reckon ZZZ will work second time around, with these new v2 units. I had a conference call with the CEO a little while ago, and running through the figures with him, it seems clear that there is very strong demand for the product, and that the economics of the v2 units are compelling, especially when you compare the set up costs with the outgoing v1 units.
In effect, the v1 units proved that there is strong demand for the product, but were not viable in commercial terms due to the complexity & cost of installations. The v2 units have eradicated all those problems, and are very quick & cheap to instal. Therefore I'll stick my neck out here, in saying that I believe Snoozebox should become a viable business in 2015.
Bear in mind also that the last Placing came with Warrants exerciseable at 10p, on a 1 for 1 basis with each new share bought. Therefore, in my opinion the company is likely to go on a major investor PR splurge later this year, in order to ensure that the share price goes well above 10p, to incentivise Warrant holders to exercise those Warrants, which could bring in another £ 10m in fresh funding to buy more v2 units. Therefore at 8.5p to buy now, there could be decent upside here with a six month view. It's speculative of course, but there are much more solid reasons to invest now, than there ever have been, in my opinion, because the company seems to have worked out a revised business model that stacks up.
As always, this is NOT any kind of recommendation, it's just my personal opinion, so the onus is on readers to do your own research.
The historic figures for ZZZ look dreadful, and 2014 is likely to show more losses too, but investing is all about the future, and they seem to have good prospects for 2015 onwards, in my view.
accesso Technology (LON:ACSO)
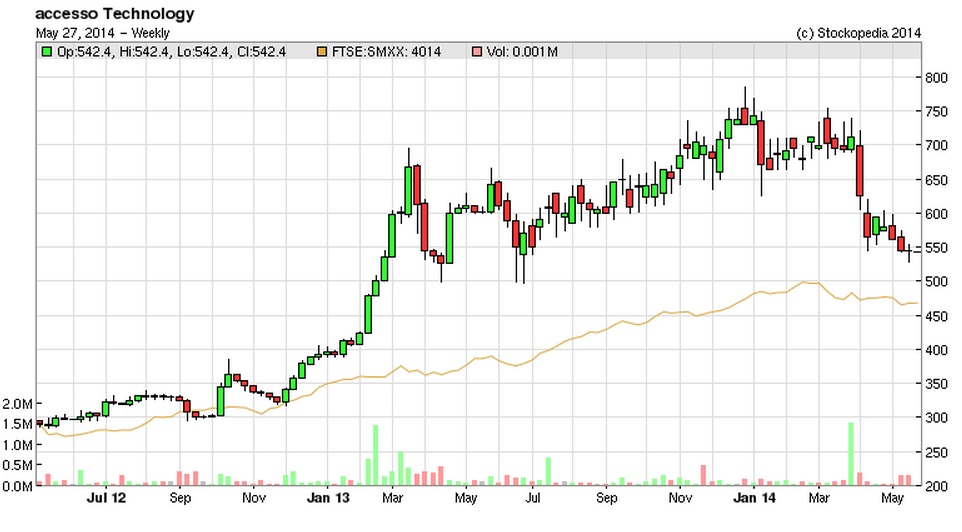
These shares have looked over-priced to me for a long time, but along with a lot of other highly rated shares, have come down considerably in the last two months.
Although when I last looked at the company on 25 Mar 2014, on release of its 2013 results, I could see that the growth in adjusted earnings to proforma 19.2p EPS (adjusted for the year end change) was starting to make progress towards growing into the racy valuation.
One would expect further progression this year, maybe to 25p adjusted EPS? Although I'm a bit confused since broker consensus seem to be much lower figures of around 17-21p EPS, taking the average of two websites. Maybe those are unadjusted figures? So I would need to see more detailed broker forecasts to get a handle on the valuation here. Even if my guesstimate of 25p EPS is correct, then the rating still looks pretty warm at 542p per share that is a PER of 21.7. The forward PER goes up to about 30, if you base your calculations on the forecast EPS shown on Stockopedia & another website.
So I'm not really sure how to value it. Directors seem to have cashed in around £7m by selling at 600p and 690p, so that was a good signal that it was fully priced at the time.
The statement today sounds upbeat, with the summary section saying;
We remain at an early stage of the financial year and there is much still to be done. Nevertheless we are making good progress in important areas of focus, delivering combined wins for queuing and ticketing offerings, deepening our relationships with existing customers, and extending some of our longest-standing relationships further in to the future. With all of that in mind, the Board believes that accesso currently remains well positioned to perform in line with its expectations for the year as a whole.
The company seems to have good growth prospects, but I'm not really sure how to value it, and am hence not really interested even at the significantly lower price today compared with a few months ago. 400p or below might start to get me interested, but I can't see a margin of safety above that.
Right, I have to dash, as am off for an investor lunch, 2 hours drive away.
See you tomorrow.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in ZZZ, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
Paul
General question - are you still recording shares in your value/GARP listing for further research? Last entry I have on spreadsheet was Creston in December.
Regards
Peter
Hi Peter,
Oh, I'd forgotten about that! LOL!
There's not much value around now, and I think people just used to treat it like a tipping service, which wasn't good, and then I forgot about it. So it's in limbo really!
Regards, Paul.
I think Renold is well placed internationally; It has 14 manufacturing sites around the world and 20 sales offices. In the year ending March 2014 North America accounted for 38% of sales, Europe ex UK, 28%, Australasia 12%, UK 9%, China 4%, India 3% and other 6%.
Only 558 of its 2739 employees are UK based.
It gives management a good platform to successfully implement the second stage of its three stage turn around; Phase II focuses on organic growth and market share gains by leveraging its market and brand leading positions and superior products.
I think there is a risk people are being too sceptical; yes its risky but recovery situations usually are and I think in this case new management have demonstrated sufficient progress so far.
Hi John,
I think Renold (LON:RNO) have done well with their turnaround.
My only issue is the price - it's far too expensive, given the weak Bal Sheet.
I wouldn't pay more than a PER of about 6, given the extent of debt & pension deficit. That's the right sort of price in my view. Maybe push it up to 8 if more earnings recovery is coming. But a PER of 17 for a mature company with such weak finances, is pretty crazy in my book!
Regards, Paul.
In fairness to Punch they have tried to dispose of Pubs - its just that they have a huge number which is difficult for the market to absorb.
I recall that in 2011 they tried to sell 2300 pubs to landlords on the basis that these pubs had no future for either the tenant or Punch under existing arrangements. I would guess that this was about 30 - 40% of the pubs they owned at the time.
The real problem is that the pub market is weak and the tenanted business model is flawed. Far too much financial baggage for Punch. Very interesting to see what happens when interest rates rise.
"Very interesting to see what happens when interest rates rise."
Isn't almost all of their debt fixed interest? Is there anything to refinance at maturity? If their debt is essentially a repayment mortgage on the pubs they should be debt free by 2035 when the last issues mature and they shouldn't have an exposure to rates between now and then.
You could well be right. The Punch debt is very complicated but I would guess that there is some sensitivity to interest rates. I am intrigued that after much bun fighting a debt for equity swap is being agreed just as there is a real possibility of an interest rate rise.
Interest rates could also affect indebted Landlords and consumers so I doubt that a rise could be good news for Punch.
Ive looked at Punch as one of those companies that might be a turn around situation but have always pulled back from investing due to it's weak financial position and it's shrinking market.
2035 must seem to be a long way into the future for Punch. Will it last that long?
Completely agree with scepticism about RNO. It has a globally recognised brand name but it is operating in a mature low margin industry, and it is not the market leader. The new management team has talked up the recovery story, and backed up their confidence with sizeable share purchases - all very admirable.
But the group's balance sheet remains in a terrible shape. Leaving aside the huge pension deficit, the company's net worth fell from £31m to £18.1m in the latest year whilst its net debt rose from £22.8m to £24.8m.
If ever there was a company that needed a rights issue to repair its balance sheet it is RNO. Have always been surprised by the long-term loyalty of some of RNO's biggest institutional; shareholders, particularly M&G, which have stuck with this company as it struggled to survive.
Perhaps they will stump up for another rights issue (the last one was at 20p in 2009). But, like Paul, I would not be tempted to reinvest in this company until its shares drop below 30p.
My concern on Renold is their ability to continue to drive forward on the international stage - given that most opportunities for this company lie outside the UK. There is highly competent competition from German, South Korean and US players and I wonder about Renold's longer-term competitive edge. Add the pension issues to the pot and it makes me wonder if my cash can be deployed more prudently elsewhere.
Re. Renold. They took a £7.7m foreign exchange currency hit, net of hedging. Not insignificant. The strength of the pound is a major factor for companies deriving a significant proportion of their revenues outside the UK.
Hi Paul, Just looking at the plain numbers I can see where you are coming from with Renold. I do however feel that there is a good recovery going on at Renold under the new chief executive. Pension Fund deficits should not be ignored but at least we know the extent of the problem and the annual cost. The problem could get worse and it could get better- my money is on it getting better as I expect the last valuation will have been performed when bond yields were at rock bottom. There were costs last year with closing the Bredbury plant and other cost cutting measures which hit the balance sheet but underlying cash flow seems to be on an improving trend, something that makes the £2.5m annual pension cost less of a (relative) burden. I do believe that companies can grow out of these problems, admittedly given a fair wind.
This is a recovery story and investing in it requires some belief that it can eventually achieve its target of double digit operating margins which would push earnings towards 10p per share. It is a recovery story and I do share some of your reservations and appreciate the risks, hence it is the smallest holding in the JIC Portfolio at 1.9%.
Start of the football world cup is just round the corner. Any views on the likely shares to come out winners by the end of the year? My nap is Domino Pizzas.
I like the look of William Hill. Bookmakers tend to do well during a world cup year.
Hi Paul. Re Renold. I agree with your analysis and would add that the adjusted EPS looks good only because it excludes the pension adjustments. Not convinced that they are a one off. Also revenues are down and the outlook for increasing sales can only be marginal in this mature market. I sold my holding this morning.
Regards, Ram