Small Cap Value Report (28 Jan 2016) - SSY, AIR, QRT, FLYB, MTEC

Good morning!
A shortish report today, as I have to travel up to Oxford, for a brainstorming afternoon at Stockopedia's HQ. It's a pleasure working with the Stockopedia team, as they're not only super-intelligent, but also super-decent people. After one particularly bad experience in 2013, I now only work with people that I like and respect. Life's too short for anything else.
SCISYS (LON:SSY)
Share price: 73p (up 6.6%)
No. shares: 29.0m
Market cap: £21.2m
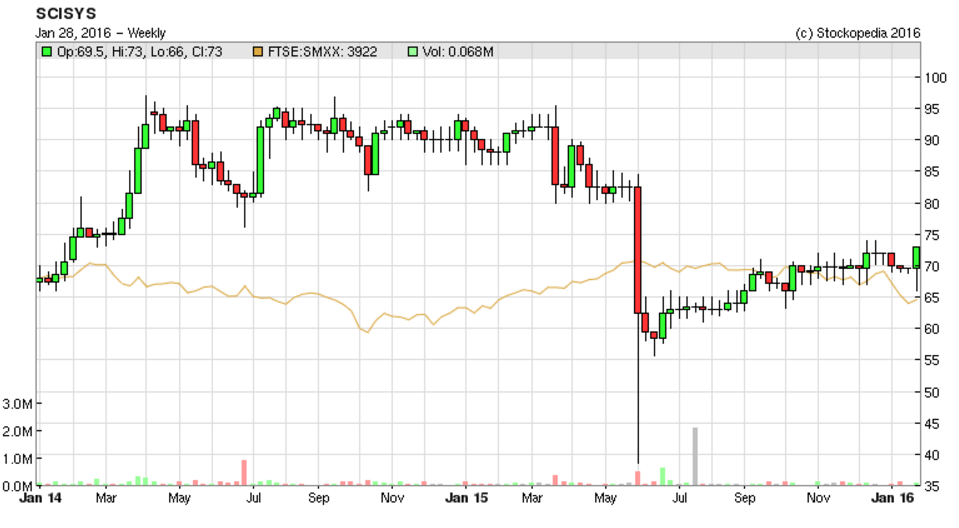
Trading update - this sounds encouraging to me, and it looks as if the company has moved on from the problems encountered in H1;
The Directors are encouraged by the performance of the Group during the second half of 2015 and believe that the underlying results will comfortably meet current market guidance.
Despite the continuing headwinds created by adverse foreign exchange movements, the Group's trading performance for the second half of the year indicates that the Board's previously-expressed confidence, that problems encountered in the first half were a temporary anomaly, was well founded. As announced on 14 October 2015, the isolated contract that had been the cause of the problems was brought to a mutually satisfactory conclusion, ensuring that SCISYS could fully focus its efforts on its unaffected activities which represented the vast majority of the Group's projects.
It's good to see that the problem contract which gave rise to the profit warning in Jun 2015 has now been resolved. Although I would still like to know how this problem arose, and what internal controls have now been put in place to prevent a recurrence.
Outlook - this sounds reasonable;
The Directors remain confident that current market guidance for 2016 will be achieved. Although we anticipate that the relative weakness of the euro will continue to have an impact on our financial performance in 2016, we have implemented currency hedging contracts to mitigate the risk and this is reflected in the guidance.
My opinion - It seems to me that a business model which is susceptible to major problems occurring without warning on a large contract, needs sorting out. Perhaps stronger internal review processes are needed before contracts can be signed? Perhaps a complete re-think of what contract terms are used is needed? If another accident is just waiting to happen, then I wouldn't want to repurchase the shares I used to hold in this group, even though it has some attractions, such as a forward PER of 11.
The shares are extremely illiquid, and I had considerable difficulty selling just a small amount of shares a while back, which combined with a wide spread, is a negative.
Overall the business looks stale - it's ex-growth, and profits are unpredictable. With a dividend yield of only 1.3%, it's difficult to see much attraction for shareholders. Although I do like the fact that the company has generally quite reliable recurring income streams, and is embedded into a lot of large organisations, providing mission-critical software.
What is needed is some growth excitement. It's no good just pottering along with turnover static, or falling. Most investors want to see growth, and that is needed if the PER is ever to rise from c.11 at the moment. This share has always been on a low PER, it was as low as 8 a while back. There needs to be a catalyst for growth, to increase the rating.
It's interesting how shares behave after profit warnings. If you'd managed to catch that spike down to c.40p on the profit warning last year, then you'd be laughing now - people are dismissive of catching falling knives, but in some situations it's the right thing to do.
Air Partner (LON:AIR)
Share price: 388p (up 5.6% today)
No. shares: 10.3m
Market cap: £40.0m
Trading update - this sounds positive, although note that profits should be up against last year, as 2 acquisitions were made;
Trading momentum in the second half of its financial year ended 31 January 2016 remained good, with a stronger than expected end to the period. As such, we expect underlying pre-tax profit to be not less than £4.2m which compares to £2.6m reported in the same period last year.
It's good to see a figure given for expected profit. All companies should do this, or give a range if they are uncertain of the exact figure. That takes the guesswork out of interpreting these update statements.
I've only got an underlying EPS forecast for 2015/16, not a profit before tax forecast. So given that the EPS forecast of 27.5p is almost identical to last year'a actual EPS, then assuming no distorting factors, one would expect 2015/16 EPS to be considerably higher, since PBT is up 61.5% against last year.
Another way to estimate it, is to take the £4.2m underlying PBT estimate given by the company in today's update, take off c.20% tax, and that gives earnings of £3.36m. Divide that by 10.3m shares, and it implies an EPS figure of 32.6p, well ahead of 27.5p forecast.
If my 32.6p EPS estimate is right, then the PER would be 11.9, which seems quite reasonable.
Note also that there is a very generous divi yield here - so a strong update today probably strengthens the case for maintaining a big payout.
It has a StockRank of 99 - another positive factor. So all in all, this share looks quite interesting.
Quarto Inc (LON:QRT)
Share price: 216p (up 3.8%)
No. shares: 19.7m
Market cap: £42.6m
Trading update - a positive-sounding update today from this illustrated books publisher;
A strong performance in the core publishing businesses sees Quarto well placed to exceed management expectations for the year. Our recently established global sales and marketing structure has worked effectively to attain a market-leading presence in the adult colouring book category, particularly in North America. Further, the Ivy Press acquisition has been successfully integrated into our business and has surpassed expectations in its first year.
This strong trading will enable Quarto to report earnings growth and debt reduction for the third year running. Net debt on 31 December 2015 was $59.7m (31 December 2014: $66.0m) and we continue to maintain our focus on managing our working capital. The reduction of the company's debt (over 25% since 2012) and further increase in earnings will allow progression in the company's Final Dividend, to be announced on 17 March 2016.
Interesting to note that the group has caught the fad for adult colouring books - apparently a stress-busting activity.
The forward PER of 5.48 looks attractive at first glance, at a very low 5.48, however the sting in the tail is the awful balance sheet - loaded up with way too much debt still. It amazes me that the group's bank have been so relaxed about letting it have so much debt. Although the trajectory of bank debt is downwards, it would take many years to reduce it to a level where I would consider this share investable.
Still, if you like a low PER, and are happy to ignore the risk of high debt, then this share might appeal to you? Strong trading certainly helps anyway, so shareholders are in a better position today, knowing that the company is trading well, than they were yesterday.
Flybe (LON:FLYB)
Share price: 82.75p
No. shares: 216.7m
Market cap: 179.3m
(at the time of writing, I hold a long position in this share)
Trading update - this is frustrating update, because it really doesn't give private investors the simple information we need - i.e. how is the company's profitability performing, compared with expectations? That's pretty much all we want to know, but is notable for its absence in today's statement - as is so often the case with updates from many companies. I think there needs to be some sort of rulebook introduced by the authorities about trading updates, giving specific requirements for what must be included in trading updates, and their frequency, etc.
Instead we get reams of stats, which is great for the analysts who have detailed models on the business, but private investors (and commentators like me, where I cover 500 companies - far too many to build forecast models for them individually!) are difficult for us to interpret.
Revenues per passenger are dropping, and load factor (utilisation of available seats) has dropped quite sharply, from 74.3% a year ago, to 68.9%. However, the benefit of cheaper fuel is also feeding through, as hedging (at higher prices) gradually works its way through.
The terrorist attack in Paris has had some impact on air travel, as you would expect, but that tends to be a temporary factor - denting confidence for a little while, then is gradually forgotten, as people regain the confidence to use air travel. Terrorist attacks never stop me going anywhere - after all, if you change your plans, then you're letting them achieve their objective. It's more dangerous crossing a road than flying anyway.
Cantors have helpfully crunched the numbers, and their morning note says that they are leaving forecasts unchanged for now, but there is an increased risk of a future downgrade.
My opinion - I'd like to see more broker notes, to better understand how the figures have been interpreted, but from what I can make out at this stage, this seems to be a slightly negative update today.
Matchtech (LON:MTEC)
Share price: 495p (up 1% today)
No. shares: 30.9m
Market cap: £153.0m
(at the time of writing, I hold a long position in this share)
Trading update - This staffing group shows how it should be done - a simple one liner at the start of the update, tells me everything I need to know;
The Board currently anticipates profit for the full year to be in-line with its expectations.
There's then more detail given, but I don't see any need to report on that - profits are as expected, job done!
Outlook - sounds positive;
"Demand in the UK for skilled engineers remains robust and looking ahead we have identified a number of opportunities to roll out our Engineering recruitment services across our overseas locations. Investment in headcount is taking place in these areas and I remain confident that we will convert these exciting opportunities into significant growth over the next few years."
My opinion - the acquisition of Networkers seems to be going well. I cannot understand why the stock market repeatedly ignores positive updates, and progress from this group. It's possibly due to an overhang of sellers in the market, who knows?
As you can see from the usual graphics below, the valuation is modest, and this share has an attractive divi yield of 4.79% too. Directorspeak sounds encouraging, so all in all I like the look of it, and am considering a top-up.
In my opinion the market price of this share simply looks wrong. I think the correct price would be in the 600-700p range, based on a more appropriate PER, bearing in mind the group's expansion and good performance/outlook.
Right, I'd better get my stakes on, can't keep the boss waiting!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Interestingly the Air Partner (LON:AIR) stockrank has now gone down to 64 now from 99. And there is a split announced for the 31st of January which may cause a bit of volatility.
Flybe (LON:FLYB) trading Statement (April 7/16): http://www.investegate.co.uk/flybe-group-plc--flyb-/rns/trading-statement/201604070700064321U/
Continues with excessivle low load factors in a growing market. Buys aircraft to improve margins (due to lousy passenger growth etc) which just pushes the can down the road a bit until those asset values go to naught pretty quick (expect write downs in a few years) because those aircraft types depreciate very quickly....
Ref: Flybe
Given the hopeless history of the airline industry, I would need a very good justification to break my "no airline stocks" rule & invest in Flybe. I just don't see it.
Running the E195's is clearly just a "least worst" option as they cannot sell them. No surprise, considering Embraer had almost no waiting list for this aircraft, therefore suggesting it was not much in demand.
I would have thought they should be making good money at this stage in the economic cycle, with low oil prices as well. Do we have to wait for their fuel hedging to expire ?
Paul, Couldn't agree more with conclusion of your first para!
I see it, thanks! But in case I'm actually interested in firms I'm not yet interested in, I want a comprehensive list.. for instance Matchtech (LON:MTEC) have a smaller rival Interquest (LON:ITQ) which I didn't know about til recently.
No need to only put actual investments in a portfolio. I use virtual portfolios all the time to assess groups of stocks and analyse them using my preferred customised screens. You can always delete some or all of the stocks in a given portfolio quite easily.
Gus.
SCISYS (LON:SSY) is a sound company, as far as I can tell. (I'm long, it's my industry, and I joined the PI lunch the company held after the profit warning.
As for catching falling knives, the graph shows that you could wait for the knife to bounce a bit, catch it more safely, and still be in with a good profit!
I see no reason why this shouldn't recover steadily to the pre-profit-warning level).
match tech poor rating
noticed that debtors have made a quantum leap from £3 to £33 million and the return on capital has dropped from 30 to 11 %.
might have something to do with the low rating .
bit red flaggy
jb
Matchtech (LON:MTEC) John- the purchase last year of Networkers International (LON:NWKI) for £57.9m at the start of 2015 is the reason for the debt increase to 33m.
Given the synergies which will occur through owning both businesses, profitability should improve & with it ROCE
Disclosure: I hold £MTEC
This is a general question..
Is there a list somewhere of companies with a description of their business, but at a level of detail higher than the 'subsector', down to which the LSE (& so stockopedia) goes with it's numbering classification? For instance 'Recuitment agency' rather than 'Professional & Commercial Services'.
Or better still, a paragraph like the Profile summary given at the foot of each company's page here.
Thanks if you can help.
Hi Snickers.
If you put the list of companies you are interested in into a portfolio and the click on the second (of four) grey icon by the "Holdings" heading this will pull up for each company the summary of its business, rankings and key valuation parameters.
Gus.
I don't follow Flybe closely, but am I not right in thinking that they have over the past months started using some of the E195s themselves to increase capacity on some routes, rather than have them sitting idle, and costing?
In that case failure to use all the additional capacity efficiently may not be either unexpected, or bad news in terms of overall profitability - better to have the planes in use, even if not as full as ideal, than have them unused.
Peter
Only true if operational costs < ticket revenue, which is not a given for the wrong kind of plane on the wrong kind of route (dunno the situation in FlyBe's case).
I had a look at FLYB update and it looks poor to me - 10% increase in seat capacity and yet only 2% increase in volumes and 3% in passenger revenue??? But maybe the slower revenue growth is as they are passing fuel cost cuts to customers...? Anyway, my mind is thinking of pressing the Sell button at this stage... :-/
Paul - any idea what the "bear case" on Air Partner is?
High stock Ranks and dividend yield
+ve trading update.
High Joel Greenblatt score
a Lord Lee stock.
Obviously I'm long - but I'm a bit nervous because I don't understand the bear case? Wondering why you don't own it?
From memory, the balance sheet is much weaker than it appears at first glance. If Air Partner (LON:AIR) were to categorise customer deposits on their jet-card scheme as debt rather than other creditors, the company would be in a net debt position rather than appearing to have net cash.
@fek47 Ah - thanks very much. Didn't know that. Will mind my eye.
If you look at the September interims for Air Partner it reported net cash of £1.4m after allowing for £13.6m of jetcard deposits. An issue that has tended to detract from the company's rating is a lack of visibility of earnings. The recent purchases of Baines Simmons and Cabot Aviation should over time improve the quality of earnings and hence the market rating, all being well. For what it is worth I made a small purchase this morning.
Good Luck
Not being an accountant your point about booking of jet card has interested me. Having had a look at their annual report for 2014 I note it states:
"Amounts invoiced to customers in respect of future ights, including amounts related
to the JetCard product, are deferred at the balance sheet date and only recognized in income once the ight has taken place."
Doesn't it therefore mean that the revenue is deferred as a liability on the balance sheet at least until the flight takes place and the amount becomes an asset? I'd really appreciate your explanation.
I don't hold but I'd suggest that wording "invoiced" means that it doesn't encompass non specific points accrual as result of prepaid jet card subscriptions. You'd need to ask Air Partner or someone who knows them better than I to confirm that.
I'd imagine IAG have a similar issue over accounting for Avios as the number in circulation is mind blowing.
The potential issue is that net debt looks better than it otherwise would be, because the liability matching the pre paid cash is not taken into account in the net debt calculation, while the cash is.
Flybe (LON:FLYB) is growing capacity and for whatever reason their load factors are appallingly bad. Fuel costs Fuel costs are currently around $350/ton and they are still hedged at double that.
Their Project Blackbird was closed down after failing in its intent on getting rid of the aircraft Embraer E195 aircraft (which I previously indicated would be near impossible because they are wholly noncompetitive version of the aircraft), which will remain a significant drag on their costs of £40m over the medium term.
This airline is going to continue to struggle for quite some time to come and the key indicator is whn and if that load factor starts marching upwards in leaps and bounds.
With regards Flybe (LON:FLYB) wouldn't we expect revenue per passenger to drop as we pass on fuel savings to customers to remain competitive?
Obviously the load factor is a little concern, but we do have a lot of new routes this year too which will definitely have a bearing.
I agree with Paul tho, the 2 points above, the stated decreasing costs and albeit temporary Paris issue mean a lot of spinning plates making it hard for us to determine the quarterly profit.
Slightly off piste, but make sure to catch The Big Short at the cinema this weekend even, or especially, if you already read the book. It's brilliantly well done.
Hi Paul
If you have time, I'd appreciate your thoughts about the Flybe (LON:FLYB) trading update this morning.
Best wishes,
Imran.