Small Cap Value Report (28 Jul 2015) - MCLS, INTQ

Good day!
I see Dialight (LON:DIA) is down again, to 409p at the time of writing (mentioned in yesterday's report). It just shows that, when something goes wrong, selling quickly is a good idea. This is where we private investors have a massive advantage over institutions - if anyone buys more than about 1% of a small cap, then when something goes wrong, they are left high & dry. They often can't sell, even if they want to. Whereas you and I can just ditch a bad company unceremoniously. OK it might mean taking a loss, but we live to fight another day, and can make up the loss on something else.
So my thought for the day is that forming an emotional attachment to a bad share, and hesitating over selling, is the biggest unforced error that most of us make. If/when something goes badly wrong, then ditching it on the opening bell is usually the best thing to do. I like to get my sell order into the market, and executed, whilst the institutions are still worrying about what to do, ahead of their first committee meeting of the day. I'm long gone by the time their sell orders come in, and smash the price. That's the theory anyway.
Apparently we're all meant to be terribly worried about China. I'm not. According to someone on Twitter, the UK exports less than 1% of GDP to China. Lower commodity prices makes everything cheaper, thus boosting a services based economy like the UK. So the way I look at things, investors in resources stocks might be getting massacred, but that doesn't affect me. It won't affect the number of conservatories that Entu are going to sell, nor the number of frocks that BooHoo shift. All in all, it's just background noise for a long-term UK small caps investor, in my opinion. There's always something that people fret about. Bottom line for me, if I hold good value shares in decent UK companies, then what the Chinese stock market does is completely irrelevant.
There's not much in the way of news today, hence the ramblings.
Somebody in the flats over the road (I'm in Islington) is obviously smoking a joint, as the pungent aroma of cannabis is wafting into my room. Who needs sniffer dogs when it stinks to high heaven like this?!
McColl's Retail (LON:MCLS)
Share price: 160p (up 1.3% today)
No. shares: 104.7m
Market cap: £167.5m
Interim results, 26 weeks to 31 May 2015 - this convenience store operator seems to have been successful in eking out a modest profit margin again, despite LFL sales being down by 1.9% against last year. Pre-exceptional operating profit came in at £9.6m versus £10.0m in H1 last year.
Adjusted EPS is up 45% to 6.1p, which seems odd - why would EPS be up, when profits are slightly down? It must be down to cost-cutting, which is mentioned in the narrative. Here is note 11, giving the reconciliation of adjusted to normal EPS:
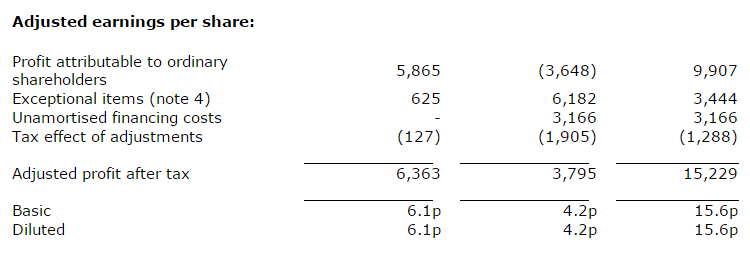
Dividends - note that the interim dividend has been doubled, from 1.7p to 3.4p. That's impressive.
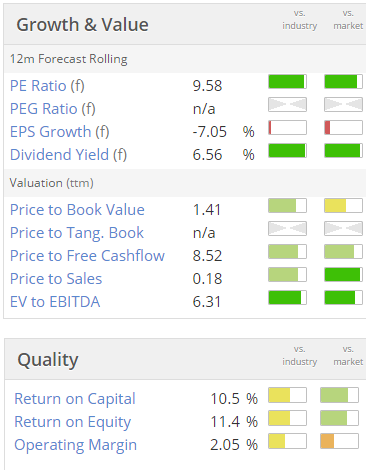
Valuation - the usual Stockopedia graphics are below, and as you would expect from this type of business, it's on a low PER, and pays a cracking dividend yield.
Balance sheet - looks bad to me. Net assets are £117.2m, but that includes intangibles of £141.8m. So write that off, and net tangible assets is negative, at -£24.6m. That's not necessarily a problem for a retailer, as they sell for cash, and get credit from suppliers, so retailers can operate fine with a relatively weak balance sheet.
However, in this case I am concerned about the level of debt. You have to be so careful with any business which was formerly owned by private equity ("PE"). In my view, PE is a scourge - they're parasites, who load up businesses with debt, in order to reduce taxable profits to as close to zero as they can get.
The sole purpose of PE is to make a profit buying and selling businesses, and they often leave a trail of destruction behind them, in my experience - businesses can be starved of capex, in order to generate short term profits, and they nearly always float the company back onto the market with far too much debt remaining.
Net debt has gone up here from £36.3m to £47.3m, but then the company also presents "underlying net debt" of £35.3m! That's a new one for me - underlying net debt!! A (sort of) explanation is given in note 10:
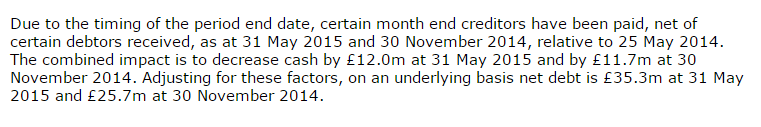
This makes me uneasy - it's reinforcing the reality that debt is too high, although I suppose being given an explanation for swings in net debt is helpful. I don't like this "certain..." debtors and creditors. Why can't they just say payroll, and money paid to us by the Post Office?! That would be my guess of what items have caused this issue.
It also flags up the problem with having a 26, and 52 week year end cycle, as opposed to calendar month accounting. If your major outgoings (e.g. payroll) is paid on the last day of the month, then the accounting periods need to reflect this. I had this problem back in my days as a retailing FD. I inherited calendar monthly accounting, but it was fiddly to get the cut-off right at month end, so in a eureka moment, I decided to alter the accounting to 4 or 5 weekly cycles (instead of calendar months).
It was a complete disaster - the 4-week periods were loss-making, and almost scared the bank into withdrawing our overdraft. Then every now and then a 5-week period would happen, and show a big profit. Then when it came to year end, if the 52 weeks ended before the 31st of the month, all was fine, because the payroll was paid on the 31st, so the year end on (say) 28th January, showed a big cash balance.
However, we had to do a 53 week period every now and then, which threw out all the comparatives, and suddenly the year end was on the 3rd February, just after payroll had been paid, so the overdraft was maxed out!
After a while, I realised that 52 or 53 week accounting was a complete nightmare, and went back to calendar months, as that meant that each month and year reported the same cashflow cycles. It seems to me that McColls need to have a think about this, and maybe switch to monthly reporting, instead of 4/5 week reporting.
My opinion - I can't shake off the feeling that this is a cigar butt business - squeezing out a small profit margin, but probably doomed to eventual failure.
With such a weak balance sheet, it should be conserving cash, not paying out big divis, in my view. You have to be so careful with high yield stocks, as they can often be dying businesses made temporarily attractive by a big divi yield. Remember that HMV paid out bumper divis until shortly before it went bust.
Having said that, McColls has done well to remain profitable, which suggests to me that they might be benefiting from reduced rents on lease renewals. Another issue to consider is the planned increases in Min Wage, which are likely to affect companies like McColls - with a profit margin this low, I imagine they are only paying Min Wage, or marginally above, in many locations. So a 3-4% annual rise will hurt. Wetherspoons were belly-aching about this recently, in their results statement.
Overall, I think this stock is high risk, and the big divi yield could lull people into a false sense of security.
InternetQ (LON:INTQ)
Share price: 300p (up 2% today)
No. shares: 39.9m
Market cap: £119.7m
Trading update - in my view, this company is almost a carbon copy of Globo, at least in terms of its accounts, if not its activities. In particular, the bumper profits reported never turn into cash, but instead the debits on the balance sheet just pile up into ever larger amounts - especially intangible assets and debtors. That's essentially a sign of fictitious profits, the way I look at things, which is confirmed by a negligible tax charge.
Every trading update is positive, so naturally today's is positive. The company says;
The Company has a strong pipeline with good visibility for the coming six months and is on track for even better growth in the historically stronger second half. The Company remains confident for full year results to be in line with market expectation
Cashflow - consider this small excerpt from the cashflow statement, showing what I consider to be the crux of things for calendar 2014 and 2013:
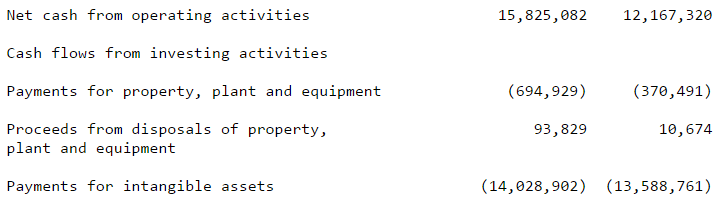
So in other words, if you're being kind, all the cash profits are re-invested into intangible assets. If you're being unkind, what this means is that they happen to call some costs "intangible assets" in order to by-pass the P&L, thereby creating fictitious profits.
I was reading up on Warren Buffett's shareholder letters whilst on holiday last week, and his approach cuts through all the nonsense. In his view, you can ignore costs if they are just (largely meaningless) accounting book entries, such as goodwill amortisation. However, you absolutely must not ignore business costs, of whatever kind - whether you capitalise them or not, a cost is a cost.
So a business such as this, which generates nothing in real cashflow, is not profitable at all, whatever the accounts purport.
Investment by Tosca - there was an interesting announcement on 9 Jul 2015, saying that Tosca has invested E17m to buy a stake in INTQ's Akazoo music streaming business. It says the post-money valuation is E104m, of which INTQ owns 69.1%, or E71.9m, about £50.9m.
This third-party validation of a key service of INTQ certainly strengthens the investing case. Although how this music streaming service is going to compete with Apple's new offering, and existing services from Spotify and YouTube, is the big question.
My opinion - overall, I don't think this company is profitable at all, but it clearly has some value, as it has been successful in securing outside investment into Akazoo. Therefore as a glamour stock, it might attract a high valuation if it can get people excited with big growth numbers perhaps?
It's definitely not for me, but as a complete punt, I would say this is nowhere near as bad as Globo.
(article in the process of being updated, pls refresh the page from time to time)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Re "third party valuation" of the InternetQ (LON:INTQ) subsidiary, somehow that reminded me of a quote from some Silicon Valley startup investor, who was telling an investee company "you can pick up the [post-money] valuation you want, we will compensate for it in the terms". So caveat emptor unless the underlying transaction is fully transparent...
Hi Paul,
Have you noticed FCCN have been moving south last few days. Something to worry about you think?
best wishes
Re INTQ, music streaming does not make any money. There is so much competition now from about 10 providers, I can see some going in the next year or so. I use Deezer its free for 1 year, no adverts, I also use Spotify for odd albums that are not on Deezer. I also use youtube and musicloud.
Hi Fangorn
3,400 for fascia and guttering? Do you live in Buck House??? Just get a decent local joiner to do it for you. Or send me the rough dimensions and I will give you a quote myself. ( Entu (UK) (LON:ENTU) seem a rather spivvy, high-pressure selling outfit, despite the green dressing on the website).
@Herbie,
Any idea what the price difference is for a standard Victorian Conservatory between Entu and Everest. I've always used Everest as they have never disappointed, 10yr Guarantee, plenty of after service, reliable, courteous workforce.....but yes, they are relatively expensive,even after the discounts,deals and whatever other one offs they claim to be having.
No idea its very hard to get prices from these people as they are sold by salesreps, who set the prices high to get a sale. Had one for guttering and fascias the other day, if I had know it involved a salesrep I would not have had tyhem. Anyway price started as out at £11k then went down to £7 then with advertising boards etc came down to £4k, sign today. Still I said its too much, then phone the office blah blah, can do it for staff price of £3.4k. Still too much goodbye.
@Cisk,
"I just don't see that much of a link between a loss in value of a UK fund holding chinese equities / commodities and whether people would buy new double glazing or not"
I'm not talking about a UK fund holding Chinese Equities. I'm talking about UK equities indirectly/directly exposed to Chinese fall out eg Commodity funds/Commodity companies listed on UK market. many people will have invested in these oblivious to the impact an imploding China will have! So when demand plummets,and commodities drop leaving their UK porty looking decidedly sickly do you really think they'll splash out on a new conservatory?
The link would be from the POV of assessing their relative wealth/the extent that they could crystalise some of their Equity into cash to pay for said Conservatory. If their holdings are off 30% are they still likely to engage in such a "large expense"
"I suspect it's a fairly small number who are overweight in Far Eastern commodity / mining funds and who have deferred buying double glazing".
That would be relevant IF I was talking about people exposed to Far Eastern commodity/mining funds. Do you classify BRCI as a Far Eastern Commodity fund? Perhaps we are looking at this from a different perception of what constitutes a Far Eastern Fund.
Many are subject to such concerns without even knowing it I'm sure. The FTSE 100 for starters is very commodity focused and therefore exposed yet many will be buying exposure on basis that its the UK FTse100,ergo it's mainly UK exposure.
If you take the average person,with some savings/pension, if its taken a whack they are hardly likely, in my view, to go out an splurge on an expensive new conservatory.
How cheap are these Entu conservatories? Victorian for example.I cant find a price without getting a free consult.
Although you noted it as a quiet day it seemed to me to be quite active and this may be because you do not cover certain slices of the market.
Trading updates today include Shawbrook . Scientific Digital Imaging and Rightster, with 1pm (a Stredder favourite) giving an update to supplement an acquisition and a placing with an open offer. There is obviously no requirement for you to cover anything but I wondered if these were ignored for a reason
Hi Aislabie,
Re the stocks you mention:
Shawbrook - interesting company, but I don't usually cover financials.
Scientific Digital Imaging - too small/illiquid for this report
Rightster - a jam tomorrow stock, but I am limbering up to writing a section on this next, but haven't had lunch yet, so am off to Angel for a burrito.
1PM - I hadn't spotted that, thanks - will take a look. Yes it's a financial, but quite an interesting growth company.
To a certain extent I have to cherry pick the company announcements which look most interesting. So there will always be things I miss, usually because I've had a quick skim of the results, but didn't think they look interesting.
Regards, Paul.
@Cisk,
In similar fashion to Paul I avoid "NEARLY ALL" Chinese stocks - the exceptions being the likes of PetroChina ,listed in the US. I wont touch any Chinese small caps with a bargepole.
"I don't think the typical boohoo customer will have a basket of UK stocks, nor will double-glazing salesmen be selling less patio doors because their customers have taken a bath on the Hang Seng. Just a thought anyway"
I'm pretty sure a customer purchasing an Entu conservatory will be far more likely to be invested in the UK equity market though. Cant comment about booHoo as I dont follow it,nor do i know anything about it.
These Conservatories/New Bathrooms and Full set of double glazings aren't cheap. For the avoidance of doubt I'm assuming most wont invest in the Hang Seng/Chinese markets but will undoubtedly have some form of savings. So whilst the Shanghai composite taking an 8% bath wont cause anyone to bat an eyelid, the 8% fall in their BRCI fund might in fact do just that and delay some "discretionary spending"
Last time I checked for "a "New Double Glazing windows" set I was quoted £15,000. That was on top of the £8000 I paid a couple of years ago to have the flat roof all sorted by Everest.
I just don't see that much of a link between a loss in value of a UK fund holding chinese equities / commodities and whether people would buy new double glazing or not....
Sharesoc reckon there are a couple of hundred thousand active investors with non-trivial amounts invested, so that excludes the SID-types etc; if you take out people who own shares in their employers etc, you probably end up with a relatively small investment pool of people (don't forget that we are a small minority here) - and out of those, I suspect it's a fairly small number who are overweight in Far Eastern commodity / mining funds and who have deferred buying double glazing...
Well I won't not use Everest and many of these prices are pie in the sky, start off very high then come down. I would not use companies that sell products with salesreps who are on commission.
"So the way I Iook at thngs, investors in resources stocks might be getting massacred, but that doesn't affect me. It won't affect the number of conservatories that Entu are going to sell, nor the number of frocks that BooHoo shift. All in all, it's just background noise for a long-term UK small caps investor, in my opinion."
Interesting line of thought. Ever considered that those most likely to splash out on a new Conservatory, or new windows throughout the house, or a brand spanking new bathroom are just the kind of people who will mostly likely have put a decent chunk of their savings into the Equity markets(of which a reasonable sum will be in Commodities, either through fund exposure or single company investments.) Given the hammering Equity markets have taken in general - eg Glaxo, Drax, Shell and commodities in particular(Eg BRCI, BRWM as examples) I suspect home improvements will be on the back burner. They are from my POV as an opening evidencer!
The UK economy is far more entwined than you realise. Still on the plus side we;re all spending the petrol savings on more travel etc etc aren't we! Even though we've lost far more as a result of the paltry interest rates we've had for the last 5 years :)
Fangorn, I suspect that the demo profile of the customers of companies that Paul mentioned are less likely to be invested in the Chinese stock market (either direct or via a fund), or in the UK stock market.
I don't think the typical boohoo customer will have a basket of UK stocks, nor will double-glazing salesmen be selling less patio doors because their customers have taken a bath on the Hang Seng. Just a thought anyway...
Also re: IR - I have no empirical evidence but suggest that borrowings far outweigh savings in terms of the number of people having them, and outside of the folk that are lucky to have plenty of savings, the drop in mortgage costs more than outweighs the loss of savings income.
You are right that everything is interlinked, but IMHO it's far better to concentrate on the company, rather than second-guessing the market. Markets, like FX rates, move of their own volition, and there are always winners and losers.
I think people who have large mortgagees tend not to have many savings or shares. People with savings tend to be older and probably have small or no mortgage. It seems double glazing sales are down 10% in the last year. There has been speculation that with the change in pension rules that some people will have funds to spend on their homes.
I don't get the fuss over China, their market goes up 150% and you don't hear anything then it goes down 8% in a day its on the news everywhere. But then most news is bad news anyway. Only problem is if it affects other markets, which it did yesterday.
Have you considered investing in European or US small caps, Paul?
Hi hedley05,
No, I have never invested in US or European small caps. The reason being that there are all sorts of subtle factors which affect our understanding of UK companies, which would be missing if I were to try investing in overseas small caps.
Take McColl's Retail (LON:MCLS) for example. If I were to do a stock screen for overseas companies, I would probably come up with something similar, with a lowish PER, and great divi yield. Yet, as a foreigner, I would have no idea that their shops are often tired & depressing places to visit, and that competitors like Sainsbury, Tesco, Waitrose, etc, are opening far more appealing convenience stores at a rapid pace.
You wouldn't necessarily understand factors like that, if you're a foreigner.
So for me, I would only buy large caps on US or European markets.
Also, I don't like currency issues. An overseas share can go up a lot, but if the currency is dropping, then that can negate the gains.
Overall, my view is that there are many ways to make money from the markets. The method which appeals to me, and which most of the time works well, is to become expert in under-researched, and illiquid stocks - we're spoilt for choice with UK small caps, so why try to widen the net and start making mistakes by buying overseas small caps, where I would be unaware of cultural & business differences to the UK?
Also, there is the danger of spreading yourself too thinly. To my mind, covering 500 UK stocks is more than enough for me! With that number, you remember important things about individual companies. But broaden that to say 5,000+ companies by including US & European small caps, and I think you would end up completely mentally overloaded, and then mistakes would start to happen.
Regards, Paul.
"Yet, as a foreigner, I would have no idea that their shops are often tired & depressing places to visit, and that competitors like Sainsbury, Tesco, Waitrose, etc, are opening far more appealing convenience stores at a rapid pace. "
Your quote reminds me of Warren Buffet buying Tesco shares off Neil Woodford.
Living here, I recognised Tesco stores were indeed tired and depressing & they could not get the stock on the shelves. Being unable to complete my shopping as a result, I started going elsewhere. I figured other customers would do the same. Perhaps Neil Woodford reached similar conclusions, but how would Warren Buffet know about that?
For overseas stocks, I usually go for investment trusts. Something like JEO or JESC does Europe.