Small Cap Value Report (28 Oct 2014) - TEG, UTW, MACF, FITB

Good morning! Another quiet day for small cap news, which is handy as that gives me time to properly research Avation (LON:AVAP) ,whose FD is visiting my Brighton Investor Group tonight to give a talk about the company. We're fully booked, although I suppose one or two more could be squeezed in, although it's awkward because our usual section of the restaurant comfortably seats about 25, and when we go over that we get into a halfway house situation, where we over-spill, but not enough to have the entire restaurant to ourselves. Ah well, I'm sure it will be fine. It's really good that we've managed to generate enough interest to establish an investor group on the south coast, so thank you to everyone who supports these evenings.
Teg (LON:TEG)
It's bad news for shareholders here I'm afraid, as the shares have been suspended today, with the dreaded phrase highlighted below;
The Group has requested the suspension of trading of its shares on AIM pending clarity on its financial position.
As @MrContrarian correctly said this morning on Twitter, "Companies rarely recover from this stage."
It's usually a good idea to look at companies which go bust (this hasn't yet, but it looks on the verge of it) to check whether you spotted the warning signs. In this case, it's obvious that things were going badly wrong. The narrative to the interim accounts published on 30 Sep 2014 made it clear that the company needed additional funding.
Also, the Balance Sheet shows that cash had almost run out, plus there was debt on top of that. Yet again though, the big "tell" is excessive debtors, which we discussed yesterday. In this case, debtors of £8.5m (compared with only £5.6m turnover for the six months to 30 Jun 2014) clearly indicated that something was badly wrong - if customers can't or won't pay for goods/services that have been billed, then you run out of cash, which seems to be what's happened here.
The cashflow statement also shows a worsening position.
I see that Peter Gyllenhammar owns 20.1% of the company, so maybe he'll sort out some kind of rescue refinancing? It's difficult to imagine that shareholders would be prepared to stump up more cash, without agreement first being reached with customers over the disputed contracts. Some sort of compromise deal to partially settle outstanding disputed amounts sounds the best way forwards, if there is a way forwards. Good luck to everyone involved, I hope a solution is found.
As you can see from the chart below, some shareholders had the sense to get out at any price after the 30 Sep 2014 announcement.

Sensible screening of the Balance Sheet and Cashflow statements should mean that you never have a company in your portfolio which goes bust. I've made it my mission to never again hold shares in a company that goes bust, as it should be possible to avoid these situations altogether.
Why do people continue holding when something has gone disastrously wrong? Usually because hope overcomes logic, and/or because the losses have already been so heavy, you can't bring yourself to crystallise the losses.
If a company still has enough cash to operate, then it can trade its way out of trouble. The death spirals happen when inadequate cash resources exist - hence why Balance Sheet testing is so important. Also just because something is shown on the Balance Sheet as an asset, doesn't necessarily mean it has any value - a debtor is worth nothing unless & until the customer has agreed to pay it.
Utilitywise (LON:UTW)
Share price: 289p
No. shares: 74.5m
Market Cap: £215.3m
This is a utility cost management consultancy, for corporate customers - to get them better deals on electricity, gas, etc.
Final results - for the year ended 31 Jul 2014 issued today look good at face value.
Organic growth is very impressive - 62% growth in like for like revenues, which has come from adding more headcount. Total revenue grew 93% one acquisitions are included too.
Profit before tax is up a highly impressive 76% to £13.1m, and headline diluted EPS is up 58% to 13.4p.
Historic valuation - this pace of growth won't be cheap, and sure enough the PER is 21.6 based on that 13.4p figure. Although one could argue that such a PER is cheap, considering how strong the growth is, if that growth is likely to be maintained. So let's have a look at the outlook statement to get a steer on future growth prospects;
Outlook - this is somewhat vague;
The new financial year has started well, in line with management expectations. The increasing diversity of our offering and commitment to further broaden our products and services auger well for the future. Our plans remain to continue to grow headcount to support organic growth; we have successfully integrated our recent acquisitions and we continue to show the strength of our proposition with the value we add to our customers.
We are well placed to take advantage of opportunities as we continue to grow.
Therefore, in the absence of anything more concrete, I'll just assume that broker consensus forecast for the current year are realistic.
Future valuation - another big jump in EPS is forecast for this year (ending 31 Jul 2015), to 17.6p, so that would bring down the PER to 16.4, which looks a sensible valuation to me.
Dividends - A big increase in the dividend is good to see. A 2.7p final divi has been announced, taking the full year payout to 4.0p (up 54% on prior year), a not very exciting yield of 1.4%, but it is at least growing fast.
My opinion - as mentioned before, I have some concerns about this company. The main one is that profits may prove to be unsustainable in the long run.
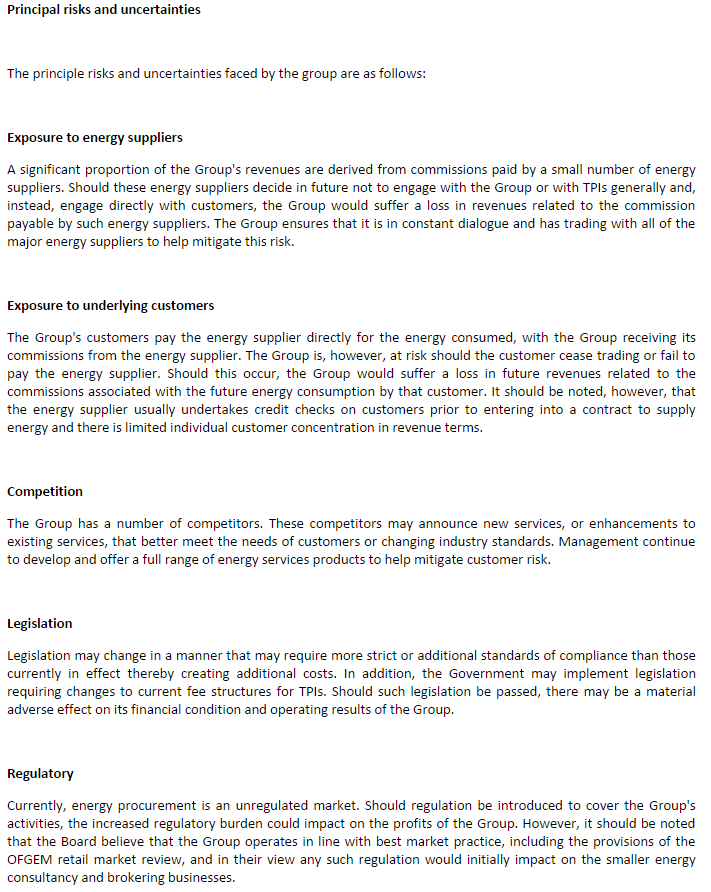
It's worth reading the "principal risks and uncertainties" section of today's announcement, which I've put into a screengrab on the right (click to enlarge).
The following risk in particular shows that the company is on potentially shaky ground;
"A significant proportion of the Group's revenues are derived from commissions paid by a small number of energy suppliers. Should these energy suppliers decide in future not to engage with the Group or with TPIs generally and, instead, engage directly with customers, the Group would suffer a loss in revenues related to the commission payable by such energy suppliers. The Group ensures that it is in constant dialogue and has trading with all of the major energy suppliers to help mitigate this risk."
There are also regulatory risks, although in my opinion the Govt won't usually interfere in commercial arrangements between companies, as opposed to consumer-facing companies.
These risks, combined with the very high profit margins being achieved by Utilitywise, make me feel that this company is probably making hay whilst the sun shines - i.e. arguably making super-normal profits. At some point the utility companies could move the goalposts, and suddenly this type of work could overnight become a lot less lucrative. I've seen that happen in other similar areas in the past, hence generally why I avoid this type of company unless it's dirt cheap, which this isn't.
Balance Sheet/ Revenue recognition - another concern I have here is that the Balance Sheet shows a debit entry of £13,068k within non-current assets (and presumably an additional amount will be included within current assets, inside debtors), relating to "accrued revenue". So the double entry here would be Cr turnover (i.e. goes straight through to profit), and Debit accrued revenue on the Bal Sheet. No cash has been received for this part of turnover, which is quite material. Instead the cash will be received over time, indeed over a year in the future, for the £13,068k within non-current assets.
I'm not keen at all on this accounting treatment. It may be perfectly permissable, but it seems to me that the company is anticipating future profits, and booking them in advance, which is never a good thing. Personally I would reverse out these entries, and account for profit as the cash is received. That would greatly reduce profit of course.
Another slightly odd item on the Bal Sheet is that the company has increased loans from £5m to £6m in the year. Why would they do that, when the company also reports £15.8m in cash? Surely that is inefficient in terms of interest cost? It just makes me wonder whether the cash figure has been window-dressed for the year-end, and might be a lot lower throughout the year (which would explain why the company has increased its borrowings).
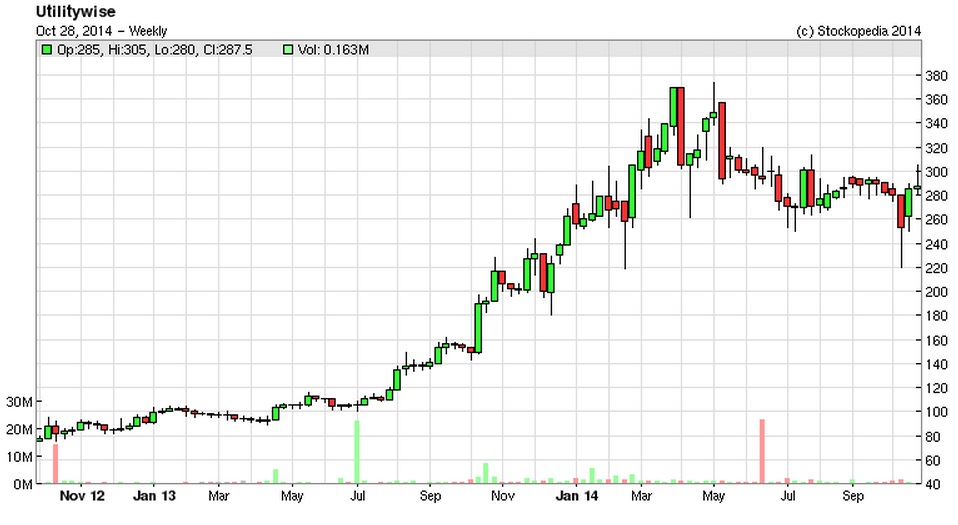
Director Selling - check out the huge scale Director selling, they've banked about £52m selling shares all the way up from 75p to 290p. True, Directors also spent about £4m buying shares in a flurry from Nov 2013 to Feb 2014, but the weight of money overall is massively on the selling side. That's another big red flag to me, and reinforces my view that the company is in a sweet spot for profitability which may not last long term.
Conclusion - I don't like it. There are too many red flags, the accounts look odd to me, and I'm not at all convinced that profits will be sustainable in the long run. Combined with a high valuation, that makes these shares uninvestable in my opinion. It's just an opinion, and I fully expect to get shot down in flames by existing shareholders in the company!
Macfarlane (LON:MACF)
Share price: 35p
No. shares: 124.6m
Market Cap: £43.6m
I spotted an article in the Scottish press today saying that this company has come up with the idea of making packaging materials for online sales, which fit through a standard sized letterbox. This seems such an obvious idea, but appears to have eluded the entire packaging industry until this point. Therefore such a cutting edge innovator is worth investigating as a possible investment.
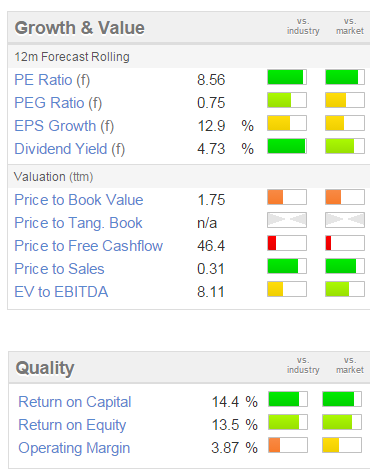
It scores quite well on the Stockopedia value & two of the three quality scores too:
The company did a small Placing in Sep 2014, to supplement enlarged bank facilities, and has done an acquisition which looks sensible in terms of price paid, and terms (an earn-out if profit increases by 40%).
My interest waned when I worked out the that gearing is rather too high for my tastes, and the company has a significant pension deficit, and has just paid £2.5m into its pension fund, suggesting that more will be required to play the £13.2m deficit at 30 Jun 2014.
Although the dividend yield looks good. I note that these shares have come down from a peak of 49p in May 2014, to 35p now, but on balance the debt & pension deficit put me off.
Has anyone else looked at this one at all? I'd be interested in any views on it.
Fitbug Holdings (LON:FITB)
Share price: 7.26p
No. shares: 168.5m
Market Cap: £12.2m
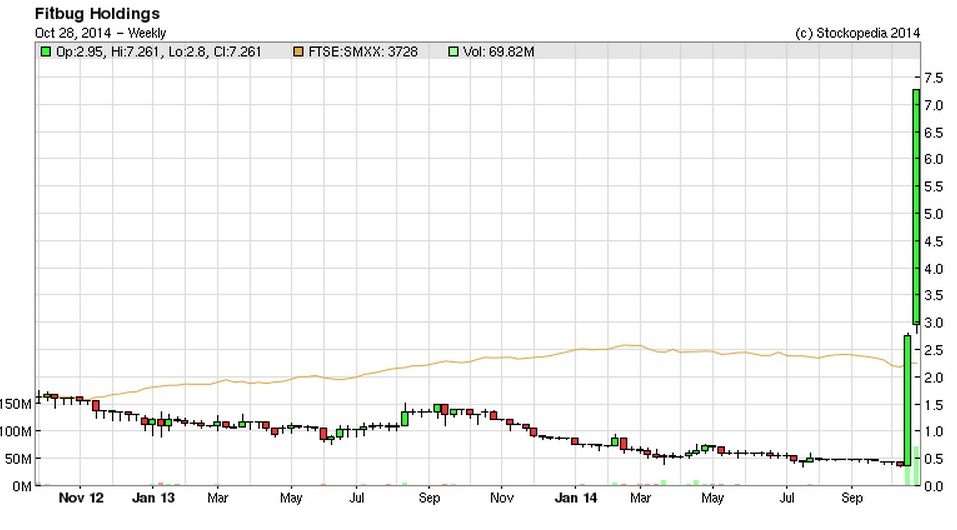
This has only just caught my eye - the shares are up 89% today on an RNS that its product (a wearable fitness device) is to be sold at major US retailer Target, and Sainsbury's. Impressive stuff.
Looking at the last set of results, the company is clearly insolvent, and being propped up with loans. So I'd say it's a racing certainty that a Placing will take place to refinance the Balance Sheet now that there is some good news out.
Also note that the company is taking legal action against a competitor product called FitBit.
As a speculation, it might have further to go, who knows? Check this out for an insane chart!! A 15-bagger in two days!!!
On that note, I shall sign off. I'm looking forward to hosting tonight's Brighton investor evening, so see some of you there, mine's a Peroni!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Looking at UTW again, sp down to 220p, Woodford has been buying now has over 16%, I also believe directors have bought on 15/01/15, however they did pay around 245p.
I'm tempted to buy some if they drop a bit more.
Hello Paul
With Utilitywise are you suggesting Net Assets of £36m should be reduced by £13m or £26m?
Thanks for arranging the BIG event last night
Many thanks for the heads up on Utilitywise - the last time I read similar reviews was for Blur Group and look how that turned out!
Dasv - it's kind of hard to take that particular comment seriously given its tone. And as you say it's hard to tell what's truthful online, spiteful or glowing.
With that caveat in mind, looking at ReviewCentre, there are roughly 1000 good/very good reviews, and 19 poor - which seems pretty good (esp compared to utility companies), and i note the poor reviews have UTW replies in some cases, offering some kind of resolution.
The business model, in my understanding, grew out of the lack of SME focused in-house sales teams within the energy companies, and their preference to use intermediaries like UTW. This coupled with SMEs not having the resource to scan the fairly complex non-domestic market of 24 ish electric and 30 ish gas suppliers (source Edison), has allowed UTW to develop.
It seems UTW does more than find the best price, as perhaps evidenced by the growth in corporate revenues (£9.9m 2014 ) which seem to be more consultative around energy efficiency and management rather than procurement. UTW also aggregates demand across its customers to achieve better prices.
I know that the CEO & director sales generated a red flag, but the green flag was also waved by Woodford becoming the largest shareholder (by picking up a good chunk of those shares), with the CEO still second largest and River and Mercantile third.
But I do take comfort in you Paul finding the actual valuation for forecast growth reasonable, and i guess it is up to people to judge on the sustainability of the business model.
Good point on the £1m increase in loan when the cash is of course stated at a very healthy £15.8m.
FWIW, UTW was given AIM company of 2014 award. Although maybe someone more knowledgeable than me can tell me what actual significance that has...
Cheers
HP
Fitbug is also sold on Amazon, so that could boost the sales before Christmas. I would like to know what profit margins they are running on. 77 million shares were traded today. This is also a global market too for them, with downloads available to mobile phones. An exciting share to say the least. Not many like this about. I got some yesterday.
Cheers
Lightningtiger
Paul further to your bearish thesis on UtilityWise, there are a number of worrying reviews online suggesting that the model is based on duping customers into taking contracts with uncompetitive rates using hard sell techniques.
Also it seems UTW is attempting to bury negative reviews by paying customers (bribing customers) to write positive reviews.
Please see http://bizenergysaving.wordpress.com/2013/09/05/the-utilitywise-rip-off/
It's hard to know what is truthful or not online but this comment to the article would be worrying for me if I was a holder.
"Nicky January 14, 2014 at 9:40 am
I currently work at Utilitywise and am horrified by what goes on at this place!
Here are some examples
80% of the time we are told to push the deal that makes us the most money and not the deal that we should be pushing, namely the one that saves the client money
There are 2 or 3 main suppliers who (household name energy companies) that are quite happy in providing pricing that is in some cases uplifted by 2 to 3 pence per kWh, a competitive uplift would be in the region of 0.2 of a pence per kWh, you do the maths in terms of a company with a 2gig (2 million kWh usage per year), its obscene how much money these people make!
The place is riddled with inadequate managers, and I use the term manager loosely here, from team managers to ops directors, what a joke they are.
Make no mistake, EVERY deal that is put through where a client has been known to be ripped off is authorised by one of the so called managers at Utilitywise.
Even though I work for Utilitywise, not for much longer though, I truly despise the way this company rolls along looking like it is saving clients money, when all the time they simply rip clients off and process business which is bordering on being fraudulent.
I want something done about this company, im leaving in 3 months as I simply cannot be a part of this SCAM
"
UTILITYWISE
"There are 2 or 3 main suppliers who (household name energy companies) that are quite happy in providing pricing that is in some cases uplifted by 2 to 3 pence per kWh, a competitive uplift would be in the region of 0.2 of a pence per kWh, you do the maths in terms of a company with a 2gig (2 million kWh usage per year), its obscene how much money these people make!"
Quite frankly, if you are in business, using 2 million KWh per year; and don't know the competitive price; you deserve everything that is coming to you.
"The place is riddled with inadequate managers, and I use the term manager loosely here, from team managers to ops directors, what a joke they are."
I wish more of the companies I invest in were as humorously managed.
Bonitabeach
Disclosure: Long: LON:UTW
And check out Splosh.com, which we use for all our washing detergents, because they sell the concentrates in plastic tubes that melt when you put them in a bottle and pour hot water over them and, guess what, the tubes are sent to you via regular mail, precisely because they are robustly packaged but designed to fit through any standard letterbox!
'but haven't Amazon been doing this for decades? '
Aye, that crossed my mind - always looking for packaging feedback etc, do they not carry patents on certain forms of packaging (none at hand to check)?? Heathspan (supplier of vits/supplements) have invested heavily in this area too (tubs to blister packs) to ensure delivery (and economies) rather than a trip to the P.O. Flat bottles (HDPE) are readily available too........
...........GPA's problems were not on income side of P&L - were on their expense side - and more particular the liability side of their BS - particularly their funding where they had a mismatch of short-term debt financing long-term assets which was meant to be sorted by a large equity flotation .....................they then hit a liquidity crises post the Oct 97 stock market crash. That business still exists today and has been very successful.
Paul,
having worked in aircraft leasing - a few questions to help with your Avation research:
1) What have your asset utilisation rates been for the past 5 years i.e. % of aircraft on lease or in reverse what is your assets off-lease %.
2) How does this compare with your direct competitors:
3) What is the average period of remaining lease terms
4) What is your average MRF ( Monthly rental factor - being Monthly rental income/total asset cost. Compare this to direct competitors
5) The Dep'n policy point is more precisely defined as over what period to you depreciate your assets and how does this compare to industry norms?
6) What is your current all in cost of debt finance for the past 12 months? How does this compare to the last three years?
7) What is your current leverage %?
8) Are you match funded? i.e. it is industry standard practice to fix your major cash expense - Interest - for the period of the associated lease income. So if you have a 5 yr lease ( rents are generally fixed during the lease term) you should take out a fixed rate loan/swap for a similar period thus hopefully locking in a fixed profit and eliminating interest rate risk. You want to know that this business is a play on leasing aircraft successfully and not a punt on interest rate movements.
In general there is a real opportunity for leasing companies at present because of record low long-term interest rates. Lease income is reasonably fixed - interest rate environment impacts rental levels but not on a one for one basis - so if leasing companies can lock in low interest rates ( which are currently available i.e. 10 yr USD swap rates are 2.5%) then you can increase your profit margins.
Betjeman
I may be a little cynical but unless Macfarlane (LON:MACF) have found an ingenious way to alter physical matter or dimensions in space and time, surely whether the item will fit through the letterbox will depend on the item and not the packaging! It would make a interesting demonstration at an investor event - and for our next act - how to get a kettle through a standard letterbox - our new super physics altering packaging! I'm being silly, sorry, but haven't Amazon been doing this for decades?
And there is no such thing as a standard sized letterbox either.
macf such a small profit margin there is fatter fish in the sea any innovation in the packaging would soon be copied as they say if in doubt leave it out NEXT!
Re Teg (LON:TEG) surely in normal circumstances debtors (if the company offers 60 day terms) should be in the region of 1/6th forecast turnover and if not then turnover (and hence profit) is either being manipulated or the company is controlling its debtors?
Surely either is a red flag? Can on screen for debtors as a percentage of turnover in Stockopedia?
Macfarlane has over 20k business customers and specialises in protective packaging. It is also looking to grow the proportion of trade it does via the internet from 22% to 30% over the next 2 years. ASOS is a big customer and one that should benefit from todays announcement. Their market is fragmented and earlier this year they secured a £20?million bank facility, giving them the firepower to buy up small businesses. One announced so far....
I haven't heard of the company before, so I don't have an opion. I'm glad I don't own shares in it though. I shall save my pennies for a better prospect.
Paul - When looking at AVAP and Co's like it - aircraft leasing - the problems arise when the indistry goes into recession, its said when a national economy catches a cold aviation gets flu'. Thats when aircraft are thrown back to the lessors - AVAP et al - by struggling airlines and airports are littered with unemployed aircraft known as "white tails". it was just such a scenario that took down one of the biggest leasing companies - Guiness Peat Aviation based in Shannon in 1998 just before a planned flotation.
Hi DGW,
Yes that's right - a very cyclical business, is aircraft leasing. Also, depreciation policy is critical - get it wrong, and you suddenly find aircraft bouncing back on you that nobody wants, but are still on the books at £millions.
Regards, Paul.