Small Cap Value Report (29 Dec 2015) - IND

Good morning.
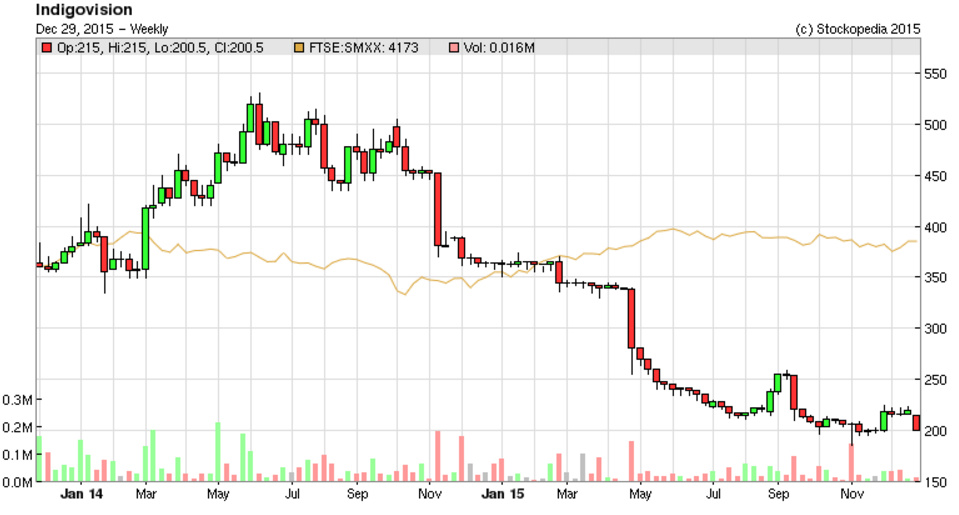
I trust that you had a pleasant break over Christmas. I'm afraid that for me, glad tidings of comfort and joy have already been eradicated by bad tidings of discomfort and rage - a profit warning from Indigovision (LON:IND), so let's have a look at that first.
Indigovision (LON:IND)
Share price: 200p (down 8.7% today)
No. shares: 7.6m
Market cap: £15.2m
(at the time of writing, I have a long position in this share)
Profit warning - this Scottish digital CCTV company had a poor H1, making a loss before tax of $1.3m for the 6 months to 30 Jun 2015, but the outlook statement at the time was much more upbeat about H2 prospects, saying on 17 Sep 2015;
After a disappointing start to 2015, the Group experienced an improving trend in financial results as the first half progressed. The pipeline of large projects for the second half is significantly stronger than the first half and, as a consequence of this and management actions taken to reduce costs, profitability in the second half is expected comfortably to exceed first half losses.
So H2 profit was expected to "comfortably exceed" $1.3m.
Roll forward to today, and we are updated as follows;
As expected, IndigoVision returned to profit for the second half of 2015. Operating profits for the six months to 31 December are expected to exceed $0.5m after a first half operating loss of $1.3m.
The year on year sales decline of 29% reported for the first half slowed, and is expected to be approximately 18% in the second half. Sales in the second half were lower than anticipated, principally due to a delay to a project in the Middle East. The action taken in the first half in relation to operating costs meant that operating profitability was restored in the second half notwithstanding lower sales. Focused working capital management is expected to result in net cash balances exceeding $2m at 31 December 2015, a material improvement over the net debt of $0.5m reported at the half year end.
To quantify the miss, it looks to be about a $1m profit shortfall in H2. The reason for this profit shortfall is mainly down to a project delay in the M.East.
My opinion - it's yet another disappointment I'm afraid. The company's Achilles Heel is that it relies on a handful of major projects each year to make the difference between poor results, and good results.
The overall loss for calendar 2015 therefore looks to be about -$0.8m, which is clearly a poor outcome, and very disappointing for a company which has generally produced reasonable profits, in 5 out of the last 6 years. Although no discernible sales or growth trend has emerged.
With sales down 29% in H1, and 18% in H2, at least the rate of decline is slowing, but sales shouldn't be slowing at all - they should be growing.
The cash position has improved markedly since the interim results, moving from $0.5m net debt 6 months ago, to $2m net cash now, and the balance sheet overall is strong, so the company is pretty safe for the time being. Bear in mind also that most costs are variable, so the company can scale up or down its overheads to suit.
Overall, I expect that other shareholders are, like me, just punch drunk after the seemingly endless cycle of good progress being made, followed by profit warnings. The company doesn't really have much visibility on profitability, because it is so dependent on a relatively small number of high value contracts each year.
So far the company hasn't achieved adequate scale, so I hope that a trade sale will be the exit route. A competitor was recently sold on a fairly high multiple (2x sales), which would imply good possible upside here, if a similar deal could be achieved. So for me personally, this isn't the right time to sell, but I'd certainly like to be put out of my misery by a trade buyer at some point.
A bit of mince pie might have got stuck in the computers at investegate, as the news feed wasn't working this morning, but it seems to be up & running now. As a backup, you can always look at news announcements on the Stock Exchange's own website, here, although it's not very user-friendly in my view.
There's nothing else of any interest to me today, so I'll sign off for today (unless there are any more profit warnings of interest issued later today).
Regards, Paul.
(I have a long position in IND. A fund management company with which I am associated also holds a position in IND.
These reports are my personal opinions only, which are subject to change without notice. They are never recommendations or advice. Please DYOR)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
I have also previously invested Indigovision (LON:IND), Software Radio Technology (LON:SRT) and Dialight (LON:DIA). Lost money on IND and SRT, but got out of DIA at the top of the market. Therefore agree with MarK C comments -all dependent on large contracts. DIA dived due to a lack of large orders in their "obstruction lighting" Division - at least they had other Divisions still doing well. All talked about jam tomorrow, but tomorrow has failed to arrive. Therefore I have now tended to invest in companies like Scapa - making industrial tapes - in different parts of the world for different markets. Sounds boring but a much better investment. Does have a poor stock rank!!
I don't know much about Indigovision, but this opinion might be useful.
I have seen so many labs where scientist/researchers have put software and cameras together that I am prejudiced against the technology (from a barriers to entry viewpoint).
If I were to consider this company I would need to know a lot about the competition and be able to explain exactly why it is better than that competition. It may well be better, but the proof would be in a technical/value comparison of different solutions, not in an analysis of this company's balance sheet.
apad
For me the attractiveness of Ind is tied up in the valuation. The Balance Sheet is strong enough to survive a competitive market place. The business is competitive and lumpy and this is reflected in the operating margin. As a rule I like companies with more than 10% operating margin consistently as it suggests some defence mechanism. They have cash which should enable them to invest to stay abreast of technology. So for me Ind have 3 options
1) they will have a good year or two and you will see their PE increase at which time it is time to take a profit.
2) the competitive nature of the sector will lead to a shake out and they use their cash to buy market or they get bought out. In my experience it is better for shareholders to get bought out.
3) the sales team fail to deliver or margins go downhill.
In my opinion the probability is weighted toward 1 or 2 for the time being. Meantime there is a reasonable dividend!
Hi Paul with reference to your comment "The company doesn't really have much visibility on profitability, because it is so dependent on a relatively small number of high value contracts each year."
it would appear that IND has worked itself into a corner. In 2013 it entered the third year of a three year turnaround when it changed emphasis from encoders ( a big earner in the past) to intelligent cameras and the enterprise markets which give improved margins but lumpy results. It also recognised the need to develop the mid-market and the Chairman said in his 2015 y/e statement " The size of the mid-market is significantly larger than the enterprise market and is of increasing importance to the long term growth...over the past two years, Indigovision has been developing the product range, price points and logistic support required to compete in the mid-market."
IND should now account to share holders as to just what is happening to its attack on the mid-market.
Best wishes for a successful and profitable year to all,
I wonder if Marcus Keen, the CEO of Indigovision (LON:IND) would be willing to do an interview to address the concerns voiced above.
BW,
Ben
"profitability in the second half is expected comfortably to exceed first half losses."
When you think about it, how could this possibly be a meaningful statement given the fact that sales are lumpy?
Perhpas we all put too much stock in management representation in general. We seem to have the idea that managementa can predict the future better than we can; but they're just as subject to all the foibles and mistakes that we are.
Hi Mark
Precisely and for that reason I'm increasingly keen on businesses with very long order to delivery cycles because many of them have their 2016 result all but in the bag now, if a hole opens up in their forward work schedule they can flex pricing ,product and or resources accordingly , Lamprell, Capital Drilling , Galliford Try or Cape for instance.
#hostage to fortune!
Everybody is going to hate me for this, but this company reminds me of Software Radio Technology (LON:SRT). It doesn't seem as though there is any real business here, just occasional targets of opportunity for the company to seize upon. "Lumpy sales" seems to be just another way of saying "lucky sale". I think people are investing in it hoping it's going to be the next big thing, but all it's really demonstrated is that it can make sufficient lucky throws of the die.
Stock Rank 98, so maybe they'll accidentally have a good year sometime and one can cash out at a profit.
Paul/Ed
Please explain how this stock is ranked 98 - given its past performance,numerous profit warnings etc - seems weird
Imagine you have a choice between the 3 following perpetual cash flows:
A) pays £5000 annually, but in every five year period one of the annual payments, picked randomly, is skipped
B) pays £4000 annually without fail
C) pays £2000 annually without fail
If you can pick only one, which one do you pick and why? If B is withdrawn, do you pick A or C?
(Hint: the good rank for lndigovision likely reflects that it's an A priced as if it was a C, looking back.)
Difficuly to see how a rational case for investment can be made.
Information provided by the company is lacking in key data and there is a track record of unreliability.
The directors must know there are questions to be answered, their disinclination to to so is a warning signal.
There are some straws in the wind which might turn out to be positive in the end.
I do not own any shares and will not be buying any.
This market is absolutely fllooded with companies competing for a share of the spoils, both quoted and unquoted. There's no moat and very little to distinguish between any of them. It's no surprise at all that the revenue streams are choppy and unreliable. If i recall correctly C21 had a profit warning not so long ago too. Indeed many of them are completely reliant on one or two large customers, picking up other tit bits during the year. Not one of those i've looked at has any kind of consistent earnings record. Look at the charts of C21, IND, SEV and SNX. The sector has lost it's technical advantage and has become commoditised. A poor investment in my view.
wc
I've held SEV for over 10 years - a serial disappointer though they claim their transition to a recurring revenue model will benefit the bottom line. C21 is another player in the transport space. Although surveillance is arguably a hot concept, the challenge for all these minnows seems to be to grow revenue consistently. Spending on R&D tends to be high, to keep competitors at bay, and I suspect any USP's are rapidly copied. SEV in particular sells in many territories, which means establishing and maintaining distributor networks, who presumably take a chunky % of any sales. Who remembers Appian (APN), one of Michael Walters' hot tips a decade ago? Despite their class-leading number plate recognition technology I don't think they made money for shareholders.
I expect there are some winners in this space - companies with real scale and marketing drive (but not necessarily cutting edge technology) though I haven't researched trade publications. For the also-runs and the minnows a key question for investors is, given they've all been in this game for several years and failed to make a real impact, what catalyst might emerge to change this cycle of lumpy sales and marginal profitability and realistically how likely is this to arise? I'm not sure there's much scope for consolidation as the underlying systems are presumably all quite different but there may be some 'run off value' from existing contracts if, in the worst case, they stopped marketing.
One question perhaps worth asking is what proportion of contracts tendered for are won. This would give a feel for the level of competition - though they might say they can't answer for commercial confidentiality reasons.
Yet another H2 weighted profit warning. As mentioned above, with no forward guidance there is little you can do to value this company at the moment.
Hi Paul,
This is what IND's chairman said in his y/e report of 25/02/2015 which was for a period of 17 months:
" Although sales performance was mixed, the fast pace of innovation has continued and the product portfolio is more competitive in both range and price. Product quality is market leading with very low return rates and strong customer confidence, and this allowed IndigoVision to maintain healthy margins.
The mixed regional performance has continued into the current year, with some regions up and some down, resulting in a quiet start overall. We anticipate growth going forward from the mid-market, for which we have been preparing and positioning product and pricing. The mid-market represents a significantly larger available market than the enterprise market, and this should serve to ameliorate the lumpiness that inevitably arises from the sizeable projects which continue to form a significant part of our current sales base."
I seem to remember that you have had held IND shares for a number of years and that in the past you have called their CEO and FD or met them every six months or so and I presume you will be doing so again. If so, would you care to ask the CEO questions on the lines of those raised by Jane B as well as asking what they are doing in the way of attacking the mid-market? Hopefully the CEO would agree to a phone interview, possibly after the publication of the y/e accounts. Regards, Roger
Must admit that I don't know much about Indigovision (LON:IND), but a competitor I do like is Servision (LON:SEV). Their stockrank is at the other end of the scale - a lowly 7 compared to IND's 98, but SEV have 'has created a ground-breaking system that allows closed-circuit television (CCTV) to be streamed directly and live from moving vehicles'.
http://www.proactiveinvestors.co.uk/companies/news...
Also, from their website: 'Innovative compression techniques make it possible to transmit very high-quality video recordings over narrow bandwidths. As a result, video gateways can stream smooth video over cellular network links so remote users can view live feeds in real-time via their PC, laptop or smart phone.' Management seem pretty convinced this gives them strong, unique technological advantages over the competition.
I bought a few shares in them last month as a speculative play. It may or may not work out, but if it does then I'd imagine it might impact on the likes of IND.
Cheers, James
Dear Paul,
I hope you had a great Christmas break.
Indigovision (LON:IND) is really frustrating and I for one would be very keen to hear from the CEO about how the business can diversify away from large one off contracts to a more granular sales approach. I know Vislink (LON:VLK) have taken a lot of (justifiably) flack but what they have done is move away from a model of selling hardware to selling software via Pebble Beach. I would like to see Indigovision (LON:IND) grow its software and maintenance arm and perhaps change to a different model of subscription for its services??, which should therefore reduce the lumpy nature of its sales.
It seems to be a reasonable company with a very good balance sheet but as you say they do have a tendency to disappoint. In the announcement today there was no mention of pipeline or 2016 and some guide as to if and when the large contract in the middle east will be signed. There is no forward guidance, so we investors do not have much to work with! Perhaps they left the announcement until the 11th hour of 2015 because they thought that the contract in the middle east would be signed?
I bought Indigovision (LON:IND) because I thought about the nature of the world in which we are living and therefore thought that the demand for Indigo's products would be in greater demand.
Would it be possible to do an interview with Marcus Kneen? I'm sure investors and potential investors would really like to hear in more detail about current trading and future strategy.
Cheers,
Ben
Paul,
There ought to be no end of opportunities for Indigovision, given the obvious increased need for urban and industrial security systems, of which videosurveillance would be an important part. Terrorism must only have increased the scope and size of the market that ought to be open to them. They have previously boasted of the local offices they have all over the place. Exactly why these are not translating into sales must be a serious concern. Are their management up to the task? Are their systems simply not up to scratch? It would be the technology and system expertise that any potential buyer would be interested in and, given their seeming inability to actually secure business consistently at a time when their market surely must be growing strongly, one must ask oneself exactly where and what their product offering is lacking. Lots of questions here, no obvious answers.
Best wishes,
Jane.
As a holder I too am bitterly disappointed in the performance. I guess we just hang on in there rather than crystallise the loss. Either a sale or a more effective Saes and Marketing team. Here's to 2016.
Charles