Small Cap Value Report (29 Oct 2014) - AVAP, POS, PSL

Good morning! Thank you to everyone who ventured down to Brighton last night, for my third investor evening, it was great fun, slightly marred by a very noisy restaurant who serve nice food, but are utterly devoid of common sense - i.e. putting other diners in the area directly next to our enclave, where they disturb us to the maximum extent, and it can't be terribly nice for those other diners either, hearing an unsolicited lecture about aircraft leasing when they are trying to enjoy a hilarious, shrieky night out with their friends.
Work has already started on finding a better venue.
The FD of Avation (LON:AVAP) gave an interesting talk last night in Brighton about aircraft leasing. One point which stuck in my mind is that he said the lower oil price is increasing the value of older aircraft, since airlines are now less concerned about fuel efficiency. Also, that once hedging is stripped out, the lower oil price is having a dramatically positive impact on the profitability of airlines. So whilst investors have perhaps been preoccupied with Ebola, a much more positive factor is working its way through the system, in lower fuel prices. So arguably this might be a good time to think about aviation stocks perhaps? Interesting also to look at the rapid, relentless growth in air travel over many years.
I haven't bought any stock as yet, but Avation is on my watch list now, and is something I might dip my toe into on the next big red day - BLASH and all that!
It's quiet again for results today, I must make a note to schedule a holiday for late October next year.
Quartix
Admission to AIM - FinnCap seems to have successfully got away this IPO, for a telematics company. My last interviewee, Edward Roskill, mentioned this stock as one to watch on Sunday evening's podcast. People seem to like these podcasts, so I'll keep doing them most weekends, they're great fun. I loved the Tweet from MrC, saying that it was like listening to two surgeons chatting whilst they dissect a body!
Plexus Holdings (LON:POS)
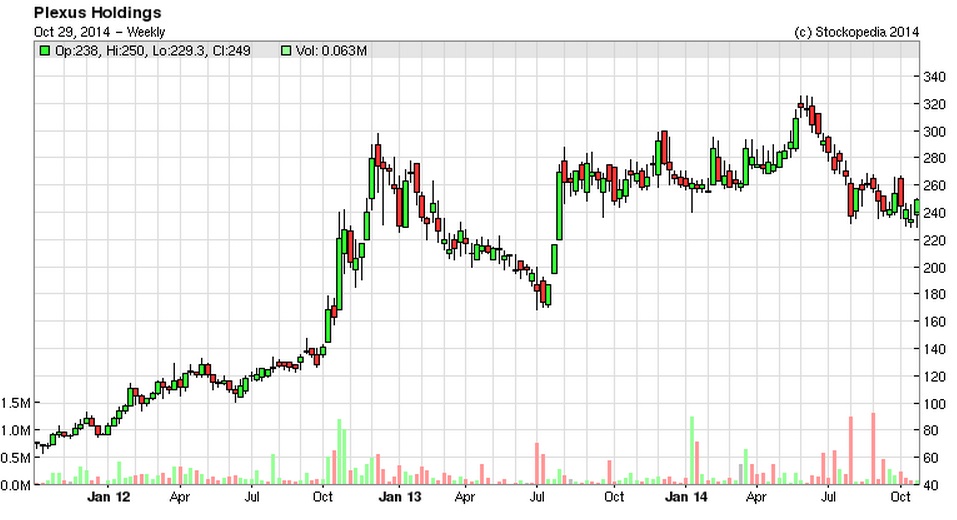
Share price: 253p
No. shares: 84.9m
Market Cap: £214.8m
This company's description is as follows;
The Company markets a patented method of engineering for oil and gas field wellheads and connectors, named POS-GRIP which involves deforming one tubular member against another within the elastic range to effect gripping and sealing.
My first thought is whether the company has been impacted by the drop in oil price, and hence reduction in capex from oil companies?
Final results out today look pretty good. Turnover is up 5.7% to £27.0m, and pre-tax profit is up 25.9% to £5.4m - note the high profit margin there too.
Valuation - the price looks very high based on these reported numbers. Going by the reported EPS of 6.0p, the PER is 42.2, which clearly factors in a fair bit of continued growth that investors are paying up-front for.
Outlook - I don't understand this sector at all, so here is an excerpt from today's statement;
In summary our key strategic goal over time is for POS-GRIP wellheads, whether for surface or subsea exploration and production applications, to become a new industry standard which is recognised as a superior method of engineering that delivers a quality of metal seal that cannot be matched by conventional wellhead technology. The science based driver for our ability to achieve this goal is simply that unlike conventional wellhead designs available from all other wellhead suppliers, Plexus is uniquely able to deliver and maintain enough interface stress between the perimeter of a metal seal and the wellhead bore, within Hertzian Contact Stress limits, throughout the life of the well. In line with this strategy, we are beginning to actively explore how best to exploit this simple message with potential partners worldwide.
My opinion - this share looks expensive on the reported figures today, but if they have a strong growth product, then who knows, it might end up being cheap if the company grows profitability to multiples of the current level? For anyone who understands this sector, this company looks potentially interesting in my view, and worthy of deeper research perhaps. I like growth companies which are already decently profitable, which this is.
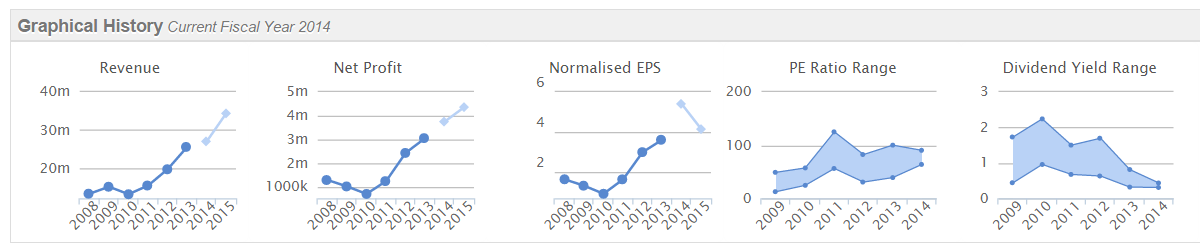
As the graphs below show, the trend on sales & profitability looks positive. Is it worth the £215m price tag? That's the big question.
Broker forecast was for 5.4p, so at 6.0p the company seems to have come in ahead of forecast.
Photonstar Led (LON:PSL)
Share price: 3.25p
No. shares: 143.8m
Market Cap: £4.7m
Profit warning - oh dear, not one of my better ideas this one. I held a few of these in my long-term portfolio, but have bitten the bullet & chucked them out today.
Here is the main part of today's profit warning;
The Group now expects sales of fixed white lighting products for the year to be lower than indicated, due to several large lighting domestic and export contracts being delayed into 2015.
The light engines business has also experienced a slow-down in sales with pressure on margins. The Board has now decided to commit no further development resources to this area of business and focus its efforts on expanding the Halcyon product range more rapidly. The Board believes this strategy will offer a greater return on investment in 2015.
The Board now expects that revenues for the year ended 31 December 2014 will be below market expectations which will result in a loss for the year.
Although the message is mixed, in that the company does make positive noises about new products;
As announced on 22 October 2014, PhotonStar is now shipping the HalcyonPro lighting system - the first wave of Halcyon products (servers, lamps and sensors). The Group is seeing significant demand for its connected lighting products and is realigning its sales partners and channels to reflect this. The formal launch of the Halcyon system with additional products, accessories and connectivity needed to deliver a fully connected lighting platform will take place at Lux live on 19 November 2014.
My opinion - it's not clear from the above statement how bad the loss will be for the year, so it's impossible to value the company reliably at the moment. I've lost confidence in the company, so would rather just chuck them out and move on. One to chalk down to experience I think.
I had hoped that new products might transform the company, but there's no sign of that at the moment, and I wonder whether the company might need to come back for more cash, after the amount raised earlier this year wasn't large.
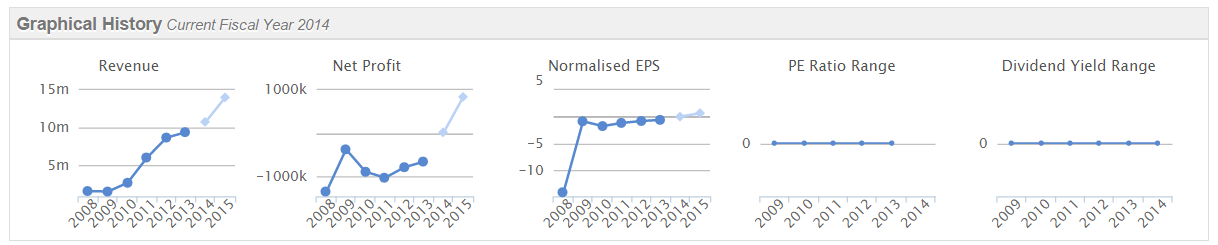
Its track record (see below) is such that the company must be getting close to drinking in the last chance saloon, given that forecasts for this year & next are now looking too optimistic.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
I'm no expert on aircraft leasing and don't hold Avation (LON:AVAP) but when I met the company at a recent conference I came away wondering if the key to their performance are the delivery slots they have for the new ATR-72 600 aircraft. The ATR-72 600's currently make up 10 of their 27 strong fleet with a further 4 and 5 on order for 2014 and 2015 plus options on a further 27 beyond that. This is a plane that came to the market in 2011and has proved popular with short haul operators. It occurred to me that airlines might be compelled to dealing with Avation (LON:AVAP) if they wanted relatively quick delivery of one of these planes and consequently the profits might lie in the delivery slots they have secured from the manufacturers allowing them to get enhanced margins. This might only last as long as demand and supply are out of balance. Others with industry knowledge might be able to comment on this idea.
Andrew
Paul,
A related Aviation business that effectively asset manages other peoples jet aircraft, so they dont carry the cost themselves is Hangar 8 (LON:HGR8) Fuel price movements have little effect because the costs + Hangar 8 fees are recharged to the client who hires the plane. Hangar will report final results in the next few weeks and in the July trade article below reports, "Last month we had the busiest charter month in 7 years, so that has been significant. We have taken a lot of deliveries of new aircraft in the last few months, so that's been good".
See http://www.ebanmagazine.com/mag_story.html?ident=11198
I have a small long position.
Ian
I cant believe you swallowed that nonsense from the FD about companies being less bothered by fuel effeciency Paul. The oil price may be on the way down presently but as you know it could be back over $100 in a heartbeat given the geopolitical tensions. What an absolute prize joke of a statement that is from the FD.
A canvass of any airline management would shoot that statement down in flames.
Avap not currently for me but I did indulge last year when it was in a pe of 6 but no longer hold.
p
Hi pyemacay,
I cant believe you swallowed that nonsense from the FD about companies being less bothered by fuel effeciency Paul.
OK, let me try to explain it a bit better, then you might see the point he made.
Airlines have to make a choice between operating new aircraft, which cost more initially, but are cheaper to run mainly because they are more fuel efficient. Or, they can pay less to buy older aircraft, and accept that they will cost more to run, mainly additional fuel.
So, there is a price differential between older & newer aircraft, which also reflects the wearing out of the aircraft over a 25-30 year period.
What the FD of Avation (LON:AVAP) said, is that because fuel has dropped sharply in price recently, this has had an unusual impact in that it has increased the market value of older aircraft - since the additional fuel they use is now a less onerous cost.
That makes complete sense to me, so I accept the point, and am not sure why you are disputing it?
If we look at the reason for why the oil price has fallen, it's surely due to over-supply, as the USA has dramatically increased its production of shale fuel, and has become a net exporter recently. Combine that with a probable slowdown in China, etc, and it's easy to see why the oil price has come down, and might go down considerably more. Nobody really knows, the oil price is one of those things that nobody seems to be able to predict reliably, hence I doubt whether airlines even try to forecast what the oil price will do, instead they just hedge some of their exposure, and react accordingly on an operational level if the oil price goes against them (e.g. hiking up fares, surcharges, etc).
Regards, Paul.
Paul, there was a great opportunity to buy AVAP at 125 in the last market downturn a few weeks ago.
Fingers crossed for another chance!
The other big beneficiaries of lower oil prices would be producers of fairly low valued added polymers based on oil products derivatives. Most of these basic products are produced by divisions of large chemical companies with lots of moving parts, but there there are companies out there who buy these products. BPI springs to mind -its gross margins will receive a nice boost from lower polythene prices.
Paul
Recently joined, and thoroughly enjoy your columns, not least because of their down to earth nature, most refreshing.
Anything about Avation that you didn't like, or caused mild concern? I ask because I have been keeping an eye on them, and just wondered what your thoughts were on the 'negative' side, as it were, other than thinking the price could become more attractive on a drop.
Many thanks
Kevin
Hi Kevin,
Re Avation (LON:AVAP) - the FD obviously talked the upside, as you would expect.
Downside risks? I would say those are generic to aircraft leasing - i.e. in a recession airline clients could go bust, resulting in planes bouncing back on the lessor (AVAP). We discussed this last night, the FD said it is a risk, but they would keep the deposits, and then just re-let or sell the planes affected.
Another risk is that in a recession there could be a glut of planes, and result in a big write-down to book value, which could potentially be a problem is bank financing dries up, etc.
My view is that it's definitely not the type of share you want to be holding when the economy is going into recession. But in the meantime it could do well perhaps?
I'm leaning towards viewing it more positively than negatively at the moment.
Regards, Paul.
Thanks Paul. Appreciated
Is Photonstar Led (LON:PSL), down a juicy third today, too small for your coverage? Curious to see if it gets a seat on the bargepole list or not.
If you're interested in Aircraft leasing, perhaps a look at Doric Nimrod is in order.
Structure revolving around the lease of aircraft to Emirates - concentration risk to the fore as the aircraft are all leased to the same airline,but it's quite an interesting investment...and great for a spot of diversification/yield
Still struggling to buy in myself as I've set my buy limit and am rigidly sticking to it.
Paul, I thought your last podcast was very interesting, keep up the good work! The only slight comment I would make is that it can be a little 60s-like when listening using headphones, with your voice in one ear and the other contributor's voice in the other!
Thanks, Edmund