Small Cap Value Report (3 Dec 2015) - INTQ, TRCS, IMO

Good morning!
Apologies for the lack of a report yesterday. Things seem to be starting to improve, with the patient (in hospital) showing early signs of recovery, so I'm getting back into the usual routine again now. Therefore there shouldn't now (hopefully) be any more gaps here.
Ed's doing a webinar at 1pm today, and it looks like it's on track to be the most popular ever - with seats limited to 500. Hardly surprising, as Ed's NAPs portfolio, selected using StockRanks, has returned an astonishing +38% performance YTD. If there are any seats left, the link is here.
InternetQ (LON:INTQ)
Share price: 77p (down 42% today)
No. shares: 40.3m
Market cap: £31.0m
Damaging article - in a pattern which is now becoming increasingly familiar, another dodgy-looking company has been attacked online, with serious questions being raised by Tom Winnifrith over its accounts, and operations.
Stockopedia readers already know to avoid this share, as I've written about it five times here since Apr 2014, each time warning that the profits are not genuine (but are manufactured by capitalising a large amount of costs into intangible assets), that debtors were too large, and various other remarkable similarities to Globo, which led me to conclude in Jul 2015 that InternetQ looked "an almost carbon copy of Globo". That was before the full extent of the Globo fraud was known, of course - actually, we still don't know the details of what really happened at Globo, nor what has happened to the culprits since the wheels came off.
So the next step no doubt will be that InternetQ will issue a rebuttal document, and will either blow over, or blow up.
I haven't shorted InternetQ (pity) because it did get some third party investment into one of its companies, although from a fund that doesn't strike me as being the sharpest knife in the drawer (Tosca), with regards to its small & micro cap investments anyway.
It will be fascinating to see how this pans out, but once again it reinforces the point that AIM is a magnet for awful overseas companies, and it's safest to just avoid all of them, in my opinion.
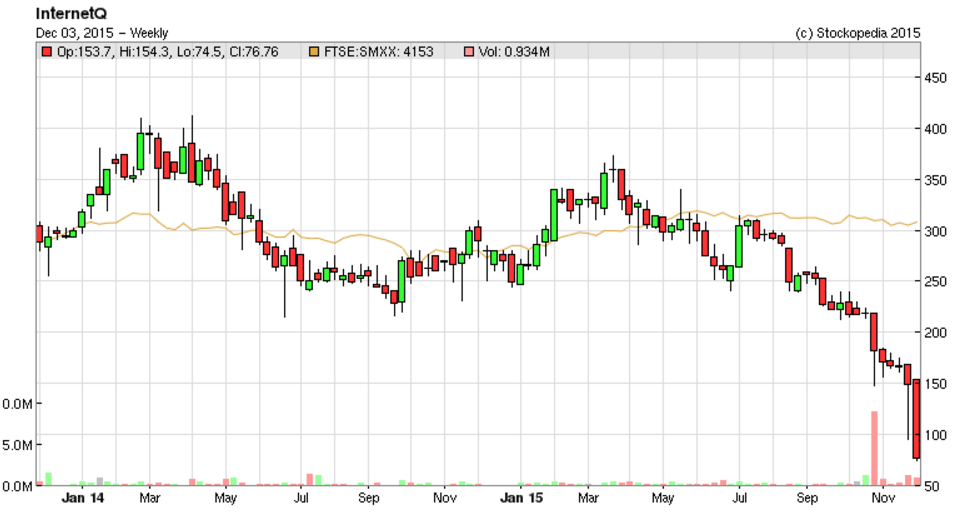
EDIT: here we go, there's a rebuttal statement from the company. It confirms that trading is in line with management expectations;
InternetQ plc (LSE-AIM: INTQ), a leading provider of mobile marketing and digital entertainment solutions for mobile network operators and brands, notes the recent share price decline and related market speculation. As a matter of course, the Company does not normally comment on such matters. The Board, led by the audit committee, will of course review the allegations however given the factual inaccuracies in the blog post the Company has taken the decision to strongly refute the assertions made and the conclusions drawn. The Company would also like to state that it has not been contacted by the author in advance of publication.The Company confirms there has been no material change to the operational and financial performance or outlook for the business as set out in the Q3 trading update and that trading remains in line with management expectations.
So far the rebuttal statement has not triggered a rebound, which is unusual, as in these situations the share usually rallies for about 24-48 hours after the rebuttal statement is issued.
Tracsis (LON:TRCS)
Share price: 520p (up 6.6% today)
No. shares: 26.7m
Market cap: £138.8m
Acquisition of Ontrac - Ramridge asked me in the comments section below, to have a look at an acquisition announced yesterday by Tracsis, of a rail software company called Ontrac.
Adjusted profit before tax was £2.4m for the year ended 31 Jan 2015. I've had a quick look at the abbreviated accounts filed at Companies House, and 2014/15 appears to have been a bumper year, with profits greatly increased from the previous year. So my only concern is whether this level of profitability is sustainable or not?
Tracsis management have a superb track record of making good acquisitions, so I'm sure they've done their due diligence thoroughly.
The price paid certainly looks reasonable, if profits are indeed sustainable, and the deal is structured with additional earn-outs, if profit targets are hit, which is the best way to structure deals in my view, as management are heavily incentivised to keep up performance after the deal completes.
The market clearly likes this deal, as the share price has responded positively in recent days. Tracsis has a very thorough, and commonsense approach to acquisitions. It's a class act in my view. Also, as this deal is putting the cash pile to work, it has just bought in a significant extra earnings stream, using cash that was just sitting in the bank doing nothing. That makes a lot of sense to me.
IMImobile (LON:IMO)
Interim results - just a quick mention, as time is running short. The headline figures look solid - revenues up 29% to £27.8m in H1, and adjusted profit up 19% to £2.7m.
Points to note;
- Share based payments are substantial, and should be expensed as remuneration in my view, not adjusted out.
- The balance sheet is strong, with net cash.
- Note that there is a significant non-controlling ownership element (what used to be called minority interests), due to not all subsidiaries being 100% owned (see note 2 in today's accounts)
- The cashflow statement shows that capitalised development spending was fairly modest, at £419k, which is pleasing.
- Note that the ownership structure is very concentrated, with little free float, so it's illiquid and can be tricky to deal in.
- Coincidentally, our friends at Tosca are the biggest shareholder, with 34.3%
Outlook - this sounds confident;
The Group remains on track to achieve market expectations for the full year. The sales pipeline is well diversified across sectors and regions and the acquisitions are trading in line with expectations. We continue to invest in our product portfolio to capitalise on the use and growth of new mobile and digital customer engagement channels and we see good levels of interest from our large blue chip customers in all our operating regions. As a result the Board are highly confident of the Group's future prospects.
I met the CEO of this company shortly after it floated, and he struck me as one of the smartest CEOs that I've ever come across in the small cap space, over quite a detailed briefing and Q&A. So overall I think this is a potentially interesting company to look into more.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
Re. IMImobile (LON:IMO)
It should be possible to check extent of dilution by comparing the number shown in the StockReport under Average Shares (44.3m) with the corresponding figure under "Diluted Weighted Average Shares" in Income Statement (click on 'Income' just across where it says Financial Summary).. Unfortunately in the case of IMO the data is wrong! It shows 44.3m when it should be 63.3m.
Maybe someone in Stocko could look at this?
Hi,
I hadn't spotted the issue with share options dilution - if the potential dilution is over 10% of the existing equity, then normally I wouldn't touch a company. So 40% dilution sounds outrageous! Will check that out when time permits, but many thanks for flagging the potential issue.
As I always say, investing is a team sport, and I can't cover everything single-handedly, so it really adds value when readers comment here about pertinent issues, and specific info that I haven't covered.
Many thanks, Paul.
Herbie
Take a look at note 5....EPS in the interim statement. It's always worth finding out how they calculate diluted EPS, it can be quite revealing. Also with normal EPS, whilst average weighted number of shares for the year is a fair way of accounting, always take note if the updated number of shares are very different as this "may" affect future EPS.
Edit - Nigelo beat me to it.
I had a quick look at IMImobile (LON:IMO) and I see that there is potential for 40% dilution due to share options. That is where my interest in the company ended.
Where did you see that?
In Note 5 of today's interim statement:
Weighted average number of ordinary shares for the purpose of basic EPS 48.0
Effect of dilutive potential ordinary shares: share options 19.7
It seems to me that any downside would be borne by shareholders but upside is creamed off for insiders. The CEO does indeed sound very smart.
OK thanks. I knew it was 11 before, yes something to watch out for.
Well I must say I was tempted to take a profit in Tracsis after its heady recent rise on the basis that selling on the good news is quite often the right thing to do, plus what looked like very heady forward valuations. I was especially concerned by the high price to sales - mkt cap is around 138m, last year's notional profit around 7m and I suppose revenues around 32m if you just add Ontrac to the Tracsis 4.5m profit and 25m sales. But I haven't done anything as just perhaps the acquisition takes it a step up and into new client territory, the big league if you like. Let's hope so though a reaction wouldn't be a surprise? What do you think?
I do hold Tracsis (LON:TRCS) as well, yes its tempting to take some profits I agree. I think share price will fall back soon, I was considering holding and topping up on any falls. I thinks its a good company, well managed, my only regret was was not buying more.
Paul
Re: InternetQ
Once again, investors owe you a big vote of thanks for your continued vigilance in highlighting these dubious companies.
There can be little doubt those that heeded your constant warnings would saved themselves from a somewhat poorer Christmas, today!
Yes IMImobile (LON:IMO) does look interesting, the spread today is only about 1%, normal trade is 2,000 shares which may put some off, I have bought a few.
Re. Tracsis (LON:TRCS) Much appreciated , Paul.
Paul, Glad to have you back.
Interesting discussion 2 days ago on CCT (Character's) results. Interested in your take. Seems to scream value- but you have a talent for spotting the suspicious stuff!
Thanks!
Hi Paul - Really good to see you back.
Yesterday Tracsis (LON:TRCS) made an interesting acquisition. My initial analysis was very favourable and therefore bought a decent amount (besides being impressed by John McArthur). Would be interested in your take.
Regards, Ram