Small Cap Value Report (3 Feb 2015) - LWB, NWF, NBI, ALU, CRE

Good morning. It's a fairly short report today, as I'll be heading to the Islington Design Centre shortly for a Cenkos/Shares investor forum, as there are a few interesting companies having stands there. There are also several companies which I have been rather uncharitable about in these reports, so I might need to dispose of my name badge before approaching their stands!
Low & Bonar (LON:LWB)
Share price: 52p
No. shares: 327.8m
Market Cap: £170.5m
Final results for the year ended 30 Nov 2014 are out today. About two thirds of this group's turnover is in Europe, so they have suffered from a generally weak economy, and exchange rate weakness. So there was a profit warning in Sep 2014, but the company then put out a more reassuring trading update in Dec 2014, which I reported on here.
Looking at today's results, I'm moderately impressed that the company has performed alright, when up against macro & currency headwinds. As you can see from this highlights table in today's results, it had a reasonably good year before currency movements, with both turnover & profit solidly up in constant currency;
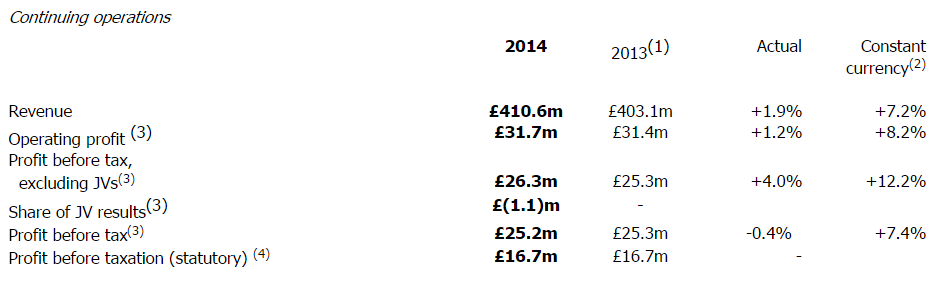
This seems quite a lot of business for a market cap of £170.5m.
It clearly has some pricing power too, as the operating margin isn't bad. The group makes a wide range of niche industrial fabrics, and coatings, e.g. advertising hoardings, artificial grass, flooring materials, etc.
Net debt - as I've mentioned before, the level of net debt here is quite high, and the latest number reported is net debt of £88.0m. This has worried me in the past, but I've done a bit more digging, and note from the 2013 Annual Report that all borrowings are unsecured. That is a very good sign - as it means the bank is extremely relaxed with its exposure to the company, seeing it as extremely low risk.
The old bank facility was renewable in Feb 2015, so I've checked today's statement for more details on that, and am pleased to note that a new 5-year facility has been agreed, on improved terms;
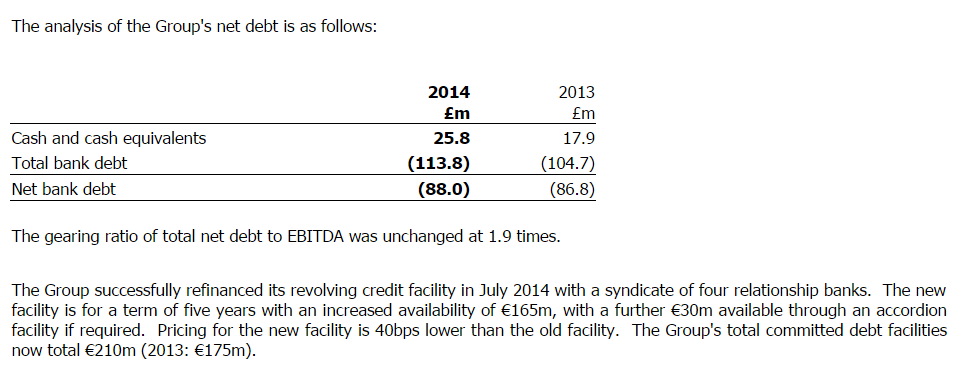
This looks OK then. If the banks are relaxed, why should I be worried? Well, bank managers can easily change their minds, especially in a recession, so it's not a stock that I would want to hold in a deteriorating economy, and/or another banking crisis. Outside of those times though, it looks a reasonably good proposition.
Pension deficit - this looks under control, and isn't huge. Although I note that from the 2013 Annual Report, overpayments were quite significant, at around £3.6m p.a.. So I need to do a bit more research on this. Ultra-low bond yields mean that pension deficits are sticking around, and indeed increasing further in many cases, at the moment.
Dividends - are one of the main attractions of this share, giving a very healthy yield of about 5.6%. The final divi is maintained today.
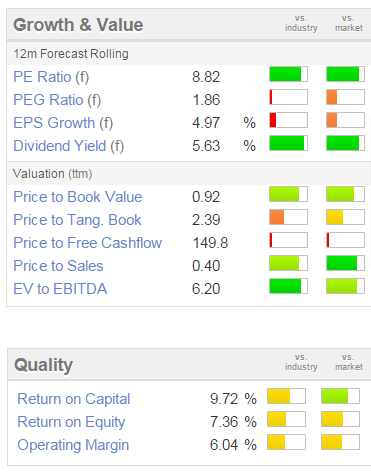 Valuation - it looks cheap (see the usual Stockopedia graphics on the right), but bear in mind that the PER is flattered by the considerable amount of debt. Although there is some freehold land & buildings on the balance sheet.
It's a generally capital-intensive business, so you could just accept the debt as being there to finance fixed assets.
My opinion - I am gradually warming to this company. It has proven that it can finance the pension funds, capex, and still pay generous divis.
Trading in 2014, when up against considerable headwinds, has turned out alright - so I like a business that can get through a tough patch unscathed.
The high level of net debt does worry me still, but there is plenty of headroom on the facility, and it was recently renewed. The company has some freehold property, and generates very strong EBITDA, so the bank are likely to remain supportive on an ongoing basis.
Upside could come from a recovery in Europe (who knows when, but it will recover). Also I note that LWB is spending over £20m building a new factory in China, so that should provide considerable opportunities for future growth from 2016 onwards, as China is a huge market for these products.
Overall then, I think it's an interesting stock, with a very good dividend yield, and a reasonable chance of a capital gain if you take a 2 year+ view. As usual, I'm very interested to hear readers opinions in the comments section below. Do you share my cautious optimism for Low & Bonar, or are you more wary?
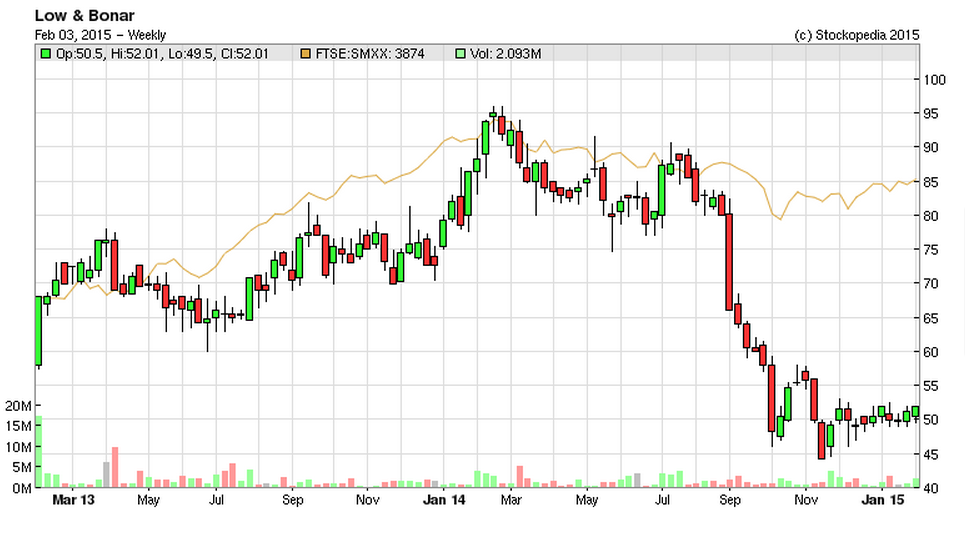
I also like charts where the shares have fallen a lot on bad news, which then turns out to be actually not that bad after all, and where the shares have seemed to bottom out over several months. If the stock is reasonably priced, then providing there's no more bad news, the trend might become an upwards one next, possibly?
Oil price
I'm keeping a close eye on this, as I'm sure many readers are, to try to determine if & when to take the plunge and buy some oil producing, or oil services shares. Some have already bounced quite nicely - e.g. I mis-timed my buy in Pressure Technologies (LON:PRES), but am now in profit on that one.
I note that engineering group Goodwin (LON:GDWN) which had appeared on my radar, bounced strongly in Dec & Jan.
Another one to bounce is Lamprell (LON:LAM) which was starting to get interesting when it fell to 90p, but has since bounced to 116p.
The big question is whether these bounces will last? Surely the newsflow is bound to be unrelentingly bad for some time to come, as it will take a longer term recovery in oil prices for capex to get back anywhere near previous levels. In the meantime companies providing equipment & services are going to be under enormous pressure to cut their prices.
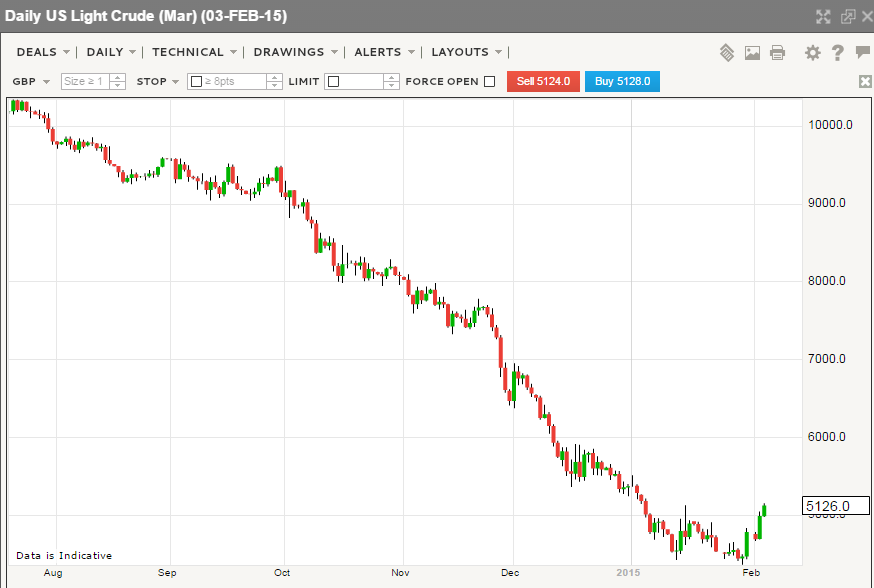
I see that we've had the strongest-yet bounce in the price of crude oil in the last few days, as you can see from the candlestick chart (courtesy of IG) on the left. So all eyes are on this, wondering whether this is the beginning of a recovery in the price of oil, or just a larger than usual blip within a down-trend? Nobody really knows - one thing we've learned in the last year is that you can safely disregard the views of almost all analysts & experts about the price of commodities, as they haven't got a clue any more than the rest of us!
I note that quite a few low quality oil stocks (things where debt so outweighs equity that the equity arguably has little to no value) are spiking up, but those type of moves can reverse just as quickly as they start, so those are best left to gamblers only.
The plunge in oil price recently has just reinforced my aversion to the whole resources sector. Why invest at all in companies where their viability can be snuffed out in just a few months, if the price of the product they extract collapses?
Mello Bloomberg
Many of you know renowned small caps investor, David Stredder, who has been organising investor evenings & events under the Mello name for years. His latest idea is an evening at Bloomberg's London offices, with some excellent speakers lined up, including Mark Slater, who's always worth listening to. There is an entry charge, but that includes hospitality laid on, all for a relatively modest £49 fee.
I know tickets are selling fast, I've already got mine, so for anyone interested in coming along to this tech-themed evening, here is the link.
STOP PRESS! I've just asked David for a discount code for Stockopedia readers, and he's given us one! So please use the discount code: DISCSTOCK when buying tickets, and you will get £14 discount, reducing the price from £49 to £35.
NWF (LON:NWF)
Share price: 128p
No. shares: 48.3m
Market Cap: £61.8m
Interim results for the six months to 30 Nov 2014 are out today. They don't look much good to me. Operating profit fell from £3.6m in H1 last year to £2.8m this year, and that's barely above a 1% operating margin, on turnover of 24/7 Gaming Group (LON:247).1m.
The falling milk price seems to be a particular issue, and it makes you wonder what they are going to put in the animal feed to make it cheaper? On balance I'd rather not know;
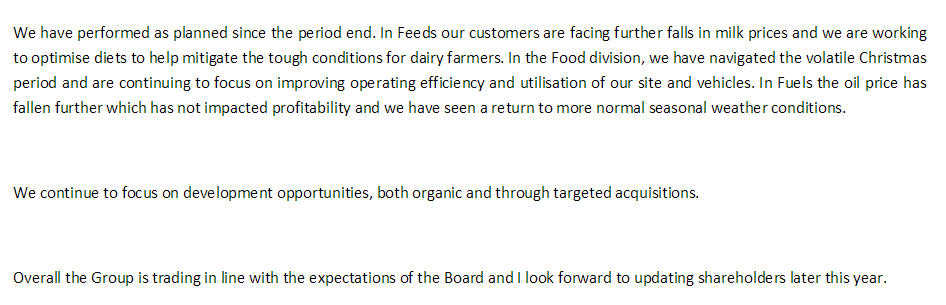
My opinion - I can't see any point in investing in a business which only ekes out a 1% profit margin. That's not enough to absorb any bad events. That said, this company does have a track record of paying decent divis, consistently.
However, I don't think it's sensible to invest in any part of the supply chain for supermarkets, as they will all be under unrelenting price pressure for the foreseeable future. The risk to this company is surely that they might see a rising incidence of bad debts, as more farmers go bust. If 1% of their customers by value go bust, that wipes out all their profit. It's not for me.
Northbridge Industrial Services (LON:NBI)
A cautious outlook today, due to the impact of reduced demand from the oil sector;
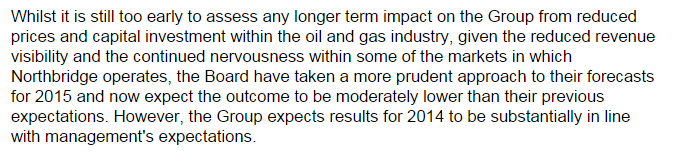
So with some uncertainty here over future trading, I'll probably give this share a wide berth for now. Although having said that, at 384p, the shares are down substantially from a peak of around 600p last summer. So it ties in with my comments above about oil services companies, that at some point there could be a favourable entry price, we just don't know when.
Alumasc (LON:ALU)
I don't have time to review them properly, but the headline figures for interims published today look good, so worthy of a bit more research perhaps when time allows.
It looks cheap on the Stockopedia graphics, but I seem to recall there is a pension deficit here to consider. If you check back in the archive here, for my previous comments, I've been through the accounts in detail several times.
The shares are up 9% today, so the market clearly likes these results. The outlook statement sounds upbeat too, so could be an interesting company to research in more depth perhaps?
Creston (LON:CRE)
Softer trading in their health division has resulted in expectations for the current year being trimmed a little. Doesn't look disastrous though.
Shares are off 9% today, which looks a sensible reaction to a mildly negative trading update.
I've noticed that a few advertising/marketing companies have been dropping of late, so confidence in economic recovery is perhaps becoming more fragile?
That's me done for today. Back tomorrow, with some comments on companies I see this afternoon at the Shares/Cenkos event, in addition to tomorrow's review of the RNS.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in LWB & PRES, and no short positions. A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Paul,
To check for freeholds do you just check operating leases, finance leases and depreciation on property?
Thanks,
Morning Beginner,
Don't own any Getech, but I'm not so sure that they will be squeezed that badly over the next couple of years. My limited understanding of their business indicates to me that they are a low cost service, when compared to the "real" oil service company expenditure on seismic, access provisions to facilitate drilling, drilling and interpretation. What they provide aiui, is early information needed to define areas of interest, before companies bid for licenses, and further info to define more clearly areas of interest within newly awarded licenses.
As the whole process from pre bid stage to the start of serious expenditure with seismic etc takes quite a while, measured often in years, I would imagine that a service which doesn't cost enormous amounts but enables oil companies to choose areas of interest more successfully pre license application and then beneficially refines the information pre seismic, might suffer a little as part of an overall reaction to the oil price, but could well benefit from oil companies looking two years down the road and wanting to define the best areas of interest.
Regards.
Hi Muckshifter
I reckon you are right, and Getech (LON:GTC) may be less impacted on than others in the field, but I am told that BP (LON:BP.) are getting rid of manual staff and clerks in Scotland. This suggests the cuts will be huge, deep and far reaching. Even Getech (LON:GTC) may feel them (I have no Getech (LON:GTC) position and am not looking to take one up. Potentially I like Hunting (LON:HTG) though).
Hi Beginner,
You are right of course, and I have sized my positions accordingly.
Steve
The thing about Creston (and other small marketing agencies) is that revenue is very dependent on a few clients, so the chances of a profit warning is always in the air. IMO, it is always worth looking at them on a cyclical basis - buying after a profit warning or two, and then selling on the rebounds above a PE of 12-14x
The oil price has risen but price of around $50 pb is still too low for most companies to make a profit. With oil running out in some areas and the need to drill deeper wells which is more expensive and risky, see BP Mexico for example.The insurance rates are much higher for deeper wells. I read an article recently about the production costs for each oil producer which was interesting, Dragon was the lowest (maybe too low?).
With regard to the oil related stocks jumping today on a bit of news, it would appear that after the oil price consolidating for a couple of weeks ,this is just a Technical bounce as the consolidation has been read as the bottom & traders piled in. They may well bale out just before 63.0 .to create another buying opportunity latter. Plenty of time.
Hi Paul,
I read your email pretty much every day and find the analysis admirably consistent and considered despite your other obligations -- not surprised to see you have had job offers! I am a firm believer in the internet's potential to evolve and democratise the investment process and I believe that several members of Stockopedia are accomplishing this.
Just wondering if you have any thoughts on the creston Q3 update (http://www.digitallook.com/cgi-bin/dlmedia/rns.cgi?action=news&rns=1&view=full&story_id=22445910)? No worries if not, I just bought a small, speculative holding and am looking for a second opinion. It's a warning, but a mild one upon inspection.
Also, with your background in retail, do you have any thoughts on Findel? You have dismissed it in the past and it is certainly an unusual company. I have written a piece here:
https://indieinvest.wordpress.com/2015/02/03/findel-plc-basket-case-or-rough-diamond/
I have included a part on its consumer credit book etc. but I was just wondering if you had any more thoughts on it? Considering your regular balance sheet analysis and retailing background, I would value your input!
Cheers,
Jack
Hi Jack
Paul's covered Creston (LON:CRE) Q3 update in the article above.
Best wishes,
Imran.
Ref Low & Lonar
I don't understand companies like Low and Bonar in the current credit climate - personally it would be much better if they cancelled the divi , managed cashflow and used the vast majority of cashflow to pay down debt for 2 years. Anything above double profits for debt is potential suicide in 4 years time or sooner if profits take much of a dip or interest rates go up and lending can't be rolled over.
Even a hybrid plan where they aim to reduce debt by £10 pa for 5 years would give confidence.
I have noticed that the share price of companies that morph from high but on the face of it manageable debt into less high debt tend to do well share price wise (ISG being a good example where they did a good job on the debt)
Presumably management group think that investing for the future of the business instead is on the balance of probabilities the only way forward at all times, sometimes they are right but when they are wrong and high debt is an issue it can end badly. With the modern changing world we live in relying on the fact that the business has always managed for the last 100 years is a slightly dangerous thing.
Anyway rant over - i still think that the debt is very manageable from a practical perspective i would not preclude it being worthy of a small punt - but from, a risk point of view worst case scenario there are probably plenty of safer bets at present.
I seem to remember as a kid my mate had unlimited supply of Low & Bonar playing cards which always impressed me. Oh for the old days when little pleasures were big pleasures.
According the AD.FN podcast Nik reckons its a DCB in Oil.
Paul,
I have looked and the Oil and Oil support companies and decided to invest in the price of oil itself. My reasoning is that the odds of Oil going up are greater than it coming down and that Oil producers who cant produce at current prices will wind down production or go bust, which will address the over supply issue. My modest "investment" is in ETFS Daily Leveraged WTI Crude Oil ETFS DAILY LVG WTI CRUDE OIL ETC (LON:LOIL) which tracks the daily oil price with 2x leverage, which reflects 200% of the daily percentage change, (up or down). So double the pain, or gain! Ian
Hi Ian,
I think there could be some bargains to be had in the oil support services sector at the moment. I have recently had a nibble at Getech (LON:GTC) and Cape (LON:CIU) both of which have been out of favour recently but are showing signs of recovery and are paying nice dividends to boot.
Steve
Take care Steve. Getech (LON:GTC) and Cape (LON:CIU) are essentially oil services companies. Paul's podcast with Mr Curtis suggested these will be squeezed by oil companies well after the oil price starts to rise again. Also remember BP (LON:BP.) reckon oil will stay low for a couple of years yet. Many experts seem to think oil is still searching for a firm bottom. Those dividends are vulnerable, especially at Cape (LON:CIU) .
See http://boards.fool.co.uk/which-oil-companies-for-the-long-term-13156501.aspx?sort=whole#13156501 for the hidden costs of using an EFT or even worse a geared EFT for playing oil.
MrContrarian; Thanks for the Motley Fool link which discusses the maths of levered Oil EFTs. The daily compounding points are well made and the conclusion is that they work well for a short term oil play when Oil prices are rising, but nothing more. Ian