Small Cap Value Report (3 Jun 2016) - GOAL, SVS, SEA

Good morning!
It's a very unusual day today - there are no results or trading updates at all, in my universe of stocks. That's rather handy actually, as I'm off on a jolly today - I'm visiting English wine producer, Chapel Down. Their shares are listed on ISDX - I reviewed recent results here on 22 Apr 2016. Pity I didn't buy some shares, as they're up 41% since then - a big rise in just 7 weeks.
There are decent shareholder discounts (about 33%, from memory), if you own 2,000 shares or more in CDGP (about £930-worth at current share price of 46.5p). Mind you, on trying their white wines previously, which retail for about £10, personally I wouldn't seek them out. Perfectly pleasant, but nothing special, in my view. I reserve the right to change that stance, after today's slap-up lunch, and wine-tasting at their premises. So there's the distinct possibility of some rambling Tweets later today.
A few other things have caught my eye today, so here goes.
Placings (again)
Some readers may recall that, a couple of years ago, I set up a (now defunct) website called PlacingWatch. I reviewed every Placing that occurred, and rated it on some key criteria;
- Whether there had been suspicious share price movements in the month before the Placing was announced (which there often were).
- Also I looked at the level of discount to the prevailing share price for each Placing (the smaller, the better).
- Dilution should not be excessive (where the price discount is large)
- Finally, I urged companies to include an Open Offer for existing shareholders to participate - especially where the price discount was significant.
I had expected to find considerable problems. However, in most cases, the deals done actually looked perfectly reasonable. If you buy shares in a small company, with a weak balance sheet, then you should accept that at some point you're likely to be diluted a bit by a Placing.
Institutions usually demand a discount of say 5-10%, to compensate them for the lack of liquidity - i.e. if something goes wrong, then they can't exit quickly, unlike small shareholders. That's not unreasonable.
You only really need an Open Offer for existing shareholders if a deeply discounted Placing is being done. If there is a deep discount, then chances are the company is crap anyway. So shareholders can't really blame anyone other than themselves if you get caught up in a situation like that.
Placings do however rely on privacy, and everyone respecting the rules on inside information. This quite obviously doesn't happen right now. Whether it's spivs who are told about the placing, and then break the law by insider dealing in the shares. Or misguided journalists/bloggers unilaterally deciding to scupper a deal by publicising inside information. Both make a mockery of the current system where a company's shares continue to trade, in what is undoubtedly a false market whilst a fundraising is being done on the quiet.
The only solution is to suspend shares once the fundraising process begins. Only then can there be a fair market in any share. Fundraisings should be done quickly (say, within 1 week), then the shares should resume trading. That is the only fair way to do it. I look forward to brokers taking up this point, and hopefully some might take a lead on this issue, demonstrate some integrity, and do things in the fairer way I suggest.
So what is the essence of a good Placing? It should:
- be done quickly,
- have no impact on the share price (i.e. no leaks),
- and at only a modest (under 5%) discount to the prevailing share price.
Whether we like it or not, the best way to achieve the above is by the broker only involving a small number of Institutions.
In an ideal world, I think companies should actively manage their shareholder base to achieve a roughly 50:50 split between Institutions and private investors. The role of each is then:
Institutions - to support Placings when the company needs more funds, e.g. for acquisitions.
Private investors - to provide liquidity, narrow the spread, and set the price. There's not much point in having a listing, if there's no liquidity in the shares.
Goals Soccer Centres (LON:GOAL)
Share price: 107p (up 3.4% today)
No. shares: 58.5m + 16.75m Placing shares = 75.3m post-Placing
Market cap: £62.6m (pre-Placing). £80.6m (post-Placing)
Placing to raise £16.75m & strategic review completed - this deal falls squarely into the "good placings" bracket, in my view. So a pat on the back for Canaccord Genuity in this instance.
The Placing price of 100p per share does not disadvantage existing holders at all, as you can see it's at the top end of the recent share price movements. It looks as if the share price was well supported at 100p, which might be a coincidence, I don't know:
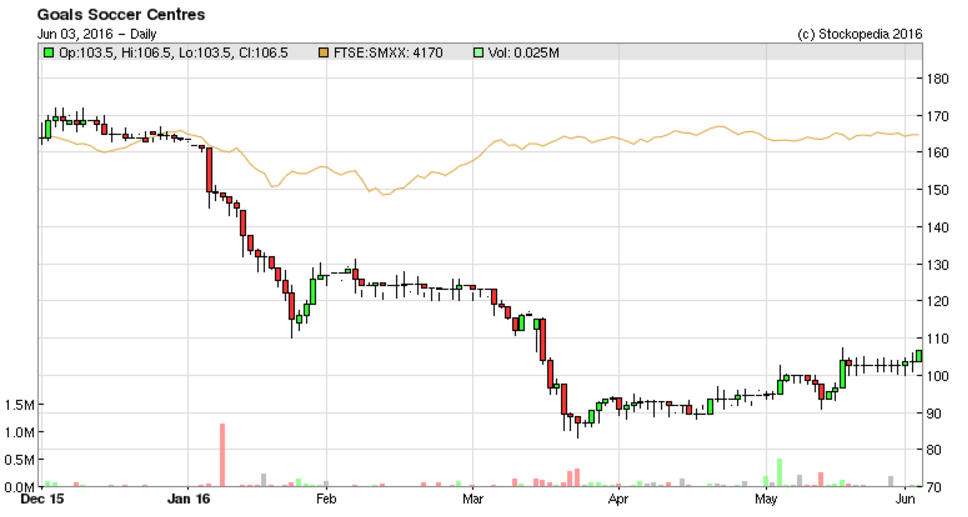
The Placing proceeds are being used for:
The net proceeds of the Placing will be used by the Company to primarily fund the following strategic priorities:
(i) arena modernisation catch-up programme;
(ii) clubhouse refurbishment programme;
(iii) committed US pilot site;
(iv) deleverage the balance sheet.
That all sounds sensible, but it raises questions in my mind. What seems to have happened is that the company has allowed its UK sites to slip into disrepair. So there's a capex backlog.
This calls into question whether the previously reported profits can be seen as entirely genuine, or not? I think a more conservative approach is required - so expensing more costs as P&L maintenance spending, rather than capitalising it.
Also, the question needs to be asked - is this a business which was only able to report profits & positive cashflow by allowing its fixed assets to slip into disrepair? What would profits have been if those assets had been properly maintained & updated?
Current trading - looks similar to the last update:
The Company announced on 5 May 2016 that like-for-like sales for the first 18 weeks of the year were marginally negative compared to minus 12 per cent. like-for-like UK sales growth experienced in H2 2015. The Board can now report that trading for the first 21 weeks is tracking that same improved trend with like-for-like sales marginally negative.
Directors - are putting some (but not a huge amount) money into this Placing, clearly a moderately positive thing:
Certain Directors of the Company have agreed to subscribe for, in aggregate, 165,000 Placing Shares at the Placing Price.
My opinion - I did dabble in this share recently, but changed my mind and sold. It's tempting to go back in, as with such a well-supported Placing, there's clearly good Institutional demand for the shares. With fresh money raised, and a new CEO, and OK-ish current trading, then the newsflow is more likely to be positive than negative, for a while.
So I could see this share having a reasonable run upwards over the next year. It could have maybe 20-50% upside in it, who knows? I'm just not convinced that the basic business model is any good, longer term. The company has mentioned before that competition from local authority funded sites is problematic. Overall then, it looks more a shorter term trade, with potential upside from more positive market sentiment. Rather than a good long-term proposition.
Savills (LON:SVS)
Investment in online hybrid estate agent - Estate agents Savills is not a small cap, with a market cap just over £1bn. However, we've been discussing Purplebricks (LON:PURP) here recently, so this announcement today from conventional estate agent Savills is relevant & interesting.
A group company within Savills is participating in a £16m fundraising by YOPA - which seems a similar proposition to Purple Bricks. There must be something in it, if existing estate agents are backing their own hybrid online estate agents. So maybe I was wrong to dismiss PURP the other day? Although my issue with PURP was more about its valuation, and the marketing budget, than the concept.
Savill's CEO says:
"We have followed the rapid advance of the online 'hybrid' estate agency model over the last year. This investment broadens the Group's access to the UK residential sector by enabling us to take an interest in the high volume segment of the market, comprising over 1 million transactions annually, to which Savills has had little exposure to date.
We have been consistently impressed by YOPA, whose technological edge, dedication to transparency and focus on the client at the heart of the sales process all resonate strongly with our core values and the way we do business."
All of which makes me wonder whether it's time to short shares in some conventional estate agents?
It is, after all, money for old rope. When I last sold a house in 2008, the conventional estate agent I used wanted a fee of something ridiculous, like 1.5% - which would have given them a fee of about £12k! I challenged it, and got them down to 1%, but even then it was a joke. Why is the fee even linked to selling price at all? They did exactly the same work selling an £800k house as they do selling a £200k house.
So this is clearly an area with excessive fees, ripe for disruption. I certainly wouldn't want to be holding shares in any conventional estate agents, that's for sure.
Sea Energy (SEA)
A tearful goodbye to this appallingly badly-managed minnow, which has gone into Administration. The only decent bit of the company, R2S, has been sold to James Fisher and Sons (LON:FSJ) .
Such a pity, as decent management could have really made something of R2S, despite the downturn in oil & gas markets.
Bond International Software (LON:BDI)
Possible cash offer at 105p - from Constellation, its biggest shareholder. This has been on the cards for a long time, with bid rumours surfacing every now and then.
Today's announcement looks much more serious though, with a proper statement from the possible bidder.
All done for today, and the week! Have a super weekend - sounds like some decent weather is finally on the way.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
In Scotland Home Reports are mandatory --and in my view a good idea -- and solicitors, particularly in the provinces, do a lot of estate agency. I was one and we tried a deal whereby clients paid us a marketing fee of AMUNDI SP 500 ETF (LON:500)-750+VAT max [depending on size], but we got paid 10% of the excess on prices greater than 5% over the Home Report value, but it didn't really take off and went back to 1%+VAT.
I'm not a wine drinker, but I think that Chapel Down's Curious Brew Lager is excellent. It's just a little more 'beery' than normal lager, but still lager. Smashing stuff.
No,don't think so.
In Portugal and Spain estate agency fees are much higher 4 or 5% plus VAT and they try and take their fee out of the deposit,rather than when the full price has been paid,also agency fees are much higher in the US.
I eventually managed to sell my flat in Lisbon through a newspaper ad. baulking at the ludicrous fees agents wanted.
No idea how they can get away with it. But they do.
Is that because prices are much lower in Spain?
With regards to Goals Soccer Centres (LON:GOAL) its interesting that, on the day they announce the placing, they also sneak out an RNS about a grant of 1 million shares under their new LTIP scheme at a nominal exercise price of 0.25p. At this point, you're probably assuming this is for their recently appointed CEO but you'd be mistaken. This is for their CHAIRMAN, yes, their CHAIRMAN. That's nearly 2% of the pre-placing shares in issue in one year's grant. Makes you wonder if that's best practice and also what are they likely to grant to their new CEO. I don't think this meets the new ShareSoc guidelines on such matters - see section 2.3 here http://www.sharesoc.org/ShareSoc-Remuneration-Guidelines.pdf and one wonders how much more is to come for the exec team.
Hi Dennism,This was mentioned in their annual report, on the 5th April, which first mentioned the LTIP:
If approved by shareholders, the first grant under the LTIP will be made shortly following the
Annual General Meeting to Mr Nick Basing, the Group’s Executive Chairman, who joined the
Company in November 2015. As explained in the Appendix, Mr Basing’s award (the “NB Award”)
will be granted over a total of 1,000,000 ordinary shares in the Company (“Shares”) and its vesting
will be dependent on the satisfaction of certain stringent performance conditions relating to the growth in the Company’s share price (as measured against an assumed starting price of 100p perShare).
The ' NB Award' is "in the case of the NB Award, it has been decided that its vesting will be subject to a share price growth condition measured over the period up to the third anniversary of its date of grant (the "NB Performance Period")".
The award is then split into two segments which need to be realised before the shares are then awarded to the chairman:
In relation to 400,000 of the Shares over which the NB Award is granted (“Part A”):
Part A - under 50% - 0
50% - 80,000
100% - 400,000
Between 50% and 100% Between 80,000 and 400,000, calculated on a straight-line basis
In relation to 600,000 of the Shares over which the NB Award is granted (“Part B”):
Less than 101% 0
101% 120,000
200% or more 600,000
Between 101% and 200% Between 120,000 and 600,000, calculated on a straight-line basis
Hope that clarifys things.
Hi JamesrWilson, thanks for the information which helps to clarify the background on the Goals Soccer Centres (LON:GOAL) LTIP scheme. I'm relieved to see that they have a cap of 10% on the total shares in the scheme which is in line with ShareSoc guidance but the overall concept of the LTIP and nil cost approach is still questionable and not in line with ShareSoc guidance. Its also not obvious to me why the chairman should receive such a large chunk in one go but i accept it was only recently approved by key shareholders - presumably a few chosen institutions. I note that their new scheme is claimed to be "in line with best and market practice". But LTIP's are coming under increasing criticism and rightly so.
I noticed that convenientional estate agents around where I live are now charging as little as 0.65% for sales. I think that's the only way they can compete - the days of fat 1.5% and 2% commissions are gone forever.
Paul I have often found that buying at around the price of a (good or middling) placing has been very lucrative. Have you any plans on reviving your placingwatch website? Or any other way to automatically identify placings on a daily basis from RNSes? Cheers.
I don't think the estate agent got you an extra 10%, however the market did. All the EA did was showcase your house. Don't believe for one minute they're worth what most people pay them. They're basically glorified auctioneers. A good auctioneer can certainly help but if two people want something they decide the price.
I sold about 10 houses through online estate agency half a percent and house network over the last decade. Half a percent were the first that I can remember who did this sort of thing but have since folded I believe which probably says it all however anything to shake up the ridiculous EA market has to be a good thing.
Having recently dealt with agents after viewing many houses in LB Kingston/Sutton I think estate agents are worth their commission as they know current market values, where as people selling with online portals don't.
I saw two common themes with houses listed on online portals: severely underpriced hence being sold immediately for far less than an agent would have got OR severely overpriced hence not selling at all.
People selling online think they know the market value but they don't. You can't get that info online, only the agents truly know the current market.
Nevertheless good to have competition to reduce EA's fees but overall I think I would still use one when it comes to selling. Also if you're in a chain EA's suffer from massive self interest which works in your favour on the buying side when they want commissions from selling your existing place.
If there's anything EA's need in general it's to behave more professionally and adhere to an ethical code. Currently EA's just pretend to be professionals but there's nothing professional about them.
That's nonsense. Firstly you don't need to know the market price as other estate agents come and value the house also. I get 5 in as well as the independent. So that's 6 valuations. I like to waste EA's time ;-). I already have my valuation also. It doesn't take a rocket scientist to value a house. What most people don't understand is that EA's will value property per sq foot/m. They don't just make it up! London is a different beast to pretty much everywhere else though so prices can shift depending how much someone wants the place!
Properties abroad are all priced this way and its how pretty much all other countries buy and sell property. I don't really understand why we don't realise that's what we do here but we just don't advertise the fact. You only need to know the price per sq f/m in your area to know what the value is. A 2 minute search on rightmove tells you all that info so I've no idea where you are looking.
The same people are coming to look at your house as everyone looks on rightmove and zoopla etc. Don't kid yourself thinking an estate agents adds value to your gaff. He don't. Same as people thinking an investment manager adds value to their portfolio. He don't either.
The market decides the price but nobody likes change do they.
Thank you for mentioning SEA and R2S I knew I had read about them before. Not so good if you were a shareholder in SEA of course but not a bad result for R2S especially if you are a long term holder of Fisher ( James Fisher and Sons (LON:FSJ) ) as am I !
The announcement from FSJ this morning states that many of R2S clients are existing FSJ customers. Fisher has an excellent track record of managing its acquisitions spectacularly well, letting the existing management do their work and providing the support. In the current difficult environment for oil and gas I doubt that R2S could have found a better home?
Fisher shares rarely appear cheap and right at the moment with the setback in the oil and gas sector the shares look well expensive at a forecast P/E of around 21 ! But Fisher has a stable of highly performing specialist technical businesses in the oil&gas, defence, nuclear & renewables sectors and acquisitions they are making now will perform strongly in a couple of years time. I predict some sizeable upgrades in the next couple of years and am holding. Should the share price fall to under £12 I'll consider adding more (it's my largest holding already).
cheers
Mark
Thanks Paul for your Placings overview.
Your musings on such subjects are always very helpful to allow one to take a balanced view on events. For example you point out that Institutions should be allowed a certain discount as their size makes a quick exit more difficult. It is so helpful to understand the logic behind these facts.
Equally, while I’m in a mood for commenting on the workings of this website, there was a very good exchange of views prompted by your Glassdoor reference on 1 June. Julianh questioned that employees of ACSO, on the Glassdoor website, felt that technical decisions by non-tech management were slow to adopt new developments. Apad came back with a view that this was common feedback, particularly on software companies because the techies had to be moderated or aims became unrealistic.
So useful to get these interpretations and thank you for the constructive atmosphere you have created on this website.
While defending estate agents will not make me popular here it is only fair to acknowledge that when I sold a higher price house three years ago the agent made a huge difference. He set the price at a level a fair bit above what people expected to pay (or what I would have accepted). But low enough to still have five serious enquirers. He then managed the buyers offers and counter offers until eventually one paid the asking price. His 1.5% commission got me a price over 10% higher than I would have probably accepted.
But Aislabie - going back to the core argument
That's his job
Hi Aislabie
I don't think the percentage fees are normally much of a motivator for the average estate agent to get a better price for you when selling your home. If you think about it from the point of view of the agent, he or she will make more turning over more properties that they will investing more effort to get an extra, say 10%, on the sale price.
Worked example:
Sale price £100K @ 1.5% = £1.5K but sells the same day.
Sale price £110K @ 1.5% = £1.65K but takes a week to sell.
So would you rather make £1500 in a day, or £1650 in a week?
Is it worth risking a sure-bet £1500 for a risky £150 premium in commission?
I'm sure they'd let the market bid up the price when there are multiple buyers & it's a sellers' market, I'm just saying I don't think they're motivated to work too hard to get that extra few £K on the sale price, the difference in commission is just not worth the hassle.
Cheers, LT
Paul
You're quite right to question why estate agents' commission should be related to value.
So why should so called professionals such as fund managers, tax accountants, anyone in financial services also expect to be paid in the same way?
I thought a professional person was paid to do a job. Anyone expect to pay a dentist dependent on the pain relieved? Or a teacher for succeeding with a difficult child?
We live in a very greedy world.
I think its fair to say that an estate agent does, or should, do pretty much the same work selling a high or low priced home. ie: visits, brochure, office costs. Whereas a financial adviser, tax accountant has more work to do if planning higher net worth ie: different accounts, multiple complex tax returns etc etc.
Fund managers and other services however are a different matter.....I think you can argue percentage fees for some services, where the amount of work involved does rise/ become more complex and others where it doesnt.
Have a try of the Chapel Down Sparkling Rose.Quite tasty and decently priced compared to many champagnes. Not such a fan of their white, or red though.
hTTp://www.marksandspencer.com/chapel-down-english-sparkling-ros-case-of-6/p/p21127606
Sparklers are pretty good, on par with some of the champers imo but then I'm not into the pretentious swilling of Cristal, Dom or Bolly. a Moet or Veuve will do quite nicely.
Hi Paul,
I too have dabbled with Goals and regularly used their centers - it has always looked like an attractive proposition but for whatever reason hasn't been a great investment. Can't really offer an explanation but I'm convinced that my money is better invested elsewhere.
Enjoy your visit to the winery!
Regards, Maddox
Hey Paul - any plans for an investor interview? Always enjoy hearing you talking stocks with other investors.