Small Cap Value Report (3 Mar 2014) - SEE, THT, JSG, NWS

Good morning! Developing events in the Ukraine seem to be increasingly the focus. Personally I think the risk of war involving the West is virtually zero - politicians and the public lack the will to take on Russia in it's back yard. Indeed, we're so dependent on Russia for gas, that it's difficult to see how much leverage can be put on Russia before Putin just flips the switch to turn off the gas, to make a point.
Still, markets hate uncertainty, and risk, so expect volatile times ahead. Personally I won't be making any portfolio adjustments based on this, as I never do. International crises like this are little more than blips on the chart historically, as things always get sorted out one way or another. Although I will be looking for bargain purchases via panic, or forced sellers in stocks that I like.
The question is whether after such a huge bull run in small & mid caps, the market might now use the Ukraine crisis as an excuse to sell off? I think that's a strong possibility, but we'll have to see. At the moment Russia itself is bearing the brunt of the markets' nerves - with the Rouble hitting a record low this morning, and Russian shares down about 10%. Also it has been forced to raise interest rates from 5.5% to 7.0%, I see from scanning my Twitter feed this morning.
Seeing Machines (LON:SEE)
A reader complained that I didn't comment on results from Seeing Machines last week. There's always the option of reading the results yourself! Joking aside though, I didn't report on them as it was a busy day, and there was nothing remarkable in the figures or narrative - everything looked as expected to me.
Seeing Machines is the Australian software company which has developed and is already selling equipment which monitors face and eye movements in vehicle drivers, to identify and alert driver tiredness, thus preventing crashes. It works well, and is being rolled out in the large & expensive vehicles used in the mining sector, via Caterpillar dealers.
So whilst the market cap of about £65m (at 7.6p per share) might raise some eyebrows (since it is a small, and still loss-making company), it is the market leader in a huge, and exciting market. Having proven the product in the rigorous mining sector, SEE should be in pole position to dominate the coaches, trucks, trains, planes, and eventually car markets too. Their product also has exciting potential in consumer electronics, and could become ubiquitous, as e.g. advertisers gain benefit from tracking eye movements, or mobile phones are controlled simply by looking at particular items on the screen.
Anyway, it is now cashed up in the surprisingly large recent fundraising, where a £15m Placing was done, plus a token £1m Open Offer that was considerably over-subscribed. So hopefully that should accelerate progress and keep the news flowing, which is essential for shares that rely on growth to support a high price. This morning brings news of another CAT dealer, WesTrac having signed up to sell Seeing Machine's product.
This is a good quote from the CAT dealer;
WesTrac's Executive GM Jamie Sanders said:
WesTrac is pleased to work, through our alliance with Seeing Machines, to support our customers to improve safety in their operations. Driver fatigue and the associated safety risks are high on our safety agenda and we are happy to be able to provide high ROI solutions which work.
So many blue sky companies have a supposedly great product, but then have a mountain to climb in terms of selling it. What I like about SEE is that the product is proven, already selling, and the hard work (and costs) of selling are done via CAT dealers.
Their shares are not cheap, but if the positive newsflow keeps coming, then investors will keep focussed on the future upside. I remain a holder.
Thorntons (LON:THT)
Bulls have very much been vindicated at Thorntons, both with a strongly rising share price, and good interim results published this morning. The half year reported today is an unusually long 28 weeks (seems odd!) to 11 Jan 2014. This period includes the very busy Christmas period, so constitutes most of the full year profit.
Revenues rose 4.5% to £139.7m, and pre-exceptional profit before tax rose an impressive 47.3% to £7.2m. The strategy behind this improved performance has been to pull out of loss-making shop leases, and concentrate on developing commercial sales. This seems to have worked well, pulling the company out of a highly precarious situation a few years ago.

Although glancing at their Balance Sheet, it's still far from healthy, and shareholders very much have an understanding Bank Manager to thank for this turnaround having been given the time to work. So it's been a very high risk investment that has turned out alright.
EPS is 7.8p for the busy H1 period, so fulll year might be heading for around 10p perhaps? So that looks ahead of broker consensus of around 7.9p for this year (ending 29 Jun 2014). The share price at 153p already factors that in though, at about 15 times forecast-beating 10p EPS for this year.
It's difficult to see how that price is attractive, unless you think further substantial progress in earnings is likely? There's a big pension deficit here too, which has grown to £28.3m on the most recent accounting basis. Looking at note 22 to the 2013 Annual Report, this section concerned the overpayments needed;
In August 2012 and as part of the schedule of contributions agreed with the Trustees to Thorntons’ Pension Scheme, it was agreed that the Company’s annual deficit contribution would increase from 1 June 2012 from £2.2 million to £2.75 million.
It was also agreed that the Company would make an additional contribution over each of the next three financial years, equivalent to the higher of either:• a third of any reduction in the net debt excluding VAT creditors for the financial years ending June 2013, 2014 and 2015; or
• the amount of dividends paid to shareholders above the level of £1.5 million.
...The pension contributions to be paid by the Group during the financial period ending 28 June 2014 are expected to be in the region of £3,188,000.
As you can see from the excerpt below from Thorntons 2013 Annual Report, note 26a, almost 20% of the group's cashflow is being used annually to plug the shortfall in the pension fund (see £3,065k paid into the pension fund, versus £15,469k operating cashflow);
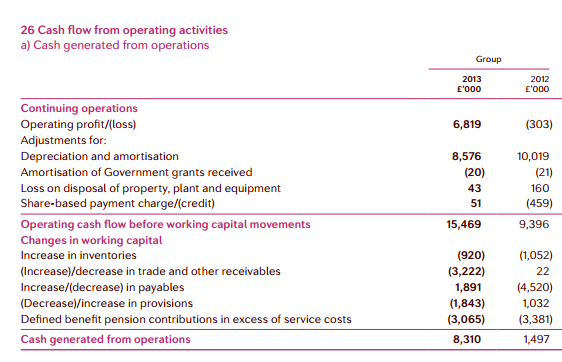
So in my view you would be justified in seeking a 20% discount in share price to take account of the pension fund deficit recovery payments. Hence that takes the underlying PER up from 15 to 18, which strikes me as very warm.
If I were the FD here, I would take advantage of the buoyant share price & recovery story to do a fundraising, and get that Balance Sheet properly sorted out. In my view they need about £20-50m in fresh cash to properly straighten out the weak Balance Sheet.
On a positive note, see how large the depreciation charge is - therefore in a crisis the business could just be run for cash. Although it also raises the question as to what level of capex is needed just to stand still? It looks a fairly capital-intensive business, presumably all the machinery needed to make the chocolates, plus the fittings in the remaining shops.
Very small dividends are forecast for 2014 and 2015, which as noted above is restricted by the pension fund, since payments over £1.5m p.a. trigger additional payments into the pension fund.
It's remarkable how the market is just ignoring these negative factors, and pricing the company as if it were well financed and didn't have a pension deficit. On the other hand, perhaps bulls are offsetting the freehold property assets against the debt and pension deficit? Note 13 to the 2013 Annual Report shows £25.2m in long leasehold and freehold property, which I think relates to their Head Office site? I've tried googling to find information on the value of that property, but am misdirected to residential property in Thornton Heath, near Croydon!
EDIT: Some interesting exchanges on Twitter this morning concerning Thorntons.
@RebelHQ has been a long time bull on the stock, and has been very much proven correct. He points out this morning that there are 80 more store closures in the pipeline, all of which are currently loss-making, so sees 15p EPS being possible for next year. That would put the stock on a PER of 10, which looks a more reasonable valuation.
@equity_research (the Twitter account of commissioned research company, Equity Development), say: "Just back from packed $THT analysts meeting. Co confident re prospects for EASTER. Excellent momentum at FMCG division"
Johnson Service (LON:JSG)
This group is also a successful turnaround, which is starting to look interesting in my view.
Results for the year ended 31 Dec 2013 are out this morning, and look to be slightly ahead of broker consensus of around 3.7p, with 3.8p having been achieved. That 3.8p EPS figure is diluted (good, as that takes into account outstanding share options), but adjusted (potentially bad, if management have stretched the definition of adjusted).
Checking out the small print, the only items adjusted for in 2013 were £0.6m of intangibles amortisation, and £0.6m of exceptional items. That's small enough in the context of £17.0m adjusted operating profit, to be of no concern to me. So having established that I'm happy with the adjusted EPS calculation, how does the valuation stack up?
At 52p current share price, the historic PER for 2013 is 13.7, which looks about right to me.
Debt has been a big problem here before, but was sorted out in 2013 with a disposal, and ended the year with net debt at £24.5m, which looks OK to me. That's about 9.3p per share, or just under 18% of the share price, which seems a reasonable ratio. More importantly, the business generates a lot of cash (£32.3m net operating cashflow in 2013), so the Bank are probably pretty relaxed about things at this level.
Remember to factor in the pension deficit here too, which required £2m over-payments, costs that normally do not go through the P&L.
A quick review of the latest Balance Sheet shows a net current liabilities position (not good) - with current assets of £35.8m being 83% of current liabilities of £42.9m. With a further £46.1m long term liabilities, net tangible assets are too small, at only £15.1m. Personally I like to see a fair bit more Balance Sheet strength, although I'm probably being too conservative on that front.
Also announced today is a Placing at 51p, to raise £12.8m net of expenses. That's an impressive discount of virtually nothing to the current market price, and is about 10% dilution. The company being acquired looks a good fit, being a hotel linen provider. Proforma net debt will rise to £34m at 31 Dec 2013 following the acquisition and Placing, which is not excessive, but certainly at the top end of what looks comfortable, in my opinion.
Given that the company got into problems with excessive debt before, I'm surprised they have not adopted a more conservative approach this time around.
Overall, this company is starting to look interesting to me, so is going on the watch list.
Smiths News (LON:NWS)
This is a distributor of newspapers, magazines, and other products. Their shares are down nearly 13% today to 180p, on publication of a trading update today. The key part says;
As a result underlying Group profit before tax for the first half is expected to be in line with the prior year.
There has been no change in the underlying financial condition of the Group since the year ended 31 August 2013 and the Group continues to operate well within its new bank facilities.
So no change on prior year performance suggests about 21p EPS this year also. Broker consensus seems to have only been for marginally above that anyway, so the sell-off today seems a bit harsh at a first glance.
This share might look attractive for the 5% dividend yield, but in my opinion it shouldn't be paying any dividends at all - because the Balance Sheet is very weak. Reported net assets are negative, to the tune of £56.9m, and once you write off intangibles that worsens to a deficit of £125.1m. That's bad, and makes it uninvestable as far as I'm concerned.
Remarkably, a banking syndicate renewed their facilities, and even increased them, to £200m, maturing in Nov 2018. I can't understand why the banks are so comfortable extending such a large facility to a group this financially weak, although it seems to hinge on EBITDA rather than assets. So that's fine as long as the EBITDA keeps flowing.
Hence my view remains that this looks a potential value trap - shareholders are taking on a lot of risk in return for the 5% yield. There must surely be attrition in its core markets over time, as newspapers & magazines will presumably decline over time as the use of tablets increases? They seem to be offsetting that impact by acquiring companies in other areas.
I've not managed to cover everything today, so apologies for that.
Also, a reminder for Mello Central investor evening, this Weds at FinnCap's offices in London. Click this link for more details & how to book a place via the organiser, David Stredder.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in SEE, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
"So lets just accept that the Russians are on their door step, and have the most influence. Lets trade with them, and do deals, help the people of Ukraine by giving them opportunities without pulling them into the eu or nato, both of which would be a mistake. (because I don't want to finance their bailouts, fight wars over the ukraine, or have 100,000's ukrainians come here looking for work).
K"
Spot on. :)
Re JSG. Paul thanks for your review
The acquisition of Bourne is interesting. From my previous time spent in the industry, Bourne was always regarded as a technically innovative and well run outfit. As you say should fit in well,
JSG on my watch list as well now, was always put off in past by the heavy weight of those loss making dry cleaning outlets.
Yep concur with much of what you say. One hopes though that it's swiftly sorted for all concerned.
The warnings of
"March 3, 5:03 p.m. -- Russian Black Sea Fleet Commander Aleksandr Vitko issued an ultimatum to Ukrainian troops in Crimea on March 3. “If they do not give up by 5 a.m. tomorrow, there will be a real storm of subdivisions and units of Ukraine's military forces all over Crimea,” Interfax news agency quoted him as saying.
Earlier, the Ukrainian Navy was given an ultimatum to give up by 7 p.m. on March 3, otherwise they will be attacked."
certainly wont diffuse the situation. One hopes it doesn't snowball and other countries get involved.
Crimea certainly has a long history of being part of Russia(18th-20th century) prior to becoming part of USSR, then achieving independence in 1990's apparently s part of independent Ukraine. Who can forget the tales as a youngster of the fabled "Charge of the Light Brigade"
The Russians seem to be denying that the Ultimatum was given to the Ukranians.
There is clearly no appetite in the west for any more military adventures, especially against Russian in their back garden. As such, I think we should keep our rhetoric constructive.
I think the Ukraine has been subjected to a tug of war, where the west, particularly the US has been trying to pull them into european/western infulence. I suspect much of the revolution has been financed and planned by western powers, just as it was in libya (remember the SAS men who were captured just before the revolution ?).
So lets just accept that the Russians are on their door step, and have the most influence. Lets trade with them, and do deals, help the people of Ukraine by giving them opportunities without pulling them into the eu or nato, both of which would be a mistake. (because I don't want to finance their bailouts, fight wars over the ukraine, or have 100,000's ukrainians come here looking for work).
K
We need to see this from the other side too, there has been an uprising, and a democratically elected pro russian government has been removed. How would the Americans react if this had happened in Mexico ?
Sums up my opinion succinctly Kenobi. US hasn't a leg to stand on. And both it,and EU should keep their noses out. Elections are due in Ukraine next year - at that point Yanukovych's Govt could be voted out - not as now, via a coup.
US has little in the way of options to force Putin to back down, similar for Europe which is heavily dependent on Russian gas.(Who's smart idea was that?)
Putin, for once, well within his right s with regard to current manoeuvres.
Whatever the rights and wrongs of what is going on in Ukraine, whether you call it a coup, anti-government demonstrations that escalated, or outright civil war, and whatever your sympathies with Russia, to say that Putin has the right to invade another sovereign state is stretching the definition of "right" way beyond what is understood and accepted internationally. Clearly Russia is keen to maintain their influence over their neighbour, and to ensure that the Russian-leaning minority of the Ukrainian population is somehow protected, but it is difficult to believe that the change in regime in Ukraine, however it has been brought about, represents a clear and present threat to the security of Russia such as to justify an invasion.
And yes, I would make exactly the same point if the USA were to invade Mexico.
It doesn't really represent a threat to Russia, but there is a large ethnic Russian population in the country, over 50% in the Crimea, so it's not surprising what they are doing, the US would do exactly the same in its backyard. It's long been accepted, although never officially, that these superpowers have their own sphere of influence which can become very complicated if it also includes an ethnic population of the superpower. The US doesn't even need that excuse as it showed with Grenada and various attempts at Cuba. As usual there is a lot of hypocrisy and sabre rattling type talk which all of these major powers engage in to justify their actions. Been the same throughout history. I suspect that if the Ukraine had been taken over by or was being attacked by an radical Islamist militia the UK and US wouldn't have said a word to any Russian invasion accept don't be too brutal and don't infringe too many human rights. Chechnya springs to mind. So much for that.
Hi Kev,
As far as I am aware Russian troops have only move into the Crimea, not invaded Ukraine proper. And it was to Crimea that the deposed Yanukovych fled - hence Russia moved at the request of the legitimate President of the Ukraine, the man who had been democratically elected, to ensure his safety. Not sure why you think this is invading, illegally, another sovereign state.
As full disclosure I have no sympathies with Russia outside of this one current issue. In case that helps. It's purely a case of self determination and who is the legitimate elected representative of Ukraine - the new incumbents are not. Yanukovych is. And the latter has clearly asked for his Ally, Putin, to back him up and save him from a lynching.
Population demographics are interesting. Countrywide as you say Ukrainians 77%, Russians 17% odd but I gather that the majority of Russians reside in Crimea/East Ukraine, along with Russian sympathising Ukrainians in the East of the country. The Pro Europe leaning Ukrainians reside predominantly in West Ukraine.
"but it is difficult to believe that the change in regime in Ukraine, however it has been brought about, represents a clear and present threat to the security of Russia such as to justify an invasion."
A debateable point I agree. Ultimately, if Yanukovych , as the legitimately elected ruler has asked for Russian assistance then it's a done deal, regardless of whether the West likes it or not and the likes of Kerry haven't a leg to stand on.After all, there are plenty of examples round the world where the US/Britain/France have moved in at the request of the legitimately elected government of the day are there not.
It's certainly an interesting time for investments - Gold up, but some,most notably gold miners are down. FXPO, clearly suffered a bout of knee wobbling.. :)
Hi Oliver
You've made some interesting points, and clearly the situation is not as clear cut as I'd thought. These would appear to be the salient facts:
1. It is true that Crimea is an autonomous republic within Ukraine, but its current state is that of being governed by a representative of the president of Ukraine. I'm no international lawyer — I wish — but I reckon that invading Crimea would be considerd tantamount to invading Ukraine.
2. I take your point that, were Yanukovych considered still to be the legitimate leader of Ukraine, his inviting the Russians in to protect his country could render Putin's actions legitimate.
3. However, his legitimacy at this point in time is at the very least, I would suggest, questionable. Yes, he fled Kiev because of civil unrest, but he was, apparently, then fired by the Ukraine parliament, and disowned by his own party.
My arguments have nothing whatever to do with what the West thinks — particularly America. I am only basing my observations on my scant knowledge of what constitutes international law, which does — as was so often brought up in relation to the invasion of Iraq — generally prohibit invasion of a sovereign state.
As you say, interesting times. And a great opportunity in my opinion to pick up some bargains before everything settles down again.
Ukraine - A good write up from Tom Winnifrith here, with which I agree( and with K above).
http://tomwinnifrith.com/articles/4417/ukraine-my-sympathies-are-almost-entirely-with-putin-russia-not-the-meddlers-of-the-west
The risks with Ukraine is that this starts another cold war, will the US do something daft ? I don't suppose many Americans or Europeans have any appetite for foriegn wars, but like Syria, I'm not sure that the governments feel the same.
We need to see this from the other side too, there has been an uprising, and a democratically elected pro russian government has been removed. How would the Americans react if this had happened in Mexico ?
and then a government took over which wanted to befriend Russia ?
Yes I doubt that the Americans would feel relaxed about that, yet they expect the Russians to just accept it.
What will this do for oil and gas prices ? and what will that do for the world recovery ?
hopefully it will just blow over, it could turn very nasty indeed. I'm glad GWB isn't president.
cheers K
How about Vertu Motors Paul? Should bode well for the likes of Cambria also!