Small Cap Value Report (30 Aug 2016) -BMS, IGR, PRES, SAT

Good morning!
There seems to be a problem this morning with live prices, and news. The usual site many of us use for RNSs doesn't seem to be working. When this problem occasionally arises, I go direct to the London Stock Exchange website, to read RNSs. Although its user interface is pretty lousy.
For alternative sources of live prices, which work nearly all the time, I use a watch list on IG or Spreadex accounts.
By the way, if you want a good laugh, then click here to see a short video of my epic fail on this holiday, trying to jump into a rubber ring in the swimming pool. Apparently it's already going viral on Facebook! You've Been Framed next possibly?! Some serious dieting is needed once I get back to the UK.
Braemar Shipping Services (LON:BMS)
Share price: 370p (down 8.9% today)
No. shares: 30.1m
Market cap: £111.4m
Trading update (profit warning) - a fair bit of detail is given, but the crux is that it's a profit warning;
...while the results for the year ending 28 February 2017 will be materially lower than 2016, the structural management changes and cost reduction measures we have put in place (the costs of which will substantially fall in the first half of the current year) will result in an improvement in business performance.
The market seems to have reacted gently to this profit warning, perhaps because the company says (above) that it's already taken action to improve performance.
The StockReport shows that consensus earnings forecast is currently for a 5.4% rise this year. So the company now saying it will be "materially lower" than last year - materiality is usually 10% or more - means this is quite a significant downturn in profit.
Dividends - the forecast dividend yield is now about 7%. So if the divis are held at 26p, where they have been static for the last 6 years, then this could be a good opportunity to pick up a high yielding share.
The downside risk is that the divis could be cut. In my experience, a static dividend payout for several years is indicative of a company that is struggling to maintain that level of payout, and sooner or later a cut may happen. Or re-basing, as management usually call a cut!
It's crucial to consider the balance sheet strength at high yielding companies, to see what capacity the company has to continue paying generous dividends. In this case, Braemar has a fairly strong balance sheet with net cash, so that's encouraging.
At a guess, I would be inclined to factor in a 50% possibility of the divi being cut by perhaps 20-50%, to be on the safe side, when valuing this share.
My opinion - I don't understand the dynamics of the shipping industry well enough to be able to give a firm view on this. Profits have been quite volatile in the past, and today the company mentions various negative factors in the sector - e.g. over-supply of dry cargo ships, and falling demand for tankers. Also the oil & gas sector doldrums is hurting Braemar's technical division.
To invest in this company, I think one would need to understand the sector well, and be able to anticipate a positive turning point in freight rates, etc.. At that point in time, there could be good upside here, as it looks a fundamentally sound company.
Decent divis are also an attraction, if they are maintained.
Overall then, it might be worth a closer look, although I imagine EPS forecasts for this year will probably be coming down from 33p to perhaps 25-28p. So with the shares at 370p, it doesn't currently look a particular bargain (that's a PER of about 13-15, based on my guesstimate of likely EPS this year).
So it all hinges on whether you think this year's earnings are the low point (in which case the share might be a good buy), or whether there's more bad news to be expected further down the line (in which case the shares are probably best avoided). I don't have any idea which it is, so I'll pass on this one.
IG Design (LON:IGR)
Share price: 236p (down 2.3% today)
No. shares: 62.3m
Market cap: £147.0m
(at the time of writing, I hold a long position in this share)
Trading update - a solid, in line update today from this maker of gift packaging & related products. As it has a 31 Mar year end, today's update is for Q1 of the current year ending 31 Mar 2017.
Key points;
- Q1 trading in line with management & market expectations, both sales & order book.
- "opportunities for incremental growth" in H2 - sounds promising. Presumably they mean in excess of existing forecasts?
- Record order book.
- Growth from increased international geographies - e.g. sales in Mexico have doubled.
- Growth from new products too (e.g. party ware)
- US acquisition (Lang) has "hit the ground running"
Outlook comments sound bullish to me, which makes me wonder whether broker forecasts might be raised as the year progresses. Companies don't usually sound this bullish early in their financial year.
Paul Fineman, Group CEO, commented:
"The Group has made a most encouraging start to the year with our order book at record levels and an excellent blend of sales activity across categories, regions and brands, both with new and existing customers.
"We are also pleased to have 'hit the ground running' with the integration of our new business in the US - Lang Companies Inc. Early indications are positive and we are confident of future growth opportunities. This is particularly pleasing alongside the robust organic growth that we are achieving throughout the Group."
Valuation - this share has risen strongly in recent months, which is reflected in a valuation that probably looks about right for now;
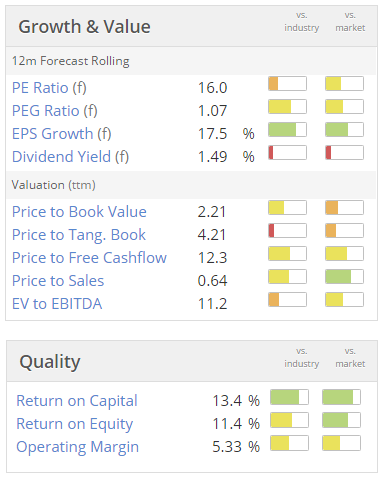
My opinion - this group is clearly on a roll, and I'm sitting tight on the position I hold.
Shares don't rise in a straight line forever, so I think it would be healthy for this one to pause for breath, maybe even drop a bit on profit-taking.
Longer term though, this share very much looks to me as if it's heading up, because the group seems to be firing on all cylinders. Management are highly rated here, by several fund managers and serious private investors that I've spoken to, although have not met them myself.
So in my view, this is a nice long-term share that's probably heading higher, although maybe not immediately.
A couple of quickies now to finish off with:
Pressure Technologies (LON:PRES) - it's another profit warning. Key points;
Some positive developments, e.g. order intake for alternative energy, division - which they expect to be a major profit generator from 2017 onwards.
Overall trading continues to be in line with expectations.
However, a number of factors (contract delays, R&D spending, and a legacy issue) will together have a material impact.
FY result will now be a loss.
Bank covenants will be OK in Oct 2016, but cashflow sounds tight.
My opinion - I'm tempted to nibble here, but the balance sheet is too precarious for my liking - I'm worried about bank debt, and the risk of it having to do a discounted placing.
That said, there seem positive signs for the future, so the market might begin to see the glass half full at some point perhaps?
I think they'll have to pass on the divis for a while, given that bank covenants sound too close for comfort. So I would not rely on there being any dividend yield at all for the next year or two, possibly. This is definitely a situation where I would not hang my hat on the apparently high dividend yield, since it's likely to be cut, or passed altogether in my opinion. I actually think it would be quite reckless of management to continue paying divis in the current circumstances.
At some point though, this share could start to look interesting, so I'm going to keep an eye on it. If they fix their balance sheet, with a fundraising, then I would have the confidence to buy some.
Satellite Solutions Worldwide (LON:SAT) - an interesting company - which is doing a roll-up of fragmented small companies in the satellite broadband space. I like management here. However, the business model is cash hungry. It's not yet profitable, and needs to keep doing equity/debt fundraisings to buy more bolt on businesses. The trouble is also that customer acquisition involves up-front costs, then a long tail of revenues. So again, cash hungry.
It reached EBITDA breakeven in Jul 2016. I think this company will succeed, even though it's still a bit jam tomorrow. The valuation strikes me as a tad too warm, for where it has got to so far.
That's all for today, see you tomorrow!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Shipbrokers, rather like stockbrokers, should make money in good times and bad, as they are facilitating the transactions between shipowners and charterers, or sellers and buyers. However, as commissions are usually a percentage of the value of the deal, then lower charter rates and lower vessel prices inevitably result in lower earnings, unless the volume of transactions increases considerably. From my knowledge of the industry, I would say that the earnings of shipbrokers are certain to fluctuate with a rough correlation to the shipping cycle. Clarksons has grown through acquistion, as has Braemar, but there's a limit to what they can buy, and asset-light shipbroking companies with "portable" talent are really only worth their forward order book plus "alpha" (whatever you decide alpha may be).
B2V
Excellent article again. I think this series is all the better for the editorial freedom.
Cripes .......... Who is that jumping into a rubber ring . Judging by the belly it must be Whinny Froth .
PS. Have lots a Fun!
Wonderful views from your Villa; & it is a lovely quiet resort. With regard to feeding the engine ; I have found that a Low carb High Fat regime really works; I started 18 months ago and slowly and steadily have lost substantial weight. The beauty is you will not feel hungry between meals ( I now have only two per day) and I can still consume with my partner a bottle of nice vino each evening. Won't bore the folks with details, wrong place, but contact if you wish more info.
PP,
Marben has a good handle on BMS - he's been a long term investor(alongside Clarkson). I've always been bearish,given Global trade/Baltic Exchange/freight levels etc...and was surprised they held up so long.
Hi Paul,
Is Dewhurst (LON:DWHT) on your small cap radar?
" full-year profits would be significantly higher than market expectations." Some currency comments too.
Regards David
Paul, I take it that the round floaty thing was not on charter from Braemar Shipping Services (LON:BMS) ? The only shipping company I retain is James Fisher and Sons (LON:FSJ) very specialised, nuclear, submarine rescue. Braemar Shipping Services (LON:BMS) is also technical as well as directly involved in chartering on the consultancy side. But I guess the profits must to some extent depend on the market cost of bulk shipping The forward marker for bulk shipping is the Baltic Dry Index, and there are sub indices for the various speciality fleets but you may need membership for full access. Here is the main index, available openly on Bloomberg:
http://www.bloomberg.com/quote/BDIY:IND
A man, braver than I, might call Feb 2016 a bottom, in which case Braemar Shipping Services (LON:BMS) would be worth a punt, exiting if the BDI falls back to below Feb 2016.
Regards, Seadoc
Re BMS, worth noting that it was one of the most recent stocks highlighted by John Lee in the FT as one of his holdings. I dabbled a bit a few months back - very illiquid - but it was one of the few stocks I ditched after the Referendum result. Thankfully.
If diving into a rubber ring were an Olympic sport.......!
Now I know what doggy paddle looks like. Thanks for that Paul
I see the Daily Mail was reporting a potential takeover bid rumour over the weekend for French Connection (LON:FCCN) - a regular share featured on this column. There were a couple of big share trades on French Connection (LON:FCCN) over the last few weeks.
Looking around The Times had more detail and they say Rutland Partners were considering bidding 40p. I don't think the business would be sold for that. Daily Mail says they were thinking about bidding £400m but those two figures are miles apart!
Video very amusing - judging by the intense preparation and body language you look like someone who has previously had a traumatic experience trying to jump onto an inflatable!
Good video Paul, you nearly made it in!
Very good interview with Gervais Williams on Small Cap Radio today. He doesn't like net importing companies with internal exposure to the UK (e.g. retailers) but does like companies exporting abroad with foreign earnings. He makes a good point that the internal companies will have hedges in place, so the fx impact won't be immediately felt. When the hedging does come off, he reckons profit margins will have to take a hit, as the UK consumer doesn't have capacity to take the price increases.
https://audioboom.com/boos/4969236-the-small-cap-investor-featuring-gervais-williams-of-miton-group.mp3?source=rss&stitched=1
Thanks, I'll have a listen to the Gervais interview later.
Incidentally, Miton has appeared today with a new 5% stake in Cloudcall (LON:CALL) - encouraging news.
There are several high profile fund managers who seem to be getting quite positive about this stock at the moment. I suspect it might be near a turning point? But that could be wishful thinking, as I've held for a long time, and it's been poor so far. Have topped up today at c.59p, following Gervais's lead.
Regards, Paul.
Thanks for covering Braemar Shipping Services (LON:BMS) this am Paul. I've had Braemar Shipping Services (LON:BMS) on the w/list for a while but never bought in and Clarkson (LON:CKN) also issued a PW recently so I thought Braemar Shipping Services (LON:BMS) wouldn't be immune and indeed they've warned on profits.
Do you or any other Stocko members have a definition of what the various PW issued by companies translate into eg. materially lower, significantly, substantially? For example you say materially lower equates to at least 10% or lower which is a pretty wide margin which makes it difficult to value the shares.
Any advice would be greatly appreciated.
Imran.
Hi Imran,
Yes, I agree. The current system of profit warnings is highly unsatisfactory.
In my experience, there's no alternative but to wait for the broker note updates, which will quantify the likely profit reduction. The trouble is that many companies tend to put out vague updates to the market, with no meaningful figures - forcing us to guess what the change in profit might be.
They then brief brokers in far more detail, giving them the likely figures. It's a ridiculous system, and puts investors with limited or no access to broker notes at a serious and unfair disadvantage.
I would like to see regulations changed, to require companies to adopt best practice, of giving specific figures to the market, on likely profit/EPS, when they issue trading updates. This should be in a range, like Next (LON:NXT) does.
Sadly, some brokers are a major impediment to communicating clearly & accurately with the market. Several companies have told me that their broker/NOMAD forbids them to issue any estimated profit/EPS figures to the market. My reply is that they should sack their broker, and find one with a more investor-friendly approach.
Of course companies can issue guidance to the market, and they all absolutely should!
Regards, Paul.
Thanks for the reply Paul - much appreciated. As a PI I don't have access to broker notes so am reliant upon revised EPS estimates being worked through on Stockreports or news articles. I agree Next (LON:NXT) shareholder comms are one of the best in the market and they are transparent and issue forward guidance. Given their size I don't think there's any excuses for other large, mid and small cap companies to follow suit but I'm not holding my breath.