Small Cap Value Report (30 Dec 2016) - PXS, SGI

Morning! Paul is off today, so there's no need to look for a Part 2.
The LSE is closing very soon - at 12.30pm.
It feels very quiet in terms of RNS announcements, as should be expected before the long weekend to ring in 2017.
Provexis (LON:PXS)
Share price: 0.87p (-6%)
No. shares: 1,750m
Market cap: £15m
I don't normally cover early-stage pharmaceuticals - the lack of news this morning has forced me into covering this one!
Half-year Report (for six months to 30 September 2016)
Make of it what you will, but this company has announced results on the very last day before it would have broken exchange rules. Not exactly confidence-inspiring to me!
Provexis develops Fruitflow®, a tomato extract which is scientifically proven to improve blood health.
It has been listed on AIM for 11 years, but revenues remain limited, despite trebling in the current period.
Key highlights
- Total revenue for the period £123k (2015: £41k), a threefold increase from the prior year. Revenue for the half year to September 2016 exceeds revenue for the full year to March 2016.
- Revenue from profit sharing Alliance for the period £88k, a 115% year on year increase (2015: £41k).
(GN note: The "Alliance" is the profit-sharing arrangement by which the company outsources manufacturing, marketing and selling)
- Underlying operating loss* reduced to £128k (2015: £196k), a record low for the Group
There are plenty of encouraging announcements/initiatives included in the statement, but I find it somewhat hard to believe that the company is on the cusp of major financial success, so many years after discovering its technology.
That said, the share price has performed extremely well this year (up about 200%), so investors have clearly been impressed by news flow.
On a bigger-picture view, the number of shares outstanding has increased by about five times over the last ten years, and dilution is set to continue in the short term:
Funding
The Company remains keen to minimise dilution to shareholders and it is focussed on moving into profitability as Fruitflow® revenues increase, but while the Company remains in a loss making position it will need to raise working capital on occasions...
Based
on its current level of cash it is expected that the Group will need to
raise further equity finance in the coming four months. The funding
proceeds which the Company expects to receive will help the Company fund
ongoing promotional activities for its Fruitflow® + Omega-3 dietary
supplement product, to include the further sales channel opportunities
which are currently being explored.
My opinion
If I was involved in a situation like this, where I believed in the company despite the fact that it needed to raise fresh funds, my preference would be to take part in the placings - not to buy in the secondary market.
The problem with the secondary market is that it only indirectly helps the company, by marginally increasing the share price.
The primary market investors are the ones who directly help (or save) the company, and so they are the ones who need to be treated like royalty in the negotiations! So you can get a much better deal that way, rather than buying on the open market.
As for Provexis, I like the sounds made in the announcement today, and will keep an eye on it to check if revenues can maintain their current momentum, but it's just not my style to buy into situations where dilution is on the cards. I also can't shake off the feeling that the company would have succeeded already, if it was going to.
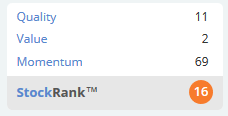
Stockopedia analysis looks consistent with my cautious point of view, as the StockRank is a lowly 16.
I'm having trouble finding anything else worth reporting on today, so unless something crops up, I'll leave it there for now.
Thanks for your comments and feedback this month - they are incredibly valuable to me.
Enjoy your new year celebrations, and I'll see you next week!
Graham
Update: It has been brought to my attention that Stanley Gibbons (LON:SGI) released their interim results at 11.15am. So I am adding a new section below, to cover them.
Stanley Gibbons (LON:SGI)
Share price: 12.4p (+2%)
No. shares: 179m
Market cap: £22m
Interim Results and Notice of EGM
What does it mean to release this at 11.15am on the last day of the year - was it not ready at 7am? Very unsettling!
The figures look as expected: heavy restructuring costs and difficult trading, as the company pulled itself through a difficult reorganisation process.
Note that of the company's current 179 million share count, 130 million shares were issued as part of the fundraising in March this year, at 10p. So as far as I'm concerned, the equity has been re-priced at 10p, and this is now the "par value" of SGI shares.
Results
Undeniably poor:
The performance in the first half of the current year is, as anticipated, slightly down from that seen in the second-half of the year ended 31 March 2016, with turnover for the six months ended 30 September 2016 at £20.2m (2015: £29.4m), down 31% on the comparative period. Trading losses before exceptional items and before pensions related finance charges, as detailed in the Operating Review, were £2.7m.
Outlook
Overall, the tone of the statement is quite positive.
The chairman talks about "giant strides" having been made, a possible "turning point" thanks to reduced operating costs, and signs of recovery/stabilisation in the divisions which were restructured first.
Expectations are kept muted:
The Board expects that following
an exceptionally difficult year for the business, with a marked
downturn in like-for-like revenue, gross margin and trading profits, the Group's revenues will better match its cost base in the second half of the financial year. Profits are likely to remain constrained by our continuing drive to release cash from the balance sheet where the Group is also working on a range of initiatives.
Strategy
The above paragraph must be a reference to the company's attempt to reduce its huge stock of inventory. Elsewhere in the statement, we are told:
A key objective is to reduce our stamp stock which stood at £40.1m at the 30th
September 2016. We have an ambitious marketing plan and are in the
process of initiating a range of sales initiatives aimed at reducing the
historical build-up of stock which had reached unsustainable levels.
The market for premium material remains strong, especially for British
Commonwealth items, but lower quality stock is slower to sell and
usually at reduced prices.
Putting two and two together, it sounds like the company is willing to take a hit on selling prices, if necessary, in order to get the inventory levels down.
Net debt
This sounds like a good plan to me, because the debt levels are still uncomfortably high, with net debt now at £16.5 million.
Debt consists of an £8.3 million loan (repayable in £500k quarterly chunks) plus a £10m revolving credit/overdraft facility.
At the time of the final results, the company said it had headroom of £1.1 million on the bank facility as at the end of September- this would not be enough to make me a comfortable holder of these shares!
Worse, the company is in technical default on these loans, thanks to the qualified audit report, and they are consequently repayable on demand. The bank is said to remain supportive.
Balance sheet
The balance sheet is still very messy, and the NAV reported today of £45 million should not be considered secure.
£19.5 million of the balance sheet is intangible, leaving a tangible book value of £25.5 million.
£59 million is inventories (of which £40 million are the stamps mentioned earlier). At the full year results, stock was written down by £1.4 million - I would be surprised if this is sufficient, and if further write-downs are not later deemed necessary.
The company is also having trouble collecting from debtors, making another £1 million provision, so there are question marks over the receivables figure too.
My opinion
While the company seems to be following the correct strategy of simplifying and liquidating as much as possible, the shares would definitely be far too risky for me. If trading fails to improve, and if it fails to sell off its stocks quickly enough, it could easily need a fresh injection of funds.
One way of looking at it is like this: the fundraising in March/April resulted in an inflow of £12.4 million, but that has done little more than to effectively pay for the company's £11.4 million cash outflow from operations over the past six months. So the fundraising has paid for the company's operating cash outflow, but the creditors still need to paid off.
With ongoing losses, technical debt default, and a liquidation process which is likely to prove testing for the company's stock valuations, I think this should be priced at a very heavy discount to the £26 million tangible NAV. A market cap of £5 - £10 million would make more sense to me.
That's just my opinion. As always, please do your own research!
Regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
For a long time SG have been buying up big stamp collections and creating a market that was not really there . Now its come back to bite them on the arse . The balance sheet is a giant stamp "ponsy" . Tom Winnifrith is a long term supporter though ..........work that one out ?
Concerning yourself with Simon Thompson's pick rate is not an effective use of time.
Even worse, trying to have a dialogue over the ones which didn't work. Ultimately they need to sell magazines & hence portray a positive stock picking record. Just keep that in mind and don't bother challenging it.
Much better to look at the analysis of the company & where it is coherent, consider buying.
I do prefer the style here. Short articles when there is nothing interesting to write about (or if Paul had a few the night before). No pressure to write to fill pages is much better than writing any old rubbish.
Then really high quality analysis.& some very good picks
Yes I agree about ST's reluctance to call a sell and to spin a +ve story when the market says there their isn't one there. I have also noticed that Simon seems to take a lot of note of brokers optimistic forecasts (maybe so he doesn't attract as much personal flack when things go wrong), rather than reporting on particularly attractive (or negative) fundamental metrics that he has uncovered. This is where Paul's commentary comes into its own to help identify (or not) companies with likely positive outcomes.
The 5 IC "Tips of the Week" are little better than random musings. Far better to paddle your own canoe and use the Stocko screening metrics and blog to identify the type of improving companies you prefer to invest in. A very big thanks to the Stocko team and wishing all Stocko readers a very successful 2017. Ian
I recall trying to engage with Simon about one of the more obvious wrong uns and i couldn't get anywhere, which I found disappointing. Some of his stuff is very useful, but some is naive.
I'm relatively new to investing (but not to the financial world) and have learned a lot from my mistakes - but even more from reading the articles by Paul & now Graham. And, especially, from the well written & intelligent comments, initially on Fool, now Stockopedia. I'm very happy with my Stockopedia sub - but would be interested in a level 2 extension, which was mentioned at some point? Another very useful service for PIs are the interviews by Paul, Share Radio & others - and the range of videos produced by my friends Tim & Tamzin.
Just to wish a Happy & Successful New Year to all!
Andy
The problem I found with him is he is reluctant to admit he has made a mistake and even when things are going wrong he is still promoting the positives, I'm sure this has cost investors a lot of money, I did get caught with one of his in the early days, think it was Thalassa Holdings (LON:THAL), you can read his reviews at 300p, 250p, 200p etc down to around 100p. I think his pick rate is not that good but if you exclude foreign companies and oil related it's probably fairly good. If I followed him I would probably have a stop loss at around 20% and I would ignore his reviews on falling shares. You can look at Globo, Stanley Gibbons (LON:SGI), Thalassa Holdings (LON:THAL), Vislink (LON:VLK), IOF reviews if you have an IC account. I can't remember a share where he has advised selling when it has only made a small loss, most of his sells after big hits. It's a pity because he does find some gems such as Ab Dynamics (LON:ABDP) and Burford Capital (LON:BUR) although he does seem to miss most of Paul's winners.
Hi Graham,
Excellent report, many thanks.
I've not looked at Provexis (LON:PXS) before - I agree with your general scepticism. Blue sky shares are usually a dead loss, apart from as speculations in a bull market, when you can catch a nice move up.
Stanley Gibbons (LON:SGI) - I totally agree with your conclusions. I think the balance sheet valuations are highly dubious. Stamp collecting is on its way out - the next generation are not likely to covet old stamps to anything like the sort of valuations that have previously pertained. Stamp collecting actually looks rather daft, in the modern world. What's the point?!
An interesting & well-written report, I enjoyed it. Thank you!
Best wishes, Paul.
Some superb articles,many thanks.
Stanley Gibbons, game over - most of its clientele no longer collecting stamps, and the new generations have scant interest to engage in such. It's therefore relied too much on "massive margins" on selling the rarer stamps to Chinese customers for example...
Dying hobby unfortunately thanks to technology?Xbox/Playstation et al.
Pity - was a great way to enhance ones geography knowledge in the first instance!
Really liked the dissection of Stanley Gibbons (LON:SGI) , I've never been able to understand the buy case here as the elephant in the room is inventory valuations which are incredibly subjective given how slow moving it has been over the years. If a disinterested 3rd party was doing the valuation I'd bet the provision resulting would tip the company into insolvency. As it is the Bank is showing remarkable forbearance imho.
Good luck to holders - my god you're risk tolerant!
Yes but Stanley Gibbons (LON:SGI) was well supported by a certain tipster in Investors Chronicle, I had quite a big argument with him about his reviews, they were all one sided. I longer subscribe to that publication. If you can see his reports then you will see the buy case.
I think when reading that tipster's articles we have to work on the basis that he is just writing down what the company management is telling him and reporting it without adding any judgement or value of his own. His Globo articles would be the best example of that.
I'm a lot happier with the sometimes opinionated debates here, but then I am someone who can enjoy a heated argument with himself before breakfast.
I partly agree but he was just taking the good parts from a trading update or results and hyping them up and not mentioning any of the negatives, I really don't see the point, he does not even own any shares in companies he reports on. I was going to mention Globo, I fell out with a few people on their even got accused of being a shorter. Never did hear from them after it all blew up. I remember his headline "Short sellers in for shock treatment" I just knew what was going to happen.
I agree it's far better on here having debates on shares and much better for my investments. Stockopedia maybe a more expensive subscription but it is well worth it.
Hi,
Are you talking about Simon Thompson at the IC? If so, I think he's a great guy - does some really good reporting, and he covers a lot of ground. He's also a really nice chap - I met him in 2016 at a dinner, and found him a little shy at first, but I soon brought him out of his shell lol!
However, as he admitted himself, he's too trusting. So if a company or adviser tells him something, he believes it, and doesn't seem to stop and think whether things pass the common sense test.
That's a big flaw with UK small caps - where liars & con artists abound, so we have to be sceptical about everything, and I mean EVERYTHING.
I was more than a bit miffed that ST won the "journalist of the year" award for the 4th year on the trot, despite making disastrous & naive calls on Globo & Chinese AIM stocks. That made me realise that the award isn't worth winning!
Regards, Paul.
Hi Paul,
Yes, that's him. I made a point of telling him "I told you so" about both the Chinese AIM and Globo debacles so I'm not saying anything I didn't already say directly to him both in advance of and subsequent to those things blowing up.
His response was that he was entitled to rely on the things that he was told by company management. I prefer your approach even if willingness to speak your mind wins less awards - it's the investment returns that really matter.
Thanks John,
I like ST, so don't want to slag him off.
However, his approach is that of a studious bookworm - poring over the numbers, and believing any old crap that management & PR companies tell him. I'm a bit more street-wise, having actually run businesses & got stuck into major difficulties myself. So I can see through promoters & liars. Dodgy accounts stick out like a sore thumb to me.
The accounts tell the story very clearly - lots of stray debits on the balance sheet, is always a sign of inflated profits & management on the fiddle. Inflated debtors usually, plus excessive & rapidly growing intangible assets.
Daft people ignore all the evidence, and worse still they try to aggressively shout down critics.
I recall here, where I published 29 critical articles about Globo, there was a wobbly point, where bulls in the fraud tried to persuade Ed & Dave to sack me! They stuck to their guns, and backed me, and of course I was correct. We haven't heard from those muppets since.
Best wishes, Paul.
Paul
You get my awards, without hesitation, and I'm sure many others of us.
You, and now latterly Graham, are a significant value-add to Stockopedia and I applaud Ed et al for having such intelligent, experienced (in the real world), honest and insightful writers.
Happy New Year
Howard
Hi Paul,
A lot of material written by financial journalists is simply not worth reading. Also, they frequently have problems with basic numeracy. A classic example is the common use of linear scales on long term stock index graphs, when any fool can see a log scale is required.
The longer IC articles are usually worth reading, but I learn a lot more here.
In the last couple of years, the best material I have seen has been written by yourself. So thank you.
Best regards
Jeff
Jeff, interesting comment about scales in graphs. Personally I've always preferred linear scales - why do you prefer log scales?
Cisco, any long term index graphs of a few decades will, if plotted on a linear scales, look like there has been no performance for decades and huge returns late in the period. Even if performance has been relatively stable. If you had a hypithetical market which doubled every 10 years and plotted returns for a century on a log scale, you would get a straight line, which accurately represents steady returns.
If plotted on a linear scales, the line would be exponential, so you would not get an accurate perspective.
Thanks for both these reports, though I suspect it was more out of duty than interest that you reported on these rubbish shares. HNY and a general thank you for earlier ansd much more valuable reports.
Regardless whether they are rubbish shares, you can still learn alot . I know very soon if i like the company but will carry on reading just for the valuable analysis.
Hi smatthews1. Agree ckmpletely. Read the reports form beginning to end though some I start with Opinion and work backwards. Admit to being biassed towards Provexis. A reco from a friend left me with egg on my face a while back, if you can suffer that fate from investing a small amount in a tomato based company and losing much of it. How a company can keep going achieving so little for is long is justa mazing to me!
Thanks for your excellent reports Graham, and best wishes for 2017.
If Provexis (LON:PXS) is largely reliant on the proven health benefits of the antiocidants in tomatoes, then they ought to be vulnerable to their customers realising that it makes more sense to eat more tomatoes than to buy a dietary supplement. I wouldn't invest here, for that reason.