Small Cap Value Report (30 Jul) - IND, NRR, PUR, ESCH

Good morning. My largest investment, Indigovision (LON:IND) delivered an unpleasant surprise yesterday just as I was nearing London Bridge station on the 12:21 from Hove, for an afternoon and evenings of meetings, so that threw things out of joint for the rest of the day. Their trading update yesterday was delivered two days earlier than the usual year-end date of 31 July, and constituted a mild profits warning.
This is disappointing, but there is no point in being emotional about these things, that just clouds one's judgment. It's always a question of carefully & disapassionately appraising the new information, and making an informed call on how that affects the valuation of the company. Then deciding whether to sell, hold, or buy more.
I'm mindful of the fact that a lot of friends & family have bought this stock, and been heavily influenced by my view on it, so before we get stuck into the numbers, I just want to apologise for it having disappointed. Although as I explain below, my view is that it's far from a disaster, but is just a disappointment.
So what are the key elements of IndigoVision's trading update?
Turnover - expected to be around £32m. Up 6% on last year (£30.3m), and in line with guidance.
Camera sales - showing strong (over 30%) growth against last year, and now account for half of group sales, more than offsetting a fall in traditional encoder sales.
Gross margins - improved in H2 versus H1, as planned. H1 gross margin was 54%, and the target range for margins is 50-60%, with the product mix being the key determinant. Gross margin last full year was 59%, so this year we are probably looking at a slightly lower margin of perhaps 55-58%? Still very good though, especially when you consider there is a further margin added on top of this for the system installer. So the products have considerable pricing power.
Overheads have continued to rise as planned. Strikingly, the sales & pre-sales headcount has been increased by a third.
Product development - increased spending on this. Product range broadened significantly.
Summary (my bolding):
During the current year we have again broadened the core product range significantly and increased the sales and pre-sales headcount by one third. The benefit of this investment in future growth has begun to show through in intelligent camera sales growth, but the transition has impacted the operating result for the year."
So, it is clear that if they had chased short term profitability, then they could have hit the profit target. My understanding is that they were hoping to deliver above target sales, and this would have recouped the investment in the increased sales teams. However, some significant deals have not been closed in time to get into the 2012/13 financial year.
Therefore the trade off is that results for 2012/13 are below forecast, because investment was made to drive growth with considerable product development & investment in the sales teams.
The company is upbeat about the outlook, with a strong sales pipeline, and feel their product strategy has been vindicated, in that they've driven growth from new products (mainly cameras), but the traditional encoders have slipped backwards due to competitive pressure & the fact that Indigo let the grass grow under their feet, and didn't update their product for five years! That has now been fixed, with a new and more competitive range of encoders being launched.
If you look at the Stockopedia graphical history, you can see there is a gently upward trend in revenues, and that the £2m profit for 2012/13 is in the same sort of ballpark as the last 4 years, broadly speaking (the second chart below). EPS looks to be coming in around 25p by my rough estimate, so again that's in the normal long term range, but below forecast of 32.7p.
I'm disappointed they didn't hit the profit target, but in the overall scheme of things, as a long term shareholder, I think it's more important that they've invested in the products, and have beefed up the sales teams for a big push for growth.
That was always the plan, remember this is a 3-year turnaround. Year 1 was to put in place the people & systems. Year two (the year just reported on, y/e 31 Jul 2013) was all about new product, and year three (the new year, ending 31 Jul 2014) is all about growth. Therefore it's now just a question of whether they can execute, and deliver the growth. If they can, the share price is likely to go up strongly, because of the operational gearing with gross margins expected to remain in the 50-60% range, depending on product mix.
If sales disappoint, then you've still got a profitable business paying a decent dividend.
So having gone through the figures, I think there's everything to play for, and the market cap of £23m is attractive, although there's no denying that in the short term the company has disappointed on profits, hence we saw a nasty markdown in price yesterday (on top of earlier falls).
I think the market has corrected the price to match short term performance (i.e. disappointing), but there is good upside from them hopefully executing the growth strategy this year, as planned.
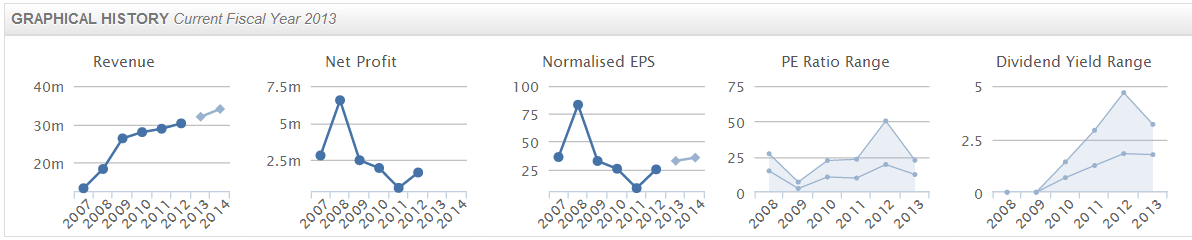
The house broker has issued an update note on IndigoVision, which makes interesting reading, and confirms my thoughts about it. So the forward PER is 10.6, and the forward dividend yield is an attractive 4.2%. The figures for 2012/13 are less attractive, as they under-performed at the last minute unfortunately, so the PER there is 15.9, and the yield 3.6%. That's based on a share price of 307p.
Right, let's look at some other companies. This report is over-running, so I'll carry on writing until about lunchtime. So if you're reading this from the email list link, then you might like to refresh the page to read the rest of it a bit later.
Newriver Retail (LON:NRR) has issued a portfolio update which the market seems to like, with the shares up another 6p to 243p this morning, after a good run of price rises lately. There's masses of detail in this announcement about what they are doing with their various properties, and it confirms my bullish stance on the company.
The discount to NAV has now almost gone, which is entirely sensible. There is also development upside on the NAV to about 300p in due course. Plus long-term capital value appreciation, and a generous dividend yield. So for a long-term portfolio New River strikes me as a good holding to have, and I'm sticking with it. Although there's probably not that much more upside % on the share price in the short term, possibly?
Pure Wafer (LON:PUR) has issued a positive trading update. They are a silicon wafer reclaim service to semiconductor manufacturers. It's an interesting turnaround situation, which I've been looking at for a while, but didn't really understand the business well enough to invest.
Their financial turnaround has been pretty good though. They state today that production is running at record levels. Trading during H2 (they have a 30 Jun year end) is described as strong, but unless I missed it, there doesn't seem to be any reference to how results will be versus expectations. So I'm not quite sure how to value it. If anyone would like to elaborate on it, please feel welcome to do so in the comments section below.
Postal industry software group, Escher Group (LON:ESCH) is an interesting company. They presented at a ShareSoc event a little while ago, and I remember being mightily impressed that this small Irish group had come to dominate the niche of providing software to postal services. The reason I decided not to buy shares, was because it was so difficult to value - because a lot of its revenue was licensing, hence very difficult to predict. They have some recurring revenues too, but my worry was that I'd end up buying after a series of good contract wins, and then see earnings fall back down in subsequent years. That's usually the big risk with software companies, and why the holy grail is getting clients to sign up for annual licence payments on long term contracts, and long term support contacts.
Escher today reports interim (six months to 30 Jun 2013) turnover is up 47% to $12.8m, and that adjusted EBITDA is in line with expectations at $2.4m.
I don't accept EBITDA as being a valid performance measure for software companies, because it ignores their product development costs, which are capitalised and then amortised. So looking at EBITDA ignores those costs altogether, which is clearly nonsense.
Strip out the intangibles from the Balance Sheet, and Escher has net assets of nothing. I'm not keen on this one, as it doesn't actually look very profitable at all, once you include all the cash costs.
I see that Simon Thompson of Investors Chronicle has stuck the boot in with a pretty vicious and badly informed article on Indigovision (LON:IND) published today. He clearly doesn't understand their business model, as he wrongly suggests that they must have known that they were going to miss profit expectations some time ago.
In reality, the lumpy nature of sales at high margins, combined with fixed costs, means that large deals around the year end date will always have a material impact on the full year figures. It's the Achilles Heel of Indigo's business model unfortunately, and shareholders just have to live with the volatility that this causes.
I'm quite shocked that a generally well regarded journalist would publish such an ill-informed piece, that has obviously been written in the heat of the moment whilst emotionally charged. As a friend just quipped, "hell hath no fury like a tipster scorned!"
Pretty poor show - encouraging readers to buy high, and sell low, and not even bothering to find out the facts before publishing a sell note.
OK that's it for today. See you from 8 a.m. tomorrow.
Regards, Paul.
(of the shares mentioned today, Paul has a long position in IND, NRR, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Agreed - looks like ST was right on this one
I personally value Paul’s contribution to this board as his financial analysis fills a gap in my research. My normal starting point for investing is looking for a growth market and then finding good quality companies operating in that market. Paul’s analysis is a very quick and easy way to rule out the cowboys and incompetents. This might sound easy but the AIM market in particular is full of companies that are difficult to analyse and understand. Without someone like Paul this would be a quite a difficult job for me to do by myself.
It’s also important to manage expectations when Paul is positive about a company. As far as I can see Paul is mainly looking for undervalued smaller companies with reasonable prospects for growth. Sometimes when a small company remains small and undervalued for long periods it is telling us that growth isn’t straight forward for some reason. It could well pop up on Paul’s radar and yet never quite manage the performance everyone hoped for. That shouldn’t be a reason to question Paul’s motives
It also has to be remembered that Paul is not making any recommendations but discussing shares from an accountancy perspective. His analysis is purely a starter for further discussion and research. Those of us who use other criteria will inevitably rule out some of Pauls favourites - which is probably what Paul intends when he says DYOR.
Hopefully Paul will continue with his daily Stockopedia posts.
Hi Paul
From someone who has followed you from day 1 on Stocko, your incisive, balanced and 'under the bonnet' analysis is spot on. There is nothing to compare against the cr***y BB elsewhere. This forum is miles better. And there is plenty of room for both your brand of analysis and SImon T's of IC.
Regards, Ram
Hello Paul
You are doing a fantastic job. Please carry on just as you are now. Your analysis and comments are insightful and informative in the extreme. I do not always agree with what you write, but really appreciate the work you are doing and the debates you encourage. I have learned a lot from you and the contributors here (and continue to do so). To NOT follow up on companies you have discussed before would be rather silly, to say the least! Good luck to all.
(For info I am in Vianet (LON:VNET) and Vislink (LON:VLK), but not Indigovision (LON:IND) )
Personally I love the continuity of revisiting old favourites at different prices and points in their evolution , I've never been drawn to Indigovision and missed out as a result but have read pretty much every posting here and in the other place .
Keep up the good work Paul!
Paul,
I admire your honesty - personally I go for lower risks and less rewards but as you say each to their own. My point was that surely this outstanding discussion forum is better served by not getting too wrapped up in a couple of companies that may or may not suit everyone.
Hi bobdouglas,
Thanks for the feedback.
I accept your point - that after 9 years of my posting about IndigoVision, even the greatest stalwarts might be suffering some degree of metal fatigue!
I'm actually quite conscious of that, which is why I don't now mention IND unless there is something specific to say about it, driven by newsflow. So checking the archive here, I have only mentioned it this year on 4 Feb (unexplained share price fall), 8 Mar (Interim results), 14 Mar (brief mention, in advance of my meeting mgt), 15 Mar (brief synopsis of meeting mgt), 2 Apr (contrasted low IND valuation with high competitor valuation, Digital Barriers), 8 Apr (Fund buys back >3% stake), 4 Jul (comment on share price falling), 30 Jul (today's comments on profits warning).
Hmmm ..... OK, point taken! There was a flurry of mentions from me in Mar & Apr 2013 that were arguably gratuitous! Although in my defence, I didn't mention IND at all between 8 Apr and 4 Jul, that's almost 3 months, which demonstrates extraordinary self-restraint!
Trouble is, sometimes on quiet news days, I need to put in a bit of filler about things that have caught my eye, and naturally with this being a Blog/column hybrid, you revert to talking about the stocks you know best, which will be the ones you own.
I've seen some pretty #####y comments on other bulletin boards saying that I've got ulterior motives, and all the usual conspiracy theory BS, and you shake your head in disbelief at some of the shite people write, when the sole intention is to put interesting & informative info out there. Which is free for anyone to read without even a registration, thanks to Stockopedia giving me a home here & paying me a modest fee to write my reports every day, which is why I now spend 4 hours+ on them every day, instead of 1-2 hours when I did them free.
Of course I talk my own book, because those are the shares that (rightly or wrongly) I'm most enthusiastic about! Of course it is always disclosed in every single article, at the end, whether I have a position or not.
People who follow my ideas have a nice set of well-researched ideas to take their pick from & develop as they see fit, especially if they are time poor and welcome somebody doing the hard grind for them & sifting through the market to at least try to sort the wheat from the chaff.
Contrast my ideas with some of the junk you read in the financial press - which is just cut & pasted from emails sent to them by the financial PR companies, given no meaningful analysis by journalists who are often hopelessly ill-trained or skilled to be interpreting the info, and don't have time to do so anyway, but some of whom are excellent (I can think of a couple from Shares who are superb - e.g. Dan & James at Shares mag, who are always Tweeting interesting stuff & like me enjoy sharing info & helping us all come to better decisions), then you read bile-filled tripe like Simon Thompson published today on IND, and you despair. He just needed to pick up the phone and find out the facts.
But I do accept that I need to focus on being more objective, and trying to give both sides of the argument. I do try, but when you are genuinely excited about the upside on a share, and believe the upside is more exciting than the downside, then you can sometimes just gloss over the downside risks, without actually meaning to.
Anyway, thanks for pulling me up on this issue, I've listened, had a think about it, and you're right that I should try to make it a bit more objective, and lose some of the passion for stocks that I like the best.
As regards Vianet, I've only been in that one since Oct 2012, so at less than a year, and with a lot of very important issues bubbling away with that one, I think it should remain at the top of the news agenda.
Also bear in mind that myself & Dave Stredder of ShareSoc did a helluva lot of work behind the scenes to coax Vianet management into engaging with the private investor community, culminating in an excellent 2-hour Q&A with the Chairman and about 30 investors at the last Mello Beckenham meeting. To our minds, it's all about building bridges with small caps and the private investor community. Dave is an amazing man at this, indeed I would say he has single-handedly changed the face of small cap investing in the UK, bringing dozens of companies together with thousands of investors, and constantly liaising with brokers, financial PR companies, etc behind the scenes to get our interests taken into account too. I'm totally supportive of that stuff too, and reckon that these reports are becoming a great way for companies to disseminate information to a wider audience - e.g. I try to get up to London once or twice a week for company meetings, and take detailed notes & refer back to that in my morning reports here, so hopefully that benefits everyone too. Beginning to ramble now, but you get the gist.
Above all, I will always tell it how I see it. That surely jumps out of the page every morning? If something doesn't float my boat, I'll say so. If it does, I'll say so. All with reasoned explanations, which may not be right all the time, but it's my best judgment at the time.
Cheers, Paul.
Hi bobdouglas,
In fairness, most days I cover 5-10 companies, and typically only usually hold 1-2 of them in my personal portfolio, and will usually mention them first, as I know them best.
So I think overall this year to date, I've covered most companies in my area - i.e. £10-200m market cap, excluding a couple of sectors (e.g. resources, financials, and a couple of other niches). I've not counted it, but we must be looking at getting on for 500 companies. That's quite a lot for one person to cover! So I don't think it's fair to say that my reports have;
got too wrapped up in a couple of companies that may or may not suit everyone.
It's difficult to think how I could cover any more companies than I do. Ideally I'd like to have a small team of analysts, who can each take a basket of companies, and drill into them in more detail, say 100 companies each. Then have everyone cross-posting on each other's reports, and challenging their colleague's ideas, along with readers doing the same. When resources permit, who knows?
Cheers, Paul.
P.S. I've also tweaked the formatting so that you can quickly skip from one section to another, based on the company name which Stockopedia highlights in blue & bold. So if you don't like a particular company in my report, then just move on to the next section. That's why I set it out like that, to make it as easy as possible for readers to select what they find most interesting & hence save your time.
Is there a time when talking about companies that are involved in beer flow monitoring or security cameras becomes non-constructive? I understand the sensitivity if you are invested in these shares but there comes a point when surely it is a time to move on.
Hi bobdouglas,
If I thought that risk/reward had become unfavourable, then I would sell. Simple as that.
That's why when the bad news broke on VNET, I sold some, as reported here, as risk/reward had deteriorated. Then when I'd done enough research to be comfortable with risk/reward at the lower price, I bought back at 72p.
With IND I sold a lot of shares at exactly £10 in 2007, because it looked fully priced, and the Chairman had sold a big chunk.
Today, for the reasons explained, I want to see the results of year 3 of Marcus's 3 year turnaround plan, so if nothing has changed in a year, then I will exit IndigoVision, but that depends on the price at the time. It's just all about assessing risk/reward, and deciding whether on balance it's best to buy, hold, or sell. I'm more patient than most, and go into most things with the intention of giving it 2 years to perform.
In my view, there could well be an opportunity to exit IND at 700-1000p within 12 months, and the downside is probably nothing, because even if it performs badly it could be sold in a trade sale for more than the current mkt cap. So IMO risk/reward is currently excellent. I couldn't care less what investor sentiment happens to be like, that is irrelevant to me.
Everyone has their own way of looking at things, this is just mine, which is sometimes right & sometimes wrong!
Cheers, Paul.
Simon Thompson of Investors Chronicle has published a scathing review of Indigovision (LON:IND) today, with a sell recommendation (having recommended buying a couple of months ago).
http://www.investorschronicle.co.uk/2013/07/30/comment/simon-thompson/indigovision-shares-slump-on-warning-mtTT4wIDVprG7CFt6DuftK/article.html
"...I have a major problem with the reporting of Indigovision. The company has just issued a trading statement two days before its financial year-end in which the board has stated that the company has been trading massively below analysts' earnings expectations. Revenues are close to those expected by analysts at brokerage N+1 Singer (£32m versus the broker's estimates of £32.4m), but pre-tax profits of £2m have missed their forecasts of £3.4m by a country mile. They have even missed the company's prior year reported pre-tax profit of £2.3m.
This all begs a question as to when the board became aware that profits would miss consensus estimates? Was it really on Monday 29 July when the company issued a profit warning, only two days before the financial year-end? Are the management controls in place that poor that the directors didn't notice their company was operating a massive £1.4m of profit shy of analysts' estimates for the 12-month period? There can be no argument at all that Indigovison has missed market estimates by a significant margin. In which case, I would request that the directors of the company issue a RNS to the London Stock Exchange immediately stating clearly when they became aware that the company was trading materially below profit estimates for the financial year to end-July 2013. I await an announcement with bated breath, but am not hopeful. Perhaps the Financial Conduct Authority would like to look into the timing of this warning and whether the directors should have issued a statement to the market earlier?..."
In talking about trading he is highly sceptical the revised 2014 estimates can be met and refers to the materially worse cash generation than previously forecast.
I have a great deal of respect for Paul Scott but I find myself much more in line with Simon Thompson's thinking. Indigovision (LON:IND) massively missed forecasts, 2014 has also been materially downgraded, management credibility has been damaged and the current rating, a fwd PE of 14, is unattractive when compared to other small cap opportunities.
Hi Paul,
I have to agree with Simon Thompson on the Indigovision (LON:IND) situation actually. I appreciate that the nature of the company's business means that sales are lumpy, however even if they had received a big order in the last few days it wouldn't have affected profit for the current year, since most/all of that order would have had to be accounted for as deferred income (ie. fall into next year's accounting result).
I agree with Simon Thompson that it's simply not possible for a company to realise it's missed it's profit forecast by over a third, and then only notify the market two days before year-end. If the Directors have that little control over the finances and management accounts of the business, my personal stance is that new management are required.
Hi fek47,
I've made enquiries, and the company expected to meet profit targets until very recently.
So there is no issue about the timing of informing the market. The IC article is simply wrong.
They don't book sales to deferred income, orders are shipped from stock, so you book the profit in full on the date of shipping to the customer. So if you have a (say) £1m deal that is ready to be signed, on 55% gross margin that would be an instant £550k boost to profit for the full year, when that order is shipped. Turnover is on average just under £3m per month, so it would only need 2 such deals in July to slip into August, and you have a £1.1m hole in your whole year forecast.
The IC article wrongly assumes (why didn't they just ask the company?!) that sales were running behind schdule, and IND failed to inform the market. That simply isn't true. They expected to beat forecast turnover, and roughly match profits. Then some big orders slipped past the year-end date, and you've got a big hole in the year's results.
However, bear in mind that this should mean we have a bumper Q1, so the proof of the pudding will be in the outlook statement issued with the year end results in about 6 weeks.
I've done my research on this, and found out the facts, so my version of events is actually much more accurate than Simon Thompson's!
Regards, Paul.
Paul / CantEatValue
Thanks both for your replies to my post. I can see merit to both sides: Paul, OK perhaps this slip-up can be excused on the basis of just a handful of orders falling the wrong side of year-end. On the other hand, I completely agree with CEV as to why haven't next year's forecasts been consequently upgraded if this is the explanation?
Overall, coming down on one side of the fence, my gut feeling is that Indigovision (LON:IND) is another 'jam tomorrow' company. I might retain a small holding, but frankly I'd rather invest in one of any number of jam-right-now companies than wait to see if IND can actually deliver on their promises....
Hi fek47,
Interesting discussion, and I accept that just like IND's order book, some investors will be one side of the line & lean more towards the upside potential, whilst others will walk away from what some might regard from a distance as being a serial disappointer.
From my point of view, I engaged with the new management two years ago, and have been very impressed with the turnaround plan, and how it's been executed. So they are all set up now for a big push on sales, which is exactly what they said was the plan for year 3, once they had fixed all the other issues & developed new products, which is what they've done.
They could have just run the business for short term cash, and delivered much better bottom line figures (e.g. try stripping out all the development costs, hardly any of which is capitalised, and the costs of the beefed up sales team, and you've got a very profitable underlying business).
But it's all about investing some of the cashflows back into the growth drivers - namely product innovation & building up the sales team.
There are no guarantees it will work, it's all about execution now, and we'll have to wait to see how it pans out.
Why were 2013/14 forecasts not upgraded? Because they never are! Brokers don't ever upgrade next year results, if downgrading the current year, for any reason. It just doesn't happen!
The jump from 2012/13 to 2013/14 forecasts is quite a big jump, normally the house broker only pencils in a slight improvement from one year to the next. So they have in effect built in an uplift for slippage from one year to the next, and I was reassured that they didn't downgrade 2013/14 more. After undershooting forecasts, everyone tends to be more conservative, it's just human nature.
It's important to keep focussed on the valuation. At 300p we're only valuing it at £23m. That's not much for a global technology company which is profitable, cash generative, and which has geared up for a big push on sales growth. So I think the current price is far from demanding, but that's probably sensible because the market wants to see improved figures in the bag before re-rating it.
Cheers, Paul.
re Indigovision (LON:IND) - no bumper Q1, running in line with last year. Results & outlook justfying Simon Thompson's sell call IMO.
Note: "The benefits of the substantial increase in headcount in the sales team made in the second half of last year are not currently expected to show through in revenues until the latter part of 2014" - the turnaround is taking longer than forecast.
Declining margins, static revenues, poor cash generation, increasing competition and no improvement forecast for over 12 months.
This was exactly my thoughts when I read that excuse. Surely they can't book the revenue that quickly anyway, it'd take time to actually fulfil the orders (surely at least a few weeks)? Also, if this is really a timing issue and the underlying growth (the now infamous 20% market growth comes to mind here) is still on track, surely FY14 forecasts should actually be upgraded as large, missed orders get pulled in to the next year?
IND are cheap if you believe the growth is likely to happen and expensive if you think they will only muddle through as has happened previously. I've no idea which one will happen so they look about fairly priced to me. I'd buy in if the market clearly gave up on IND and priced in a very low probability of execution but I don't think that's happened yet. A ~13% price fall for a ~40% profit miss says this is probably just a bump in the road, which I hope it is.
That being said I applaud the decision to invest in their sales team (which was clearly a problem before) and R&D at the cost of near-term earnings, although perhaps it would have been wiser to guide for one year's worth of reduced earnings regardless given the increased overheads and the fact such investments will inevitably take longer to come through than hoped for.
EDIT: Apologies, didn't see Paul's reply to fek which addresses my first paragraph before I posted. I agree that the outlook statement is absolutely critical here - any sign that these orders haven't arrived by then would be damning.
Ref. Escher - adjusted EBITA at US$2.4M and funnily enough Net debt increased by US$2.4M.
I hold Synetics (SNX) which to me seems rather better value than IND. The CEO picked up a few more after the recent good interims which seemed mildly positive for the longer term as well.
Hi Paul,
Like you, a long-term (but smaller scale)holder......and share the psychological burden of having several family members also involved.
FWLIW, I also share your views re prospects, so will continue (other things being equal) to hold.
One thing that grates with me - and I suspect others - is unfortunate management-speak.
The last two disappointing statements to the market have included the phrase ' As anticipated,....' when clearly (from the reaction) the news released was NOT anticipated by the market which, given the paucity of newsflow, means the brokers/analysts.
IND management would be well served IMHO to give brokers/analysts a better 'steer' on what to expect.
ATB
If Intelligent cameras are the reason for lower margins - is selling more as a percentage of turnover not going to decrease the margin further?
Of course, but the real problem here is the fall in sales of the core products. They are not choosing to sell more cameras at the expense of encoders, they are trying to sell the high margin units but are struggling to. The high sales in these lower margin cameras is helping but not enough. Hopefully the new encoders and core products can win back more business.
cheers K
Hi Kenobi,
Their problem with the traditional encoders is that IndigoVision let the grass grow under their feet, and didn't significantly change them for about five years. The competition produced cheaper encoders, that forced down prices and chipped away at IND's position.
IND recognised this & broadened the product range into cameras & other products, which has more than taken up the slack. Also, they now have a new range of encoders, so that makes them competitive again in the area that has been a headwind on growth in the last 3 yeas.
IND also have a strong market position in terms of their software, in particular how it can integrate with other systems (such as barrier controls, perimeter fences, etc).
Therefore the investing case here is now very simple indeed. Marcus has put right the issues on people, processes, and product in the last 2 years. It's now all about execution on a more aggressive sales strategy. They've had to invest up-front in a one-third larger salesforce, and if they execute well, then we should see the operationally geared benefit flow through in the new financial year starting in 2 days' time.
Also, success will feed success, in that sales growth will give them more firepower to deploy more salespeople again, and so on. So if they get it right, this could (finally!) be the upside that we've waited so long for.
Time will tell. I'm not blinkered about this, or in love with the stock. It stacks up for me on risk/reward at a £23m market cap. Others may take a more jaundiced view, given the patchy track record, which is an equally valid point of view. You pays your money... and all that!
Cheers, Paul.
New broker note from Indigovision (LON:IND) website: http://www.indigovision.com/documents/public/investors/2013-July-30+N+1_Singer.pdf
Pbt forecast £3m on revenue of £36.2m for next financial year.
"Sales for the year to 31st July 2013 are expected to be around GBP32m, ahead of the previous year and in line with market estimates. Following extensive improvements to the product range in the last two years, intelligent camera sales are expected to be up over 30% year on year, more than offsetting reductions in traditional encoder sales. Intelligent cameras are expected to account for half of group revenues in the year to 31st July 2013.
As anticipated at the interim stage, gross margins improved during the second half, but remain lower than last year overall reflecting the changing product mix of sales towards intelligent cameras"
I might be reading this wrongly, but to me it says the reason for the lower margins is "reflecting the changing product mix of sales towards intelligent cameras" however they say that "Intelligent cameras are expected to account for half of group revenues in the year to 31st July 2013." If Intelligent cameras are the reason for lower margins - is selling more as a percentage of turnover not going to decrease the margin further?
Back to the coffee
Dear Paul,
Thanks for your views on the IND trading update. As you say disappointing, but hopefully the share price will not fall any further. Lets hope that the coming year adds value. I do wonder now about the special dividend paid out last year to share holders, maybe some of that could have been put to better use updating the product?
Regards
M51
Good Morning Paul,
I have been reading NewRiver Retail portfolio update this morning - impressive stuff ! It appears to me this company certainly doesn't mess about - says what it is going to do and gets on and does it.
Cheers Bob