Small Cap Value Report (30 Jun 2014) - GTC, PTCM, ZTF, PLA

Good morning! Friday's SCVR wasn't one of my best, so feeling a little guilty, I set aside a couple of hours to write a bonus article over the weekend - namely Part 2 of my series of articles reporting on the London Value Investor Conference in May 2014. So here it is - an article covering a speech from Charles Heenan of Kennox.
I've also set up a dedicated website for my Brighton investor group, following last week's successful evening, so anyone interested might like to peruse & bookmark the link. Good old WordPress - it makes setting up new websites such a pleasure, and it's remarkably easy too.
I don't know where to start with this morning's announcements, there are loads of them, so it's going to be a busy morning! The Aldi Colombian is kicking in (coffee!!), so let's crack on!
Getech (LON:GTC)
This is an odd situation - the company warned on profits a couple of times, most recently on 10 Jun 2014. However the very next day, it announced a major $2m contract win, together with an indication that further contract wins were in the pipeline.
Management credibility is returning rapidly in my view, as today they have announced a further $600k contract win, all of which is being recognised in the current financial year (ending 31 Jul 2014). So I am coming round to the view that this company is fundamentally sound, but that they just have an inherently lumpy sales profile (small company, but large contracts with uncertain timing). There's nothing they can do about that, so shareholders will just have to either get used to volatility in the newsflow, and hence share price, or sell up and move on.
I like buying sound companies after a series of temporary disappointments, as especially in a generally rather pricey market, that can be the best way to get bargains. The difficulty is sorting out good companies with temporary problems, from bad companies that are in decline.
These shares look potentially good value in my opinion, although we won't really have the full picture until results for the year ending 31 Jul 2014 are released. I hope the company improves on the 3-months it took to report the figures last time. I note that they issued "Final Results" last year on 29 Oct 2013, which presumably means they have been audited. Personally I would much rather see preliminary results (pre-audit) much sooner after the year end (4-6 weeks should be do-able for a small company). The faster the reporting, the better the financial controls, so this is an important issue.
Director Buys
When should Director buys be taken notice of, and when shouldn't they? This is partly an art, as well as a science. Personally I try to look for the motive behind the purchase. If it's a co-ordinated set of buys by several Directors, especially over multiple days, then it's usually being done for PR reasons, to prop up a falling share price. Especially if those buys are small in relation to the Directors' salary/wealth/existing shareholding, then such buying can actually be a bearish signal, particularly where a company has a reputation for over-promoting its own share price.
The best type of Director buys are where a Director of a small company spends a 6-figure sum on buying shares, and it's a meaningful amount of money relative to their overall personal wealth, which 6-figures will nearly always be for smaller companies.
Such buys carry even more weight when a company is not prone to promoting its share price.
The other key factor to consider is how shrewd the Director making the purchases is. If the Director is a flamboyant type, then their purchases will usually be done for the wrong reasons - to prop up the share price. However, if the Director concerned is a hard-headed, often dour entrepreneur, with a reputation for getting things right, then a large purchase of shares by them is one of the best bull signals you can get.
Porta Communications (LON:PTCM)
The reason I mention the above, is because I'm trying to decide what signal should be drawn from the significant Director buying at Porta Comms this morning. It's a small, but rapidly growing PR group, headed up by very experienced management.
It's been announced that the CEO, David Wright, has spent £30k buying shares at 11p, and the shrewd Bob Morton (Chairman) has spent £105k buying shares at a keener price of 10.5p.
That equates to the CEO increasing his shareholding by 11%, and the Chairman increasing his by 3.1%, and certainly in the case of Morton, he's a very wealthy man, so this purchase is not hugely significant in terms of their overall wealth.
That said, it's a £6-figure vote of confidence, in a £25m market cap company (at Fri night's closing price of 10.75p), from shrewd Directors, so it gets a firm thumbs up from me. The market has also given it a thumbs up, with the shares up to 11.5p this morning.
Despite my critical comments about this company's presentation of its numbers a few days ago, I still think it looks a very interesting growth company that could be a good slow-burner in my portfolio. So it's one where I am anticipating waiting perhaps 1-2 years for a possibly quite large re-rating, if management execute well.
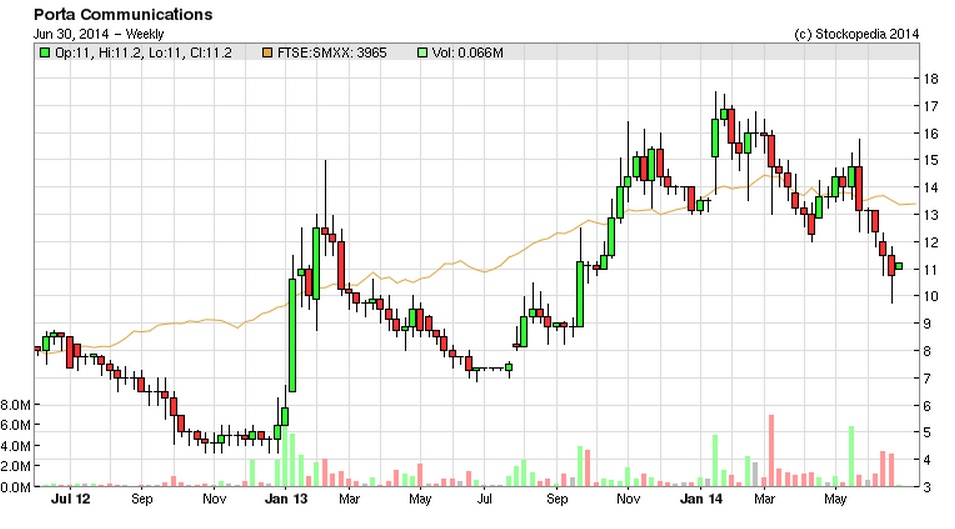
It's a volatile share, which tends to move up & down in waves, as you can see from the two year chart below. From a chart perspective, this clearly looks a good time to buy, assuming that the same sort of patterns continue. You have to remember that the chart only measures investor sentiment in the short term. It's the fundamentals that will determine the long term price. That's why so many shares move in unison, as investor sentiment goes across the whole market. People think they've found a brilliant share because it shoots up in a bull market, but more often than not they've just caught a rising tide that is lifting all boats.
It's how the fundamentals play out in the long run that will sort the winners from the losers. So that means cashflow, dividends, and sustainable growth, which are all that matter once the speculative froth has been blown away.
Zotefoams (LON:ZTF)
My last comments on this company were on 19 May, where I thought it looks a good company, but expensive at 272p per share (a PER of 22 at the time). The shares have come off nearly 14% (similar to the decline in small cap indices in the last few months) since then to 235p.
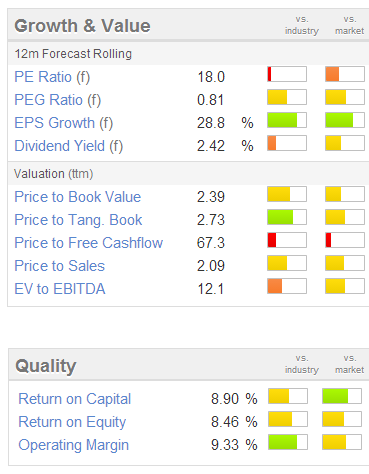
As you can see from the usual Stockopedia valuation graphics, Zotefoams shares are not cheap.
The earnings growth is high at 28.8%, but that represents mostly a bounce back from a poor year last year.
A trading update today details performance in its various divisions, which sound encouraging.
A £1.2m exceptional charge is being taken for writing off fixed assets on a production line that is being turned into a development line. That's non-cash, so not an issue.
Foreign currency movements have made raw materials costs lower, but impacted on selling prices to a larger extent.
Overall though the conclusion sounds like they are probably trading at or near to market expectations, with this comment;
Overall the Board remains confident of a satisfactory outcome for the year and continued progress in the future.
I don't know enough about the company, its products & markets to be able to predict how it might perform in future. Although at this price, I'd say that holders must presumably be expecting it to out-perform against broker forecasts.
The growth potential seems to be coming from new products, so that is probably the area to focus on when researching this company.
Plastics Capital (LON:PLA)
I've skimmed over the accounts published this morning by Plastics Capital, for the year ended 31 Mar 2014.
To my mind the valuation all hinges on whether you're prepared to accept their adjustments to EPS or not. There's a big difference between basic EPS at just 3.2p, and adjusted EPS at 11.1p.
In my view the 11.1p adjusted EPS figure has been heavily buffed up, to look as shiny as possible. It's fine to strip out the amortisation of goodwill. Looking at note 3 to today's accounts, the exceptional costs of £840k relating to acquisition & legal fees seems very high. Also £242k this year, and £210k last year of costs are within exceptionals and called "Redundancy/recruitment costs" - which are a normal part of running a business, so personally I would add these back. "Company set up costs" of £160k this year, and £64k are more costs treated as exceptional - but again, it's difficult to call something exceptional if it happened last year and this year!
A further £260k of bank refinancing costs are treated as exceptional, but I would regard as normal. It's the write off of previously incurred but capitalised bank arrangement fees. That's not exceptional in my view.
Net debt reduced a little to £7.2m (from £8.4m), but bear in mind that £2.7m of fresh equity was raised during the year to fund a small acquisition. The narrative states they want to do more acquisitions, so that will almost certainly involve the issue of more equity. Therefore I am sure management will be keen to keep the share price up, so that dilution is kept to a minimum!
They have proved adept at making good acquisitions in the past, and providing new equity is not issued at too deep a discount in Placings, then things might be OK.
Capex was heavy in the last year too at £1.9m, although that should support future growth.
The dividend has been raised a very generous 50%, to 3.0p, so the yield is starting to get into reasonable territory.
The outlook sounds reasonable;
Trading for the first quarter of FY2015 continues in line with management's expectations and there are indications that trading conditions will improve over the coming months. The pipeline of new business remains strong and converting them into sales during the year is a major priority. We believe existing business will at least continue at similar levels to FY2014 and we will continue to develop our activities in China, to make the most out of the recent investment there.
Overall, I quite like this company, but think the shares are probably priced about right, or slightly on the warm side perhaps at 134p. The PER may look lowish, but once you adjust for net debt and pare back some of the exceptionals, it's not really cheap after all. Growth looks fairly lacklustre at the moment too, so I can't see a good reason to chase these shares up to a higher valuation.
That's all for today. Thank you for reading, and as always your comments in the comments below are very welcome. If you think I've got something wrong, or missed some important detail, then do please flag it up.
See you tomorrow.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in GTC and PTCM, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Had a look at PTCM to see why people are a bit suspicious and its Altman-Z score suggests it is likely to go bankrupt and the Beneish–M score suggests they maybe lying, so hardly a super safe Paul Scott share. Hardly cheap in the first place and went up like a rocket!
Seeing results come out this evening for Eco City Vehicles (LON:ECV) you'd be forgiven for thinking these are for a year-end of 31-Mar - but no, these are for the year to 31-Dec meaning ECV has taken the full 6 months permissible to issue results before the shares would have needed to be suspended tomorrow. In almost all circumstances, I would not trust any company that could not issue its (relatively simple) results within 3/4 months - to take six is unforgiveable and is normally covering something up and delaying its release.
In this instance the results tell the tale of static sales (known I would expect), with net debt increasing from £1m to £3.6m, attributable to the purchase of a rental fleet. I've not heard mention of a rental fleet previously, having not followed closely as I've not held for almost a year, but does this activity provide decent margins or is it intended to support the used fleet prices? It's a good job the £2.2m VAT windfall was received else the position would have been worse.
The need for additional funding is also mentioned which will weigh heavily on sentiment until it is completed at a hefty discount. Working capital is just £704k for 2013 so can the company support its expansion plans ahead of the fund raising?
For me, ECV remains uninvestable whilst it faces so many headwinds. I'll continue watching but suspect it may be some time before a tangible recovery is seen.
Hi Paul, long time reader; first time poster on your fantastic blog.
Just wondered if you have any thoughts on today's latest news on Seeing Machines:
http://www.proactiveinvestors.co.uk/companies/news/69926/seeing-machines-lays-out-two-year-road-map-69926.html
Thanks, James
Hi James,
Many thanks for your kind comment!
As regards Seeing Machines (LON:SEE), I thought the update today was useful, particularly setting out in order of importance which sectors they are addressing.
I like the company. It's speculative, but they have the cash to expand the company, and I've met the CEO & FD a couple of times, and think they are a very backable team.
The technology is excellent, proven to work & being rolled out in the mining sector. It could turn out to be standard in every road vehicle on the road in 10 years' time, who knows? There is rail & aviation too. Plus lots of opportunities in advertising displays (to track what people look at), consumer electronics, etc.
So it's speculative, but further along the development road than many other AIM companies. So I like it, and hold some, although again I don't normally take big positions in speculative companies, because it so often takes longer & costs more to commercialise new things than anyone expects.
Regards, Paul.
Re:Porta Communications. One of my rules of thumb is never to invest in mining companies or banks, and the same goes for PR companies, like Porta, with rapid growth driven by acquisitions.
I have no sense of how astute Bob Morton is, but sense that the CEO’s share acquisition fits your view of someone trying to support the share price ahead of more paper-financed acquisitions. Porta’s shares have been trading at a sizeable discount to the 13p a share which was the placing price when the company raised £7m last March – increasing the number of shares in issue by a third.
Over the last couple of years Porta’s revenues have jumped from less than £1m to £24.4m and yet the company remains loss-making. At last week’s AGM the CEO stated that after five months of the current year, “the performance of the Group remains on track, making substantial progress towards our goal of delivering positive EBITDA after all costs for the full year.”
That said I was more than a little surprised by some of the ‘big’ names on Porta’s share register – a small company with a market cap of £27m. Hargreave Hale has 11.6%, Fidelity 7.0% and Ruffer 6.6%. These are serious investors, so perhaps my scepticism is misplaced.
I share your scepticism of PR companies. Low barriers to entry and over reliance on a few key people, plus a general mistrust on their own spin. There are plenty of other opportunities to be found elsewhere.
Hi DarwenLad,
I appreciate that Porta Communications (LON:PTCM) will not be most peoples' cup of tea.
However, as you say, it has very shrewd mgt (Bob Morton is Chairman, and the CEO has a strong track record of building PR businesses). Also, to correct one point, they are growing mainly by start-ups, and only a small amount of acquisitions. So they shouldn't have a Balance Sheet stuffed with goodwill like most PR groups that pay too much for acquisitions.
Yes they might well issue some more shares, so they no doubt want to pump their own share price, which I think they did way too aggressively in late 2013 & early 2014. They seem to be toning it down somewhat now.
There has been impressive growth so far, and I've put out feelers in the sector, and am told that Porta's operations such as Newgate & Newgate Threadneedle are sensible operations, and have offices in quite a few countries already.
They've done a helluva lot already, in a short space of time, so I think this is a potentially interesting company.
Not for most investors, I fully accept that, but it's the type of situation where you're really backing a serious management team, who've have been there & done it before, in a sector that is not rocket science. They should therefore be able to do it again, and this is the right time in the business cycle to be growing a PR outfit too.
It's not one that I'm prepared to back heavily, but have put 4% of my long term part of my portfolio in it, on a sem-speculative basis.
Regards, Paul.
Worth mentioning that Plastics Capital (LON:PLA) also reported preliminary results to 31st March today.
I still have a few shares in the company left, having bought originally at 30p in 2010 and topsliced heavily along the way.
The results are a bit of a curates egg:
Positives:
Negatives:
I look forward to meeting the company and grilling executive chairman Faisal tomorrow.
Cheers,
Mark
Hi Mark,
We crossed in the post! I've just finished my write up of Plastics Capital (LON:PLA) and came up with a lot of similar points as you. Although I must say your bullet point formatting is much better than my reports. I might try out that style in future, to make these reports a bit more concise.
Regards, Paul.
An impressive piece of analysis by Paul Scott on insider trades.. I will give PTCM a good look.
I suspect that most small deals are really dividend reinvestment and are not meant to trick investors at all as most directors do not realise that there trades are followed. (I have a cut off figure and just ignore trades below this figure.)
Transfers in and awards can wrongly be described as buys or sells. There is a big difference of opinion as to what some of these trades are by different sites recording them.
Remember that insider dealing is illegal even if declared so do not expect the directors to be too obvious.
Some authorities think you should ignore buys by a new chairman who often make a large purchase at the start of their term. Buys and sells by financial directors are considered more important than by other directors as they are better placed to see what the company is doing and as ordinary working managers are unlikely to make grand political gestures. (The rich can be just as greedy as the poor.)
My little system tends to ignore buys in small companies, as they tend to be small in magnitude. Check to see if they are bigger than ever before or a number of directors have bought in quick succession.
WARNING - Director buys are no guarantee of success so only consider buys that appear in your screens and you would consider buy them for other reasons – value, growth etc.
Looks like lots of people are thinking for themselves anyway!
Hi Paul,
Very impressed with the BIG website, and the events look like great fun. I'm a Londoner but will definitely try to make it to the September one. Presumably there are budget hotels in the vicinity that won't be fully booked at that time of year.
Regards,
Steve
Have to disagree with you about Friday's SCVR Paul! It was pithy and to the point, but it also gave great comfort to those (many?) of us who occasionally do whatever we do in the mornings, with alcohol still coursing through our veins from an enjoyable evening the night before.
No penance needed.
Regards.
I have to agree with muckshifter I am afraid! Perhaps it is the repressed, garret-dwelling artist in you, who needs the occasional inspiration from drink. Try the absynth Paul!
Re Getech (LON:GTC) , I noticed an awful lot of director sales over the years and no buys. They consistently sell in the high 50s or low 60s, so that may be the measure of the company. Reading their last statements the implications are that the good news was all already factored in.
Hi Paul -
Re GTC. A company that issues several profit warnings and closely follows with news of major contract wins hardly adds to its management's credibility.
Hi Ramridge,
"Re GTC. A company that issues several profit warnings and closely follows with news of major contract wins hardly adds to its management's credibility."
Yes and no, on this point. What the profit warning said, is that there were big contracts close to being signed, but that most of the turnover would fall into next year (the year commencing 1 Aug 2014). Hence they had to warn on the y/e 31 Jul 2014 regardless of what happened with the new contract wins. They are obliged to publish that information once they become aware of it.
So I think you're being unduly harsh on them. The key issue is that the big contacts HAVE been signed now. That's all that matters. Shareholders will just have to get used to this kind of volatility, it's inherent in the company's business model.
Regards, Paul.
Hi Paul. OK I take your point. But let's consider the opposite. Management issue a very bullish statement... big contracts are very likely to be signed this y/e... results are likely to exceed market expectations. and so on. A few days later they issue a profit warning. Would the market be so understanding and put it down to inherent volatility? Well methinks there would be quite a few juicy unprintable remarks made about management's credibility.
Paul
Your positive comments on Porta Communications (LON:PTCM) are particularly interesting, since the Stockopedia traffic lights and rankings make it look bargepole. Is there more behind your optimism than just the director buys?
It's not clear from your article whether or not you have a position in this stock.
Hi FREng,
Porta Communications (LON:PTCM) is a growth company, a start-up in the last couple of years, so that type of company will almost always look horrendous on the Stockopedia traffic lights & rankings. Especially as in this case where there are no broker forecasts to work on for things like PER, EPS growth, etc.
So it's a different type of investing really. What I see in Porta is an experienced management team who have done it all before, and a series of people businesses (PR companies) being created rapidly, which don't require much capex, and where you can rapidly build turnover from using the contacts & experience of the people you employ.
Growth company investing is higher risk, but every now and then I spot an interesting opportunity, and Porta is one such case. Although as I mentioned in a report a few days ago, I feel that they exaggerated the true performance of the group in a trading update in Jan 2014, which was very misleading. The issue was that they classified "start up costs" as being the first two years' trading losses! Which is crazy. However that treatment appears to have stopped now, and much more conservative reporting is being done.
Decent sized Director buying is a good sign too, in my view, for the reasons given in today's article.
I normally avoid growth investments, where companies have no established track records of profits/divis, but every now and then something interesting comes along that looks credible to me, and Porta is one such case.
As always, please DYOR. It's not one that I've gone into too heavily, it's about 4% of the long term part of portfolio.
Regards, Paul.
Thanks, Paul. That's clear now.
FREng
I am still not too certain about GTC but with two recent contract wins I have bought the 10k that was available at 45.75p. I am still concerned at what the FY results may bring but if they go on winning contracts the market may well be prepared to look past them. At least there is a cash buffer which should enable them survive a weak 6 months trading.
Will consider adding more on further contract wins.