Small Cap Value Report (30 Nov 2016) - D4T4, VP.

Good morning!
There was nothing of interest today, so I'll recap on a few interesting updates that I've missed in previous days.
D4T4
Share price: 146p (up 7.7% today)
No. shares: 37.4m
Market cap: £54.6m
Half year results, 6 months to 30 Sep 2016 - background: this company caught my eye in Feb 2016, with a very upbeat trading update, which I reported on here. Since then, the company put out excellent results here (for year ended 31 Mar 2016). Adjusted EPS rose 113% to 8.24p, and the divi was up 257% to 2p. Impressive stuff!
Note that Peter Simmonds is the Non-Exec Chairman here - he's got a considerable investor following, as his track record at dotDigital (LON:DOTD) was very impressive. Plus more recently, he's been important in helping management at Cloudcall (LON:CALL) (in which I have a long position) refocus their strategy. So it's good to see him buy 70,000 D4T4 shares at 142p yesterday.
The interims look good to me, here are a few key numbers;
- Adjusted EPS is up from 3.78p last H1, to 5.44p this time. Although note this is flattered a little by a reduced tax charge.
- Adjusted profit before tax up 25% to £2.12m
- Revenues of £10.0m in H1, so note the strong profit margin
Outlook comments sound good;
D4t4 Solutions trading remains strong and, since the start of the second half of the financial year, we are pleased to report that we have secured a number of additional contracts including one with a leading US retailer and one with a UK based insurance company.
In summary, on the back of a strong first half performance coupled with continuing demand from our existing customers and a growing new business pipeline, the Board remain confident of being able to deliver further strong growth.
Therefore, notwithstanding any unforeseen economic impact of Brexit and the recent US elections, the Company expects to deliver trading results for the year ending 31 March 2017 in line with current market expectations.
I particularly like the comment about "further strong growth". Plus of course an "in line with market expectations" comment is always good.
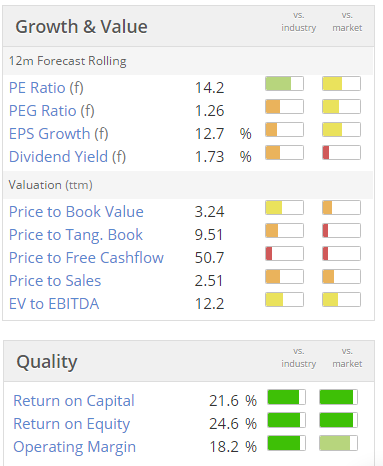
Valuation - the forward PER looks to be just under 15 (I'm not sure if the graphic below has updated for the 7.7% share price rise today), which looks fairly sensible to me.
Note also the high quality scores - indeed, in the StockRank system, the quality score is 99. Therefore this share seems to be a good QARP (quality at reasonable price) situation.
Balance sheet - overall it's OK, with £15.7m NAV. As you would expect for a software company, it has a lot of intangibles, totalling £10.3m, bringing the NTAV down to £5.4m - that's perfectly adequate for a company of this size.
One item which does stand out, is debtors. This has shot up from £2.7m last half year, to £7.0m at 30 Sep 2016. That looks unusual, but I can't find any explanation for it in the commentary. So I think management need to be asked by debtors is so high? Turnover in the half year was £10.0m, so to see £7.0m in debtors looks anomalous.
Capitalising development spend - this is a common way to boost reported profits at software companies. In practice, management have a great deal of leeway on how aggressive they want to be on this - hence why it's important for investors to check the numbers.
I can't see any development spend being capitalised here. That's good. Perhaps it's because the company is doing a lot of project-based work, so they expense costs as they go along.
My opinion - the problem for me, is that I don't understand what the company does. Its website talks in general terms about data, the cloud, etc. However I can't see any case studies to explain in practice what they actually do.
Sustainability of profits is another point that worries me. The company's work seems to mainly be project-based, with some recurring revenues on top. So what happens if the current good run of contract wins fizzles out ? Could costs be scaled down quickly, or not?
Investors really need to drill into the business model, and properly understand what the company does, how that compares with competitors, etc. That's beyond my remit here.
All I can say is that, based on the numbers & forecasts, the shares look quite attractive, providing growth & good profit margins can be sustained. Well worth a closer look, in my view.
VP (LON:VP.)
Share price: 745p
No. shares: 40.2m
Market cap: £299.5m
Interim results, 6 months ended 30 Sep 2016 - this is a group of niche equipment hire businesses. Niche is good, I like niche. It usually means higher margins than mainstream. Also bear in mind that the recent bid interest in Lavendon (LON:LVD) shows that there could be takeover interest in this sector, for overlooked, undervalued companies.
Although bear in mind the sector risk - equipment hire companies tend to over-invest in the good times, then end up facing problems from over-supply & collapsing profits in recessions.
A few key figures;
H1 revenues up 16% to £121.7m - driven by 2 acquisitions, and expansion of the hire fleet from capex
Profit before tax & amortisation up 8.7% to £18.7m. Note that profit is up a lower percentage than revenues, so some margin slippage. However, still a strong overall margin of 15.4%
Net debt up 24.9% to £107.5m - which compares with fixed assets (mainly the hire fleet) of £188.4m
Depreciation charges - I wonder if these may be inadequate, as the cashflow statement shows that asset disposals are being made below book value both in these interim accounts, and last year in full.
Balance sheet - overall it looks OK to me, for this type of business. Debt is fairly reasonable. NTAV is £78.7m. Note that the P/NTAV of 3.8 is quite high for a tool hire business. There may be a good reason for that, because VP makes high margins, but it's worth noting anyway.
This compares with Lavendon (LON:LVD) which, even with a takeover bid going on there, is still only on a P/NTAV of 2.0.
So the danger is, for VP, that its high margins might draw in competition, and squeeze those margins down somewhat.
Pension fund - there is a fund here, but it looks to be fully funded, as there were no contributions made in H1, and only £369k paid last year. So even if there is a problem here, it looks small.
Outlook comments - excellent stuff here, so more forecast upgrades are due;
In conclusion we remain very positive about the opportunities for the Group in the second half of the year and beyond, and believe that we will be able to report results ahead of market expectations for the financial year as a whole.
Forecasts - seem to have been raised from c.62p to c.65p EPS for this year.
That is a PER of 11.5. That looks about right to me, for this type of business.
My opinion - I've always liked this company. Whether the shares can make much progress from here, in the short term, I'm not sure. The share price has been fairly flat now for the last 3 years, and the dividends aren't enough (2.8% yield) to make it a nice long term one.
Lavendon was an obvious valuation anomaly, but this isn't, in my opinion. Nice company though, and it seems to be well managed. I wouldn't want to see them taking on any more debt though, as that would open up risk of the wheels coming off when the next recession hits.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
I understand that D4T4 has just been recommended in the Smaller Companies Share Watch news letter...
Paul - D4T4 work with retailers and banks to collect data from multiple touch points (eg websites, social media etc) to understand what a consumer likes (both today and historically) so that the client can offer their customers a relevant offering in real time. Eg they work with a large UK bank to offer new loan or mortgage products based on current and historical browsing habits. On the retail side the poster child for them is Shop Direct who have worked with Celebrus (who they acquired in Jan ’15 for £8.5m) for the last 5 years. Shop Direct’s investment in big data and personalisation even made the pages of the CEO’s review – see page 2 of their interim review here:
https://www.shopdirect.com/wp-content/uploads/2016/05/Shop-Direct-Interim-Review-2015-16.pdf
And here’s a great article that talks about Shop Direct’s digital personalisation which also mentions Celebrus
http://internetretailing.net/issue/internetretailing-magazine-july-2015-issue-53-irm53/shop-direct-making-good-things-easily-accessible-to-more-people/ . They've also just launched a new product called Insider Threat. The product has been developed with SAS – one of the World’s largest cyber fraud s/w providers – and will be targeted at Banks who want to monitor insider threats from staff. Their s/w is embedded into banks web browsers (which is where staff access c.90% of applications now) and can capture every key stroke, mouse move, what you printed etc. Essentially SAS didn’t have the collection technology - but using the Celebrus tech they can now collect data and build up a pattern. SAS then have the algos which decides whether to flag behaviour as suspicious. The City boys better be on their best behaviour!
Hi Paul
Re VP (LON:VP.) Further down the cashflow you get;
Proceeds from sale of property, plant and equipment £8.108m ,
so the net profit on disposal is c.£4.8m, its presentation is confusing but I suspect it is largely because of the way it is funded, so the first figure is the net finance balloon paid in the accounting period , and the latter number is the actual sale proceeds received in period .
The assets in question will vary from one to the other due to timing issues and some wholly owned assets but on balance VP has been very conservative and made money on RV's
Cheers
Proceeds from sale of property, plant and
Paul,
If you are circling round maybe you can get a chance to comment on Focusrite (LON:TUNE) FY results. You have commented on them once before suggesting they should go on your watch list.
I missed their FY announcement last week, but Focusrite (LON:TUNE) cropped up on the new Stocko QM movement screen this morning, up +14 points to score 90. They have a number of updated digital audio products that sold particularly well in H2. Their broker has bumped up this years earnings which probably accounts for their improved QM rating. The short term outlook is quite strong and they appear to have a dominant position in a particular audio/mixer recording segment.
Hi Paul
At the AGM we quizzed them re: their reliance on Teradata (their principle Client) as a significant amount of revenue comes via them, however, as with most major companies (Teradata) they have multiple client bodies within and hence the risk is somewhat mitigated.
The Board were very cognisiant of over reliance on any single customer and have secured a number of new Clients and partners over recent months. They also have decent recurring revenue. Your point, however, is of course still valid!
Suggest it's worth watching this re: what Celebrus / D4T4 do (well part of their business anyway):
http://www.teradata.com/Resources/Videos/PARTNERS-...
Teradata have US$2.5b of revenue....
"A large project was invoiced (through partner SAS) at the end of September, due this month. It left £4.7m working capital outflow in H1 and lifted trade debtors from £2.8m to £7.0m at September. The resultant £2.6 Free Cash Outflow and £0.5m dividend reduced net cash from £3.4m at last year end to £0.1m. We are reassured this is a major, long standing global banking client which is in good standing and payment is due imminently. With the usual strong cashflow we expect D4t4 to finish the year with around £6.0m net cash".
Good morning Doctor!
Thanks very much for posting that comment from FinnCap re debtors, very helpful, and sounds reassuring. Although it does raise the question of how dependent the company & profits are on individual large contracts, lumpiness, etc. It looks the type of business that could easily have a gap in the order book & warn on profits, at some stage (maybe not imminently though, as the outlook comments are very good).
Regards, Paul.