Small Cap Value Report (30 Sep 2014) - ZZZ, ZIOC, BEG, BAR

Good morning! Clothing retailers are in focus today, as Next (LON:NXT) has announced that unseasonably mild weather is hurting sales of autumn/winter clothing ranges at the moment. This will be affecting all clothing retailers - I recall in my days as an FD in this sector, every year I hoped for a cold snap in September, as it would give sales a strong boost as people bought jumpers & particularly coats (higher priced, so have a good impact on performance overall). So the opposite effect is happening at the moment - slower sales due to mild weather. It all averages out in the long run, so personally I see dips due to unfavourable weather as potential buying opportunities.
On the flipside of that, I suppose DIY and garden centres do better in mild autumn weather, which could explain why Kingfisher (LON:KGF) shares have been creeping up lately. Incidentally, I read the last Annual Report for Kingfisher the other weekend, and was tremendously impressed with the strength of its Balance Sheet, stuffed with a 10-figure sum of freehold property, and yet still with net cash on top. So I bought some shares in it, as it's also a nice play on a recovery in the French economy, which is going to happen sooner or later, we just don't know when. Reasonably priced, and a 3.5% divi yield too, plus share buybacks.
Snoozebox Holdings (LON:ZZZ)
Share price: 7.0p
No. shares: 211.8m
Market Cap: £14.8m
There are three announcements from Snoozebox this morning. This company has carved out a heavily loss-making (!) niche as a provider of temporary hotel accommodation - a great idea, to convert standard metal shipping containers into small but comfortable hotel rooms. The original business model failed, because the units were far too complicated and costly to set up & dismantle, thus negating the benefit from room rates charged to customers.
However, new management took over, and the business model has been re-worked. So the version 2 units are self-contained (no need for a separate utilities service unit), and can be quickly & simply fixed up or taken down, just in one day. So having learned from the mistakes of the v1s, the v2s are actually a viable proposition. On the basis of this, I took part in the 10p Placing a few months ago, which on reflection probably wasn't one of my better decisions. However, after this morning's announcements I'm starting to feel a lot more optimistic. Principally because of this;
Lease finance - until now Snoozebox has relied upon repeat equity funding rounds, each at much lower prices, and causing more & more dilution, as losses mounted. Furthermore, the last 10p for £ 10m funding round was a struggle to get away (they tried for more originally, but investors were not prepared to invest) - and being cynical, when Placings filter down to the likes of me, then you can be pretty sure it's been turned away by bigger hitters!
So I've always hoped that they could secure some asset financing - after all, the Snoozebox units are long-life assets, which could easily be sold on in the event of debt default. Sure enough, a deal has been done, announced today, to raise up to £15.6m of lease funding.
This is highly significant, because it means that as of today, Snoozebox are no longer reliant on holders exercising the 10p Warrants that were attached to the 10p Placing. So those Warrants can expire in Dec 2014 without it harming the company's expansion plans for 2015.
It is not stated what the terms of this debt financing are, so I hope they are reasonable.
Interim results - to 30 Jun 2014 are also announced today. The way I'm looking at these, is that they're largely irrelevant - as they relate to the old v1 units. This share is all about the viability of the v2 units coming into service in 2015. Certainly those of us who put fresh money into the company in the last Placing did so entirely on the much more favourable economics of the new v2 units to be built using the Placing proceeds.
So all that matters with these results is that the losses are minimised until next year's launch of the v2s (I keep thinking about Hitler when writing about v1 and v2s). On that score, the company gets a tick - the pre-exceptional EBITDA loss for H1 this year is reported as £1.6m, vs. £3.6m in the equivalent period last year. Although I am somewhat taken aback by the dramatic drop in turnover - which was only £731k in H1 this year, down from £4.3m last year. However, in this particular case, turnover is less important than cost-cutting and preserving cash, which they've done.
Balance Sheet - this is sound, with the £ 10m Placing proceeds still intact, net cash was a whisker over £11m at 30 Jun 2014. That cash is mostly being spent on a batch of v2 units under construction, I believe. More units can now be built using the lease financing. So there should be a much better proposition for 2015 and beyond, hopefully.
Outlook - a fair bit of detail is given, and I am intrigued by the international sales potential, once they have hopefully got the new v2 units working on a commercially viable basis next year;
...The Company is experiencing high levels of rebooking, with over 50% of rooms booked for key events in 2015 that are on sale. The event programme includes a hotel deployment during the Rugby World Cup next year
Snoozebox continues to see strong international demand. The Company successfully deployed at the World Equestrian Games in France and reached preliminary agreement for a Snoozebox Fanzone Village for the 2018 World Cup in Russia earlier this year. The Company continues to experience clear demand from the US, South America and Middle East and active discussions are ongoing for events including the 2016 Rio Olympic Games and 2022 World Cup in Qatar.
I believe the progress made in the underlying operating model in the first half of the year, combined with the launch of the Next Generation Portable Hotel in the second half provides a platform on which to transform the performance of the business in 2015 and to scale the business in 2016.
My opinion - Sentiment is very negative towards this company, which I like because it can mean the shares are cheap - but only when combined with specific reasons to believe that a turnaround is underway. I've drilled into the business model in some detail, and believe that the new v2 units will be a viable business, combined with the now much lower central overheads.
New management previously put some of their own money in too, which is confidence boosting.
This share is far too speculative for most people, but for me the lease financing deal is a game-changer, and I reckon this stock has potential to surprise on the upside in 2015. It may not, after all it's been a serial disappointer in the past, we'll just have to wait and see!
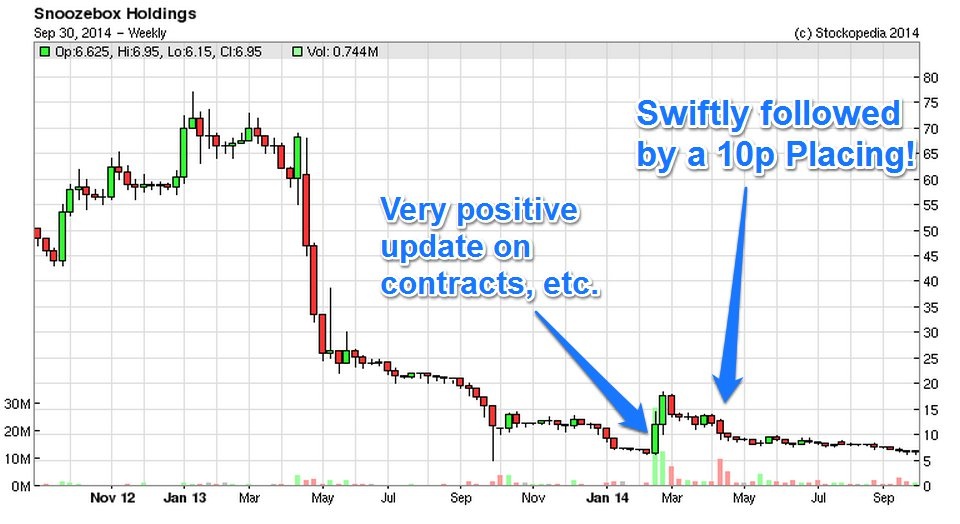
General Point - trading updates & Placings
As you can see from the Snoozebox chart above, on 20 Feb 2014 its shares more than doubled. I remember that day well, because the trading update RNS flashed up on my screen during the day, I quickly read it, noted that it seemed amazingly positive, so I then rang my broker with an instruction to buy as many ZZZ shares as he could get, below about 8p. I filled my boots, and the price shot up to peak at around 18p the following day, so I was thrilled to bits, having made a terrific profit. Like a fool, I didn't sell, as greed had set in by this stage.
However, the share price then inexplicably began falling. This is odd I thought. Maybe some profit-taking, before the price roars up again? Sadly not, as a few weeks later in Apr 2014, the company announced a discounted Placing at 10p. The Placing just about got away, but the price swiftly dropped below 10p (maybe Panmures had to pull in some favours to get buyers, who swiftly dumped the stock afterwards?) and we're now down at 7p.
Now I did bank some gains at the higher levels, although of course once I was taken Inside on the Placing then I was barred from dealing in the open market at all.
What are the lessons to be learned from this?
1. I should have banked at least half of the spectacular original gains, instead of holding on for a bit more.
2. That companies which need cash will use positive trading updates to get the share price up, in order to facilitate the next Placing.
I don't normally buy into shares with cash requirements - my Balance Sheet testing is such that I reject companies with inadequate cash reserves normally, but this was more a short term trade on the positive trading update, not a long-term investment. It's turned into a long-term investment since mind you, as I genuinely see good upside next year, and I don't mind waiting & absorbing losses in the short term.
Another key lesson;
3. Trading updates which contain lots of good news, but very few hard figures on profitability, are largely flannel! They might sound good, but you often subsequently find out that profits are disappointing, despite supposed good news on contract wins, sales increases, etc.
4. The key sentence to look out for in a trading update is "profits are ahead of market expectations". If it doesn't say that, or something very similar, then it's probably flannel designed to get the share price up! Which may well be followed by a discounted Placing.
5. Private investors are the cannon fodder that are used to lap up stories, get excited, buy the shares, create a favourable up-trend in the share price, so that Institutions then feel comfortable buying discounted shares through a Placing. So we need to be aware of this, and push back!
Zanaga Iron Ore (LON:ZIOC)
Share price: 13.625p
No. shares: 278.8m
Market Cap: £38.0m
Zanaga is one of my extremely rare sorties into the resources sector - which is not a sector I usually follow. The company has a JV with mining giant Glencore, over a huge iron ore project in the smaller, more politically stable of the two Congos, the Republic of Congo, also known as Congo-Brazzaville.
I've been excited about this project, and have delved into it in a lot of detail, meeting the company 3 or 4 times. However, I've also been tracking the price of iron ore, and it's fallen to five year lows of only around $80 recently. This project should still stack up at that level, but it's eating into the margin of safety for investors, and potential financiers of the necessary capex. So for that reason, as mentioned in the comments section of yesterday's report, I have cut back my position size to reflect the increased risk from the lower iron ore price. We discussed this in the comments sections of yesterday's report - which I urge anyone interested to read, as there were some excellent responses from readers.
From what I can make of it, and bear in mind this is not my sector, the company seems to be stating a Proved Ore Reserve statement for the first time. As expected, this demonstrates that there are vast amounts of high quality iron ore to be extracted, which has never been in any doubt. It's more the economics of the project at lower iron ore prices that is the burning issue.
As discussed yesterday, the key question is whether this project is actively progressed, or just mothballed. That depends on whether Glencore are prepared to look through the current weak iron ore price. They might well do, as it will take several years to develop Zanaga to production, and by that time Glencore are already on record as believing that iron ore prices will be rising again.
On the other hand, Glencore seem to be capex-averse, so we really have no way of knowing whether they will want to progress this project or not. The plan was to use debt financing for most of the capex anyway. We'll just have to wait and see what happens.
Today's announcement has firmed up the price by 8%, which is pleasing, but follows a period of quite sharp share price declines, reflecting the fall in the price of iron ore, unsurprisingly. Zanaga have always stated that there is a lot of high-cost iron ore being extracted, especially in China, so the lower iron ore price will be putting severe pressure on other producers. Therefore supply could tighten up again after a while, as high cost producers potentially go bust.
Begbies Traynor (LON:BEG) - today's AGM statement looks like it's warming up for a mild profit warning;
...As last year, the financial outturn for the full year will be heavily dependent on trading in our traditionally busier second half. However insolvency market conditions remain challenging, which may impact on performance for the full year...
Lower revenue is noted for the year to date (May-Aug 2014);
Market conditions remain challenging, with the Government insolvency statistics worse than expected. An 8% decline was reported in the number of corporate insolvency appointments to 8,948 in the first half of calendar year 2014 compared to 9,727 in the same period of 2013*. This reduction in market activity has led to lower year on year revenue which has been partially mitigated by the contributions from recent acquisitions.
Begbies shares are down about 7.5% today, to 48p.
My opinion - I'm less keen on this share than I was, as they've had a good run in the last year, so I was happy to bank the profit & move on some time ago. The valuation looks about right to me, taking everything into account. There's a good dividend yield. Also note that Stockopedia gives this a 99 score in the StockRank - surprising that it's so high, but it is, so there we go!
Sorry, go to dash now - lunch appointment.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in KGF, ZZZ, and ZIOC, and no short positions)
Eclectic Bar (LON:BAR) - Just a quick late one, to get my notes into the system. This company floated on AIM on 28 Nov 2013, at 160p per share. £15.0m was raised, but this was mainly used to buy out a shareholder called Avanti Capital, and to repay their shareholder loan. So the company retained only £1.8m of the net funds raised. I'm very wary of companies floated by PE/VC - they normally ensure that they get the better side of the deal. So why take the other side?
Results published today for the 52 weeks ended 29 Jun 2014 have not impressed me. Continuing operations had a turnover of £23.0m, and traded at just below breakeven for a £106k operating loss. Our attention is drawn to £1.1m in "highlighted items", being things like the IPO costs (fair enough), but also pre-opening costs for new sites, bonuses for management, etc.
So highlighted items rewind us to a £1.1m underlying trading profit, still not great for a £23m turnover business. The narrative tries to draw us to EBITDA - sorry, no way. Capex is continuous in the bars sector, because the customers trash the joints pretty quickly. Therefore in my view the market cap of £24.5m (at 190p per share) looks quite high.
Balance Sheet backing is fairly light - net tangible assets are only £4.5m.
The problem I have with bars, is that the young customer base generally can't afford to pay bar prices for drinks. They will just pre-load before visiting a venue, and buy a few drinks once inside. Why pay £3-4 a pint, when you can get a perfectly serviceable chilled can of lager from a supermarket for under a pound? It doesn't make sense for people who are struggling to earn more than minimum wage, or relying on parents for income.
So this one doesn't appeal to me at all. Bars & small nightclubs are better off being lifestyle businesses, owner-managed. I don't think there is scope for investment gains from owning emerging chains in this area. Luminar was a disaster a few years ago, as we discussed recently here. The cycle will just continue - new groups are formed, take on too much debt for expensive refits, then go bust in the next Recession. Repeats every few years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Thanks for your reply Jardine.
Was not aware of the practical implications.
I don't get the snoozebox business model.
Compared with a "proper" hotel building, the acoustics of shipping containers must be poor, therefore requiring some decent insulation to rescue that situation. I would want to stay in one or at least read some good Trip Advisor reviews before investing.
jonesjeff,
Snoozebox units have been around for a couple of years now, so there are loads of customer reviews on the internet - have a dig around. People love them, in the main. There's no issue at all with demand - quite the opposite.
What the original business model lacked was the ability to setup and dismantle quickly & cheaply. Instead setup was horribly expensive & time-consuming, using multiple contractors, thus negating all the income from hiring them out. So it was the equivalent of a normal hotel that only managed to fill its rooms about 1 day per week - i.e. heavily loss-making!
So, the new management have completely re-worked the business model, recognised that the v1 units were not going to work on a mobile basis, and instead ear-marked them for semi-permanent installations where they become small cash cows, and in addition created the v2 units that are self-contained, very quick & easy to set up, and hence will be economically viable. I recall crunching the numbers over the phone with the new CEO, and it seemed to stack up.
The only issue now is to build enough of them, to make it all work. Hence why the lease funding deal today was so important, as that opens the door to getting another batch manufactured & into service next year hopefully.
It could well work at the second attempt, in my view. Remember it's new management too.
I'm only interested at the current valuation because the stock is trading well below net tangible asset value (mainly cash), and has the funding to proceed. I wouldn't touch it with a bargepole if the valuation contained any speculative froth, but at the moment it doesn't, as I flagged in today's report.
Regards, Paul.
Re: Snoozebox
I am surprised no mention of this in the interim report, it will certainly help with the bed shortage in the NHS.
http://www.google.co.uk/url?sa=t&rct=j&q=&esrc=s&source=web&cd=1&cad=rja&uact=8&ved=0CCMQFjAA&url=http%3A%2F%2Fwww.hsj.co.uk%2FJournals%2F2014%2F09%2F17%2Fd%2Fr%2Fy%2F140919-efficiency-supplement.pdf&ei=uwUrVMaDDMbB7AbslIG4AQ&usg=AFQjCNHee4HuKuVK5Fq0gWSeO4qkoUMyMw&bvm=bv.76477589,d.ZGU
Medirest and Snoozebox have signed an
agreement to work in collaboration and are
seeking expressions of interest from NHS
trusts to take the concept forward
Great point about placings Paul. It all helps to demystify the goings on in small caps.
Thanks!
Are Snoozebox's V1's worth anything? The company has shown they can't be operated profitably. Surely that makes the asset worth scrap value.
They cannot be operated profitably as mobile units, but they will have value above scrap as static installations. (A friend stayed in one last year and was very impressed. He actually said at the time he would like one to stick in his garden!)
Hi MrC,
As Beginner says, the Shoozebox v1 units do have a value, as once they V2s are in service, then the v1 units will be used for static installations - e.g. the long-term hotels at places like Silverstone, and TT races, where planning permission has I think been granted (or in the pipeline?).
I lost my notes, but from memory when I discussed this with management a while back, I think they said that the v1 units are expected to generate a positive contribution of enough to cover their central plc overheads. I may have got that wrong, but it's something along those lines.
I did check it at the time, and the book value of the v1 units does stack up (haha, geddit!!)
Regards, Paul.
Here is an example of how Snoozebox Holdings (LON:ZZZ) are deploying their stock of the first version containers as semi-permanent hotels, which avoids the need for the expensive deployment costs every time they are moved, which was their problem.
http://www.edenproject.com/visit-us/hotels-and-ticket-packages/on-site-yha-hostel
What a great idea to link up with the YHA who are geared up to manage this sort of facility.
According to the RNS today they have already deployed 50% of their first version containers on a semi-permanent basis and the pipeline of interest exceeds the remaining stock available. I know they have some interesting ideas for deploying the remaining stock which demonstrates they've been thinking outside the Snoozebox !
So if you want to experience a first generation Snoozebox take a trip down to Cornwall and visit the Eden Project.
Andrew
Hi Paul. I would argue that now is not the time to sell Begbies Traynor (LON:BEG) because:
1. There is a large number of zombie companies which are operating at break even or worse in the current low interest environment.
2. Interest rates will increase and the number of insolvencies will therefore rise.
3. BEGBIES have gone though a difficult period over the last few years due to the above. Interest rate increases are in sight (probably early 2015) and this should improve their business and having held for the past couple of years I'm not going to throw in the towel just before rates start to rise! I bought Begbies Traynor (LON:BEG) as a turnaround/recovery situation.
4. There is a good dividend yield on offer paid whilst you wait for the recovery in business.
5. Begbies Traynor (LON:BEG) is a relatively 'safe' and boring investment which is good in the current market environment in small caps.
Best Wishes,
Ben
Absolutely crucial question. Does snoozebox have patents for the idea? Does anyone know?
If the answer is not, big avoid from me
How can you patent living in a metallic box? Its a valid point - I am sure from what I read v1 to v2 is much better there is nothing stopping someone else making a v3....
I thought they tried to patent it on ipo but never got it away. Easy to copy so international market would become competitive. margin squeeze and loss of market. low barriers of entry.
not convicing really
Hi Paul,
I take your point about Snoozebox having solid asset backing. This is indeed a fresh start for the company and they could make it a success.
My concern is that this is (1) a new concept and (2) v1 did not fly. My concern is that despite managements great enthusiasm v2 could go the same way, and there is unlikely to be a v3, given the size of the company. For me this is too speculative but then I may also miss out due to my risk averse viewpoint.
Zanaga - as you say is a binary bet. As with most such bets these are best left to investors who can diversify across a number of such companies and assess the odds of success.
Good luck to investors in both companies.
Rick
Hi Rick,
"My concern is that this is (1) a new concept and (2) v1 did not fly. My concern is that despite managements great enthusiasm v2 could go the same way, and there is unlikely to be a v3, given the size of the company."
That's not quite right. V1 did fly, in terms of strong demand - customers love it. It failed commercially because it was far too time-consuming & expensive to set them up & dismantle (up to a week either side, using multiple contractors).
The v2 units are set up in 1 day, very simply. So the business model for v2 is radically better.
You're right though, that if v2 don't work, there won't be a v3!
Regards, Paul.
Great stuff!
AIM microcap investing at its most speculative with two companies Zanaga Ion Ore and Snoozebox. Is it just me or is Snoozebox by far the most speculative? I am watching with interest but currently no position.
Hi Rick,
There are far more speculative micro cap companies than Snoozebox Holdings (LON:ZZZ) !
After all, for its £15m market cap, you get net cash of £11m (73% of the market cap), with cash burn having been greatly reduced this year.
Also you have further asset backing from the existing v1 units, with a book value of £14.5m. They've already taken an impairment charge on that, but say halve it to be conservative for resale value, to £7m, and you're actually buying the shares at a discount to the businesses net tangible assets on a fire sale!
So bizarrely, once you ignore sentiment & drill into the numbers, Snoozebox is solidly asset backed, indeed the shares are at a discount!
I would say Zanaga Iron Ore (LON:ZIOC) is far more speculative - that really is a binary outcome - multibagger if it works, heavy loss if it doesn't work.
I don't even scrape the barrel of the real junk on AIM - there are loads of way more speculative stocks than the ones I cover!
Regards, Paul.
Readers may be interested to know that the Snoozebox Holdings (LON:ZZZ) new version accommodation unit, on which the company's turnaround hopes are pinned, is likely to be displayed at the forthcoming Mello2014 private investor event in Derby (6 - 8 Nov). Given that today's statement says the new version units are to be launched in November this is likely to be the first time they will be on show to the public. This will be a useful opportunity for those (potential) investors who are interested in the concept to see what this new version offers before it gains a wider audience and, hopefully, support from the investment community.
Andrew
Declaration: I hold this if you hadn't guessed.
Perhaps it would make sense to record some time lapse photography to demonstrate how quickly (or not) they can be deployed seeing as this was the biggest drawback on their potential
Phil (no position)
Paul just a thought, so shout me down if this idea is ....?
But having listened to the webcast yesterday with your and David I understand Soozebox will be giving some kind of demonstration of their new mk2 container Snoozebox.
To expand on this demonstration?
Would it not make sense for this company to offer actual accommodation to a few brave, potential investors during the November Mello in Nottingham?
As this would give tangible experience of this business model, especially in November in Nottingham.
"Would it not make sense for this company to offer actual accommodation to a few brave, potential investors during the November Mello in Nottingham?"
I have been talking to Snoozebox Holdings (LON:ZZZ) for a couple of months to facilitate them exhibiting at the Mello2014 event in November. The original plan had been to offer some limited accommodation to a few lucky interested (potential) investors but there are some real practical problems to doing this, not least the fact that the Snoozebox experience is heavily brand orientated, and by that I don't just mean the logo. They manage the whole experience carefully from booking through to arrival and maintenance of the service delivery during the stay. As well as the room they would usually offer reception and restaurant facilities plus a lounge area. Given the limited space available it might not be possible for them to offer the whole experience and they are reluctant to compromise the brand. If the position changes I will let you know. To imagine the concept you need to think Premier Inn++ but in a field! Interesting to note that today they also announced the appointment of James Latham who had 17 years experience at Whitbread (owners of Premier Inn) to head up their hotels division.
Hi Paul
On the subject of placings Dillistone (LON:DSG) has one today at 95p. I'd really appreciate any view or comment on that, as well as the interim results and teh acquisition they mention. (For my part it seems a bit cheeky to offer a c9% discount, but I am happy with the acquisition because it gives access to some big companies).
B