Small Cap Value Report (4 Aug 2017) - FRP, OnTheMarket, YOU, SUS

Good morning and happy Friday!
Fairpoint (LON:FRP) (suspended)
This should be the last time we mention this legal services / debt management firm.
Last time I covered it, I said it was hard to imagine the equity was worth anything. £20 million in bank debt had been sold off to a sector specialist, who was continuing to finance the subsidiaries.
Those selected subsidiaries continue to trade, but the holding company (i.e. the company which some of us bought shares in) is entering administration:
...ongoing support for the Group's subsidiaries outside of the Legal Businesses is made more difficult due to the existence of the onerous lease on the Group's head office which has an annual commitment of c£1m per annum for a further 4 years. As a result, and following detailed discussions and the evaluation of a number of options, the Board has concluded that the holding company of the Group, Fairpoint Group plc, is no longer able to continue trading as a going concern and has filed notice of intention to appoint administrators.
People should have mentally written this down to zero some time ago, in my opinion.
I haven't sold anything short in a good while but this is an example of where, if the shares had been still trading up to this point, it might have been a good idea. You only need a limited number of people to think that the shares are not worthless for the share price to remain at a level greater than zero, and for a 100% negative return to be achieved!
Additional comment from Paul: I agree with Graham that Fairpoint has been a terrible mess. I've certainly learned a lot from this one, which we've discussed here before.
I'd just like to come back to Graham on the point of possibly shorting this type of thing (Fairpoint). DON'T! It's way too risky. There are a number of issues. Firstly, when the shares are suspended, the Spread Bet or CFD provider will usually increase it to 100% margin, on your original transaction price. This can suddenly swallow up a load of funds on your account, which are now effectively frozen. It can take months, and sometimes even years, for the stock to be valued at nil, and hence to get your funds unfrozen. So what seemed like a win, soon turns into something of a nightmare.
Secondly, the short squeezes on micro caps in their death throes, can be puzzling, huge, and very dangerous. Only today, we saw apparently worthless ENTU rise over 200%. I've no idea why. But anyone short on that, would have been badly hurt.
The same thing happened with Afren, in its dying days. I was stopped out at 14p on a short there, only to see it collapse days later. The share price of dying micro caps are not logical, or predictable. You can be correct in your idea, but lose your shirt in the process. So why get involved at all? It's not worth the risk.
The worst case I saw, was when something called CPP (I think, not sure, it was a long time ago) seemed dead, at about 1p. The business looked moribund, a certain zero. Then it spiked up to 31p! Apparently several short sellers were almost wiped out by that. So why entertain such a potentially vast risk?? Don't do it, it's madness.
I only ever short large caps, where the downside risk is relatively modest. Even then, you could be stretchered out, if say Amazon did an all paper bid for the company.
Some idiot was bragging about shorting Revolution Bars (LON:RBG) here, not long ago. Presumably he's learned a painful lesson about the dangers of shorting small caps. Just don't do it, it's far too risky.
Right, back to Graham!....
OnTheMarket plc
At the other end of the stock market life cycle, we have an announcement of intention to float from OnTheMarket.
OnTheMarket is the agent-owned property portal chasing Rightmove and Zoopla for market share.
The objective is to raise £50 million of growth capital in exchange for a minority stake in the business at a prospective valuation of £200 - £250 million.
It is intended that the funds raised, along with the existing fee revenue of the Company, will be used to support a heavy-weight national TV, digital and print media campaign. High profile local radio and out-of-home advertising is also planned. Funds will be committed to expanding OnTheMarket's sales and account management organisation and its technology development capacity. This will support the strategy to retain and attract more estate agents and other property advertisers to list on the portal and to grow the levels of traffic and engagement with the most motivated property-seekers.
Given the highly attractive (in my opinion) features of Rightmove as a company and a potential investment, I reckon that investors will be supportive of this IPO.
As for the merits of the valuation, I'll wait until I see some more numbers. While I don't think the other portals (Rightmove (LON:RMV) and ZPG (LON:ZPG) ) are at particularly expensive valuations, it will be interesting to find out whether OnTheMarket can convince investors to pay higher multiples compared to them.
Meanwhile, shares in Agents' Mutual, the alliance of estate agents, will be transformed into shares in OnTheMarket, so most of the portal will continue to be owned by agents:
Agents' Mutual's current members ("Members") number some 2,700 estate and lettings agency firms. In total, circa 5,700 agent branches list their properties with the OnTheMarket.com portal. Currently the Members have one membership interest per firm but, following the reorganisation into OnTheMarket plc, these firms will receive ordinary shares reflecting, amongst other factors, the aggregate amount of fees they have paid in order to list on the OnTheMarket.com portal since its launch in January 2015.
That will offer a nice bit of flexibility for these firms - some spare cash if they want to dispose of their shares, or a stake in a growing property portal controlled by their industry if they decide to hold on.
I'm instinctively a contrarian and I want to say that this IPO is another sign of an overheated property market. I also have some doubt about whether the property portal space can carry three large competitors long-term. But I'll wait and see the valuation versus OnTheMarket's latest figures. If it's reasonable, then perhaps this particular space in the property market isn't too frothy yet.
Additional comment from Paul: Many thanks for flagging this, Graham. I shorted Rightmove (LON:RMV) when OnTheMarket.com was first set up, but it didn't work, as the new portal failed to gain traction.
The IPO looks a bit of a "try on" to me - i.e. attribute a huge valuation to something that has effectively failed so far.
However, there's another way of looking at it. Rightmove (LON:RMV) clearly makes super-normal profits, by over-charging estate agents, and effectively abusing its near-monopoly position. That makes it potentially vulnerable.
OnTheMarket failed originally because it didn't have a big enough marketing budget, and the marketing they did was pathetic. Even their logo is just a meaningless symbol on estate agents windows, without a link to their website.
However, if the IPO is successful, then armed with a much larger £50m marketing budget, and hopefully some better ideas about how to differentiate themselves, I think this could have a much better chance of success.
I wouldn't invest in OnTheMarket, but I think the better trade is a short on Rightmove. So that's what I've done. Rightmove is largely ex-growth now anyway, so its premium rating is not justified, regardless of the renewed threat from OnTheMarket.
YouGov (LON:YOU)
- Share price: 277.5p (+7%)
- No. of shares: 105.1 million
- Market cap: £292 million
When I covered this market research firm in March, I asked "how can it be worth nearly £300 million"? The profit figures, once you ignored the various adjustments (and I think it's right to ignore them), didn't seem to come close to justifying the market cap.
It does have decent growth rates - constant currency revenue growth of 8%, last seen, plus a currency exchange rate tailwind.
And this latest fiscal year (the year ending July) has gone well and should be ahead of expectations.
YouGov has achieved another year of revenue growth well ahead of the global market research sector and maintained the performance trends reported in the first half of the current financial year. In line with our strategy, revenue from Data Products and Services has continued to grow strongly across a number of regions and our Custom Research business has significantly improved its profitability.
It's certainly a very well-known name both inside and outside its industry.
I can't get too excited by it as an investment proposition, however. Firstly, there is the unusual accounting presentation which Paul has covered extensively and which I've also discussed previously.
Furthermore, margins have never taken off here, despite it being a fairly mature business. Poor operating margins have resulted in weak return metrics:
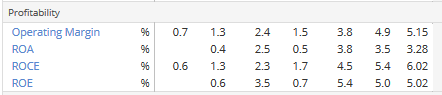
Maybe that's finally about to change. I'm just a bit sceptical after so many years of lacklustre profitability, that's all.
And I'm guessing that staff costs have accounted for most of the increased expenses over this time period. It's a great place to work by all accounts but external shareholders shouldn't expect too much, in my opinion.
Additional comment from Paul: I agree with Graham. The valuation of YouGov has been wrong for years now. It generates very little free cashflow, and the tiny dividends reflect that. It's a good example of how aggressive accounting treatment of capitalising costs into intangibles, can fool institutional investors very easily. I think that's because not many Instis actually bother to scrutinise the accounts properly. There are some honourable exceptions to that rule, but most do very little proper due diligence. The accounts here are not at all credible, in my view.
S&U (LON:SUS)
- Share price: 1928p (+2.3%)
- No. of shares: 12 million
- Market cap: £231 million
This motor finance business and specialist lender issues an update for the H1 period (having last updated at the AGM in May).
S&U's share price has been drifting lower for the past two years despite the business continuing to grow strongly, and this trend continues.
It arranges hire purchase car loans for subprime borrowers:
Trading at Advantage, our motor finance subsidiary, continues at record levels. New loan transactions are up by 20% and monthly collections are 27% higher than a year ago. Monthly collections hit a record £10m from nearly 49,000 customers in July and debt quality continues to be good.
Some noteworthy figures have been speculating receently about the possibility of a crash in the car loan market, in particular with respect to personal contract plans ("PCPs") (see this article).
PCPs have cheaper monthly payments than hire purchase, because you are only really paying for the car's depreciation, nothing else. Instead of making flat payments with hire purchase, you have to make a balloon payment at the end of a PCP contract if you want to buy the car, which is worth nearly 100% of the car's estimated value at that time.
So PCP is akin to renting, with the option to buy at the end, whereas hire purchase is akin to taking out a mortgage.
PCP involves more exposure for the lender but S&U has nothing to do with these types of contracts:
Advantage is not involved in the PCP market which has recently come under public scrutiny. Advantage's average loan size is just £6,200 so should changes in the PCP market have a knock-on effect upon car residual values generally, this would have only a marginal effect upon S&U's business.
Indeed, maybe it would be a good thing for S&U if PCPs ran into difficulty, as it would increase the demand for hire purchase agreements?
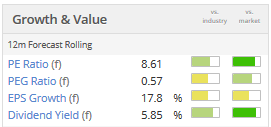
I wrote positively about this company last time I covered it and it still looks very interesting to me at current levels.
That's all for today. Have a great weekend!
Best regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
I am looking forward to hearing Paul / Graham's views on Telit Communications' massive drop this morning - wondering if I should have picked some up, down as low as 40%, now at -34%...
I have just purchased a second home and in the process of selling our current property both have been listed on rightmove. I did check onthemaket but for the whole of Bolton it has 9 listed, rightmove has 1,694!! They are going to have to spend every penny of the £50m and cant see them getting near zoopla either.
Am looking to buy into Strix on Tuesday but maybe small holding, its makes profits but UK growth looks limited and based on infromation from the admin doc they are looking for overseas growthth etc.
Nobody should be buying 2nd homes, when many people don't have 1st homes. Sell those 2nd homes.
This not so much a second home in the tradtional sense just a temporary situation, property came up at short notice and used savings to purchase.
Current home just sold this weekend used traditional estate agents for the job and was listed on rightmove but no other site. Nowhere near that rich be able have second home but appreciate many cant afford one. Took many years of saving so just the one but have upgraded to something with a garden.
The thing with on the market is that's it's owned by agents, and has only got anywhere by giving shares to agents and implementing a one other portal rule. This has meant that many agents have stopped using zoopla and use rightmove and otm. Astonishingly, while imposing this rule on other agents some founding agents have flaunted it. Eventually someone took them to court, but incredibly they won http://www.telegraph.co.uk/business/2017/07/05/battle-property-portals-continues-onthemarket-wins-competition/
they are in fact allowed to contractually insist that their customers list their property on only one other portal. Of course this means that they don't go on zoopla. When they list, they'll get rid of this rule, of course they will, because otherwise the agents will sell their shares and go on the other two!!! I think this is the third horse in a two horse race ! It will be interesting to see if they're profitable, and if the estate agent owners will stick with it or cash in their chips. My bet would be that they'll blow the 50M, get no where near zoopla, and remain a the third portal. If you're looking for a house, why would you go there ? how many homes are there that aren't on rightmove and zoopla ?
Regarding SUS, is this comment accurate? "...you have to make a balloon payment at the end of a PCP contract if you want to buy the car, which is worth nearly 100% of the car's estimated value at that time."
I understood at the end of a PCP contract there is a "guaranteed future value" of your car. Isn't that why they are popular?
Hi Prem, the guaranteed minimum future value is an estimate of what the car is worth at the end of the PCP. If you want to own the car, you have to pay it.
The positive element of this for the customer is that they don't have to pay it, and the GMFV is usually set low enough so there is some small cushion between it and the true market value. So the customer gets a little bit of equity to play with.
Re the builders and the housing market. There is a shortage of housing of a certain type - social housing and affordable housing. That's where the building needs to be. This shortage is being used as an excuse by builders to build all other sorts of housing. The argument for scrapping the Help-to-Buy scheme is that it distorts the very market that it's supposed to be helping people to enter and it seems that the Government understands this. But that's not the only way in which the market is currently distorted. A couple of weeks ago, the Investors Chronicle published ten ways to create a housing shortage - draw your own conclusions!
https://www.investorschronicle.co.uk/comment/2017/07/16/blueprint-for-a-housing-shortage/
Adding to the 'have you heard' and 'what do you think' element of this very useful part of Stockopedia!
Strix are intending to have an IPO on AIM with trading expected to start next Tues, 8th at 0800. They are a kettle sarefty control giant HQ in the Isle of Man, been herhe for many years.Placing 190m shares at 100p, not surprisingly expeting to raise £190m!Ticker will be KETL; Zeus Capital are the NOMAD.Established in 1982 and taken to worldwide prominence by entrepreneur Eddie Davies (also former owner of Bolton Wanderers FC). Hopefully a better investment - in Strix - than in the FC! Apparently strong institutional demand shown already.
Any thoughts Paul or Graham, or others?
More details at http://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/other/13312342.html
Strix could be interesting. Looks like a global leader in this space, and I'd expect the demand for kettles to stay constant or increase slightly going forward - certainly recession proof. However, that may be the issue - where is the growth going to come from unless they are really going to diversify.
Having said that with an MCap of 190M, the PER is around 8-9x. It's been around for more than 50 years so has a long track record. It could be a nice boring stock to put in an ISA/SIPP and sit on. It does say they plan to have 7% dividend. That's nice, but I am a little wary of new issues promising high dividends.
Will take another look on Tuesday.
Re KETL. Where did you get the financial information please?
Re KETL. Sorry, just found this myself, thank you.
I've only found some basic information in the original intention to float RNS - https://www.investegate.co.uk/strix-group-plc/rns/intention-to-float-on-aim/201707250900019875L/
I couldn't find anything at all on the company website. As it's a private company, there should be more information at 'Companies House' but I've not looked there yet - will take a quick look on Monday.
It's a Manx company so there will be nothing much at Companies House. Which also means you won't find too much in the Companies Registry in the Isle of Man! However, this is a very highly regarded business in the Island and I'm sure the shares will race ahead on commencement of trading. I wish I'd been able to get in on the placing! That 7% yield is very enticing.
If "On the Market" is controlled by agents, then presumably the business direction would be to undercut Zoopla & Right Move fees, to grow the business and leave more money with the agents. Therefore less money for the shareholders.
I don't see how that can be in shareholders interests. Furthermore, I wouldn't want to be a minority shareholder in a business controlled by estate agents.
I suppose it is also good timing for them to float off a proportion of the business before interest rates go up.
Sorry, another 'has anyone' type post.... does anyone have a view on the AIM admission today of GETB? It's pretty small in terms of revenue, and disappointing there are no historic profit figures in the announcement... although perhaps that is difficult to ascertain from the pre-demerged entity.
GetBusy, based in Cambridge, UK, has been formed by the demerger of the document management software business and assets of Reckon Limited ("Reckon"), an ASX listed technology group......
Two document management software products, "SmartVault" and "Virtual Cabinet", have seen encouraging growth rates amongst their target customer bases, which are SMEs and larger organisations in the Enterprise Content Market ("ECM") respectively. In order to capitalise on the market opportunity, it was decided that these products would be best served in a separate business entity that did not have the same organisational restrictions as Reckon. The Directors believe that Admission will position GetBusy for its next stage of development, further raising the profile of the Group in its core markets...... etc
Growth Opportunity
The need to manage digital data and hard copy documents is a significant challenge for businesses using traditional digital storage and retrieval methods in standard computer operating systems. These systems are typically cumbersome, slow, insecure and lack a standardised approach.....
The Group's core SmartVault and Virtual Cabinet software products seek to address the potential for information chaos by optimising the capture, management, preservation and delivery for each individual document in the business. These products are already well established with over 51,000 individual customers across the UK, USA, Australia and New Zealand and more than 617,000 users registered to share documents on the online portals.
Aggregate sales for both products in 2016 totalled approximately £8.0 million (2015: £6.8 million) with subscription revenue accelerating by 21 per cent. during the period to £6.5 million, or 82 per cent. of total revenue in 2016, highlighting the increasing levels of visibility due to its subscription based revenue model. The UK currently accounts for the majority of sales at £4.9 million in 2016, followed by £2.3 million from the US and £0.9 million across Australia and New Zealand.
Significant Market Opportunity
Wasted time dealing with information issues are estimated to cost organisations c.US$19,732 per information worker per year, amounting to a 21.3 per cent. loss in total productivity. The total addressable market for GETB is therefore significant. The total ECM market alone, excluding SMEs, was estimated to be US$5.9 billion in 2015. Whilst the SME market is underserved in terms of professional document management software currently, the Board of GetBusy believes it has innovative and disruptive technology to address this market segment, at the right price point in terms of both delivery and total cost of ownership.
Hi andrea341 - I had missed this IPO this morning so thank you for the post.
Just finished reviewing the admission document and on balance I am not keen for the following reasons.
- their latest 2016 results are not encouraging. Profit before tax and net profit have almost been wiped out, going from £1.9m to £0.2m . It's worse if you include capitalised development costs of £2.7m in 2016.
- staff costs in 2016 have nearly trebled from 2.4m to 6.8m, accounting for the steep fall in profits
- on the positive side, revenues have gone up by 57% in 2016, so they have possibly good products in SmartVault and Virtual Cabinet
- however, they have stiff competition and I cannot see any moat
Overall I am not keen on investing in a loss making IPO. The big ramp up in fixed costs in 2016 also bothers me. So all in all, not for me.
Thanks Ramridge - it's obvious now why they only talked about revenue and not profit or costs in the RNS announcement.
It has a very wide spread, over 10% at times. I try and avoid spreads over 5% if I can.
OnTheMarket: one has to be careful about this. There are essentially three property portals in the UK: Rightmove, Zoopla, and OnTheMarket.
Rightmove is the leader in terms of listings, agents, and traffic.
Property portals work on a network effect. As a buyer, you probably don't want to sign up for all three, search all three regularly, and get spam from all three. I suspect most buyers definitely use RightMove, and then if adventurous choose either Zoopla or OnTheMarket.
Therefore it feels somewhat like a winner takes all market. Like Facebook.
Hi, I agree - it looks like two large competitors can be supported because people always want to check for an alternative, but three large competitors might be difficult to sustain over the long-run.
If I'm not mistaken, Agent's Mutual was formed to benefit the agents by creating their own portal. In essence it was designed to capture the benefit of the money the agents were spending on portal advertising. If they convert it to a plc, the arrangements between the majority (in aggregate) shareholders and the plc need to be very carefully managed. If shareholders are allowed to sell their shares in the plc, it could substantially weaken the economic linkage between the shareholders who provide the listings and the plc.
I believe that Rightmove's origins were not disimilar to this.
The other concern for Onthemarket should be PURP who will be doing similar national advertising to Rightmove, Zoopla and On the market encouraging people to go direct to their site.
As PURP build scale its going to make it more expensive (TV, above the line and search key words spend) and more difficult (PURP and Rightmove are using a lot of sophisticated technology to support their conversion / marketing) to bring traffic to their sites. The only USP Onthemarket has is unique properties that are listed by its estate agents and then only shown there and 1 other portal ... A supply model driven by estate agents is not a sustainable model if you are trying to monetise eyeballs and traffic for investors which means PURP and their big $$$ of marketing spend would need access to display their properties ... all of which cannibalizes the estate agents even further!
There are ways for niche players to get in
rightmove - where 80% of all properties will be
ReallyExpensiveHouses.com - for 1% ers
ReallyCheapHouses.com - for 10% ers
... or if you can get content that is not on Rightmove - but why would an estate agent do a deal like that?
Anyone know please why some of the housebuilders are taking a bit of a bruising this morning? PSN were down over 6% at one point, BWY less so...
I noticed this to but cannot find anything obvious other than the comments from BoE that rate rises will happen and be quicker than people might expect
A report in in trade publication Property Week cast doubt over the future of the government's "Help to Buy" scheme which is aimed at boosting home ownership among first-time buyers.
all house builders are down, but i would like to think this is a good time to top up on any you have(i hold bellway,persimmon and redrow ) and i bought some more this morning. the government are complaining theres not enough houses being built,so i can't see how there going to stop the help to buy program over night, and at the moment all building companies are in a purple patch just read any of there statements and i look forward to reading bellway next week.
I've held BWY for quite a while, was thinking of picking up some PSN as they are down more than most for some reason; their last trading update I thought was pretty good though, they are showing good margin increases, and the Stockopedia rating looks good
i think PSN would be worst hit buy the help to buy program if it were to be phased out, but still think its a good company to have in any portfolio
Thanks dfr1 and others on your comments on housing stocks; have a nice weekend :-)
I also saw this: UK interest rates may have to go up by more than the market expects in the future, Bank of England deputy governor Ben Broadbent has told the BBC.