Small Cap Value Report (5 Dec 2016) - PLA, PURP, RXB

Paul is taking a well earned break in the sun this week. Fortunately, with Paul’s help, we’ve managed to enlist Graham Neary, who is temporarily stepping in to take the reins. With Graham’s awesome analysis and the usual excellent community spirit here, it should be more or less business as usual! Thanks, Ben (at Stockopedia)
Plastics Capital (LON:PLA)
Share price: 117.5p (+0.43%)
No. shares: 35.6m
Market cap: £41.7m
Interim Results for six months ended 30 September 2016.
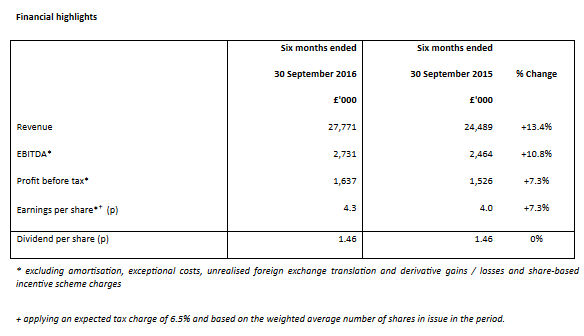
Plastics Capital is a collection of six subsidiaries, giving investors a challenge in terms of understanding each of the moving parts. But they are all related to plastic and/or packaging, so you might feel that if you understood one of them, you understood them all!
The company reports organic revenue growth of 6.7% at constant currency, and this would be my preferred measure of sales growth.
Within that, Industrial Division revenue is up 19.2%, "led by key accounts growth in bearings business". It's always worth checking for customer concentration risk when you read statements such as this! At first glance, Plastics looks to be reasonably well diversified: they sell to 80 countries and don't have any >10% customer at a group level, according to the 2016 accounts.
Those 2016 accounts remarked that the company's costs were denominated in a range of currencies, but the devaluation of Sterling still looks set to provide a healthy tailwind.
Net Debt: Increases to £15.1 million from £10.1 million during the six month period, driven by an acquisition, an internal investment program, and dividends.
Dividend: Interim dividend maintained at 1.46p. The company remarks as follows:
Because of the excellent organic growth opportunities we see, the Board now believes that our internally generated free cash flow should be allocated increasingly towards reinvestment in the business.
Outlook: Quite positive! A "healthy improvement" in the order books has been seen, and improved financial performance is anticipated for the second half. A five year plan is being executed.
My opinion: The accounts are very dirty since we have to contend with a lot of distractions from underlying performance: i) FX derivatives, ii) exceptional costs, iii) H1/H2 seasonality, iv) huge intangible assets and their associated amortisation costs, v) interest payments on the debt pile.
For the year ended March 2016, £3.8 million of net cash from operations was generated. In the latest 6-month period, £1.8 million was generated.
Compared to those figures, the enterprise value of £57 million looks quite affordable.
But is this a quality business? The balance sheet is almost as large as the enterprise value (£56 million, much of it intangible). The company's five-year plan targets EBITDA growth, and this does tend to lead to balance sheet expansion, rather than sweating profits out of a company's existing assets. In 2014, the balance sheet was just £41 million.
So based on the strategy at play here and also on the company's track record, I would suggest it's unlikely that this company will generate above-average returns on its assets for shareholders.
Purplebricks (LON:PURP)
Share price: 124p (+18%)
No. shares: 246.8m
Market cap: £306m
Interim Results for the six months ended 31 October 2016
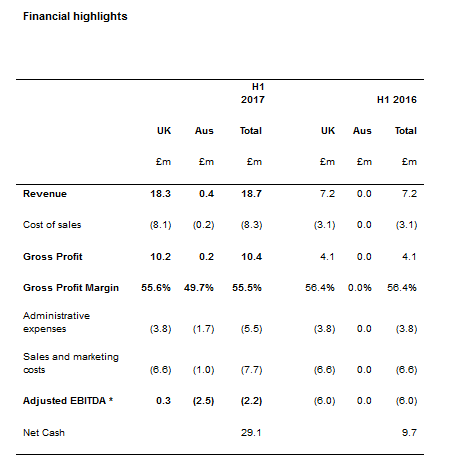
Explosive growth by this online estate agent (founded in 2014).
By taking a fresh approach to managing online sales and property advertising, they seem to be able to massively undercut traditional estate agents. Key to the customer proposition is a fixed fee.
Having listed on the market less than a year ago, the figures show that the business has more than doubled in size: revenue up 159%, instructions up 108%, and hired experts up 119%.
They claim to be "the most positively reviewed estate agent in the UK." It always helps if your customers like you!
Australia launch: an ambitious growth strategy has been launched down under, which is still in its infancy:
The launch into the £3.3bn Australian market on 28
August went smoothly. Similar to the UK, we followed a regional launch
strategy, commencing with Queensland and Victoria with a view to
extending the rollout across the country thereafter. Early indications
are very encouraging and we are growing more quickly than the UK
business at the same point in its evolution.
One thing I'd note is that revenue per customer has increased substantially over the period. This is because, on top of the flat basic fee:
There are additional charges if the customer wants
Purplebricks to undertake the viewings on their behalf, if they require
an energy performance certificate or a Rightmove premium display. The
Company's additional sources of revenue currently comprise fees from
conveyancing, mortgage referrals and insurance.
Perhaps this is a little bit like the airline strategy of getting customers on board and then asking them if they'd like to buy anything else! But it still sounds more transparent than a typical estate agent.
Loss from Operations: £2.8 million, much improved from the £6.4 million loss recorded a year ago.
Net Cash: £29.1 million, down from £30.5 million at the start of the year.
My opinion: This looks more than fully funded for growth, which is the most basic test of investability for a growth stock. I'm not surprised that the shares are sharply higher today, given the outlook statement and the prospects.
The company's market share in the non-traditional sector is now 63%. The big questions I'd be exploring here would be: assuming that Purplebricks remains the clear market leader, how much bigger and how quickly can this sector grow?
And then: how many international markets do we think the company could translate its business model to?
I like this business; whether it turns out to be a great long-term investment will hinge on the answers to these questions.
For what it's worth, Woodford Investment Management owns 29%.
Rex Bionics (LON:RXB)
Share price: 20p (+0%)
No. shares: 25.5m
Market cap: £5m
Interim Results for the six months ending 30 September 2016
This company manufactures robotic mobility devices which enable users to walk instead of using a wheelchair.
Unfortunately, previous funding rounds have failed to bring it to commercialisation. Just three units were placed during the most recent six month period (two of them sold and one of them rented out). They are said to cost about £90,000 each.
The company remains positive on the existence of a market opportunity, but having raised cash in August, it summarises its funding outlook as follows:
Additional funding will continue to be required before the end of the current financial year, but the Board remains confident that this will be forthcoming if the progress achieved in the development of the business over the last period can be maintained.
With the company remaining very far from commercialisation, I doubt that existing investors will have any ability to protect their position here.
The basic test for investability is that a company is fully funded to execute its plans. If you don't have that, you have an obligation to turn it down - if making money is your objective!
Thanks for reading. I look forward to your feedback!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Great job graham, you have big shoes to fill and you have filled them
I was blown away by all the positive comments here, thank you everyone for giving me a chance!
Good luck Paul, sounds like you are thinking Purplebricks (LON:PURP) might be the Boohoo.Com (LON:BOO) of property!!
No sign in required. It's just one of the screens that I have in my library look at from time to see if there are any updates/anything of interest.
Gus.
Hi Graham,
Love the report, well done! I see you've got 102 thumbs ups at the time of writing this, so maybe I should be looking to my laurels?!
Purplebricks (LON:PURP) looks really interesting, and I was buying right from the open this morning. It seems to me that it has reached a tipping point where its business model is clearly working. As the main disrupter in the sector (with 63% market share), I think it has a very significant opportunity in the next couple of years, to scale up significantly.
As you say in the main article, it is fully funded, with £29.1m in net cash, so there are no worries about further dilution. As it grows, then I see it throwing off cashflow to re-invest in marketing spend - that's the big barrier for newer entrants, who usually won't have the cash to compete.
I'm already seeing Purple Bricks hoardings on houses for sale, when out & about. I like the high gross margin, and the positive cashflow (getting fees up-front). The Trust Pilot reviews sound excellent too.
What's not to like? Well, in a word, valuation! The market cap looks bonkers at the moment, but growth companies are expensive right now, and this one seems to be a genuine disrupter - with fees at a fraction of the established competition, it seems to have a compelling offer for customers.
All in all, I think it looks very interesting. With doubts about the business model now banished by today's statement, I could see this one doing very well. It reminds me of Rightmove (LON:RMV) in its early days, when it looked very expensive, but ended up doing tremendously well.
Thanks for standing in for me this week, it's great to have continuity here, and I'm already feeling a lot more relaxed!
Regards, Paul.
A propos of IPOs. May I ask for help from any of the learned and experienced contributors to this valuable talk shop. Where on the web can one find a reliable and simple source of information on proposed IPOs, their prospectuses (and perhaps comments on their qualities or otherwise) and their progress in say the first year following launch. Maybe one will have to use more than 1 website but I would prefer website(s) focussed on IPOs. Thank yolu in expectaion, or at least hope!
IPO coverage tends to be a bit fragmented. By its nature, current research tends to emanate from someone with a vested interest in pushing a particular new issue. Ernst and Young do a decent quarterly review (their angle presumably being to tout for advisory work from wannabe new issuers) which gives a good summary of recent market activity. Here is the link to the latest edition from October 2016. Plenty of other useful stuff on and linked to this site.
http://www.ey.com/Publication/vwLUAssets/EY-IPO-eye-Q3-2016/$FILE/EY-IPO-Eye-Q3-2016.pdf
Best,
Gus.
Thanks a lot for that Gus. Do you sign up for this service or just check on it now and again?
I have also found out that Hargreaves Lansdown offer a service too for free e-mailing. Signed up there.
Nice work with the article Graham.
A friend used Tepilo to try and sell her London flat last year, a rival to purplebricks, paying the fee up front. What a waste of money that was! The people coming around seemed to be clueless despite the details placed on Rightmove being accurate and the photos clear. After a few months she'd just about decided to throw the towel altogether but as a last resort gave a local estate agent a go and they came up with several viewings by 'normal people' and two offers in a few days, one that came good at near the asking price - from people they knew were looking for just that kind of property. No timewasters or weirdos.
The 'online everything' argument is attractive but with these agents I wonder how many people fork out the fees but end up with either no sale, letting their property go for tens of thousands less than they could have got or end up using a traditional estate agent and have paid an extra grand on top for nothing.
I think people see someone using Purplebricks or Tepilo and as well as the usual haggling on the price they know the seller will be saving a substantial wodge of cash which they want the benefit of for themselves as well - off the asking price.
Thanks Graham, very good report...nice to read!
Interesting reading. Thanks Graham
Ditto the rest, cheers for putting in the time............
Thanks for stepping in Graham,
Rex Bionics (LON:RXB) is based in Auckland. I hope to visit in the new year and will report back here if there is any interest. The market cap is now just 50 machines and looking at it from an alternative direction there must be 50 people out there with the support (compensation?) to buy one.
Seadoc
PS I have to confess that I have a bit of a soft spot for Sophie Morgan:
http://www.youtube.com/watch?v=IR-KdnF8fYU
Thnks for the report Graham.
I hold Plastics Capital - I'd like to like them, but find myself struggling for the same reasons as others have commented.
Andy
Thanks Graham for stepping in with such a high-quality report I would just add, as comments:
Plastics Capital (LON:PLA): probably best to focus on free cash flow rather than operating cash flow to take into account ongoing investment requirements (which the company ignore by focusing on EBIDTA). The decision to increase "re-investment in the business" is clearly a turn-off for me.
Purplebricks (LON:PURP) I understand the excitement, but valuing a loss-making business by the hundreds of millions is always a tricky business, and usually a loss-making one! That segment of the market seems largely oversubscribed by people convinced they have found the next multi-bagger!
Cheers,
Thomas
You're welcome, Thomas! Nice comments.
On Plastics Capital (LON:PLA), your viewpoint is perhaps quite similar to my own. If the company buys more assets instead of reducing debt or paying dividends, then the free cash flow is lower.... and the balance sheet is bigger. So whether you are looking at free cash flow or I am looking at operational cash flow versus the size of the balance sheet, the difference between our perspectives is not so great.
Good report with your own take and style :)
Thanks for stepping in. Good report.
Three cheers for stepping up to the plate Graham.
Was starting to suffer withdrawel symptoms (actually made a start on cleaning the inside windows) so this is a very welcome alternative.
Purplebricks (LON:PURP) "I'm not surprised that the shares are sharply higher today" - but have you seen the market cap? I'd argue at this stage they are overvalued by somewhere between 300% and 600%.
Isn't this another case that one is paying for explosive growth and jam tomorrow... or whatever the phrase is?
Thanks for the report Graham.
Thanks for stepping in - a great start, in depth research and write-ups just like we're used to, but with your own slant; keep it up :-)
Hi Graham,
Thank you for your report, and welcome!
Ruth
Thank you very much!
You're very welcome!
Shoes filled very amply. Top job, Graham.
Hi Graham
Thx for filling in so ably, my issue with Plastics Capital (LON:PLA) is 2 fold, firstly the recurring nature of very substantial adjustments, what you end up with is accounting treatments that obscure the fact that the business has reduced its NAV in the period by £1.1m , not good but secondly as part of that NAV debt has risen by nearly half again over the same period!
This looks unattractive given the risks
1 Thank you for writing this.
2 To avoid any misunderstanding, should this article have a title that is different to that used by Paul Scott?
Morning!
We'll shortly be making it clear at the top of the report (I don't want to go editing Graham's work - he's got enough to worry about without me deleting his copy)...
Paul's away this week, but with his help we've managed to get Graham to fill in. So, he's a guest editor this week. It's not an easy task, so I'm sure he'd be grateful for some community support!
Cheers, Ben