Small Cap Value Report (5 Feb 2014) - UTW, WLF, FCCN

Good morning. I've come down with a cold overnight, so feel pretty ropey this morning, so will do as much as I can then go back to bed. Luckily it's very quiet for announcements anyway.
Utilitywise (LON:UTW)
This company is a utility consultant for businesses, so think along the lines of a more sophisticaed price comparison service. It is paid commissions by the energy companies, and the arrangement works because they generate savings for the clients, thus incentivising people to use this service. I know this space reasonably well, having used a similar company for years in my days as a retailing FD.
We saw the company present at a Mello Central investor evening a while ago (late 2012 I think?), when the shares were well under a quid each. I liked the concept, but the Director who presented struggled with the questions asked, and some questions were really left hanging about a potential conflict of interest between the clients best interests, and UTW receiving the best commissions. Combined with massive Director selling (usually a bearish sign) - Directors sold £17m of shares at 100p! So this made me cautious about the share.
That was a mistake on my part, but an ever bigger mistake on the part of the Directors selling, as their shares would now be worth over £30m more. Ouch. Still, a £17m windfall is more than enough for anyone. The shares have since rocketed up to 288p in the past six months, and have been further helped by two substantial recent Director purchases - £337k at 204.5p, and an astonishing £3m at 260.2p. It's a different Director to the ones who sold at a quid though.
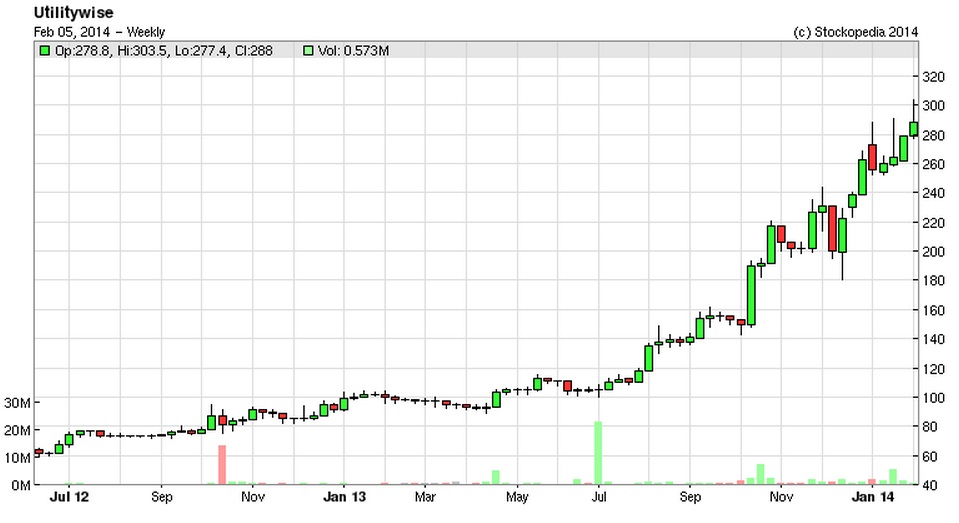
The reason I'm mentioning Utilitywise is because it has issued a trading update this morning for the six months to 31 Jan 2014. The key part says;
The Board is pleased to announce that the Company has performed slightly ahead of management expectations for both revenue and adjusted profit before tax in the period.
Figures are also given for the increase in order backlog. So it all looks positive. However, the valuation already factors in a strong performance, and with a forward PER of 20, and a dividend yield of only 1.6%, it's not of interest to me.
My worry is that it would only take a change of policy or practice by the energy companies to kill off this lucrative niche. In my experience when any part of a supply chain is making hefty profits, sooner or later people notice, and they get squeezed. And/or competitors spring up. So the shares have been a remarkably good performer, but it's not something I would consider at this valuation now.
Wolfson Microelectronics (LON:WLF)
I've never reported on Wolfson Microelectronics before, as I don't understand the business, or the sector, hence thought that any amateurish comments from me wouldn't add any value!
However, it's begun to twitch away on my radar because the shares have come down a lot, and on skimming over their figures today, the Balance Sheet looks pretty solid, and I am very struck by the huge amount they are spending on R&D, which is being expensed through the P&L.
Generally I've found that businesses spending very large amounts of turnover on R&D can be strong long-term performers, when the fruits of that spending come to market.
That said, the figures they report today (in US dollars) for Q4 and 2013 as a whole, look pretty grim. Q4 revenue fell from $56.1m last year to $42.0m this year. That generated an underlying loss of $4.5m (versus a $1.5m profit in Q4 2012). Annualised cost savings of $10m are planned, so that would have reduced the Q4 underlying loss to $2.5m, still not great but hardly disastrous.
Overall for 2013 turnover was slightly down at $179.4m, gross margins fell from 46.9% to 42.3% (not a good sign), and their underlying operating loss widened from $2.9m to $12.6m. Cash has fallen sharply, from $48m at end 2012 to $25.9m at end 2013. So they're not in the last chance saloon, but if I were the FD, I'd be getting concerned about cash burn. Although a $25m working capital facility has been agreed recently.
The outlook comments sound positive, re new products, etc, and increasing margins, but refer to;
A lower cost base, coupled with expected improvements in gross margin and a return to revenue growth, support a determined push to full year profitability.
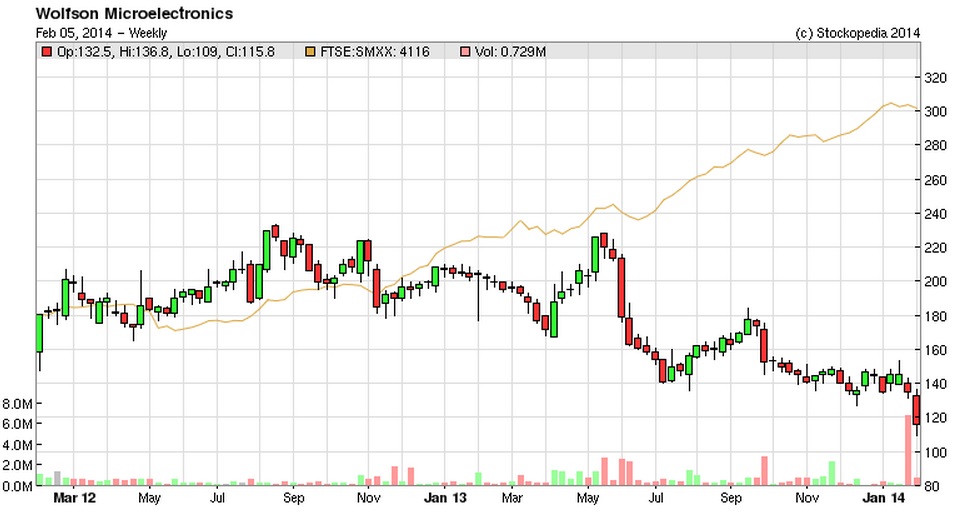
So that doesn't sound too good - a business that will be struggling to even get to breakeven by the sounds of it. The market cap is still pretty hefty, at about £129m, after this morning's 15% share price fall to 111p.
The company has been highly profitable in the past, but has struggled for the last four years, bleeding cash. Although the R&D expense jumps out at me - they spent an astonishing 30% of turnover on R&D in 2013, being $54.2m. If that is genuine R&D that is likely to product future blockbuster products, then this could be potentially interesting. If however it is just internal costs that they happen to call R&D, and are necessary to run the business as it stands now, then the picture is far from rosy.
As you can see, the shares have seriously under-performed the small caps index in the last two years;
Overall, I welcome readers comments, from people who know this company & the sector. I'm not tempted to buy any yet, but it's going on my watch list as something that needs more research on the products, sector, and outlook.
There was an interesting article I linked to on Twitter last night (@paulypilot) which demonstrated how about 1 in 6 shares that drop below 90% off their all time high, go on to be >5 baggers in the next five years. That feels subjectively right to me, as I've also done very well on some really bombed out stocks in the past, but it is very much a case of looking for a needle in a haystack. Buying the right stocks when sentiment is really bombed out, can be massively profitable, if you side-step the ones that go bust.
French Connection (LON:FCCN)
Late update: Fashion chain French Connection has issued a trading update intra-day, which is a bit annoying - 7am trading statements are always best, as people then have time to digest, and a level playing field to react. Whereas putting out an announcement randomly during the day gives an unfair advantage to those of us who are sitting at a screen most of the day.
Everyone knows that FCCN has been struggling for a while, but their trading over the key Dec and Jan period was better than expected (both sales and margin), and they say the wholesale forward order book is strong.
The loss for the year is now expected to be £4.7m (prior year £7.2m loss), so that's an improvement, although obviously still poor, being a loss. Broker consensus was for a loss of £5.75m, so they recouped just over a million of that in the busy Christmas & January Sales period.
It ended the year with net cash of £27m, only slightly down on the £28.5m reported a year earlier, which is most encouraging in my view. My main worry with this stock (which I hold) was that their trading losses would worsen, and the cash pile would burn up. That's clearly not happening, so the share price has reacted positively today, up about 19% to 42.75p, which looks a sensible reaction to me.
They clearly still have a lot of work to do in turning the group around, but have at least stopped & begun reversing the decline in trading. So overall I'm satisfied with that, and will continue holding.
The longer term potential here is very significant, because the wholesale, overseas, and licensing divisions are nicely profitable. So if they can gradually downside the heavily loss-making UK/Europe retail division, by handing back shop leases as they expire, then the problem part of the business should gradually shrink.
Everyone says lots of bearish stuff about the company, which people have been saying for years. The reality is that FCCN has a niche, they just need to up their game, which I think they are beginning to do. The market cap of £40m after today's rise leaves plenty of upside potential if they turn it around, and is supported by a remarkably strong Balance Sheet with £27m in net cash (at the seasonal peak of end Jan).
I'm not wedded to this stock at all, and would ditch it without hesitation if they had reported disappointing trading. As it is, there's everything still to play for. As someone pointed out on Twitter, the trading statement today means that H2 was actually profitable. So if they manage to deliver an improved H1 this year, nearer to breakeven, then 2014/15 could even eke out a small profit hopefully?
As it's loss-making, and doesn't pay a dividend, you can't value it on conventional methods. My view is that with trading back in the black (hopefully) fairly soon, then the value of this internationally recognised brand could be substantially more than the £40m market cap. If they really hit the spot with fashion trends, celebrity endorsements,etc (which they already get a lot of), then it has potential to be multiples of the current valuation. No guarantee that will happen of course, but it's interesting potential. Mid to high end brands can end up commanding crazy valuations.
This really is a very quiet day indeed for newsflow - I've just checked another newsfeed to make sure that mine is working! I suppose it makes up for me writing War & Peace on busy days, and is very welcome today as I'm under the weather (quite literally, it's blowing a gale here in Hove).
It's nice to see some confidence returning in smaller caps - plenty of blue on my monitor this morning. Buying the dips with cash held on the sidelines has proved an excellent strategy in recent months, and I shall very much continue that approach - so top-slicing or selling things that become fully valued, then waiting for dips to buy things at attractive valuations. The beauty of this strategy is that you should usually be positioned correctly in the event of market downturns - which happen when stocks are expensive, so a Value investor won't tend to have much money in the market when it is over-priced & hence due a fall.
See you tomorrow! - Thursday morning reports are on time now, as I'm on the wagon until 31 Mar 2014.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
Thanks folks. As an aside it is good to see that HL have backed down on the proposed change to investment trust charges.
Just worth noting that IWeb is owned by Halifax Share Dealing, which is owned by Lloyds, so from the point of view of spreading money around to be protected in the event of anything going wrong, these would be lumped together as one for the purpose of compensation.
I've been using IWeb for just under a year for accounts I run for my mother - and it seems pretty good. With the current repricing following RDR, i was concerned they might increase charges significantly, but their recent revision affects Funds only - and I don't hold Funds.
I'm just moving one of my Alliance Trust accounts to IWeb on the back of my experience - and because ATS are very expensive for the account in question - and are offering a free transfer. I have a feeling IWeb charge for Corporate actions - but nowhere near as much as ATS used to. The ATS fee could be played to ones advantage - for relatively small tender offers / rights issues, lots of their clients didn't take up their allocation on cost grounds.... I did very well out of this, especially as I hold several liquidating Investment Trusts. Never mind, all good things come to an end!
Hi Paul, sorry to hear you're under the weather. A good drink should help - but think you're still being good?!
Back to WLF. I've held them on and off for years (no current position as they've always lost me money). Their fortunes started to turn when they lost apple as a key customer; the shares have really treaded water ever since.
Their core competence is audio chips; which I understand they are good at making, but the market is ultra competitive, and WLF always bang on about limited order visibility
Basically the rate of change of phones and consumer audio is so quick, technology makes inventory obsolete faster than Zara can turn its stock around so unless you can leverage your (protected) ip, and licence rather than produce etc it's incredibly difficult to make money unless you happen to be in the 'it' product of the moment.
That's not to say there could be value tucked away in WLF at some stage...
Andrew
For a straightforward ISA account dealing in UK equity you may wish to try IWEB. It’s quite basic with a very reasonable dealing charge of £5. The prices quoted seem to be as competitive as other online brokers and I have always been able to trade.
You might also consider IDEALING and TDW. TDW has access to more exchanges but for some reason I dislike the user interface. IDEALING has been around for a few years and always served me well.
I have also used HL and Selftrade. I had a rather disappointing experience with Selftrade who appointed a new compliance team and in my view treated long standing customers quite badly with endless requests for information. I couldn’t really recommend them.
If you are looking for some financial diversification on both equity and temporary cash balances - then you should also check which bank holds the client’s money. For instance, I think from memory that TDW has its client bank based in the Netherlands whilst I would guess that IWEB might be Lloyds.
Thanks, iWeb was on my list. I left TDW a few years ago for similar reasons. Charles Stanley Direct looks interesting too.
Paul, thanks for your great reviews. Been a member for about 3 months now I think and have recovered my subscription many, many times over thanks to Stockopedia and your goodself. Other commentators "on the firm" provide excellent reading too. Do you or anyone else reading have any views on the various online brokers? Currently use HL (ISA), Alliance Trust Savings (SIPP and ISA) and Selftrade (Trading) but will need to open a fresh account for the forthcoming new ISA year as I am well over the FCA compenastion limits on my existing accounts. This is for a share ISA - no funds. Service is top priority for me. Hope everyone is ok with this weather - I am near Dawlish in glorious South Devon (well it is in the summer!)... you might have seen it on the news today.
Hi Paul,
Thanks for today's update - sorry to hear you're unwell : this ISN'T supposed to happen to people who've been virtuously 'on the wagon' since Xmas ?
Hope it doesn't interfere with your 1/2 marathon preparations : which one is/was it - and do you have a charity you're running for ?
ATB
extrader
On Wolfson Microelectronics (LON:WLF), I would think R&D really is R&D, because there's not much else engineers in such a company can do -- the actual production of chips is outsourced. Whether products that sell come out of it is anyone's guess, but I find it likely enough to be long. It's relatively cheap by semiconductors industry standards.
Hi Paul,
Any reason you think LON:CAP have been falling recently? No news has come out I'm aware of.
Cheers
Wow, what a shocker that has been since it reached the heady heights of 14p last August on the back of the Russian Abramovich connection, around 6.5p now and seems to have dropped like a stone. Market maker shakeout? For those that bought at 12 to 14p they must be wondering where this bull market is everyone is talking about. Market cap was around £15million before today, about the price of a Chelsea reserve, perhaps investors should give Roman a bell and ask him to bid for it.
Paul,
Interested to know if you saw any Companies worthy of comment at the show yesterday. Sadly I couldn't get there.
regards
Johh
Hi Paul, re your 1 in 6 article, if you look at the whole FT 350 and see how many 5 baggers there are over time, it's 9 over the last 5 years, 26 over the last 4 and 6 over the last 3 years, so maybe this is just the statistics of going through the crash in 2008.
Rgds
PS: avid reader of your column though!