Small Cap Value Report (5 Feb 2016) - LAKE, OTB, DSG

Good morning!
Quiet today, as usual on a Friday, so I'll comment on a couple of news items from yesterday too, that I missed.
Lakehouse (LON:LAKE)
Share price: 40p (up 13.5% today)
No. shares: 157.5m
Market cap: £63.0m
(at the time of writing, I hold a long position in this share)
Director buying - 4 Directors of Lakehouse conducted apparently orchestrated (as same quantity & price) buying of shares yesterday, at 35p. A total of £100k, or £25k each.
Personally, I'm not a fan of orchestrated Director buying, as it looks bad to my mind - with the main motivation presumably being to send a PR signal to the market. Anyway, it doesn't really matter what I think, because it's what works that matters, and today's announcement has certainly triggered a significant bounce in the share price after heavy recent falls. up 13.5% today, at the time of writing.
I reported on the company's shock profit warning in Monday's SCVR, here. At first my view was fairly scathing, as indeed was the market, crushing the shares by 54% at the time. However, as I updated Monday's article in the afternoon, to reflect a Peel Hunt note which suggested that the market reaction was overdone, and that it could be a buying opportunity. You might quip "well they would say that, wouldn't they!", since this was the broker that floated Lakehouse in the first place, and now has egg on its face, and probably some very unhappy clients.
Having said that, personally I really rate PH research - it's usually very good indeed, so worth sitting up & taking notice of.
Hence I did pick up a medium-sized position in Lakehouse earlier this week, and wonder if the Director buys announced today might support the share? It has done in the short term, but we'll have to wait and see if the sellers are done yet? I've been looking out for TR1 form announcements, to see what the major shareholders are doing (i.e. buying or selling), but so far there haven't been any. Therefore we can only really gauge market sentiment from the share price.
If PH are anywhere near right, that the company will do 9.9p EPS this year, then the shares probably won't stick around on a PER of 4 for very long. Personally I think there's scope for this share to rise to say 60-70p in the coming months, which would be a very nice return from 40p, providing existing big shareholders are happy to give management the benefit of the doubt.
The downside risk is that big shareholders now want out, and could drip-feed stock into the market thus depressing the share price for perhaps a long time? There's no one-size-fits-all rule after profit warnings - the subsequent price action depends entirely on the balance of buyers & sellers in the market, says he stating the obvious!
It's always very uncomfortable buying shares after a profit warning, but I ask myself one key question - are the problems transitory & fixable? I'm not entirely sure with Lakehouse, but am leaning towards that probably being the case. Therefore it's one I'm prepared to take a punt on. As always though, this is just my personal opinion, and includes an element of guesswork at this stage, as we're trying to predict an uncertain future.
On the Beach (LON:OTB)
Share price: 295p (down 3.4% today)
No. shares: 130.4m
Market cap: £384.7m
AGM Trading update - this online travel company has a 30 Sep year end, so today's update covers the first 4 months of the y/e 30 Sep 2016. Clearly it has disappointed the market a little, as the shares are down 6% today.
I did a review of the company's IPO here on 9 Dec 2015, concluding that the shares looked quite attractive at 180p. It's since shot up 64%, so am annoyed that I dithered too long, and didn't actually buy any.
Back to today's update. It gives some background, but the key figure is that UK revenue is up 26% year-on-year, so clearly that's good growth, and seems to be slightly above broker consensus turnover growth for the full year of 25.8%. There's a bit of international growth, but it's mainly a UK website at the moment.
As regards profitability, it's a tad annoying that the company refers to management expectations, when they could surely have not introduced doubt by referring to market expectations?
"On the Beach continues to efficiently execute its strategy. The Board believes that the Group is well positioned to continue generating attractive levels of growth and therefore remains confident in meeting management's full year expectations."
Valuation - broker consensus is for 12.4p EPS this year, which means the PER is 23.8, which is clearly rather expensive. However, brokers are forecasting a substantial increase in next year's EPS, to 18.1p, so providing the company executes well and meets that forecast, then the PER next year would drop to 16.3, a more palatable level.
My opinion - the company seems to be performing well, and the share price looks up with events in my view. Before being prepared to chase the share price any higher, personally I would want to see much more credible overseas expansion. So far, the company seems to only be dipping its toe into Scandinavian markets.
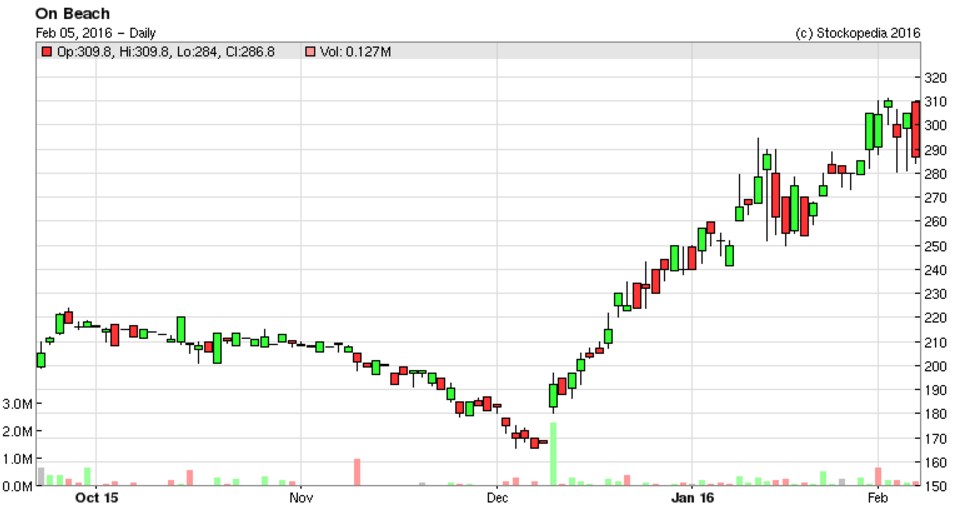
Looking at this chart, and thinking about the rather warm valuation, personally I would be banking some profits at this stage - as it's had a very nice re-rating in the last few months - probably justified, but can it continue at the same rate? I doubt it.
Dillistone (LON:DSG)
Share price: 73.5p
No. shares: 19.7m
Market cap: £14.5m
Trading update - this sounds quite solid;
We are pleased to confirm that pre-tax profits before acquisition related items are expected to be in line with market expectations. The Group is expecting to report an increase in revenue approaching 10%, with both divisions delivering organic growth. Product development has continued to be a priority throughout 2015 with a number of upgrades and new product launches successfully achieved and more expected in 2016.
The Group has enjoyed a promising start to the year with new business order levels in January up on those seen in the previous two years in both divisions. In addition, the Group has a strong prospect pipeline. As a result, the Board is optimistic about making further progress in 2016.
However it is also mindful of wider economic influences and their potential to impact on the performance of the business. The Group remains profitable and cash generative and continues to follow a progressive dividend policy, subject to the needs of the business.
My opinion - quite a nice business, and the dividend yield is particularly attractive.
However, the shares can be a bit of a lobster pot investment - easy to get into, but difficult to exit from. The spread can be prohibitive too, so it's easy to lose all of the first year's divi just on the bid/offer spread, which means that it's only worth buying for the dividend yield if you're happy to hold for years. Arguably it makes more sense to go for a large cap, if you want good divis, as at least there the cost of changing your mind is minimal.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Re "Lakehouse - LAKE", management is solid from my research. I would believe they took that 100K buy action to inject confidence. I think worth buying and holding for a while - the business is good.
Now all we need is a nice write up on ALY, it deserves it imho!
Re LAKE : there were a good few monster sell orders on Monday and early Tuesday of 450-700K sizes which I'd imagine were not PIs. Might suggest that Lake was dumped PDQ and not dripped. The price action was pretty catastrophic : a good example of technical selling since there were tons of AT sells on the order book as well which suggest stops being hit and the inevitable cascading that then occurs in price action
The consolidating and quiet accumulation that followed looks consistent with a recovery move. I took a trading position into the supporting volume profile Today's break-out was a nice vindication of this . The co-ordinated DDs is a bonus tho I am no fan of cheerleading moves either. I reckon we should see 60p as well so will hold for that. There's a huge gap at 65-85p which I will steer clear of.
dscollard re LAKE
Those 'monster' share sales at the start of this week can only have been made by private investors.
After all, a 450,000 shareholding was worth less than £160,000 earlier this week.. if this had been a 3% shareholding of an institution, it would imply AuM of just £5m (160,000/0.03)... unlikely.. even if the 450,000 had been a small chunk of a larger holding.
Moreover, 25 years of experience within asset management has led me to the observation that large institutional shareholders don't sell immediately after results. Instead:
.. they deliberate,
.. they ponder,
.. they enter denial,
.. they then seek judgement through a committee
.. then, some time later..
.. they choose to either buy or sell.
The immediate activity post any announcement is that of hedge funds, private investors & market-makers realigning their books.
In conclusion, any institutional selling of this stock has yet to happen!
indeed you may well be right:though given the average volume of trades for an entire day for Lake was around 150K then on a relative basis trades multiple trades of 400k to 700K are fairly enormous. That they were multiple is also significant. of the 158m shares in issues most of the big holdings are individual directors...
I'll follow the data and let the price action lead
Agreed, always follow the data rather than subjective emotion!
The data says: volume picks up around results days.. which has occurred here.
The data says: (as mentioned by Paul) The Directors have been buying (not selling?)
Good luck with this one.. things should work out OK
The 3% is of the company ,eg Lakehouse, and nothing to do with AuM ?
Paul, Since its quiet... French Connection is doing well again today, I think you mentioned that you were "backing up the truck" when it was about half current price, so, congratulations. Investors Chronicle tipping it this morning as a Bargain Share as well, so there seems to be a groundswell of positive opinion. Results I think come in March and I have the feeling that whatever those are, there will be a sharp movement in price.. mkt is expecting something good - if it is good they could fly, it if is less than good could bomb again. Any thoughts?
Another curious one is that Somero price has drifted again even though a couple of weeks ago everyone seemed to be talking about it
Lobster pot, like it! I've been in one or two lobster pots in the past.
Somero - someone seemed to dump 30,000 shares early this morning in partial lots. I bought a few more on the back of it.
Richard