Small Cap Value Report (5 Jun 2015) - CCT, SCS

Good morning!
Being Friday, it's quiet for news, especially so today, with very little of interest in my section of the market. That's useful, as I'm busy in meetings all afternoon. So I won't have time to do a YouTube video today, sorry about that - also no point, when there's no material.
Character (LON:CCT)
Share price: 435p
No. shares: 20.8m
Market Cap: £90.5m
(at the time of writing, I hold a long position in this share)
Director sale - I thought that yesterday's price weakness in this share was just a bit of profit-taking. However, it's more likely a bit of flipping (for an instant profit) from people who bought some stock from the Chairman in a secondary placing.
This is nothing to worry about, as the Chairman has had the stated aim of selling down his shareholding gradually for some time, and is doing so in an orderly fashion.
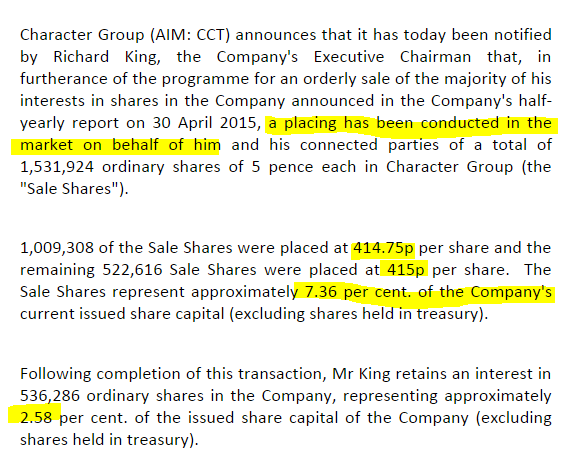
My opinion - it's pleasing to see that there was demand for 7.36% of the company, With this overhang now pretty much cleared, I am hopeful that the shares might make new highs - IF the newsflow continues to be strong.
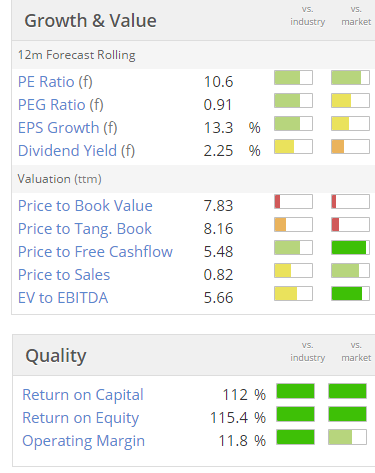
The valuation looks reasonable still, and note that this is one of the top ranked Stockopedia shares, with a StockRank of 98.
Director Remuneration - some readers have crticised the company for excessive management bonuses, and I think that's a perfectly valid criticism. Here is the Director remuneration table from the last Annual Report, where you can see that Director pay was pretty bonkers for what is still a smallish company (although note that they didn't get any bonuses the year before);
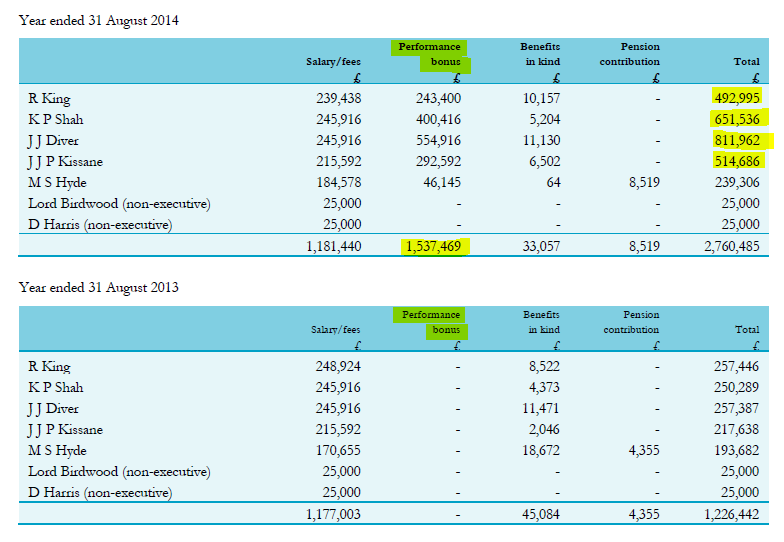
From my point of view, do I really want to cut off my nose, to spite my face? No. The shares have been a terrific investment in the last 8 or 9 months since I flagged it here (several times), and bought some myself. Therefore I can live with the Directors having a bit of a feeding frenzy too, even though bonuses of this size seem excessive.
A cap of about 50% of salary should I think become best practice for performance bonuses. Anything above that is rewarding people excessively for just doing their job, in my view. Often overly generous bonus schemes incentivise management to make bad decisions to chase short term personal gains too.
A few tweaks are needed to company law, to make remuneration votes by shareholders legally binding, and to give all shareholders (including those held via a nominee) an automatic electronic vote on AGM resolutions. If those two changes were made, then I think the ownership class would rein in the managerial class's excesses.
Although Directors are also big shareholders at CCT, which gives more scope for them to award themselves generous packages.
Bottom line for me, is that if I'm making a 100%+ profit on my shares in under a year, as is the case here, then I can live with overly generous management bonuses for the time being!
Bellway (LON:BWY)
Interim Management Statement - with a £2.9bn market cap, this is a giant company to me! The only reason I mention it is because, if I can find the time, I always find it worthwhile to read the market and outlook comments from the big housebuilders - as these are a very good barometer about consumer confidence, and the general outlook for the UK economy.
Do you remember how SCS (LON:SCS) blamed the General Election uncertainty for the slump in sales of sofas, causing them to warn on profits? At the time I remember commenting that this was a fairly ludicrous idea, and that is reinforced today by Bellway saying the following:
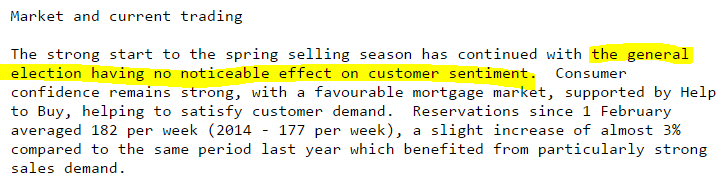
So people will happily spend £250k on a house, regardless of the General Election, but deferred the purchase of a sofa because they were worried about Ed Milband running the country! It just shows what utter tosh is put into trading updates sometimes.
This got me thinking though. Back in my days as a retailing FD, whenever sales dropped, the excuses given internally were nearly always weather-related. I can't remember ever hearing Area Managers saying that the product wasn't good enough - they didn't dare, as the Buyers would have ripped them to shreds! Or they might tell me in confidence that the product was no good, in hushed tones over a traditional English breakfast (a coffee & a fag!) outside the office, but they didn't dare say so in management meetings.
So perhaps companies on the stock market believe their own excuses when they under-perform too?
Well, apologies for today's report being so threadbare, there just wasn't any interesting news in my sphere.
Have a super weekend, and see you back here on Monday morning!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in CCT, and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
A few tweaks are needed to company law, to make remuneration votes by shareholders legally binding
Not sure about that - especially since they now are - no payment can be made outside of the declared policy, with the directors collectively holding responsibility (and a duty to pay back) in the event that this is breeched.
Character looks agreat company - but why is Richard King selling if they have a lot further to run? Director sales bug me where the company looks so attractively an investment.
I want directors to be greedy for shares - if they see potential share price gains they would surely be reluctant sellers indeed?
This is company statement: "Richard King, the Company's Executive Chairman that, in furtherance of the programme for an orderly sale of the majority of his interests in shares in the Company announced in the Company's half-yearly report on 30 April 2015,"
OK further to that I have just read the report it says he is nearly 70 and this sale is for his retirement.
Still remember the Starwars Episode ! debacle, which destroyed much value and took the company close to folding. It's to the credit of the management that they bougght the company back. However it shows how a few bad deals/licences, and poorly judged toys can effect the company. If the md is happy to sell 2/3 of his shares (£6M) at this price, while earning half a million a year, it's maybe not the best time to buy in risk/reward time.
What do I know though ? I didn't buy in when you flagged it up at 200p or so !
well done to those who traded this, I would be very tempted to topslice myself !!
K
Hmm... Maybe SCS (LON:SCS) 's slump in the sales of sofas signifies a lack of anything good on telly lately. Which in turn leads the shrewd trader to consider shorting Entertainment One (LON:ETO). I'll ask ShareProphets to get in on the act, pronto.
We're going to be rich I tell you! Rich!
Hi Paul,
Interesting to hear you say that you (and Bellway) think uncertainty regarding the general election is "utter tosh"!
I'm in the process of trying to buy a house in London at the moment and pretty much every estate agent I've met has said there was a noticeable slow-down in the 2-3 months prior to the election and a dramatic pick-up immediately afterwards.
Chris
London is one of many housing markets in the UK. Bellway is supported by direct government subsidy (HTB1).
Paul, Re CCT, I am fairly sure that a glowing rec from Simon Thompson played its part on both his Monday report which caused a 10% jump the next day as well as being published in today's IC....
Hi danyou,
Indeed it did. I mentioned Simon Thompson's article on Character (LON:CCT) in my video on Monday this week.
It's always tempting to top-slice when he tips something I hold, as the spikes can often be short-lived, but I decided not to top slice CCT, as I think the shares still look good value, and there could be more upside from new product ranges.
The main risk with CCT is that the end customers (kids) are fickle, so their products could go out of fashion. Although they seem to have a good bedrock now of core products which seem to be enduring. Also the Teletubbies are coming back apparently, and CCT are making a range for that.
It's so difficult deciding when to sell, but with CCT I have a feeling in my bones that it has the potential to go a lot higher, IF and only if the trading newsflow continues to be strong.
Regards, Paul.
As the parent of toddlers I would say that the kids themselves are not fickle. Once they latch on to Peppa pig, they are not letting go! However over the years what it is that the current batch of kids latchs onto changes.
Yeah, I'm with you on that. Peppa Pig, Ben & Holly and now Scooby Doo - I've got young kids and the interest in these things can be counted in years. And these pieces of plastic don't come cheap !