Small Cap Value Report (6 Mar 2014) - IND, CRAW, BEG

Good morning! A thoroughly enjoyable evening was had by all at FinnCap last night, for the latest Mello Central investor evening. The organiser, David Stredder, asked me to give a brief rundown of the key financials (market cap, etc) before each presentation, so I did exactly that, flagging up what to me seemed the key issues. This didn't go down too well with the presenters, one of whom muttered "Who the hell is this guy?!" to a colleague, and the rather prickly presenter from Skil Ports and Logistics (LON:SPL) said sarcastically, "This was REALLY worth flying all the way from India for!".
He seemed to take offence at my point that since the market cap was way below their own cash, then the quickest way to create shareholder value was to disband the company & return the cash to shareholders. A perfectly valid point I thought. He gave a rather unapologetic, and defensive update on the company's project to build a small port in India. What was lacking in my view was any sense of what upside shareholders might see from the port once it has been built. Still, hats off to him for coming all that way to face some tough questioning from unhappy investors.
As expected, the CEO of Cambria Automobiles (LON:CAMB) was tremendously impressive, that's clearly a well run business that's going places, so I remain very keen on that share. Must get round to buying some at some point too, I think that share will be a long-term winner.
The CEO of CityFibre Infrastructure Holdings (LON:CFHL) certainly made an impact with his enthusiastic, American delivery! I think he could sell snow to eskimos. It's not my usual cup of tea, being a loss-making growth stock, and I'm sceptical of companies that build telecomes infrastructure, since they often go bust and someone else snaps up the asset for a fraction of the original cost. However, he did make an exciting-sounding case for building high speed fibre networks in towns and cities outside London. I'd like to see more forecast figures on this one before taking the plunge, but am intrigued.
Finally, small recruitment company Servoca (LON:SVCA) gave an informative presentation. My feeling there is that having already 4-bagged in the last year, the shares now look fully valued. It's been an impressive turnaround in performance by the company though.
Indigovision (LON:IND)
This is both my largest, and longest duration shareholding, which I have held continuously since 2004.
We are now in year 3 of their 3-year turnaround plan, and it seems to be working. So interim results out today show a 33% increase in operating profit, and EPS is up 51% to 15.9p. Annualise that, and it's about 32p, so assuming H2 also delivers further growth then I would hope for 35-40p for the year. Put that on a PER of say 15-20, and a share price target of 525-800p is implied.
So you can see why the shares have jumped 60p this morning to 417.5p. The company has had false dawns before though, so it might take some time before investors trust the sustainability of improved results. The narrative gives more flavour for how they are generating growth, which is being driven by the new camera ranges, whilst the traditional video encoder business has continued declining. That decline should now reverse, as a cheaper mid-range of encoders has been launched.
I'm also encouraged by the outlook, which sounds positive, although there isn't much visibility of sales here unfortunately, that's just the nature of the business. They have a large pipeline of sales leads, but can never be sure which will convert into actual orders. It's good to see all regions delivering growth, which reassures me that their competitive position is improving, rather than having just had one-off gains from one large contract.
I usually meet the company shortly after results, so hopefully will get an update direct from the horses mouth shortly. I had intended to really read them the riot act this time if the results were no good, but thankfully that will not be necessary now, as the company has performed well.
The Balance Sheet is strong, with net cash. One thing I like with IndigoVision, which is worth flagging up as a general point, is that there have been 7.5m shares in issue all the time I've had a stake in the company. So you don't see the constant dilution that occurs at many growing companies, where new shares are thrown around like confetti. I always check the "average shares" in issue, near the bottom of the Stockopedia page for each company. So a flat or gently rising trend in number of shares in issue is favourable, as that means existing shareholders get the benefit of growth in profits, rather than being diluted from repeated new issuance of shares.
Crawshaw (LON:CRAW)
Shareholders in this small chain of butchers will be delighted with another strong trading update from the company today. Sales in January were "particularly strong", so they now expect to beat expectations which had already been raised just two months ago. It's a 31 January 2014 year end.
Current trading also sounds positive;
I am also delighted to report that strong growth has continued into the new financial year.
Broker consensus is shown on Stockopedia at 1.0p EPS for 2013/14 and 1.3p for 2014/15, so at 33p the share price is now on a high rating for a fairly unexciting business. That said, broker forecasts have turned out to be far too low in the last year, so if this strong performance continues then who knows?
I'm not entirely clear how the company is achieving this strong performance, nor whether it is sustainable, but hopefully the results will provide more details on that, and are due out at the end of April.
The company also reports that a new shop is being opened towards the end of March.
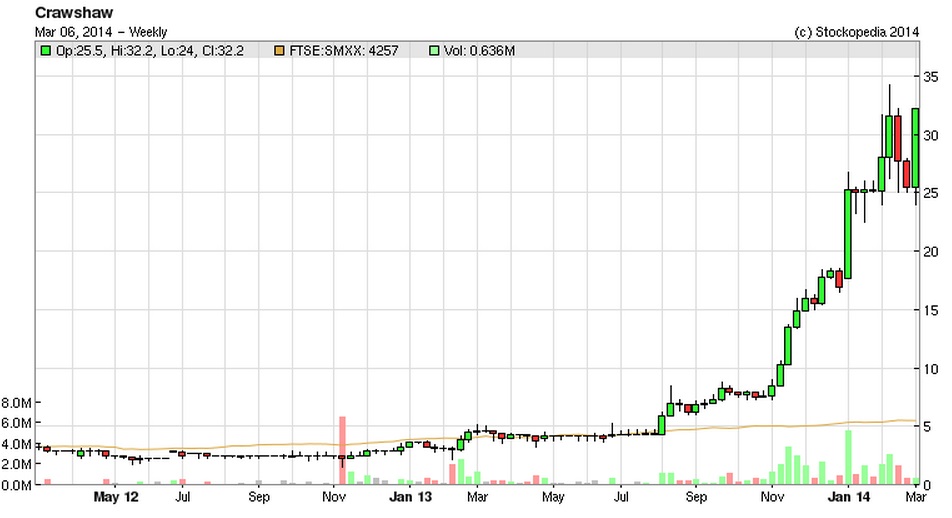
Here's their two year chart, which looks pretty amazing, but does beg the question as to how much gas there is left in the tank after such a spectacular rise?
Begbies Traynor (LON:BEG)
There's a reassuring trading update from the market's only quoted insolvency practitioner. Conditions have been very tough for several years now, due to the artificial stimulus to the economy from ultra-low interest rates, and political pressure on the Banks not to pull the plug on insolvent companies. Hence we still have many zombie companies (and households) that can just about survive by meeting low interest payments, but will probably never be able to repay their debt in full.
Hence Begbies have been forced to carry out several rounds of cost cutting in recent years as turnover and profit remained under pressure.
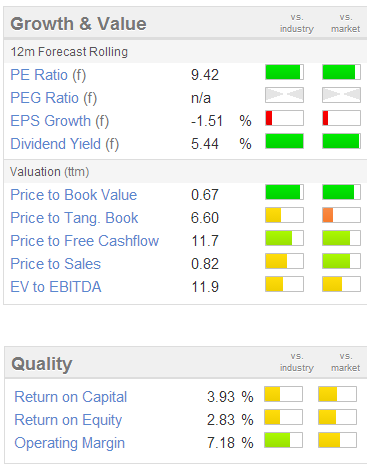
As you can see from the Stockopedia valuation graphics on the right, the PER and dividend yield are attractive.
There is a lot of bank debt, but this is necessary for insolvency practitioners, since they have to finance a very long debtor book - since fees are usually paid from asset disposals which can take a long time.
At some point corporate insolvencies will rise, as zombie companies are restructured, and that is likely to happen now the economy is improving, and bank Balance Sheets are more able to take the write-offs needed. So I am wondering if Begbies might now be over the worst?
I'll leave it there for today.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in IND and BEG, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Paul has your opinion changed at all?
Muckshifter,
Thanks for your reply.
I have read your posts on various boards over many years on multiple subjects and have always greatly appreciated them and benefitted from them. Thank you for the very considerable efforts you have made.
Kinkell
Kinkell,
Sorry if I misread your post. Perhaps I've been suffering too much abuse and deliberate misrepresentation of my posts on shft boards in "another place", and that has made me too defensive of sanity here. No offence intended.
Regards.
This is rather interesting, from p50 of the AIM Admission Document:
Cheers,
Mark
I had a quick look at SKIL accounts for 2012. The main shareholder, Mr Nikhil Gandhi, controls 28.91% of the company. He also controls another company (Grevek), to which SKIL had lent £1,732,665 as at December 2012 ("demand deposit"), up by £1,314,721 from £417,944 the previous year. It is unsecured. The interest rate is 5% per annum. However, the company had interest income in 2012 of £5,114,000 and average cash balances of £63,813,000. This suggests an average interest rate of 8.01% per annum.
It seems to me that the company is giving a 3% interest benefit (at least) to an insider. I would expect that the bulk of the remaining deposits are with relatively secure, probably regulated, institutions. A bit of a red flag if I were considering an investment here.
Bezhe
Thanks for picking up that point of which I was not aware. I certainly think it is worth following up by asking for an explanation.
Re Indigovision
Interesting comments, Paul, thank you
I noticed this in the Interim Report
'IndigoVision Group plc ("the Company") is domiciled in Scotland.'
Does anyone believe that this fact might/should influence the timing of any purchase? Regardless of whether you really believes an independence 'yes' vote is likely or not, I would have thought the uncertainty caused by the vote might provide some interesting buying opportunities in companies with perceived 'Scottishness'.
Rgds
That looks distinctly like a typical comment from "another place" Kinkell. An insinuation, intended or otherwise, that Paul's comment was intended to have an effect on the price after which - he would buy.
He said "I won't be investing" - enough said.
Insinuations are best kept on the maniacs boards.
Regards.
Muckshifter,
Certainly no such insinuation intended. I most certainly do not think that Paul operates in that way. If I did I wouldn't read his articles.
I just feel that perhaps the discussion got off on the wrong foot and the emphasis was perhaps less than it might have been on the possible strengths and weaknesses of the project. I might be wrong. As I said I wasn't there.
But it does seem to me that this is a promising potential investment and I would have liked to have seen more discussion on the project. A personality clash perhaps?
Companies are going to go bust in a capitalist market. That's necessary and of overall benefit to society, as badly run or obsolete businesses are eliminated, leaving well run businesses to serve customers.
If only there was a similar mechanism to dispose of inefficient public sector operations.
Begbies providse a valuable service to society. There is no ethical concern at all investing here.
Hi Paul -
Re. BEG. I find it difficult to get enthusiastic about a company that profits from increased corporate insolvencies. Increased misery = more profits. Definitely a candidate, together with banks, for my personal room 101 :-). I don't pretend to take the moral high ground, but it somehow goes against the grain.
Hi Ramridge,
Fair point. I also don't like investing in companies that make money from other peoples' misery. However, insolvencies need to happen, and Begbies charge about half the rates charged by the leading insolvency firms, so more money ends up going to creditors. I worked in this sector in the early 1990s, and it's more akin to legal work than anything else. To my mind it's at an acceptable level on the ethical scale for investing, but probably only just.
Regards, Paul.
Paul
Any further view on Communisis who reported prelims today?
Regards
Peter
Hi Paul,
Just wanted to add to what others have already said. You were just saying what most there last night were thinking, I had a look at my own figures for SPL in the afternoon and was glad I wasnt going crazy when you opened your presentation. Hats off to you for stating it as it was. These midweek sessions are extremely worthwhile. 8I'm not a member of ShareSoc, but I see they do similar 'member only' presentations. Is it worth while joining to get access to these evenings?
WN
For anyone whose interested in hearing an "on the ground" view from the owner/manager of the Port of Bombay regarding Skil Ports and Logistics (LON:SPL):
NB. I do not hold (and do not intend to acquire) any position in Skil Ports and Logistics (LON:SPL) , long or short
I looked at CAMB about half way up the price's vertical ascent (+160% PA) and thought its trajectory couldn't last because it has tiny op margins and yield (and trading spread of 5-10%). I was wrong again but it has gone too far up for me now.
The Skil Ports and Logistics (LON:SPL) thread on ADVFN has some excellent posts on the development and potential earnings, including some insights from posters with experience of the industry. Worth a read.
A friend from school runs the Port of Bombay. I've emailed him to get his view on Skil Ports and Logistics (LON:SPL) - will post when he replies.
Good morning Paul,
A great investor evening indeed.
Never stop being yourself, I loved your "company introductions" they were to the point. CEO's are paid very large incomes, and private investors need to know the facts, you were polite, direct and to the point.
When it is our own money at risk there is no time to be worrying about offending the well paid CEO's feelings.
Well done Paul.
Cheers Neville
Morning Neville,
Nice to see you last night, and sorry I forgot your Dad's name, how embarrassing!
I think companies are used to being introduced in a glowing fashion, so having some bloke get up and ask why they don't pay a dividend, or point out the net debt, or suggest they might like to shut down and return the cash, is probably not something they are used to!!
But why not? I find it ridiculous that some Directors expect to be treated deferentially! Why? They are paid handsomely by shareholders to do a job, so should be questioned hard on how they do it, especially if the share price weak - which is after all the market collectively judging that they are doing a bad job.
Personally I like to thoroughly explore the bear case in every investment, before buying. That way you don't usually end up with any nasty surprises. Companies usually like to present just the positives, and gloss over the negatives, so putting them in front of a sceptical and shrewd audience at Mello is a very good test of how watertight or not the investing case is.
I think CAMB passed with flying colours. Servoca wasn't bad. CityFibre sounded good, but I need to do more research before being convinced. SPL didn't convince me at all, but I can see the attraction of buying at less than cash, if you think the project will ultimately be good once built. There's so much risk investing in India though, most similar Indian property companies have been a disaster. I lost a packet on Hirco a few years ago, so when these things go to a deep discount to their supposed asset value, there's usually a good reason for that.
Regards, Paul.
Couldn't agree more Paul. All business relationships should be appreciated and treated with respect and politeness, but the fact remains that there is a hierarchy. It goes, in grossly oversimplified terms: contractor/supplier, employee, manager, board director, owner. As a shareholder you are an owner, and business executives really should remember that their elevated position within a company does not apply outside the management structure.
So keep up the good work of being 'some bloke'. Best, Kevan.
Hi Paul,
I have given you a tick for your report generally but I am very disappointed with what you have said about SPL and not in the least surprised at the presenter's reaction. Surely you know that this is a large project unfortunately delayed by Indian bureaucracy but now going ahead with all approvals in place. To suggest that they just return the cash seems to me to very simplistic and bordering on insult. I would have expected you to view the current share price as an excellent buying opportunity. Although I am very wary of all companies involved in India I do think this one has excellent prospects. I hope so anyway as a happy holder.
Hi Kinkell,
If an asset is priced way below its liquidation value, then liquidation is an option that should be considered. That is a rational thing to consider. Reacting in an emotional way, as both the presenter from Skil Ports and Logistics (LON:SPL) did, and how you also have above, is something I find very peculiar! Business is business, so there is no place for people getting flouncy when they're asked a direct, and sensible question. If they do, then it tells me that they have a weak case.
What he should have done, is explain how he is going to create more shareholder value by building the port using shareholder cash, instead of returning the cash. He didn't do that. No figures were mentioned in terms of how the port is likely to perform once it's built, and he ducked my specific question on that, just saying that he believes it will operate on a high profit margin.
So I can see why the market is currently pricing this share below the value of its own cash. Also, as I pointed out, if you factor in the depreciation of the Rupee, then £ 10m comes off the last reported cash balance, when translated into sterling. So the discount to net cash is not as great as some people think, once this has been adjusted for.
How long is it going to take to actually build this port? A long time I would guess. I was also struck with how small it is. As an attendee last night pointed out, 200 acres is not a lot of space to run a port. The images in SPL's Annual Report give the impression of this being a major port, but it's actually going to be a small unloading operation using barges. So I'd want to see detailed forecasts on how much money it is actually going to make once it's built. How else can you justify building it?!!! Yet that wasn't even touched on last night.
Regards, Paul.
Hi Paul,
Thanks for reply re SPL.
I wasn't there so may have misjudged the tone and if so I apologise.
I agree entirely about detailed questioning of CEOs.
In the case of SPL they have raised sufficient funds as I understand it to construct the port and as the work is underway I presume that they have entered into contracts to this end. Therefore it seems totally impractical to suggest that they hand the money back - apart from anything else presumably they would incur large penalties. I suggest that only people who do not know what they are doing set out on major projects and turn round half way - unless the facts change, which as far as I know have not. Reading your introduction gives me the impression that you think the directors don't know what they are doing so they should return the funds. A rather poor welcome to someone who has flown from India to give what I believe to be the company's first presentation to private investors.
Obviously your point about the currency devaluation is correct but they hold the funds in the currency they require to build the port. With the wisdom of hindsight it would have been advantageous to hold sterling or dollars but is that a valid criticism of the management? Remember the funds were raised some time ago and the delay in obtaining consents was not foreseen. Should it have been? I don't know but understand the company was caught up in a country-wide delay arising from political scandal, not as far as I am aware directly concerning this project.
You may think I am being emotional here but I can assure you that I realise I could lose my entire investment but am hopeful and reasonably confident that it will turn out well. We shall see.
I am disappointed however to learn that your questions were not adequately answered.
Hi,
Again, I think you've over-emotionalised it!
I'm not making a judgement on whether the Directors are competent or not. I'm simply saying that if the share price is well below net cash, then returning cash is the quickest way to create shareholder value.
It totally baffles me why people think that is such a complicated idea, or insulting in some way. It's just basic common sense - there are 2 options - 1) Build the port, or 2) Don't build the port, but hand the cash back. Any rational person would assess the options, and then decide on the better course of action. Emotions don't come into it at all, it's just a business decision.
Regards, Paul.
Paul,
I don't think it is an emotional matter! Its more a question of common sense.
If the company had not entered into the construction phase and therefore contractual relationships, your scheme would be perfectly feasible. I honestly don't think you are taking that factor into account.
Incidentally When you accuse me of being emotional I wonder if you are thinking I am under water in the shares. I am not an original investor in the company. My involvement is much more recent - actually at the low point of the share price. I am delighted with the recent sp improvement and am hopeful that it has much further to go. Emotion doesn't come into it.
Also as far as I know this is the company's first effort to communicate with private investors. I think that they should be encouraged especially if they travel from as far afield as India. I don't think suggesting that they stop the project and hand back the remainder of the cash in the circumstances is likely to create a favourable impression. Just my opinion.
Sure, so let's ask what the contracted costs are. Then you can make a rational decision about whether the shut-down & liquidation option makes sense or not.
I don't hold the shares, and I generally find that people who do not hold a particular share are far better & more impartial judges of that share's prospects. People who have bought the shares naturally want to protect & promote their investments, and are emotionally attached to them, something we are all guilty of.
The Skil Ports and Logistics (LON:SPL) guy did not impress me. He struck me as far too arrogant for someone who has presided over a disappointing investment to date. He wanted to impress upon us the credentials & importance of the Indians involved in this project, and seemed to be demanding respect from us, whilst failing to understand that will not cut any mustard at all with UK investors.
He hit all the wrong buttons with me, so I won't be investing. Good luck to those of you that do.
Regards, Paul.
Interesting comments, thank you.
Perhaps a less hostile beginning might have created a better climate for rational discussion?
There is a very interesting post by Mount Teide in another place (#1258).
Sorry you have missed the bottom of this one, but you may not be too late...!!!
I was impressed with the Indigovision results this morning (although I probably would not have had the patience to hold these for 10 years!). It seems that the investment the company has made in sales staff is finally paying off and also shows the value of their R&D spend, with market leading technology - which is being used across the globe by some very impressive customers. I'm not entirely sure I understand their revenue structure however. How much of the sales translates into recurring income/maintenance fees etc. which will make customers much more sticky.. I also know that Techinvest rate IND very highly and have made them one of the highest conviction buys in the 2014 portfolio. I would also like to flag IQE which has risen today because of T. Rowe Price Associates, Inc taking their holding up to 12%. IQE looks like a value situation in a growth market - semiconductor wafers. Their results are out later this month.
The bulk of Indigovision (LON:IND) revenues are of a non-recurring nature, from individual contracts for their CCTV equipment. However, they have made some progress in recent years charging software maintenance fees, which from memory I think were under 10% of revenue, but growing, and of course on a 100% margin.