Small Cap Value Report (7 July 2017) - PMP, DIS, QRT, PHD

Portmeirion (LON:PMP)
- Share price: 925p (-3.4%)
- No. of shares: 10.8 million
- Market cap: £100 million
Good morning - Graham here, and I'm kicking things off today with this homeware manufacturer and distributor.
It has a heritage dating back to the 1960s and has been listed on the stock market since 1988, so in theory that should make it a relatively safe place to invest.
2016 was difficult for it, however, as sales suffered in South Korea, India and at home in the post-referendum UK. Pre-tax profit declined from £8.6 million to £7.8 million despite the impact of a home fragrances acquisition (£17.5 million deal size).
But management insisted that the outlook for 2017 was positive, and that the challenges would be overcome. Which brings us to today's first-half update (six months to June).
PBT forecasts for the full year remain in line with market expectations:
The Group is pleased to announce that total Group sales are up 16% for the six months ended 30 June 2017 relative to the same period last year, although 2016 only included two months of Wax Lyrical sales from its acquisition in May 2016. Excluding sales from Wax Lyrical, on a translated currency basis total Group sales are 3% ahead of last year and on a constant currency basis, excluding Wax Lyrical, total Group sales are 1.9% down on last year.
1.9% like-for-like, constant currency sales shrinkage is perhaps a little disappointing, and so the share price is down a few percentage points.
Edit: Martin in the comments has helpfully pointed out that these H1 numbers are noticeably worse than numbers given for the first four months of the year in the AGM statement. So trading looks like it has softened on a comparative basis over the past two months.
As you can see from the Stocko charts below, analysts have been forecasting net profit and EPS to increase this year, after the dip in 2016, with the help of the Wax Lyrical acquisition.
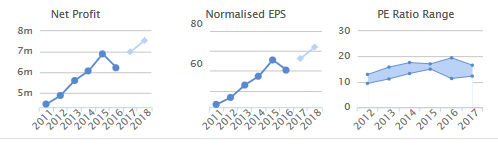
Note also the PE ratio range; so far this year, the share price has produced a PE ratio range of 12.3x to 16.6x. 2013 and 2014 had somewhat similar ranges.
The current PE ratio is just below 14x, close to the middle of the range, and with like-for-like sales growth being where it is, that seems about right.
It's not the most exciting company in the world by any means, but if the acquisition produces some decent synergies in the years ahead, I could see the share price doing well. Maybe a decent candidate for a long-term buy-and-hold.
Distil (LON:DIS)
- Share price: 2.9p (+16%)
- No. of shares 500 million
- Market cap: £14 million
This premium drinks business updates on trading in Q1 of the fiscal year (April to June).
It's a micro-cap where I've missed the boat so far this year - arguing that it "might be worth looking at" when the share price was below 1.5p!
It's arguably very early days for Distil, of course, so there are still huge gains to be had from the current levels if it succeeds.
Final results for the year ending March 2017 showed revenues and gross profits up 40%, stable margins, and the company achieved breakeven with a small operating profit. The major driver of this was domestic UK sales of RedLeg Spiced Rum. The cash balance ended at £910k, encouragingly only slightly reduced compared to the prior year.
Now that the company is in the black, at least for one year, it seems a much safer proposition, especially given the growth trajectory. Skimming the historical accounts, I see that the prior seven years were all losses! RedLeg Spiced Rum was first launched in 2012, back when Distil was known as Blavod Wines and Spirits and traded under the BES ticker.
Trading Update - that's enough history, now onto today's update. It is merely in line with expectations, but it's still very good.
Unaudited year-on-year first quarter revenues rose by 61%. Sales in this first quarter include Easter promotional sales appearing in April compared to prior year when they appeared in March. To remove this phasing imbalance, we also update the six-month performance figures to 30 June 2017; year on year revenues during this period rose 46% and volumes increased by 53%.
RedLeg has been picked up by a couple of major supermarket chains for distribution, and this is doubtless helping to drive the surge in revenues.
I can only see one commissioned analyst forecast, which suggests group sales can improve from £1.64 million to £2.1 million in the current financial year, a 28% growth rate.
As was with last year's forecasts, that appears too conservative.
It looks to me as if operating profit could be in the region of £250k this year, doing some back of the envelope calculations.
Still quite a long way to go then to reach critical mass, and to overcome its operating expenses in a meaningful way, but I remain of the view that this one is interesting!
Quarto Inc (LON:QRT)
- Share price: 170.5p (-1.2%)
- No. of shares: 20.4 million
- Market cap: £35 million
Sale of Books & Gifts Direct Limited (New Zealand)
A quick mention of this book publishing company which has recently suffered a severe share price fall and been widely discussed by investors here.
The forecast PE ratio appears minuscule but there is a lot hinging on a H2 recovery, and the PE ratio would be somewhat misleading anyway since there is over sixty million dollars of debt on the balance sheet (December 2016).
Non-core assets have been disposed of in recent times, improving the cash position and simplifying operations.
Today's disposal is small ($0.6 million, plus some debtor receipts and profit share for the next few years). The significance of it is that it moves Quarto fully away from bookselling to instead become purely focused on publishing. CEO comment:
"With the disposal of Books & Gifts Direct New Zealand - our last non-core business - Quarto starts a new chapter as a publishing-only business with a unique platform to become the dominant publisher of illustrated books worldwide. In the short-term, everyone across the Group remains focused on delivering our plans for 2017."
I am getting curious about this share, as I have the impression that it can do well having disposed of those parts of the group (the non-publishing elements) which dragged on results last year.
Net income for 2016, excluding Books and Gifts Direct (BGD), was $10.7 million, versus the current enterprise value (using $60 million net debt estimate) of $105 million.
Those odds look ok to me. Net debt has reduced from $81 million in 2012, and should reduce further now without any BGD distraction.
Proactis Holdings (LON:PHD)
- Share price: 184p (+5%)
- No. of shares: 50.2 million
- Market cap: £92 million
Proposed Acquisition, Placing and Notice of GM
A massive deal announcement, relative to its size, from this software company which helps businesses to improve their processes and manage their spending.
It is raising £70 million (gross proceeds) at 165p to make a £102.4 million ($132.5 million) acquisition of Perfect Commerce, LLC, a company operating in the same sector of spend management solutions. The rest of the funds will be coming from £45 million of new debt facilities with HSBC, and some convertible loan notes.
Perfect Commerce is said to have "complementary territorial reach" with Proactis- that's really important, because it means that the companies are not merging simply in order to stop duplicating each other's efforts in the same territories! Although there may be some element of that all the same.
The CEO of Perfect Commerce will become CEO of Proactis, and the deal qualifies as a reverse takeover.
"Significant efficiencies" are expected from the deal.
I tend to be a cynic when it comes to mergers and acquisitions. There is a lot of research out there suggesting that most of them destroy value. But I'd try to keep an open mind here. If it's true about the complementarity of their respective geographies, this could be one of the good ones.
£5 million in annualised cost savings in the enlarged group, to be achieved by July 2018, would make the £5 million one-off cost of the placing seem like a good deal.
But Perfect Commerce has been loss-making for each of the past three years according to the summary financial information provided in the RNS, though it achieved to an operating profit of $3 million last year on significantly improved revenues.
It operates an SaaS revenue model and with tech and growth-oriented valuations where they are at the moment, it is not hard to justify a $130 million market cap on $3 million of operating profit from such a business.
Even if the combined group performs well on its own terms, I think this sector as a whole is currently overvalued and therefore would stay away from this.
That's all from me for today. Have a great weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Thanks for this Howard. You would hardly expect them to offer anything but a positive spin on the deal. I certainly hope goes brilliantly, but a slice my holding went to cash this morning sweet 195p. I paid 32p so happy to bank a win. It's still my biggest holding, so will be paying close attention.
Jon
PS Synergies. A word often preceded with the expression "We thought there would be . . ." ;)
Easier to analyse and plan than deliver, in my experience.
Market volatility to come:
Jeremy Corbyn is scheduled to meet Michel Barnier, the European Union's chief negotiator next week, ahead of which the Labour leader said he was ready for snap elections.
It is understood that the meeting with Barnier on 13 July would provide Corbyn the platform to "outline what our issues are," he said in an interview with Bloomberg Television in London on Thursday.
The meeting was requested by Corbyn, according to an EU official who confirmed the meeting.
The announcement, it is believed, pointed to confidence that Corbyn - an old-school Socialist - could exploit the weakness of his Conservative rivals and come to power on a call to end austerity.
Mujtaba Rahman, Eurasia Group’s managing director for Europe, said in an email quoted by Bloomberg: “He is trying to create the impression of a prime minister in waiting.
"It sends a terrible signal to the EU about the U.K.'s overall stability and the government’s mandate and survivability. It suggests Corbyn is going to play dirty and use his presence in parliament to disrupt the Article 50 negotiations."
https://www.digitallook.com/news/international-economic/corbyn-to-meet-barnier-ahead-of-snap-elections--2757987.html
Collector
Yes if those 20,000 artillery pieces go off that 's an awful lock of broken crockery to be replaced!
...Sorry, it's Friday
Trident
I think Portmeirion (LON:PMP) could become a takeover target, especially from a USA suitor - as we're seeing, there are lots of takeover bids for UK companies coming from USA right now - partly because of weak sterling, but also because M&A is the main way highly rated US companies can achieve the growth that they need to justify high share prices.
Bear in mind that PMP's best-selling line is the "Christmas Tree" range, which sells very strongly in USA, and is a very well known, classic, design, which many Americans collect, buying new pieces each year, or exchanging them as gifts.
So, with a reasonable valuation, I could see PMP being snapped up by an American buyer, sooner or later.
Regards, Paul (long PMP)
S.Korea is a very important market for PMP and N.Koea has some 20,000 artillery pieces aimed at the south most of which within the range of Seoul. Considering the latest rumblings if I lived there buying more crockery would not be a high priority at the moment.
Quarto Inc (LON:QRT) 's net income as a detailed extrapolation of FY16 results may be up to $6m less than you think. $3m from one-off royalties and $3m from becker&meyer acquisition (they report $1.9m as profit for the 4 months they owned but notes disclose if they owned it for full year they would have lost $1m as - backend when they sell, front end is when they invest). There was a hefty share payment charge (from memory $1-1.5m above normal) which mitigates some of above for FY17.
Add in what seems to be implied in frontlist versus backlist sales and they look like they have a problem in their backlist which traditionally drives the FCF. They are making really good first year returns from their "frontlist" with a return of 1.5x what they invest for the year (so near $60m revenue on near $40m investment pa). That's 50% higher than they would have a few years back. However, even allowing for some erosion in last couple of years from Antipodean business, the fact that profits and FCF are not meaningfully higher from this front end investment suggests some struggling older assets.
What's changed? They have bought and developed more children material. Maybe this is the year that the backlist from that comes alive. In which case Quarto could be considered a sort of special situation recovery play with a new FCF developed that can pay down debt.
I owned it buying sub 200p for similar reasons to you. However, I have become simultaneously more bearish markets in general and a little bit more free time on my hands which has made be dig through my holdings. In the circumstances I am looking for either idiosyncratic risks or very cheap more conventionally exposed risks. Quarto would be the latter if its business was operating robustly. IMO the odds are that they struggle in 2017 to reach even current expectations and that some form of equity issue or takeover occurs. But if childrens books are fantastic I could be wrong...it needs to be quite fantastic as they are only approx 30% of revenue. So I sold a few months ago (lucky).
Note here - http://www.stockopedia.com/content/quarto-financial-noose-chokes-good-operational-advances-in-publishing-188339/
Hi Graham ,
Real Good Food (LON:RGD) was taken off Paul's bargepole list a couple of years ago and appears to have seen a decent turnaround through organic expansion and acquisition. It came to my attention around three weeks ago topping a small cap value screen In an IC article.
I only noticed last night that a major announcement was made on 29th June regarding a very large expansion and capital raise.
.Expansion Plan and Capital Raising
In a private placing Downing are to take a 10% stake at 35p and provide finance of up to £7.5M. The two largest shareholders who hold over 60% are providing a short term loan of £4M. Downing's partner in charge of public equity, Judith MacKenzie,has been appointed to the Board.
I believe this is a major growth opportunity in the somewhat unexpected area, that of ingredients for dessert food manufacture and home baking!
The shares can be bought at 35p, the same price Downing are paying and I shall be pleased if you could take a look at it. I have taken a position this morning with a view to a 12/18 month hold.
Dave
Hi Graham. Proactis Holdings (LON:PHD) 's acquisition announced this morning is pretty meaty, reverse takeover?
Hate to use this over used word, but could be transformational.
Any views?
Cheers. Ram
Re the Proactis Holdings (LON:PHD) reverse takeover, transformational is indeed the correct term in the sense that Proactis are acquiring £30m of turnover (compared to the £20m of sales they had in the last reported year).
The Admission Document reveals Perfect Commerce was profitable at the EBIT line last year but had a high interest charge - no doubt today's HSBC loan will allow a re-financing. The announced cost savings of £5m reveal why the deal will enhance earnings in the first year. For me, it's all a question of scope for cross-selling opportunities as well as the assessing the calibre of the new CEO.
I am struggling with this deal. Proactis is my biggest holding and I have long seen it as a safe growth story. Whatever the merits of the deal it inevitably as a lot of execution risk, so I think a reducing of my position may be necessary.
Having already trimmed a lot of my holdings this year I don't really want to be in a lot more cash, but I am not seeing any competing opportunities. Plus there are serious CGT consequences of cashing in. I could really have done without this deal.
Hey Ho
I hear your concerns Jon but thankfully I think they're misplaced in this instance.
Mergers and acquisitions can be a common source of execution risk as (in order to gain whatever synergies are expected) it is necessary re-structure and integrate businesses. But with this particular acquisition, the operational execution risk appears limited re p18 of the Admissions Document "PROACTIS and Perfect Commerce businesses have complementary solutions and technology which are provided to customers in territories and sectors with minimal overlap"
This lack of overlap suggests low operational execution risk. For me, the risks (as revealed by the targeted cost savings at the bottom) are twofold:
* rationalisation of IT operations - saving £1.7m p.a., this appears to be a major project
* off-shoring of customer support
Outside of these, my key question regards the calibre of the new CEO, which could be upside or downside risk. However the Board don't see a problem here & have irrevocably undertaken to vote in favour of the Resolutions to be proposed at the General Meeting in respect of a of 21.1 per cent. of the Shares.
The key attractions of Proactis 2.0 remain for me unchanged:
(a) it is a growth company both organically & from M/A cross-selling opportunities
(b) 80%+ of it's revenue is recurring year to year
(c) it ought to be counter cyclical given it's customers desire to lower procurement costs
=========================================================================
Net anticipated annualised cost savings (p25 of Admission Document)
? Senior management rationalisation: approximately £0.6 million;
? Relocation customer support (off-shore): approximately £0.3 million;
? Rationalisation of IT operations: approximately £1.7 million;
? Finance and administration: approximately £0.7 million;
? Sales and account management: approximately £0.9 million; and
? Other general operational efficiencies: approximately £0.8 million.
Hi Ram,
I've made an effort to cover this
Cheers!
Graham
Many thanks, Graham. In particular I will ponder on your last statement.
#PMP Graham, have at look at the 25th May AGM stat. It quotes End April (4 month) sales +26% (now +16% after 6 months) & constant currency sales excluding Wax Lyrical as flat (now -1.7%). Quite a dip in 2 months even though the "in line" forecast is maintained. Must have been a poor last two months. As a result I sold at the bell.
Thanks for that Martin,
I will update the article to reflect
Cheers