Small Cap Value Report (7 Oct 2014) - NXR, ULT,NFC, BVXP, SNTY, LTC, SNT

Good morning! I've been so busy reading & digesting results & trading statements this morning that I've not got round to writing anything yet! Plus I have a conference call starting at 10am with a company that has reported today, so this report will be a little later than usual - I'll keep updating it until about 2pm today, so feel free to refresh the page later to see the new sections added. Lots to report on today! (I thought this week was meant to be quiet!!)
Norcros (LON:NXR)
Share price: 15.88p
No. shares: 594.9m
Market Cap: £94.5m
This is a bathroom fittings and tile manufacturer. Its operations are split about 60:40 between the UK and S.Africa on a turnover basis, but profitability is more like 90:10 in favour of the UK. To a large extent I feel their S.African operations dilute the quality of what is a very good UK business, and personally I would like to see the S.African operations sold, as the shares would command a better rating if it was just a UK business, in my opinion.
Turnover for vanity, but profit for sanity, and all that.
As you can see from the two year chart below, the share price has been relentlessly declining in 2014;
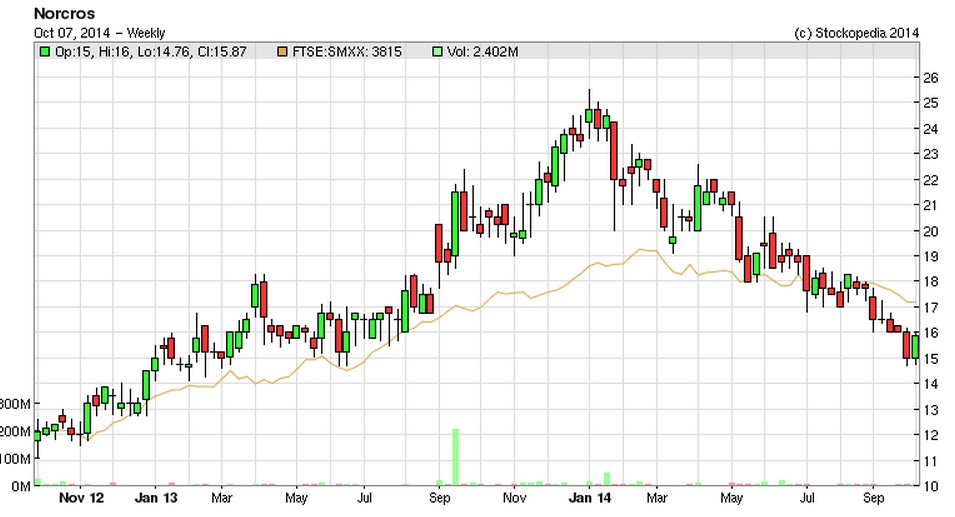
This price movement didn't make any sense at all to me. The company confirmed it was trading in line with expectations on 23 Jul 2014, and that has been confirmed again today with another update. So presumably the price seems to have drifted down on general negative sentiment - after all, we have been in a bear market for small caps since Mar 2014.
I never make decisions on price movements, but always on an assessment of fundamental value. Hence with the newsflow neutral, this share has become a stronger hold for me as the price fell. That is particularly the case because the price has been falling on very little volume - suggesting that weak holders were just getting bored and moving on. Whereas in other cases, share price falls on larger volume are more worrisome - since that suggests more serious investors are getting cold feet.
Trading update today - I am very pleased to see that the company has adopted best practice of opening the announcement with an unambiguous statement, then with the detail below.
Performance in the first half is in line with full year market expectations.
Great! That's all I need to know really. However, the update today helpfully gives specific figures too on profitability (covering H1, the six months to 30 Sep 2014);
Notwithstanding the adverse impact of the South African Rand we have continued to make solid progress with Group underlying operating profit expected to be 11% higher than prior year at approximately £7.4m (2013: £6.6m). Group underlying profit before taxation is expected to be 13% higher than the prior year at approximately £6.7m (2013: £5.9m).
There is good news about net debt coming down to a level I'm now comfortable with. This also gives them a little more scope for further acquisitions. The Vado acquisition seems to have been a success, so management have a decent recent track record on this. The group's stated strategy is to double the size of the business by 2018.
Closing net debt is expected to be in the region of £20m (2013: £28.8m), and includes the net proceeds after costs from the sale of our Australian subsidiary of £3.8m.
Outlook - this sounds noticeably more upbeat than in the recent past, in my opinion;
With an improved second quarter performance, our strong brands, leading market positions and continued self-help initiatives focused on market share gain, the Board remains confident that the Group should continue to make progress in line with market expectations for the year to 31 March 2015.
Valuation - it really does look cheap to me. The figures below are based on last night's closing share price, so today's share price rise will obviously push the PER up a little, and the divi yield will come down a little, but it still looks strikingly cheap. Indeed Numis say today that the discount is unwarranted, and they have a target price of 30p, which looks about right to me. That's almost double the current share price.

Pension deficit - note that Norcros has a humongous pension fund, but it was about 95% funded last time I looked, so the over-payments are not onerous, and do not restrict the company's ability to pay good & rising dividends. However, a big pension fund is likely to deter any takeover bids, and could unsettle some investors. However, this is a known issue, and is not causing any problems.
My opinion - In my opinion the share price here seems anomalously low. I don't know why that is, although it has the look & feel of a share where a selling overhang exists in the market. Sooner or later that overhang will clear, and providing the company continues trading well, then in my view there is obvious upside potential.
As always, not a recommendation, just a personal opinion.
Ultrasis (LON:ULT)
De-Listing - Serial jam tomorrow disappointer Ultrasis is finally leaving us - the company announces today that it is planning to de-List as part of a refinancing package. A large shareholder is propping up the company with loans, and presumably doesn't want to continue funding the costs of the Listing.
The shares are down about 71% today to 0.19p. That still values the company at £3.3m, which is about £3.3m too much in my opinion.
I remember buying some shares in this at the height of the dot.com bubble in early 2000, and thinking that the story sounded interesting. They've not managed to commercialise it over the last 14 years, so time to call it a day as a listed company anyway. I'm sure there is a small lifestyle business there for the employees.
Another timely reminder of the dangers of story stocks, and why they are best avoided altogether, especially if they don't have plenty of cash in the bank for fund operations through to breakeven.
Also another reminder of how savagely the market marks down the share price of any micro cap that announces it is going to de-list. There will probably be lots more de-listings in the next year or two in my view - so plenty more accidents waiting to happen, for people who ignore reality and refuse to give up on the story.
It's also a reminder that once a story stock has become stale, then it's not likely to succeed. If a company has been trying to commercialise a new product for 5 years or more, then the chances of it becoming a big commercial success are virtually nil. If it was going to happen, it would have happened already by then.
Next Fifteen Communications (LON:NFC)
Share price: 122p
No. shares: 60.8m
Market Cap: £74.2m
This PR group is changing its year end to 31 Jan 2015, giving rise to a one-off 18 month accounting period. For this reason the company reports today on the six and twelve months to 31 Jul 2014. Seems a strange way to do it. I would have just expected 12 month figures today.
Profitability - the headline twelve month figures look good - turnover up 6% to £101.5m, and adjusted profit before tax up 36% to £10.5m.
I'm not keen on the Balance Sheet here, which is somewhat on the weak side.
The accounts are altogether too messy for me to want to dig into them - too many adjustments & complicating factors, and it's therefore uncertain what the true trading positions actually is. I much prefer nice clean accounts, with no funnies, and buckets of cash being generated. That said, the cashflow statement here looks reasonably good, so it is generating real cash.
It's been a reliable dividend payer in recent years too, although at 2.3% the yield is nothing to write home about.
Looking at the valuation, it's probably about right, so I'll move on. The PER is about 12, which seems about right for a company in this sector with a not particularly good Balance Sheet.
Bioventix (LON:BVXP)
Share price: 612p
No. shares: 5.0m
Market Cap: £30.6m
This is a very interesting little company which moved on to AIM a few months ago, having previously been Listed on ISDX.
Take a look at the graphical history below, to see the remarkably steady growth, and huge profit margins the company makes. It is in a specialised niche in biotechnology, making antibodies derived from sheep. The products are like annuities - taking a few years to develop, but then churning out profits. I've seen management present at an investor event last year, and thought it sounded interesting. There is a good stream of dividends too.
Results for the year ended 30 Jun 2014 are out today, and look very good - turnover up 31% to £3.5m, and profit before tax before exceptionals of £2.2m. That's got to be one of the highest profit margins I've seen in a while!
The shares are very illiquid though. The company has an excellent Balance Sheet.
That's about as much I know about the company. ISA millionaire Leon Boros is a keen holder of this share, so I will be asking him about it when I interview him for my next Sunday evening webcast, this Sunday 12 Oct 2014.
Synety (LON:SNTY)
Share price: 190p
No. shares: 8.4m
Market Cap: £16.0m
This is one of my favourite more speculative investments. It's cloud-based telephony integrated into CRM software. I won't go through a full description again, but please refer back to my previous comments on it for more background, if you wish.
This is another share which has been relentlessly falling this year, and people have been getting jittery, assuming that there must be bad news on the way.
Thankfully there isn't bad news. Today's quarterly KPIs announcement was buoyant, as expected (the Chairman had previously indicated that he was expecting a decent upturn in Sep 2014, after a rather quiet month in Aug 2014, and that is exactly what has happened - reassuring to hear.
It is obvious that there is a selling overhang in this share too, indeed Commerzbank seem to be dropping 100k blocks of shares into the market from time to time, looking at the "holding in company" announcements.
One man's selling overhang is another man's buying opportunity, is the way I view it, if you've got the stomach for a 50% drop in price without breaking into a sweat, which personally I do - that's just how things are sometimes with illiquid micro caps - there is huge volatility, but in the long run it's just background noise.
At the moment Synety is loss-making and cash-burning, so it's got to be seen as highly speculative. There should be enough cash in the bank to get to breakeven in just over a year though.
Maybe the market needs a few more quarters results in the bag, to be more comfortable about re-rating it? I'm looking beyond the short term on this, and think it presents an exciting opportunity with a 2-3 year view. So far it's been quite a rollercoaster ride (see two year chart below);

Latchways (LON:LTC)
Share price: 830p
No. shares: 11.2m
Market Cap: £93.3m
I've been patiently waiting for this share to come down to the right price, and indeed my last comments on 5 Aug 2014 proved prophetic - "The PER is not yet into bargain territory, but it's not a million miles what I would be prepared to pay. Hopefully there might be another profit warning here, which might allow me in at 700-800p per share, which is the price that would float my investing boat.We're not there yet, so I'll continue watching from the sidelines."
Profit warning - a half year update (since the year end is 31 Mar 2015) today gives various detail about various things that have gone wrong, but this is the key part;
The negative revenue impacts outlined above are of a temporary nature, but the operational gearing of the business means they are of such impact as to lead us to expect that full year earnings will now be materially below last year's levels. We expect full year profit before tax to be in the range from £4.5 to £5.5 million. We have taken steps to limit spending except on sales resources and new product development, where investment will continue.
Despite these setbacks the company remains cash generative with a strong balance sheet. Cash balances at the end of September were in excess of £10 million. Given the temporary nature of the current challenges, we expect to maintain our dividend for the current year with the expectation of resuming profitable revenue growth next year.
Valuation - That's not good. A £93.3m valuation for a business that is only going to make about £5m pre-tax profit this year is not cheap at all. I make that only about 35p EPS, way down on current forecasts of 62p EPS.
It's all very well management saying that these factors are temporary, but a series of profit warnings does make you wonder if something more serious is going wrong behind the scenes? It's all very well blaming various factors, but if your product isn't selling as well as you expected, then it means customers don't want it for some reason - is it too expensive, or are competitors doing something better at lower cost? Or were previous levels of stronger demand just a purple patch that isn't going to be repeated? Who knows.
My opinion - yes it has a good Balance Sheet, and the dividend is being maintained - although by my calculations it won't be fully covered by earnings, so the divis must be at risk if a recovery in trading does not materialise as expected.
As I discovered with Xaar (LON:XAR) recently, when things go wrong, they can keep going more & more wrong for much longer than you, or the company itself, expect . Therefore in view of weak current trading, and a valuation that looks expensive given the greatly reduced profits expected for this year, I'm not convinced this has got into bargain territory yet. So I will continue to watch from the sidelines, and wait for some sign that things have stabilised or started to improve.
Sabien Technology (LON:SNT)
Prelims for the y/e 30 Jun 2014 look poor - sales down 13% to only £2.1m, and a swing from a £0.3m profit last year to a £0.3m loss this year.
However, it has a decent Balance Sheet, and pays a divi, surprisingly for a £6m market cap minnow.
What does intrigue me is the outlook. The sales pipeline was £4.6m at 30 Jun 2013, rose to £5.8m at 30 Jun 2014, and has risen again to £6.9m now.
Outlook - the company says;
"With the stronger pipeline likely to be bolstered by the new overseas Sabien 'Tech Centres' and the introduction of M1G to the product range, we are confident that operational and financial performance will improve significantly during 2015, enabling us to achieve our targets for the year."
Interestingly, the company is forecast to make a profit of £0.73m next year. If it does that, then there could be scope for a re-rating.
My opinion - tiny, illiquid share, but looks potentially interesting as a bit of a fun money punt maybe? It has been modestly profitable in the past, and the product - which makes energy savings for clients by better controlling commercial boilers, sounds interesting. I like products which pay for themselves, as they should be a relatively easy sell.
There are a couple more shares on the list, but I've run out of energy to crunch any more numbers, so will have to leave it there for today.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in NXR, SNTY, SNT, and has no short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned in these reports)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
hi guys, I thought I would throw in my thoughts on Norcros (LON:NXR) as I think there are some more reasons for what seems a low relative PE valuation. Paul, I know you are a fan of this stock - I hope you don't mind me putting the following arguments forward:
First, the overall returns on assets, capital and equity are not too exciting (5%, 7% and 16% quoting after FT) and if you assume compounding of value at these levels it doesn't bode well for growth - unless something dramatically changes in the business economics but I can't predict that.
Add to the above the fact that between 2010 and 2013 the company generated virtually no cash flow after capex which hardy covered maintenance requirements assumed to be equivalent to depreciation. In 2014 the company generated around 6.8m of cash after capex, which again was short of the level seemed enough to cover maintenance. So two issues here - poor cash generation in the first place (more on this below) but also what seems to me just a nominal investment which may not be enough to support the growth story (unless there is a lot of spare capacity which can be easily deployed - I haven't analysed the stock in detail, so please correct me if I am wrong).
Back to weak cash flows. It stood at 6.8m for 2014. Let's be optimistic and assume it doubles to 12m after capex - I have already given them 100% growth assumption on 2014 which doesn't quite reconcile with the latest update so let's not bake in any more uncertain growth to the following valuation: based on 10x free cash flow (10% wacc in other words) the above gives as an estimated 120 enterprise value and an estimated market cap of: 120 minus 31 LT debt minus 21 pension fund deficit = 68m. So that is almost 30% downside to the current market cap based on the above assumptions (which of course are based on some of my high level subjective opinions).
Now, last point - I am not optimistic on the pension deficit. If you go to note 23 (page 84) you will see that majority of the plan assets (300m out of 380m) are invested fifty-fifty into bonds and absolute return funds (hedge funds?). I am sceptical in the ability of either 'absolute return funds' or a portfolio of bonds to deliver sustainable returns beating inflation given the current interest rate environment. So, in my opinion, there is a risk to the deficit in the long run and I would therefore not be keen on ignoring it in the valuation - hence it is included in the example approach above.
Hope my point of view gives the valuation story in a different light. I might be completely wrong with some of my back of the envelope assumptions but I hope I flashed out some different angles which explain the apparent PE-based cheapness of the stock.
I have no position in the stock. Just bored this evening at home.....
cheers.
BG,
What attracted me to ETQ is not the overseas franchise model possibility, but their success in selling these more efficient fan coils. I did a bit of background research on this to understand it better and their ECO ACs are driven by low power 10V variable fan motors. In addition the fan coil market is predicted to grow at 10-15%/annum, so even if the overseas franchise model fails there is growth in their main market. So whilst they may be metal bashers, they are selling energy efficiency with green credentials!
TUNG has had a pretty big drop in the last week .. anybody know why?
I do hold Energy Technique (LON:ETQ), but I wouldn't describe them as an energy efficiency company - they're an old school metal bashing manufacturer of coils for large air conditioners and they also produce heat curtains. They've obviously done very well over the last couple of years, but the future is still interesting, with their attempts to start a franchise operation overseas. Heat-exchangers are costly to export, so it makes sense to have local manufacture. Those responsible for designing the large buildings going up in the the middle eastern oil states have apparently had a bad time with the quality of far eastern sourced heat exchangers, so Diffusion (the coil subsidiary of £ETQ) are proposing sharing designs with a franchised local company, to give the specifier the peace of mind of using what is effectively market leading product, sourced locally. The company has engaged a US consultant to work on this new venture - I met him at the AGM, but unfortunately forget his name.
Obviously it's now on a fairly racy earnings rating, but it seems a very capable management team, and as Paul said in his webcast, sometimes you need to pay up for Quality! Note that there are no broker estimates. The policy of the company (well really it's ex-head of IoD chairman) is not to waste money on parasites, and simply provide what they regard sufficient information to the market via quarterly updates.
BG, One AIM Energy effeciency company you should look at more closely is Energy Technique (LON:ETQ) who have a 9 F Score and excellent RS in what has been a weak small cap market. The reason they are doing well is they are producing boring looking energy efficient "fan coils" adopted by the likes of Marks & Spencer, Sainsbury's, Tesco, New Look, Boots, ASDA, John Lewis, Lloyds and TK Maxx and they are now finding their way into high end London residential properties. ETQ sales are up over 25% and are results to date are "ahead of management expectations". The downside is a wide price spread.
I hold a few in my SIpp
Ian
Paul, in the way you avoid overseas companies listed on AIM, I avoid Energy Efficiency companies. The benefits of employing their product or technology is almost always subjective and difficult to measure. It is therefore often too tempting for management to exaggerate the benefits to both customers and investors. In the case of Sabien Technology (LON:SNT), it has the added issues that it's something that should not be difficult to replicate for competitors or boiler manufacturers.
The Norcross company announcements might be a model of clarity, but their product specifications are not. I spotted the water saving shower heads. After clicking on the "Specifications" there is no flow rate figure of any description, never mind a proper pressure v flow rate graph.
Never mind, it looks cheap. Shall have to research the company.
Just remembered the poor service when I had a shower mixer valve fail under a 5 year guarantee.
They wouldn't sent me a new thermostat, even though it could be the only possible cause of the failure. After I made an appointment a few days later & waited in for 4 hours, their technician arrived & confirmed it was the thermostat. However, HE DID NOT HAVE THE CORRECT PART ON THE VAN. So I had to wait in again.
Needless to say, when the other mixer valve failed, I just bought one with a different brand.
Companies need to do more to build sustainable customer support for their brand. Firstly, a simple shower mixer valve should never fail after 2 years. If it does, they need to fix it efficiently & quickly.
I hope they have improved on this. As it is, I'm not sure how much the brands would be worth.
Suppose it's a cheap enough company valuation if the housing market doesn't blow up in the next couple of years.
jonesjeff
I would certainly agree with you on the life of a mixer valve - these things should be built to last. Unfortunately, this is somethign that Ive come across with Triton in the past - they are cheap(er) and cheapful but reliability (IMO) has been compromised as a result, especially when compared to Mira (mixers and electrics) although they are more expensive, the improvement in quality and reliability is worth it I feel.
Then again, I could be biased - I used to build the old Mira electrics when I was 16 (dad was their MD).
D ;-)
Re Norcros. I see that Sharescope, presumably based on the three analysts following Norcros, show reported pre-tax profits of £5.8m for the year to March 2014 and forecast profits of £14.33m over the following 12 months. But the eps for these two periods are given as 1.99p and 2.01p respectively. Very strange unless there has been a large dilution.
However, what catches the eye even more than that is the r&d spend, which was over 40% of pre tax last year. Normally this would be regarded as a good thing if there was evidence of benefits coming through. I would have liked to have read in the update: "...Your board is pleased to report that the drive towards best in class has resulted in improvements in quality across the whole range of plumbing products, such that we are able to double the statutory customer guarantee and progress towards making Norcross showers, taps and ancilliary items the most sought after by professionals and specified by end customers."
Perhaps I missed it, but I doubt it.
Crusty (no holding)
Paul,
If you have time I would love to hear your comments re pure wafer. For transparency I hold these at about the level they have rebounded to today, but i really like them, so beeee kind please. What do I like? They have expanded production, improved their balance sheet from a few years back when they got into trouble. Their products compete with in particular Japanese companies but seem a bit more innovative (currency issue). Price to book 0.87 appreciate some of the assets would be hard to sell. Dividend coming on tap. Sorry not my thoughts I am interested in…….promise I won't come back in a defensive mode if you don't like!
Guy
Paul;
Just got round to listening to your excellent Scott/ Stredder stock discussion; Extremely interesting & informative, very educational for an investor getting to grips with Fundamentals & what actually to look for amongst all that data; (as is your daily blog) particularly for me as for years have relied on TA for my selections. Now moving down to include the sub £200m cap stocks where this stuff is essential. Do please make it a regular feature.
Just one small point , I could hear you perfectly all way through but at the beginning David was virtually inaudible but that improved progressively.
Thanks for taking the time.
Hi Paul,
Any views on Bioventix (LON:BVXP) and or ST Ives (LON:SIV) ?
Both put out Prelims this morning. Thought Bioventix stood out for me and not so sure re St Ives.
Grateful for your thoughts if you get 5 :)
Regards,
Sully.
Paul can you look at DRV after their trading statement today?
Hi Paul,
Well after the relentless grind downward this since January 2014 it’s good to see the Norcros board putting out a statement with a more positive feel. I honestly feel that if I were standing next to the Norcros FD looking out of the window on a sunny day my opinion would be “nice day” but the FD would comment “it’s going to rain sometime”.
Nice to see the first line of the trading statement saying ” Performance in the first half is in line with full year market expectations” rather than have this important comment hidden underneath all of the other comments.
I am happy to continue holding as I agree there is good value within the business supported by a yield or around 4%.
Certainly one to be patient with and I don’t see it rushing back to the mid 20’s within a couple of weeks but happy to sit tight.
Paul, any thought on the dividend and free cash flow which has been negative in two of the past four years despite increasing the dividend?
hi paul
what are their options to get the pension fund off their back?