Small Cap Value Report (8 Apr 2014) - MTEC, SNTY, INTQ, PRV, OFF, RNO

Good morning! Just a reminder that tonight is the inaugural ShareSoc Brighton investor evening, hosted by myself and Simon Cooper. We have about 50 guests booked in, so it should hopefully be an interesting & fun evening. Our speaker has confirmed (the CEO of Tracsis, John McArthur), so all systems go!
Also, just to flag up another Webinar, this time for today's interim results from Matchtech (LON:MTEC). Details can be found here. The webinar starts at 1pm tomorrow*, and enables us to listen and view online a live results presentation by management, and to submit questions. A terrific format, and much more convenient than having to make a trip into London.
So let's move on to today's small cap results and trading statements.
* = My apologies, an earlier draft of this report mistakenly said that the Matchtech webinar was today. It's not, it's tomorrow, 9 April.
Matchtech (LON:MTEC)
I might as well report on their figures first, being interim results to 31 Jan 2014. This is a recruitment group, specialising in placement of engineering and professional services staff. The numbers look good. Net fee income is up 19% to £22.1m, underlying profit from operations was up 32% to £6.2m (this figure strips out the newly acquired Provanis business, and other things like amortisation & non-recurring costs).
Including the acquisition, profit was up 48% to £6.2m - it looks as if that is a coincidence that unadjusted profit is the same as underlying profit - it must just be the case that profit from their acquisition offset excluded costs.
Net debt is reported at £8.6m. The outlook/current trading comments sounds encouraging;
Demand for contractors remains high while the permanent marketplace continues its recovery, we are seeing increasing margins and an improving NFI conversion ratio across the business. The integration of Provanis is going well as we focus on cross selling its services to our wider client base.
Trading in the second half is progressing well and we continue to invest appropriately to support our ambitious growth plans. The Board currently anticipates that the results for the year to 31 July 2014 will be slightly ahead of its previous expectations.
Stockopedia shows broker consensus of 34.9p for this year (ending 31 Jul 2014) and 39.9p for next year. So if they are "slightly ahead" then perhaps that means 36p-ish for this year? So the shares are not exactly bargain basement at 623p - I make that a PER of 17.3. If you're prepared to pay up-front for increasing earnings, then it might be worth considering, but personally I'm not, and find this price too high.
Although it is worth looking at what operating profit margins companies made pre-financial crash, and applying that margin to future turnover, to see what scope there is to raise profits in future. Trouble is, that's getting harder to do, because pre-2008 figures are now dropping off the table of comparatives, due to the passage of time. Recruiters are quite operationally geared, so there is probably scope here for the operating margin to rise from its current level of about 3% to perhaps 5% (they reported 5.3% in 2007/8 for example).
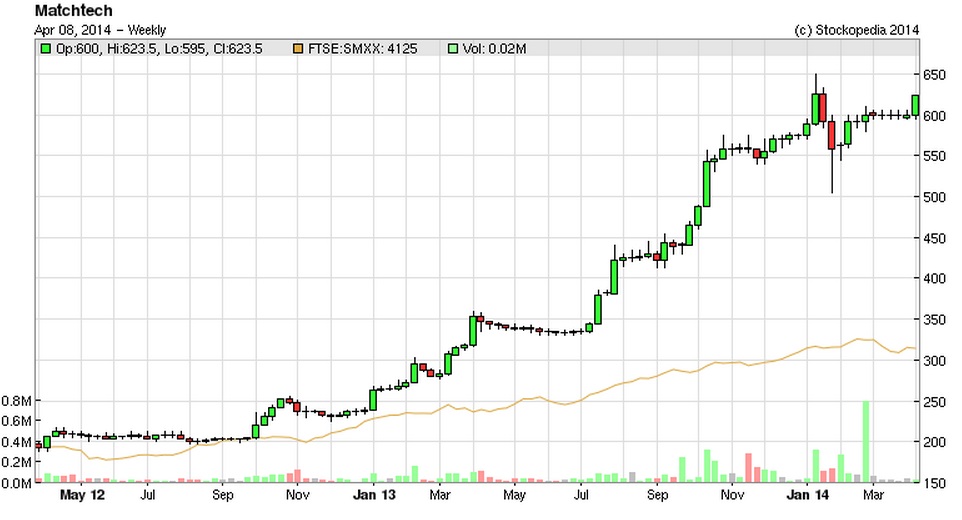
So I can see why the market is pricing this stock on a relatively high PER, but even so it's not for me, at this valuation - looks from the chart like the smart money has already been made on this stock (and other recruitment cos), I think it's too late to join the party now;
Synety (LON:SNTY)
As I expected, the Open Offer at Synety was heavily over-subscribed. My estimate beforehand was 5-6 times over-subscribed, which was in the right ballpark as it was actually 437% subscribed. Not surprising really, when you offer a 300p+ stock for 250p! I won't go on about the structure of the deal, as that's been done to death, and I've had an opportunity to discuss it with the company.
Going forwards though, I think it is extremely important that brokers and other advisers realise that squeezing out private investors in fundraisings is just not acceptable, unless there is some sort of emergency reason for a Placing with no Open Offer attached. In this case the company told me that the Open Offer element only increased the fees marginally, although I have to say that the fees at £300k (presumably mostly from their broker, Singers) are absolutely extortionate for a £4.5m discounted Placing and £0.5m Open Offer. That's 6% of the funds raised being pocketed by advisers! Daylight robbery.
We're in a bull market, so exciting growth companies have no trouble raising fresh money, this deal should have been done from a position of strength, but never mind it's done now. Or at least it should be done in a couple of hours, when the EGM authorises the new issue of shares, which should be a formality.
InternetQ (LON:INTQ)
A reader asked me to take a look at the next set of results from this company, and I have to say the figures look awful to me. Greek companies do seem to like creative accounting. In Globo's case that means profits that never turn into cashflow, but instead just pile up on the Balance Sheet in Debtors.
In the case of InternetQ, they just capitalise everything that moves! As such the profit figure is effectively fantasy in my view. Consider this - for 2013 InternetQ reports EBITDA of E14.4m. However, it has capitalised E13.8m of costs into intangible assets. So reversing out the capitalised costs, in cash terms it was barely above breakeven, at only E0.6m!
Of that E13.8m of capitalised intangible costs, E6.6m was purchased software (which could be considered alright, depending on who it was purchased from - i.e. not a connected party), and the balance of E7.2m was internal costs. So this means that the way I view it (expensing all intangibles as a cash cost), the company is not generating anywhere near as much profit as it is reporting.
Debtors are large, at E36.4m (that is Debtors + Prepayments), but not outrageously large given turnover of E104.4m, which I make just over 4 months debtor days. A bit stretched, but not horrendously so.
The market cap at about £150m (at 395p per share) looks aggressive to me, matching the accounting presentation, so it's not something I would invest in.
Porvair (LON:PRV)
Porvair issues an IMS today, but it only refers to revenues, and not profits vs expectations. It's the latter which matters, so why issue a trading statement that doesn't mention profit? It also refers to the outlook as follows;
The outlook for the coming months is encouraging. Order books are healthy and the large engineering projects referred to above are progressing according to plan.
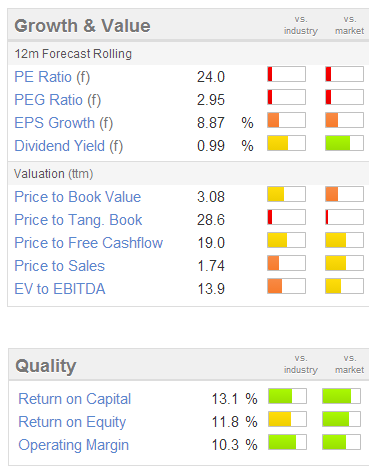
So that all sounds positive, but is it already in the price? I would say so. As you can see from the Stockopedia valuation figures & graphics, this share is not showing value on any measure. Bear in mind these are based on forecasts, so to justify this kind of valuation the company really needs to be reporting ahead of expectations profits, but that hasn't happened today.
Office2office (LON:OFF)
There's a rather bizarre situation going on at this struggling office stationery supplier. A shareholder called Nicholas Gerber has requisitioned an EGM in which he is trying to take control of the Board by firing the existing members, and appointing himself & some others in their place.
It now transpires that he apparently wants to reverse in a US fund management business, and a Bulgarian website development start-up into Office2office. This sounds an absolute crackpot plan, and in my view very foolish, since attacking a company which has a weak Balance Sheet in this way, could have been the trigger to destabilise the relationship with the bank and key suppliers.
I missed the latest results from this company last week, as it was a very busy day. However they have shown good progress in reducing net debt, which was last reported at £21.8m on 31 Dec 2013, down £7.2m compared with the start of 2013. That said, the Balance Sheet is still extremely weak, with negative net tangible assets of £43.1m. As such it's a bargepole share for me, ridiculously risky unless/until they raise a large slug of new equity to fix the Balance Sheet.
The EGM requisition looks like an unwelcome distraction, and I'd be amazed if it attracts any shareholder support.
Renold (LON:RNO)
This industrial chains group seems to be making good progress with its turnaround. A trading update today says that results for the year ended 31 Mar 2014 should be in line with market expectations.
Broker consensus is for 2.93p EPS for y/e 31 Mar 2014, and 4.16p the following year, which equates to a PER of 19.1 and 13.4 respectively. Whilst that might sound reasonable for the current year which began 8 days ago, it completely ignores the large pension fund deficit, and significant net debt. There's no dividend either. Taking all of that into account, I think the price is well ahead of itself here.
Pension deficits absorb a lot of cashflow to plug the gap, and that restricts dividend payments, so you can't just ignore them. Or if you do, then you end up overpaying for the company. As you can see from this extract from the 2013 Annual Report, there is a yawning deficit on the pension fund, which got a fair bit worse in 2013;
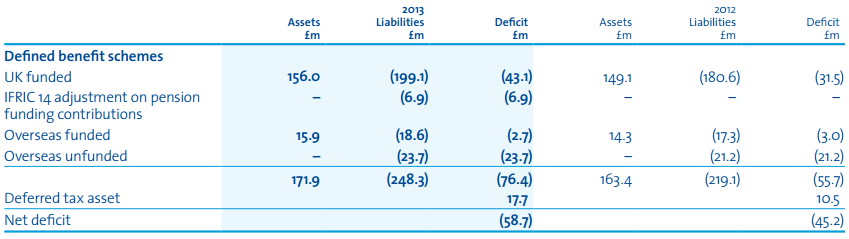
These are material figures in comparison with the current market cap of £125m (at 57.5p per share).
I've had a look through the 2013 Annual Report, and the section below talks about the deficit recovery payments, which are a large chunk of the company's profits & cashflow, therefore this is a serious issue that investors need to know about. So it looks to me as if there will be a £2.5m+RPI drain on cashflow for the next 25 years, and potentially more if profits rise significantly, as set out below;
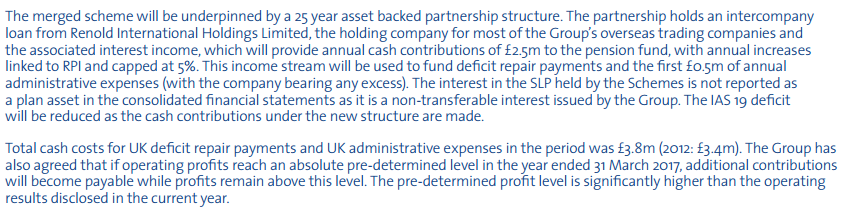
So however you look at it, the pension fund deficit needs to have a material impact on valuation here. It seems to me that is not being done, hence the market is over-pricing these shares at the moment by apparently ignoring the pension deficit, in my view.
That's my lot for today, time to prepare for this evening's investor event in Brighton.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in SNTY, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
I used to change trains at a small station where the platform was overlooked by a Temperance Hall. The bilboards proclaimed 'DRINK -the Devil's vomit' and 'The drink goes in, the wit goes out'. Their impact on me was very limited. I finally gave up drinking when my liver started to hurt. Now I am up around five each morning, and enjoy a couple of hours gentle pottering before the day begins. However, that is probably the best I feel all day.Life is so full of choices!
Great - thanks both.
Hi Paul,
I was wondering if you are going to write up Mark Slater's speech from the UK investor show, which I was unable to attend this year - due to staying in a haunted castle... (don't ask!) Last year's talk was really interesting and was available afterwards as a youtube video, if I recall correctly. I know you already do so much so no worries if you don't have the time or inclination - but last years write up was invaluable (even though I heard the talk first hand!)
I also have a question about takeovers - I hold AZ Electronic Materials SA (LON:AZEM) and they announced a takeover by Merck in December. The closing date of the offer keeps getting extended but the level of acceptances seem to remain roughly the same/or stuck @ circa 64%.... I noted the following statement in the latest RNS
'Merck has also agreed that, if the condition to the Offer relating to MOFCOM is satisfied, it will lower the threshold in respect of the Acceptance Condition to the Offer from 95 per cent. to 75 per cent.'
I find the offer update and extension documents very difficult to understand but what i would like some advice on is who sets the acceptance level (i thought it was 50%... What is the norm?) and whether the acceptance level can be changed from 95% to 75%. Is this able to be changed by the aquiring company or the business being bought? It's all very confusing! The market seems to believe that the takeover will go ahead as there is a very small discount to the offer price £403.5p to £402p
Cheers, Ben
Hi Ben,
No I won't be writing up anything from the UK Investor Show, as I was completely preoccupied with doing a one hour talk about small caps on the Stockopedia stand, and then appearing in the shareholder activism panel. So no time or inclination to do anything much else really!
Actually some people told me that Mark Slater didn't show up, and the running order was then altered at the last minute.
All main stage sessions are going to be released on video I think in the next few days/weeks, so we'll be able to catch up with what we missed in that way. The Master Investor Show seems to be going ahead near the end of April with some of the same speakers & exhibitors. Difficult to understand what the point of that is?
Regards, Paul.
Hi Ben, Paul,
Mark Slater was sick on the day, apparently. Tom Winnifrith has indicated that Mark Slater has agreed to record the presentation he was intending to give, so should be available for viewing in due course.
Cheers,
Mark
Hi jjis,
The proposed POC tax will hit NPT's profit before tax which means that the company will take longer to use up their carried forward tax losses.
The tax asset merely represents the potential tax benefit for NPT when they make profits. As the proposed POC will reduce their ability to make profits, the brought forward losses/deferred tax is of no use at all at mitigating anything.
Your take on InternetQ is a cold splash in the face for one who invested earlier this year feeling that this could be a stock of real potential (it is a component of the "10% goes to blue sky" section of my portfolio). But having looked at the said results I come away feeling that you may have overdone the bargepole rating. Of course I have no truck with EBITDA numbers is cash and sustainable growth that counts.
- You mention 4 months plus of receivables, but at their rate of growth it is likely by my calculation to be nearer or at 3 months.
- the capitalisation of E7.2mm software costs for internal development does not seem preposterous for a software company that is growing its product offering and has overall operating and admin costs totalling E46mm. Presumably Deloitte, as a heavyweight auditor is applying the normal rules that allow software capitalistion only from the point where a commercial product is completed - around the beta stage. I would wholly agree that the prudent investor should the effect on cash, and furthermore recognise that in a liquidation this stuff is worth nowt. But there appears to be a recurring base to the receipts on this software, and I like that.
- the most serious charge is that to justify its value the company (like Amazon!) must get over the "hump" of internal investment and acquisition of establishing its place in the world and reap more from what it sells and as fast as possible use cash to keep out of the hands of bankers. They and the markets seem to be offering good support now but they can never be taken for granted.
Going for the company is a growing presence in growing markets, and top line revenue to prove it. It is a "blue sky" investment for now bit with your warning I will be even more paranoid about looking out for thunderclouds
Hi Aislabie,
Fair points. I am inherently suspicious of all overseas companies that list on AIM, and especially so with Chinese, Indian, South American & Greek companies, having seen some pretty ropey sets of accounts from many of them in the past. As Mark Slater said a couple of years ago, "There's usually something wrong" with overseas companies which List on AIM, a sentiment I wholeheartedly endorse!
As regards the issue of capitalised intangibles, I'll leave it up to readers to decide for themselves which figure they want to use as the basis for valuing the company, and fully accept that there are a range of opinions on that, with me at the most conservative end of the scale.
However, few (if any) other commentators drill down into the figures & flag up these issues. Nearly all other reporters just regurgitate the published headlines, which are always set up to give the most favourable possible interpretation of performance! This can lead to investors being far too optimistic on valuation - as a lot of tech/growth investors are discovering in a painful lesson right now, as valuations are sharply correcting on inflated large cap tech stocks.
Regards, Paul.
"Presumably Deloitte, as a heavyweight auditor is applying the normal rules..."
Here is yesterday's news from Canada:
"Livent auditor Deloitte ordered to pay $84.8-million for failing to detect fraud"
Heavyweight or not, auditors have a notorious history of either willfully closing their eyes to fraudulent activities to being coerced by management in following reporting practices to their advantage.
Hi Ramridge,
As someone who originally trained as an auditor for 3 years, I now place very little reliance on audit opinions. There is a certain deterrent effect, but audits are not in any way a thorough dissection of the results. They are just a review really, with a bit of sample testing, and verifying key things like the bank balance matches cash on the Bal Sheet, etc.
So cunning management can drive a coach & horses through the financial statements, and the auditors wouldn't notice a thing, if the bodies are properly buried.
Remember also that financial statements just present one, from a possible wide range, of profit figures. Within reason, you can pretty much select whatever profit figure you like, then adjust a whole range of things to work back to that figure. Most FDs have a bottom drawer account, i.e. where they keep an unncessary provision on the Balance Sheet, which can be released when required to absorb any unexpected costs, thus smoothing out profits from one year to another.
Also remember that from what I've seen, the majority of Listed companies that go bust had a clean audit opinion, so it is no safeguard over the solvency of the company at all.
Regards, Paul.
Hi Paul -
This may be off topic...
As a PI I am particularly interested in understanding the signs that tell you fraudulent accounting is taking place ( I do mean fraudulent activities a la Bernie Madoff and not just bending existing accounting rules). The US SEC apparently have a Robocop -like analytical tool which trawls corporate filings to flag high-risk activity for closer inspection. I am sure that someone like you could come up with a few heuristics to identify red flags. Like the 'tells' to a poker player. Would be interested in your views.
Regards, Ram
Hi Paul any thoughts on NetPlay TV (LON:NPT) which you wrote on in January this year when tax was the main issue. They have provided some clarity on this today in the results when they said
I also note in the statement they say the following on tax
Now I'm not an accountant - does that mean they'll be able to offset most of this hit anyway by utilizing the brought forward losses / deferred tax asset plus the self help measures they mentioned? If so may be not such a problem - but I see the price is off so I guess people who know more about it than I do think otherwise?
I'm not interested in NetPlay TV (LON:NPT) at the moment, as the heavy Director selling, combined with unknown impact of betting taxes, and the company being less than open about the issue last year (the company and their advisers seemed to go into a blind panic when some of us questioned the tax issue), made me feel that it was not something I would want to invest in. Looks a can of worms to me.
Regards, Paul.