Small Cap Value Report (8 Aug 2014) - PURI, RCN, SEE, HYC

Good morning!
PuriCore (LON:PURI)
Share price: 35.5p
No. shares: 50.14m
Market Cap: £17.8m
Interim results to 30 Jun 2014 have been published this morning. The company makes disinfection products for a number of markets - supermarkets (fresh food, and cut flowers), and medical (wound care both human & animal). I've always thought the products sound promising, and the company has won impressive contracts with major customers, but it has not as yet succeeded in making a commercial success of these products.
The area that was commercially successful, its endoscopy disinfection business, was recently sold for what seemed a good price. Therefore the nature of the investment has changed, in that it's now heavily cash-backed, with a loss-making business attached. So it is now critical what they do with the cash.
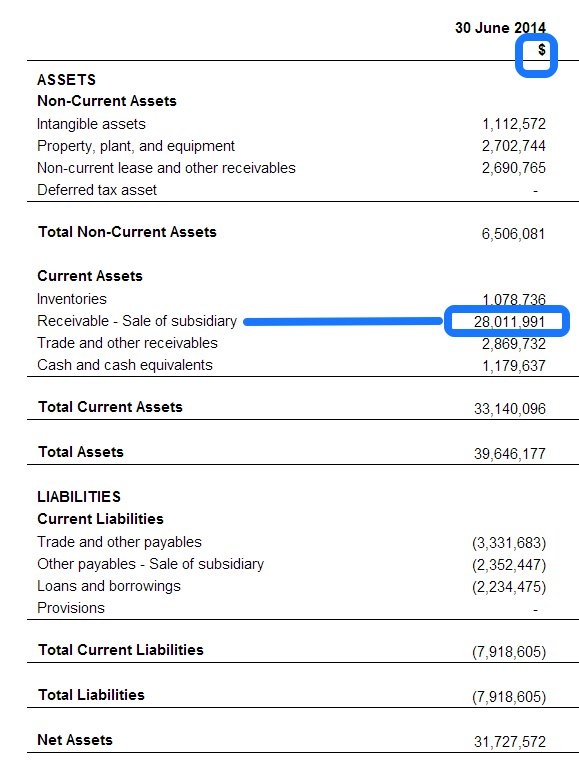
Balance Sheet - As you can see from the 30 Jun 2014 balance sheet, I've highlighted two items, firstly note that the accounts are published in US dollars, so everything needs to be divided by 1.68 to translate into sterling.
Secondly, the balance sheet is dominated by the $28.0m receivable from the sale of the endoscopy business. This sale completed on 1 Jul 2014, just one day after the period end. Therefore the $28.0m receivable can be considered as cash.
In my view the cleanest way of finding the current net cash position is to take the $28m receivable, add on cash of $1.18m, then deduct the $2.35m payable & the $2.2m borrowings figure, which gives a net cash figure of $24.6m = £14.6m.
Note that this adjusted net cash figure is 82% of the current market cap, which values the business at an enterprise value of just £3.2m.
Downside protection - Some might say that valuing the existing business at hardly anything is very sensible, given that it has not been established that they have a viable business there. I agree with that. However, it does mean that you have the downside protected to a considerable extent, whilst the upside potential (i.e. if they do deliver a good result from the ongoing business) is thrown in for very little.
Ongoing losses - The problem is that the ongoing business had a poor half year, and made an operating loss of $3.7m on turnover of only $8.6m. That was a significant deterioration from H1 last year, when turnover was $12.3m and the loss was smaller at $2.0m (in both cases the endoscopy business has been stripped out, as it is now a discontinued operation).
Valuation - I'm in a quandary about this share. On the one hand the performance of the business has been poor, which is clearly negative (although not a surprise, as poor trading had previously been announced). On the other hand, the sale of the endoscopy business has de-risked things considerably by providing a cash pile that makes up the bulk of the market cap now.
So if management do something wise with the cash pile, then hopefully they could create an interesting business - look at Tristel (LON:TSTL) for example, where a very nice growth business has been created in the infection control area. On the other hand if management squander the cash on more sales & marketing that doesn't deliver a return, then they could end up destroying shareholder value here - and let's face it, their track record is fairly mixed, if one is being charitable.
Outlook/Strategic Review - This is rather non-specific, as follows;
PuriCore continues to identify both significant market opportunities and prospects for sustainable growth within and around refocused Continuing Operations. The sale proceeds provide the resources to enable the Company to identify and execute strategic growth opportunities in a targeted and disciplined manner. The strategic planning process is underway, the results of which will be communicated to the market later this year.
It's not clear to me why a small business like this needs several months to conduct a strategic review - surely they already know their products & markets, and where the best opportunities lie? We're not talking about turning around Tescos here, this is just a £ 10m p.a. turnover minnow at the moment!
I hope management have included substantial pay cuts for themselves in the strategic review, as now the business is smaller & more heavily loss-making, the generous pay packets of the past cannot continue. If they can't come up with a convincing strategic plan, then it might be time for a clear-out of old management, and bring in some fresh blood, in my opinion. This seems to me a situation where shareholders need to start kicking some butt. However, let's firstly hear what they say in the strategic review due to be announced in Q4 of this year.
My opinion - It's not trading well, however the valuation is now on very solid foundations of a cash pile that makes up 82% of the market cap. That gives time for management to turn things around. If they cannot do that within 6-12 months, then they should probably be replaced, in my view.
The products clearly have potential, if sales can be driven up to the next level, without a prodigious sales & marketing spend to get us there. So with the cash backing, the shares are really buying mainly a cash pile, and secondly the upside potential on the business, which may or may not happen.
If some decent contract wins were to occur, and a move into sustainable profit became possible, then the upside potential could be exciting - my best investments have generally been from cash rich shares which investors had given up on, but which then went on to be multi-baggers when a commercial breakthrough occurred. Trouble is, you don't know in advance which ones will work, and which ones won't.
The company needs to do a root & branch review of costs, and strip out everything that is not vital, in my opinion, then focus all their effort on driving up sales. So a much leaner operation is necessary in my view - the "General and administrative expenses" line on the P&L now sticks out like a sore thumb as being much too high.
As you can see from the two year chart below, PuriCore has seriously lagged the small caps sector, due to its poor commercial performance. However, the Small Caps Index (SMXX) comparison line gives an idea of the upside potential if the newsflow were to become positive.

Redcentric (LON:RCN)
Share price: 111p
No. shares: 144.1m
Market Cap: 160.0m
This is a managed ICT* company that was Listed in Apr 2013, having been demerged from the Redstone Group.
(* ICT is apparently the new TLA^ that we should be using to describe IT that also involves communications)
(^ TLA = Three Letter Acronym)
It's a new one to me. The trouble is that Stockopedia doesn't show the historical figures, as it is a new listing, so one would need to do some digging on the company's website to find the listing particulars, which will probably have the historic proforma numbers in them.
I've just had a quick review of the Admission Document, and must admit I don't really get it. The historic figures look very lacklustre - a small business operating not much above breakeven. So there must be more to it than that. Looking through the historic RNSs, the company seems to have made a "transformational acquisition" in Nov 2013, financed by a Placing of 80m shares at 80p
Results for the year ended 31 Mar 2014 look a lot more sensible, with proforma revenue of £87.4m and the dreaded EBITDA of £16.2m, with synergies of £3m anticipated. A 1p dividend was also paid. I'm not keen on the Balance Sheet though, with negligible net tangible assets, and some debt. With it being recently floated, and with a big acquisition during the period, the figures are not easy to interpret.
Trading update - issued today sounds positive. The company has a 31 May year end, so it is reporting on just over 2 months of Q1 today. The bullet points say;
- Strong first quarter, delivering on all key performance indicators
- Organic growth at top end of management expectations
- Strong Q4 cash flow has continued into Q1, demonstrated by payment of maiden dividend
- Integration proceeding well
- Comfortable with full year market expectations
.
Valuation - Stockopedia shows the current year broker consensus EPS forecast as 7.55p. So at 111p per share that values the company on a PER of 14.7, which looks sensible. Although I'd want to check what basis the EPS forecast is made on, and that they haven't stripped out too many costs in arriving at an adjusted EPS.
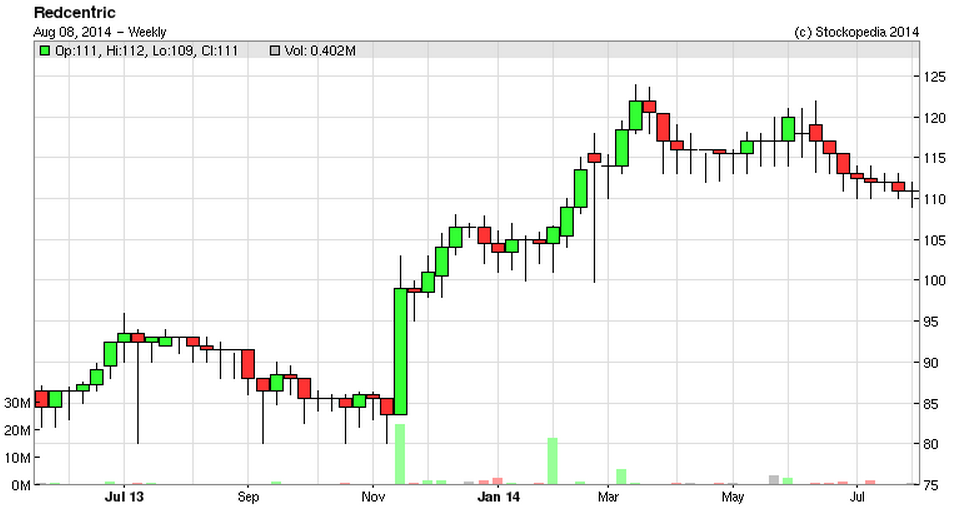
My opinion - I've only just looked at it, so don't have enough info to form a meaningful opinion at this stage. Will report back here when the next set of results are published. The shares have been a reasonable perfomer so far since listing;
Seeing Machines (LON:SEE)
Share price: 4.25p
No. shares: 822.23m
Market Cap: £34.9m
This is a small Australian company, listed on AIM, which has developed, and is selling into the mining sector, devices which read the faces & eyeballs of vehicle drivers, and sound an alert when they are over-tired or not looking at the road.
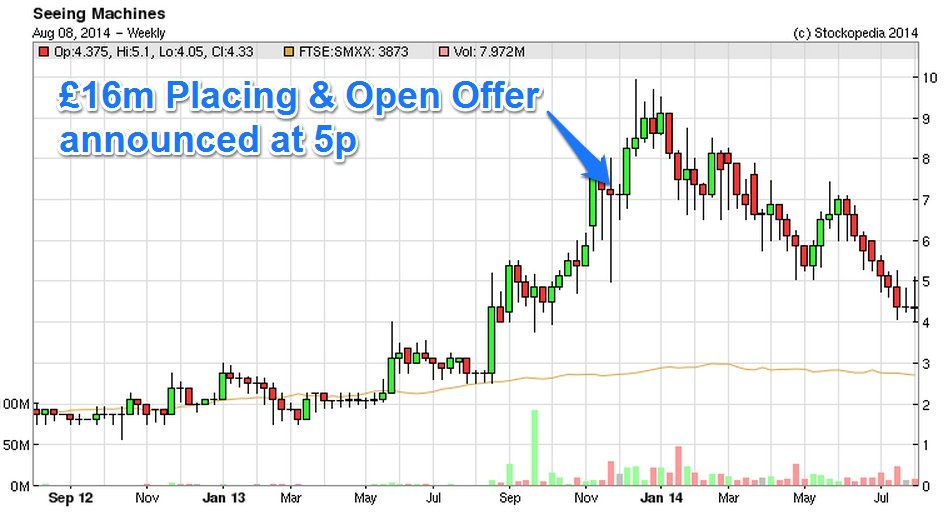
There was considerable excitement around this company late last year, which coincided with a Placing at 5p. The size of the Placing grew rapidly as there was so much investor appetite for it, and the company ended up raising £16m, which was far more than it had initially hoped to raise.
As a result, the business plan has been completely changed. Instead of being a small, lean operation that was set to move into profit, and had its R&D funded by partners, it has now become a more heavily cash burning, more blue sky company. This seems to have (understandably) scared off some investors, and of course the stampeding herd of speculators who were so active over the winter of 2013/14 are nursing their bruises in a corner somewhere at the moment, after practically all speculative stocks have sold off considerably since Feb/Mar 2014.
A series of positive announcements about business partners, etc, have been issued in recent weeks, including one today about a JV with a S.American company. There has also been a very interesting announcement about the potential roll-out of the technology into trucks, being trialled by a S.African insurance company. To my mind that's probably the most exciting development, as if this trial is successful it could lead to insurance companies eventually requiring the fitting of the Seeing Machines product into cabs, since it prevents accidents.
In the current market, nobody is interested, the shares are just drifting down regardless of what announcements come out. However, in my view this type of sell-off is an ideal opportunity to pick up companies that have been putting out good news, and in this case is now less than half the price it was 8 months ago. Plus it's cash backed (for the time being anyway).
So at 4.25p per share it's looking attractive again, in my opinion. Sooner or later another speculative surge will occur, and people who like the story will rush to get back in again once it's moving up - have you noticed how people only seem to like buying shares that are going up?! Personally I like to buy before they start moving up, once the valuation is right, as you can buy as many as you like at the price you like.
This share is speculative obviously, so not for everyone. However the cash backing, and increasing sales, mean that it's a proper growth company, not completely blue sky. I have held these shares continuously for about a year in my long term portfolio, but have now started buying them for my shorter term portfolio too. DYOR as usual.
Looking at the chart, maybe I should wait until it hits 3p before buying more, but given the large fundraising at 5p in Nov/Dec 2013, I suspect that 4p might possibly be at or near the bottom for the share price. However, that depends on what other people in the market decide to do, so it's just a guess on my part really.
Hyder Consulting (LON:HYC)
There's even more good news for shareholders in this construction consultancy group.
An agreed cash takeover bid for the shares at 650p was announced on 31 July. However, that offer has now been trumped with a 680p cash offer from a Japanese competitor. So it remains to be seen whether the original Dutch bidder, Arcadis will raise its bid further?
a very nice position to be in for shareholders though, having two cash bidders in a bidding war.
We're all done for the day and the week now. Thank you for reading & commenting.
I shall be jetting off to Greece in the early hours of tomorrow morning, for a week in the sun. However, morning reports will continue to be submitted by laptop, from my poolside location on the island of Paxos! Although they might be a little shorter than usual if I have a session on the Ouzo!
Regards, Paul.
(of the companies mentioned today. Paul has long positions in PURI and SEE, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
PURI: The CEO has just picked up 150k of shares for £56k or so..... Got to be seen as a positive sign....
http://www.investegate.co.uk/puricore-plc--puri-/rns/director-dealing/201408121149569031O/
yes... but on his salary, he should be able to afford it!!
Did anyone dial into the Puricore update? was away in a meeting so missed it unfortunately
Hi. I did listen to the Q&A which were interesting. I think they are considering delisting to save costs.... It's available on the website I believe. Please let me know what you think. Thanks.
Thanks bsharman - really curious about the wage side as this was the key bit as I dont know many that will slash their own wages... Will look at website soon and come back to you...
Pete
The Q&A session circled the issue but nobody asked about salaries directly. Someone was very keen to point out that 'admin costs' are hugely disproportionate and way too high and the CEO addressed this by talking about the cost of being listed and other fixed costs. I thought that they were considering completely de-listing but in hindsight and after speaking to Paul I realise that this probably means dropping down into aim. He did not address the wage cost at all - which means there is unlikely to be any changes made... which is disappointing to say the least!
British politeness comes through again - I wish I was on the call to ask the question directly... Its the only fear I have - but someone has bought a few today and price trending northwards so hopefully it will all work out
It will all depend on whether the new business structure and operations work, They are hiring more sales staff, whose cost will be directly related to the sales they create apparently. Let's wait and see what the strategy is, when they release it in Q4 and hope they don't waste the cash in the meantime!
Not sure Slater still holds xlm its not shown in his top ten holdings for May and June
Hi, I don't think they were ever in his top ten holdings.However on the 27th of March Slater's fund went above 5% of XLMedia (LON:XLM) and there have been no notification since - so he still holds.
Paul,
I thought you didn't invest in overseas companies?
Puricore is US based and now having sold endoscopy they have zero UK business. Its not a comfortable investment for me because management are difficult to contact and I think they are too stuck up with their own interests. The salaries of the board are horrific for little shareholder return. This says it all
http://www.independent.co.uk/news/business/news/investors-up-in-arms-over-puricore-bosses-pay-8650593.html
There is a big delisting risk in my opinion.....
I2015
Hi Investor2015,
I'm fine with US companies Listed in the UK, which have a track record of being Listed here for several years. So that isn't a significant concern for me.
Mgt salaries - yes they are too high, as mentioned in my report, so I agree on that. Shareholders need to put pressure on there.
De-Listing - not a big risk, as the shareholder base is fragmented, and Invesco have a 29.4% blocking stake. So them, together with smaller investors, can block any attempt to de-List & sack the management if necessary.
De-Listing is only usually a big risk where the shareholdings are tightly controlled by management and/or people close to management. That isn't the case with PuriCore.
As alluded to in my report, the clock is ticking for management now I think. This is their last chance to either get it right, or return cash to shareholders. It's a special situation now, not a regular investment, so I completely understand how it will not appeal to most people.
Regards, Paul.
"( ICT is apparently the new TLA^ that we should be using to describe IT that also involves communications)"
ICT isn't new. For more than a decade, it has been the term that schools and school exam boards have used for the curriculum subject that should have been called "secretarial skills using computers" or "how to use MS Office". ICT got such a bad name that the universities and professional societies lobbied to get a new curriculum with a new name. From this September it's called Computing, and involves real programming and a bit of Computer Science.
So any company in the IT industry that calls itself an ICT company is out of touch - which is a dangerous place to be in an industry that looks more like a fashion business than the professional engineering business that it ought to be!
ICT is not only not new — it's not even a TLA! At least to my knowledge people say "I — C — T" as in "eye see tea", not ict, as in predict. So it's an abbreviation, not an acronym (which literally means a word derived from the initial letters of a group of other words, and spoken as if it were a word).
TLA for that matter, though it might stand for Three-Letter Acronym, is itself an abbreviation, not an acronym (which would be virtually unpronounceable).
Interestingly, for some reason that I have never been able to fathom, Italy is the world centre for acronyms. There they speak virtually every group of letters as if they were words, while in the UK we tend to say the initials. So here we say "R – A – C", for example, while in Italy they would say "rack".
Well, one has to take one's mind off what's going on in the markets to help avoid the temptation to sell everything!
Good weekend to all
Hi Paul -
From time to time there is discussion here about Chinese companies and the large health and wealth warnings against investing in them.
I have of late burnt my fingers with couple of Israeli tech shares. Is there a similar problem(s) with these companies as well? There have been a few IPOs of Israeli tech companies this year. I have no data to back this, but have a feeling that Israeli companies have fared far worse than the average for this sector. Would be interested in your or other reader's views. (By Chinese/ Israeli companies I mean companies that have an AIM listing but in all other respects operate from China/ Israel.)
Regards, Ram
Hi Ramridge,
In my view it's best to steer clear of all overseas companies Listed on AIM. So many of them are overhyped junk that it's like trying to find a needle in a haystack. Sure, you might miss the odd good one, but you'll avoid dozens of crap ones.
The only Israeli stock which made me any money was called Pilat Media, which had a good track record, and I roughly doubled my money on it. It was then taken over, so it could have been a 3-bagger. So that was a genuine company, but I also made a horrendous loss on an Israeli CCTV company years ago.
The problem with these overseas companies, is that AIM tends to attract dodgy companies from overseas, as it's completely unregulated really - such regulation as exists is ineffective, and nobody gets punished when investors are ripped off. Sometimes things will work out, but overall, in my view it's fraught with risk, so why bother?
I fully accept that UK business practices can be pretty sharp too. Although I understand the business culture here, so I know that usually very few people will directly lie to my face. They will lie discreetly, and by omission, but you can spot that a mile off from their body language, and from their reluctance to put things in writing, etc. Also you can speak to & visit people in the UK easily, whereas with overseas companies you don't really know if any of the assets exist at all, and when you telephone, everyone stops speaking English when things go wrong.
People greatly under-estimate political risk too. Just look at what's happening with Russia, in the M.East, etc. Shares in companies that operate in those areas could easily become worthless overnight if assets are seized, etc. Again, why take the risk? There should be a very large discount for overseas political risk in less stable regions, in my view.
Each to their own, but in my view, as we've got several thousand companies to choose from in the UK markets, why not screen out whole chunks of riskier stuff, with some simple rules like geography, strict Bal Sheet rules, etc.?
There's a whole industry in London to hype up & List many speculative shares, continue hyping them in return for fees, but remember we're the cannon fodder that they rely on to buy these things, and we take the losses for the majority of these speculations which fail. Hence why I think it makes sense to refuse to play that game, other than on my terms!
Regards, Paul.
Hi Paul - Excellent advice. I think I will frame it and keep it next to my laptop, so next time I get the itchy finger to invest in say something like XL Media (sold it yesterday nursing a big loss), it will slap me in the face.
Thanks, Ram
Hi Ram, XLMedia has been beaten down on no news and I will therefore await the update in September. Despite reservations of holding a 'foreign' company I am impressed with the shareholder list which includes Hargreave Hale and Mark Slater, who spend much time and effort in due diligence before making an investment.
WELP 44.86%
Israeli VC Partners LP 10.11%
River & Mercantile Asset Management LLP 5.60%
Slater Investments Limited 5.23%
BlackRock Investment Management (UK) Limited 5.01%
Miton Asset Management Limited 4.04%
Investec Asset Management Limited 3.39%
Inflection Point Investments LP 3.23%
Hargreave Hale Limited 3.10%
Hi bsharman - The fact that a company has an impressive list of institutional shareholders is no comfort blanket. Witness Quindell and recent IPOs where a number of 'respected' fund managers have burnt their fingers. The herd effect is evident with small PIs and large fund managers.
In any event good luck with XLM; I bailed out yesterday.
Regards, Ram
Cheers Ram, I agree with you in part and this is one of my investing weaknesses. I have too much confidence in companies which 'star' fund managers hold. After doing my own research I see this as a validation to my decision - not a means to invest (if you understand what i mean..) I seem to recall that Mark Slater also invested in another Israeli IPO this year which failed spectacularly but I can't remember the company name...
Hi,
I agree that it's reassuring to see star fund managers in particular stocks - I like to see Hargreave Hale, Miton & Henderson in small caps, as they know what they're doing & have good track records.
However, don't imagine that fund managers do intensive Due Diligence on stocks, as many do astonishingly little, but will happily write multi-million cheques of their clients money, without even having read the Annual Report.
I've had lots of small cap managements tell me that I ask more well-informed questions, and have done far more research, than hardly anyone they meet in the City.
Regards, Paul.
Hi Ramridge,
I think another key consideration is before doing any other analysis on a company, is to ask;
"Are earnings sustainable?"
All too often I think small companies are Listed on AIM, but are just a flash in the pan. That is particularly the case where they obscure the business model, or dress it up in fancy language. Quindell (LON:QPP) very much did this, and the reason was obvious to me, as I have repeatedly posted for well over a year, but the investing community is now catching up with the reality that it's just an ambulance chasing claims business, that has booked revenues aggressively on whiplash claims.
That bonanza is coming to an end, as insurers & Govt tighten up. So now they're moving on to industrial deafness & other things like telematics where they can spin a good yarn about huge profits.
The crux however, is that the underlying business has profits which are not sustainable. Therefore you cannot put it on a conventional PER at all, you just have to see it as a flash in the pan.
So to my mind, properly understanding the business model, and working out whether the profits are sustainable, should always be the first step when researching any investments. I've avoided a helluva lot of junk in the last year or two by applying this simple procedure - it kept me out of Blinkx (LON:BLNX) for example - as it just wasn't clear where the profit was coming from, or how they managed to make so much money. The answer seems to be that it was unsustainable (probably), we don't know for sure yet.
Simple businesses, where you can see exactly how they make their money, are usually best, in my view.
Regards, Paul.
Hi Paul. There is a PuriCore (LON:PURI) conference call today - I might try and listen in and see what the management have to say. I will be sitting tight until the strategy document is released in Q4 and it will be interesting to see how they propose to grow the business and cut costs. I agree 100% that the executive team all need to take pay cuts and I hope that someone asks that question on the call!! I did think that the reason revenue is down is because they are moving away from capital (one off) equipment sales to consumables and therefore increase the recurring revenue stream - which is sensible. As you say, we need to see some contract news over the next few months and a bit of cash back would also be nice!