Small Cap Value Report (8 Dec 2016) - MUL, CTH, SPD, PCF

Mulberry (LON:MUL)
Share price: 1096p (-0.3%)
No. shares: 60m
Market cap: £658m
Results for the six months ended 30 September 2016
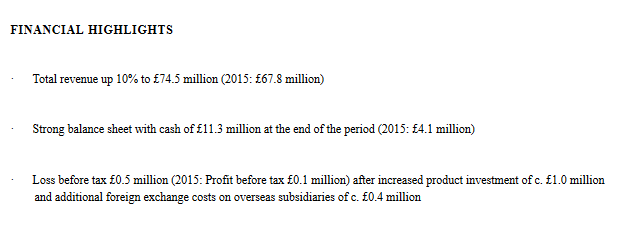
I hope you'll forgive me for venturing into mid-cap territory with this richly-priced luxury handbag designer.
Current trading: Besides the above figures to end-September, we also get an update on trading to the start of December. Total retail sales are up 4% (or 3% on a like-for-like basis).
Creative Director: Mulberry's new Creative Director has released his first collection of nine bags. He was hired last year, having previously been at Louis Vuitton. The collection is said to have been "well received by our existing customers and a new audience".
The success or failure of this type of business rests to a large extent on the inspiration of the designers. So it's important to have a look at who is behind the wheel in this regard.
While product diversification can reduce the risk, Mulberry is quite concentrated. Last year, leather accessories were 90% of sales, of which bags were more than 70%.
So the stock is almost a "pure-play" on a few handbags!
Related party agreement: Mulberry has a complicated relationship with Challice, its 56% shareholder. I don't think there is anything untoward, but the relationship is worth studying. Challice is going to own a minority share of Mulberry's new North Asian business (Mulberry will own 60%).
My opinion: I think that this company is going places, and the market cap might not be as overvalued as it appears at first glance. In FY 2012, on sales of £169 million, the company generated net income of £25 million (context: current market cap is £658 million).
That year, its H1 sales were lower than those which have just been announced.
Of course, things were different back then: gross margin was 66%, whereas it is currently 59%. Gross margin is still slipping, although the company says that this is just a short/medium term effect while the company invests in new product development.
Unfortunately, this is still far from certain. I'd have no desire, in its current stage of development, to bet my own funds on this company getting the formula right and recovering to prior performance levels. But I'd suggest that it's worth keeping an eye on, just in case things to start to pick up!
 Caretech Holdings (LON:CTH)
Share price: 306.5p (+5.3%)
No. shares: 64.2m
Market cap: £197m
Preliminary Results for the year ended 30 September 2016
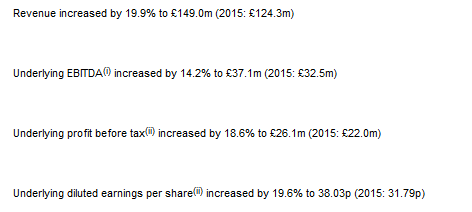
Excellent results from this provider of social care, which have been greeted positively by the market.
Final Dividend: Raised to 6.25p (from 5.6p). Full-year yield on current share price is 3.0%.
Property Portfolio: £304 million valuation, following acquisitions.
Freehold/Leasehold: Caretech raised £30 million by selling the freehold of 41 properties this year, so that it will have to pay a rising ground rent on these properties every year from now on. Apart from those rental payments, the deal is unlikely to affect existing shareholders, unless they are very young (the leases have a 150-year term).
Outlook: No concerns raised in the outlook statement.
The coming year shows every sign of being good for health and social care providers and especially for those with an established reputation for quality and innovation.
This year there has been significant policy development and we see some indicators that local authorities have recognised the need to maintain, or grow their social care budgets.
My opinion: Underlying diluted EPS of 38p looks cheap at first glance, but the risk of carrying £156 million of debt must be factored in here. That debt is worth about 240p per diluted share of the company.
For what should be an unexciting sector, I am impressed by the size of the operating profits (£30 million) and operating cash flow (£38 million, pre-working capital) which were generated on the company's assets (c. £260 million of PPE at the start of the year, much of it funded by debt).
So it looks like a high-quality performance to me, which could lead to further growth as the company reinvests its earnings this year. Depending on your view of the outlook for the social care industry as a whole, and your willingness to bear this company's financial risk, it could be worth further investigation.
Share price: 288p (-8.5%)
No. shares: 593m
Market cap: £1,708m
Interim results for the 26 weeks to 23 October 2016
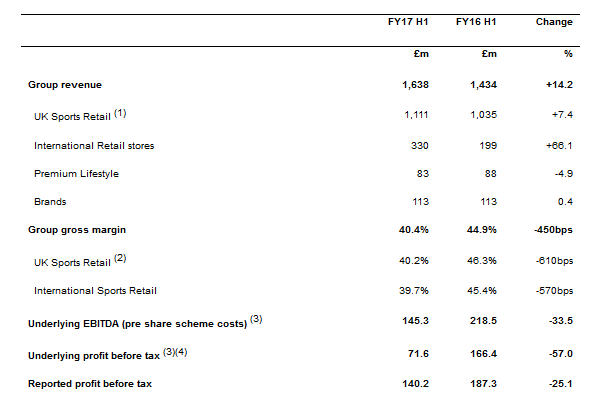
Considerable share price weakness today.
It's hard to find the positives in this statement, though of course most of the weakness had already been priced in over the course of this year.
The headwinds to underlying performance are given as follows:
o The deterioration of gross margin as a result of the devaluation of the Pound ("GBP");
o A requirement to increase the Group's inventory provisions;
o Increased provisions for onerous leases in International Retail; and
o Increasing investment in our people
While the first of these factors is beyond the company's control, the rest of them highlight prior mistakes or unsustainable business strategies.
So it's fair that the company's performance takes a hit this year.
Worryingly, the effects of the pound devaluation are likely to stick around for as long as exchange rates remain where they are. Indeed, the outlook statement is as follows:
The Group is currently facing a number of strategic
challenges across its business model and operations, and currency
headwinds, which we expect to continue to adversely impact financial
performance over the medium term.
Net debt: reduced to £72 million (cash of £188 million minus borrowings of £260 million).
Debt-funded property investment: Sports Direct has >£500 million spare capacity on its £788 million facility. Yet it says is planning to invest >£300 million per annum on property investments over the next 2-4 years.
The size of that program seems far too large to me. The market cap is £1.7 billion, and they might spend £300 million per annum on property for 2-4 years? Wouldn't there be other ways to generate shareholder value than this? Even if purchases are offset by sales, it suggests an enormous amount of change.
My opinion: Prior to this morning, brokers were forecasting EBIT of £145 million for this financial year. This will be nudged a little lower now, to the bottom end of the range of expectations.
The present market cap provides a cheap entry point against likely EBIT but I could not sign off on the company's property strategy. Based alone on what I know about this strategy, I could not consider investing here.
 Private & Commercial Finance (LON:PCF)
Share price: 29.25p (-2.5%)
No. shares: 170m
Market cap: £50m
Preliminary Results for the 18 months ended 30 September 2016
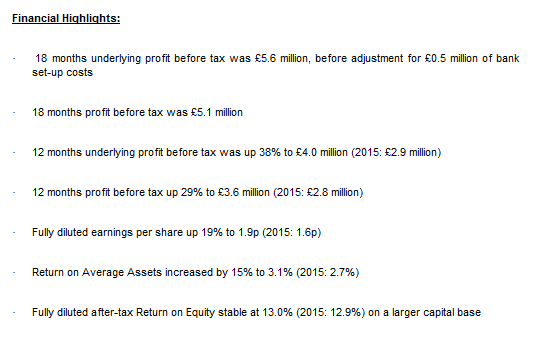
Complications here due to an accounting reference change.
Thankfully, the company provides pro forma numbers for 12 months to September 2016 and also September 2015. So I'll refer to them in what follows.
This share price has increased ten-fold since its low in 2012.
PCFG provides finance for vehicles (everything from classic cars to HGVs), as well as plant and machinery. According to their online application form, they expect most loans to be at an APR of 10.9%.
In an exciting move for investors, the company announced yesterday that it has been approved by the PRA and FCA for a banking license, and is planning to accept deposits in summer 2017.
This could have fantastic implications for investors. Bank deposits are a very cheap source of financing. Deposits can replace existing sources of financing but also, as the company states that it intends, provide an opportunity to profitably scale the business. It should be able to compete for retail deposits while maintaining a healthy spread against their loan APR.
As for the current performance of the core business, it appears to be doing fine. Return on assets improved to 3.1% from 2.7% (financial companies like this are far more interesting to me than banks, which only tend to earn around 1% ROA).
Impairment charge: record low impairment charge of 1.0%, so that portfolio growth has not been at the expense of credit standards.
Dividend: The company's first dividend declaration in 13 years. The amount is 0.1p, with the intention that it will be progressive.
Outlook:
We have delivered excellent profitability in the period as the result of
a growing portfolio, combined with further gains in portfolio
performance and a continued focus on margin and costs. By establishing
itself as a bank the Group will, for the first time, be on an equal
footing with its competitors with regard to funding cost. We therefore
see opportunity and do not expect the forecast lower economic growth in
the UK to undermine our current strategy.
NAV: Balance sheet net assets are currently £24.7 million, or only about half the current market cap. However, the company also has £28.2 million of unearned finance charges which are set to be recognised in future years.
My opinion: I like this share. Of course, there is execution risk when you open a bank, and rising interest rates might make it more difficult to compete for retail deposits, unless the spread can be passed on to customers (who might be struggling in a rising interest rate environment). But I would still consider this company to be attractively priced, given the excellence of the financial performance and the opportunities opening up for it next year.
That's it for today, thanks again for tuning in while Paul has fun in the sun.
Hopefully these notes are stimulating your own creative, analytical juices. There are no Buy/Sell recommendations here - only one person's point of view.
Until tomorrow,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
What I found most bizarre about the Sports Direct announcement today, was the narrative being full of gushing talk about "people", and how important they are, etc. When we all know the reality is that they use the cheapest possible labour, treat them badly, and overall don't give a monkey's about people!! Although the store managers bonus scheme has been spectacularly good. So maybe I'm being too harsh?
Also this bizarre section, where the management question the motives of people who criticise the company - which just sounds all wrong - more like management shirking responsibility for their own arrogance & nepotism;
I have no doubt that the extreme political, union and media campaign waged against this Company has not only damaged its reputation and influenced our customers, it has impacted negatively on the morale of our people. I begin to question whether this intense scrutiny is all ethically motivated. One of the most damaging consequences has been for the very people our critics supposedly support. The Board accepts responsibility for our shortcomings, but there has also been disproportionate, inaccurate and misleading commentary. The individuals at the heart of our organisation are blameless. They are increasingly upset and angry at the barrage of detrimental comments about the company which in their view is unjustified. On behalf of the Board I thank every member of staff for their continued loyalty during such testing times. We recognise the massive contribution you have made to the success of this Company and look forward to less stressful times.
I think the reality is that the public absolutely detest arrogant, flamboyant egomaniacs like Mike Ashley & Philip Green. They damage their own businesses & reputations through their appalling behaviour on multiple levels! Hence why few people are prepared to give them the benefit of the doubt when stuff does start going wrong.
Keep up the good work Graham! I'm finding it enjoyable, if weird, to be a reader of the SCVR!! Am enjoying my holidays though - feels so odd to be sunbathing in December!
Best wishes, Paul.
Graham, can I put in an early request for your views on photo me [PHTM], which reports its interims tomorrow. Its high depreciation charge makes it appear more expensive on a pre tax basis than the cash reality, I think, but your view would be appreciated
Graham, I join others in thanking you for filling in for Paul this week.
No need to apolgoise for venturing into mid-cap territory. Perhaps you could start a Mid Cap Value Report :P
Graham
From reading your regular articles published on ShareProphets, I've held your clear concise writing style and company analysis with the highest regard.
And your informative and enjoyable SCVR's, here on Stockopedia, can only have enhanced further your excellent reputation among the private investing community.
Many thanks.
Sports Direct has hit a real head wind by their own behaviour, even the chair is the ex-drugs czar, all very odd and probably worth keeping a barge pole away.
Hi Graham,
Any thoughts on probably one of the the biggest fallers in the FTSE Small Cap universe today the Lloyds Underwriter Novae (LON:NVA). This share had(!) a very high StockRank and a very healthy looking StcokReport but has clearly been battered today. I know Insurance company accounts are a bit unusual but after the September trading update (only Nov 9th) this seems a very exaggerated reaction?
Thanks Graham for your weeks coverage, much appreciated and enjoyed reading your thoughts on the companies you've covered.
Whilst I'm here, I'd also like to point out to my fellow readers a first trading statement since listing of Van Elle Holdings (VANL). In-line and confident so not the all too often wheels coming off immediately after listing but an encouraging start.
I like them, they're profitable, growing and are a niche contractor in construction. Beneficiary of infrastructure projects? Based on the admission document I thought they were reasonably priced too. They seem to have listed (on AIM) for reasonable reasons, to raise capital to pursue future opportunities and to allow the 72-year-old company founder to part sell down his stake. There's probably also an element of IHT planning involved too?
As they've only recently listed, the Stockopedia computers haven't got much on them yet but it might be worth a look. I do hold them.
Simon.
also a Van Elle Holdings (LON:VANL) holder, as you say the admission doc was pretty good.
also in Luceco (LON:LUCE) which is another new one.
Thanks to all for the suggestions and the encouragement, it means a lot to me. Deciding how many stocks to cover is a tricky balancing act, because I want to add value by putting forward a point of view and some analysis every time. The comments section is very helpful, so that the report gets directed towards the stocks where there is most demand (e.g. Sports Direct and Private & Commercial Finance (LON:PCF) today).
Steve, I would need more time to digest what is going on at XLMedia (LON:XLM). I see the share price is back up 6% today so maybe it's just a little bit of turbulence you're experiencing!
Julian, you are not the first person to request a comment from me on Ab Dynamics (LON:ABDP). At least I know now that there is demand for it! Sorry I can't add value on it today.
S&U (LON:SUS) would have been thematic given today's news on Private & Commercial Finance (LON:PCF). Hopefully you found the Private & Commercial Finance (LON:PCF) comment of some interest at least.
Graham
Its funny isn't it, you can reasonably suggest support investing in quoted family business as a strategy, because to a greater extent (one hopes) they are more aligned to shareholder interests, and have a long term and a generally conservative management outlook.
On the other hand a public company such a Sports Direct, which is happy to have various family members in aligned 'parasitic' business arrangements has arguably a different feel it. I think this is because they don't feel like arms length arrangements (even if they are) and those family members are not really part of the declared share holdings, but in effect have a private dividend, subject to providing the services they have been set up for.
It is less part of the upfront control of the company, and given the substantial holding of Mike Ashley, questions the true independence of the board in being able to rationalise the various conflicts of interest.
Still I guess by now, if you don't know who rules the roost in reality, you haven't really been paying attention!
Hi Graham,
nice to see that the good ship SCVR is in safe hands
any thoughts on yesterday's dramatic fall in XLMedia (LON:XLM) share price. Reported that the CFO sold his entire holding of 123k shares.
Have to say my immediate reaction knowing the slightly opaque trading that is XLMEDIA is that it was tied in some way to the FCA announcement on spread beet ing firms like I group?
I am aware that Paul is not a fan of XLMedia (LON:XLM) but wonder if you have a different viewpoint
Many thanks
Steve
Hi Graham
Thanks for standing in for Paul (so ably) during his well deserved holiday.
1. If you get a chance could you have a look at S&U (SUS) who have issued a trading update today. I have held them for some time and they have been a great investment. The shares have sold off a lot over the last two or three months. Today's trading update looks very good and specifically says that they know of no reason for the drop in the share price. My only thought is that the market is worried about the possibility of a decline in (used) car sales - S&U provide finance for used car sales. This is another financial stock so also not covered by Paul.
2. Also do you have any thoughts on AB Dynamics (ABDP)? They have just completed a placing and are also making an open offer to existing shareholders. I have only just bought a small holding to encourage me to do some more research. So I don't yet have much of a feel for the business or the numbers.
Many thanks
Thanks for another fine report
Thanks for these great articles, Graham. I guess the companies covered pick themselves to a certain extent but three bargepole jobs to start for me - the first on valuation, second on sector and third on Mike Ashley! A couple of things I've noted today amongst the companies I follow:
1. A nice slightly ahead of ahead of market expectations announcement from Amino Technologies (LON:AMO) on both earnings and cash.
2. Some chunky buys by the CEO and Chairman at Gattaca (LON:GATC) which are worthy of note.
All the best, Si
Cheers simoan. Hopefully #4 wasn't too bargepole for you! And thanks for pointing out those other two.
Graham
Thanks for the comments.
Sports Direct is in now and I'm looking at Private & Commercial Finance (LON:PCF) next.
tads, sorry I won't get to BNN Technology (LON:BNN). Maybe someone else will have an opinion they can share with you here in the comments.
Thanks,
Graham
Hi Graham
Excellent analysis on Private & Commercial Finance (LON:PCF) - Cheers
Re Secured Property Developments (OFEX:SPD) I think Mike Ashley just loves playing the bad guy, from today's RNS which also outlined some very poor results ;
"To facilitate efficiencies relating to the use of management time and the pursuit of the Group's strategic priorities, the Group will be taking delivery of a corporate plane in the coming weeks. It will form part of the Group's corporate assets and facilities, which include:
· A corporate helicopter which is used by senior management, employees and our business partners on a regular basis to visit and connect with our people across our 500+ sites and partner offices throughout the UK;
· A fleet of corporate vehicles which are used to transport employees and business partners to our sites across the UK; and,
· The Best Western Lion Hotel in Worksop and several houses in and around Shirebrook which are used to accommodate employees and business partners on their work visits to our Shirebrook campus. Employees, including the Chief Executive, whose work base is Shirebrook, but who choose to use Company accommodation, pay rent."
And;
"The Company has entered into an agreement with Double Take Limited ("Double Take"), a company owned by Mash Holdings Limited (of which Mike Ashley is the 100% shareholder) and in which Matilda Ashley, Mike Ashley's daughter, is a director. Under the agreement, Double Take licences the Group the exclusive rights to the cosmetic brand, SPORT FX. No royalties or other fees are payable to Double Take for these rights until September 2019 at the earliest, when this fee arrangement will be reviewed on a going forwards basis. It should be noted that the Group (rather than Double Take) owns the rights to SPORT FX for clothing, footwear and sports equipment. This is disclosed in Note 10 to the accounts.
Commercial arrangements
The Company has a contract in place with Barlin Delivery Limited, a company 100% owned by John Ashley, who is the brother of Mike Ashley. This contractual arrangement was entered into under market terms, and makes good commercial sense for the Company and its shareholders.
MM Prop Consultancy Ltd, a company owned and controlled by Michael Murray, continues to provide property consultancy services to the group. MM Prop Consultancy Ltd is primarily tasked with finding and negotiating the acquisition of new sites for both our larger format stores and our combined retail and gym units but it also provides advice to the Company's in-house property team in relation to existing sites both in the UK and in Europe.
MM Prop Consultancy Ltd fees are linked directly to value creation which is determined by the Company's non-executive directors who independently review performance bi-annually with a view to determining, at their absolute and sole discretion, the quantum of the fee payable. Under the terms of the agreement with MM Prop Consultancy Ltd no fees are payable until the earliest of 30th September 2018 so that the Company's independent non-executive directors have a sufficient amount of time to assess performance."
He really doesn't care does he? Oh and the share buyback is canned as well..sheesh
Hi Graham
Great work in Paul's absence - thanks for filling in.
Appreciate your thoughts on the Private & Commercial Finance (LON:PCF) results today. £48m mkt cap
Ta
I am also interested in PCF but generally financial stocks are outside Paul's remit. I am puzzled by today's share price reaction to what appear to be excellent results following the news yesterday of the granting of their banking licence.
Some costs may be incurred over the next half year as licence requirements are met but this would appear to be trivial compared to the good news. Maybe this long anticipated news is already in the price or perhaps the threat of rising rates to U.K. Borrowers is scaring investors. Possibly the overhang of its Bermuda shareholder is a worry. But overall it seems that hard work is required to make this share look bad.
I am also puzzled by the results but the "market" often seems to be a knowledgeable guide to what a share is worth. To my mind, the overhang could be;
- the interest rate cycle finally moving off the bottom as you say (I note that HSBC have just removed some of their more attractive rates)
- banking licence - Private & Commercial Finance (LON:PCF) diversifying into an area where their expertise is unproven
- bad press - finance providers who lend to anyone but prime lenders may need to find provisions for potential bad debts
I trust I'm wrong am as PCF is still attractively priced IMO. Performance over the last few years has been stellar and holders start to get a divi too!
Quick point on CTH - significant asset backing to offset the debt, as the group own most of their own premises. I don't hold.
Cheers,
Steve.
Any opinion on £BNN?
Not a small cap, but any thoughts on £SPD