Small Cap Value Report (8 Jul 2014) - SNTY, JWNG, CAMB, SDM

Good morning!
Synety (LON:SNTY)
This is the most interesting RNS of the morning for me, as I have high hopes for this small growth company.
Generally blue sky shares make bad investments - very few of them succeed commercially, and virtually all are over-hyped and hence over-valued. I've lost count of the number of times people have said to me, "This is going to be HUGE!", and it then turns out to be a commercial flop.
However, I like a good story as much as anyone else, but I look for very rapid sales growth combined with a good story. After all, if a company has sub-£1m turnover, and cannot generate 50%+ sales growth from that level, then what they are selling probably doesn't appeal to potential customers. Even if a product is good, it can be impossible to overcome the inertia of an established product from large competitors.
Therefore rapid sales growth needs to be combined with a product that is a no-brainer for customers - something that is not just an incremental improvement, but something that is obvious value for money, and provides a much better product or service than the one currently used by target customers.
Synety (LON:SNTY) ticks those boxes for me. It's cloud telephony, which integrates into CRM systems like Salesforce. Not only does that streamline making & receiving telephone calls with customers, but they are also recorded & instantly retrievable through the CRM system. It means that companies that need to record phone calls with customers can now do so without any capex at all on switchboard-based phone systems.
At the moment Synety have very little direct competition, so this is a land grab whilst they sign up customers of CRM systems such as Salesforce, Bullhorn, and others. The CRM market is very fragmented, so there are lots to go for, and integrations are fairly straightforward apparently.
So I like the company, and think it has considerable potential. Although as with all early stage growth companies, it's difficult to value, as on current performance it's loss-making, so you have to make assumptions about the future in order to value it at all.
This morning's update on KPIs is encouraging news in my view. I approve of the company's policy of releasing KPI numbers quarterly, which is exactly what you need with a rapid growth company. The key measure is annualised recurring revenue, which has risen 98% year-to-date, to £1.72m. So still early days, but that's exactly the type of very strong growth rate that I look for. I like the way the company is now reporting % growth rate against last year, as the previous quarter-on-quarter growth was meaningless. Although cynics might say that the change in reporting is because Q2 growth against the previous quarter slowed from Q1 growth - which is bound to happen because of the way the arithmetic works. You cannot continuously compound any growth numbers over short time frames, as even a static growth % rate would give you exponential growth!
Bear in mind also that the company has been setting up its USA operation, which is now already live and trialing customers, which must have been a major distraction for management time at such a small company. On top of that the company relocated in the UK to new offices in May, again a major disruption, so to continue growing sales strongly whilst that is going on, is impressive.
If they crack the USA, then the growth would go through the roof, and bear in mind that the CRM companies pulled Synety to the USA because their UK subsidiaries liked the UK product so much (many UK CRM companies are owned by American groups).
On the USA these snippets from today's update sound positive;
...in the US we are already receiving greater lead flows from Salesforce.com and Bullhorn CRM than we do in the UK.
"The board is increasingly confident about the exciting future the US business represents for Synety."
The USA market is about 10 times that of the UK, so there should be some explosive growth over the next year hopefully.
It's not for widows & orphans mind you, this type of share has to be seen as high risk, and difficult to value. The valuation is very much dependent on growth continuing. If competitors enter the space & slow them down to a crawl, then we could probably more than halve the current valuation. On the other hand, if growth accelerates as the USA operation builds, then I think this could quite possibly be a 3-4 bagger, and maybe more longer term. Time will tell. As always please do your own research, which is especially vital for small, more speculative shares like this one.
The company raised enough cash for about the next two years in a Placing and (small) Open Offer a little while ago at 250p, which probably acts both as a support for the share price, and also a magnet, as the temptation to flip stock bought in the Placing is probably too tempting for one or two placees.
Bear in mind that revenue is good quality - it's monthly recurring revenue, and once customers start using the product apparently they are very sticky - ideal attributes. Synety's product is cheap too, typically £25-30 per month, per user, so once a customer is using it, there's nothing to be gained from them moving to a competitor. The phone call charges are at wholesale rates, which helps make the customers very loyal to Synety once they start using it.
I find the market price movement this morning perplexing - but perhaps some investors had unrealistically high expectations for growth? When was the last time you saw a small cap grow its turnover by 98% in six months? It's not something I see very often, hence why I'm so keen on this company.
Jaywing (LON:JWNG)
This is a new one for me, it's a digital marketing company based in Sheffield, with a market cap of £21.6p at 29p per share.
Results for the year ended 31 Mar 2014 have been issued this morning. The company helpfully provides a table to reconcile reported profit to adjusted profit, and an H1, H2, plus FY analysis.
The adjusted figures look OK to me, because the amortisation charge relates to goodwill, which is fine as that is a non-cash item. So the £2.3m figure for adjusted operating profit for the year seems a sensible measure of the underlying performance of the business.
I won't be investing here because the Balance Sheet is too weak - it fails my testing.
Net tangible assets are negative £8.3m, which is usually a no-no for me. I like to see tangible net assets, not net liabilities. Also there is too much debt in my opinion, which was taken on to part finance an acquisition last year. This results in current assets being only 76% of current liabilities, which is a long way short of my usual comfort level of 120-150%. There is long term debt too.
Too much debt, combined with a weak Balance Sheet, is asking for trouble in my view. It can work whilst a company is trading well, but if anything goes wrong, there is nothing to fall back on. So this one's not for me. There are no divis either, which is a big gap in my requirements - I like to be paid divis whilst waiting for a share to rise.
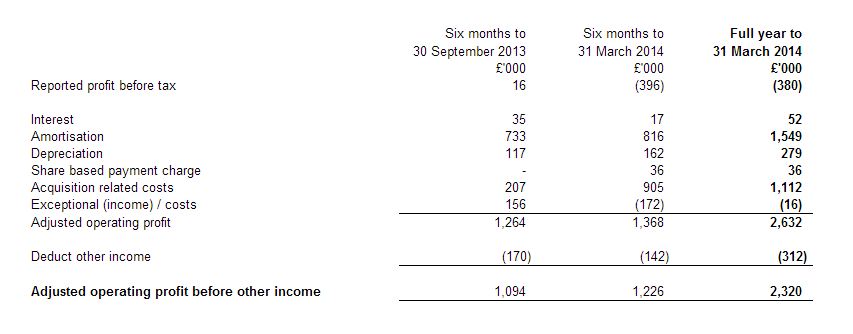
On the positive side, it's in an interesting & modern area - digital marketing, so there could be growth opportunities? Plenty of competitors too though I imagine.
On current trading the company says;
The start of the year has been in line with the board's expectations.
Cambria Automobiles (LON:CAMB)
There's an encouraging update from this growing car dealership chain today.
The key bit says;
The Board is also pleased to report that the Group's trading continues to perform well in a strong new car market and that it remains on track to at least match market expectations in the current financial year.
There is also news of a significant sized acquisition, of a Jaguar Land-Rover dealership in North London, from Lookers. The price is £10.5m, which is being financed from bank borrowings. That's fine in my view, as it includes a freehold for about a third of the purchase price, and I also very much like the way CAMB goes for freehold sites. That way shareholders gain the upside on the appreciation of the property, as well as profits from trading in it.
Remember that a turnaround specialist like Cambrian will increase the value of the property considerably when they turn around a struggling dealership. So to pass that gain over to a property company by leasing sites, would be ridiculous. It amazes me how so many investors have a complete blindspot about freeholds, and somehow think that owning them is "inefficient". That's crazy to me. If you can make money on a property as a bonus, then why give it away by leasing the property from someone else?!
This is another situation where buying these shares you are backing management. I was impressed with the CEO when he presented at Mello.
Stadium (LON:SDM)
This small electronics company issues a reassuring update, which says;
The Board are pleased to announce, trading in the first half of the year is in line with management expectations, and is significantly ahead of the equivalent period last year. Consequently, the Board remains confident about prospects for the year.
That sounds encouraging, especially when combined with an apparently very reasonable valuation;
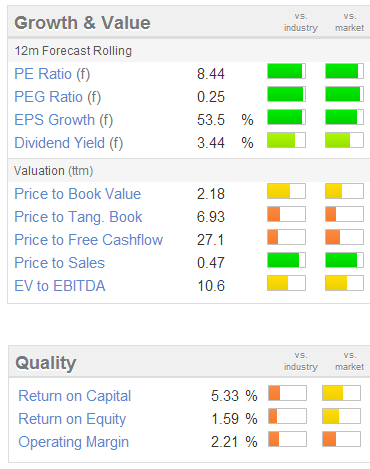
The problem here is the large overpayments being made into the pension fund, to tackle its deficit. This was £866k last year, a highly material figure for such a small company, as touched on in a previous report of mine here.
Although it is interesting to see that some pension scheme deficits are reducing sharply at other companies, which should be the case as yields rise on bonds in a recovering economy. So there might be an opportunity to buy cheap companies with pension deficits, in the expectation of those deficits melting away with time. Although they are still a big risk factor - as a huge potential liability could open up if there's another financial crisis, or rather when there's another financial crisis.
If you're relaxed about pension deficits, then Stadium might be worth a look.
I'll leave it there for today. There's one Placing today for me to update on Placing Watch, so I'll get cracking on that next!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in SNTY, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
If they crack the USA, then the growth would go through the roof
If I had a quid for every time someone has said something like that over the last 30 years, I'd be a very rich man! And it very rarely actually comes to pass.
This is a REALLY key issue for shareholders. Is there any competition in the USA and an unseen competitor about to emerge and whip away their growth opportunities (in the USA and elsewhere)? If there isn't then someone in the USA may notice them and conclude they'd make a nice bolt-on acquisition - but if there is then your hopes may be (as so often in the USA ) pie in the sky! And the US expansion may turn out to have imperiled everything.
I approve of the company's policy of releasing KPI numbers quarterly, which is exactly what you need with a rapid growth company
So do I - but you need to stay very alert....because, sure as eggs are eggs, sometime or another one quarter won't match expectations.
Emptyend,
This short video may address your concerns. It sounds like the Synety (LON:SNTY) launch in the USA has hit the ground running. The Chairman has previously said that selling their product is like "pushing on an open door", and that it was the CRM companies who pulled them into the USA.
Bear in mind too that mgt here are experienced people who've built up & sold businesses before, not some wet behind the ear dot.com trendies!
http://www.fmp-tv.co.uk/companies/synety-group-plc
Regards, Paul.
Thanks for the video link, Paul.
Bear in mind too that mgt here are experienced people who've built up & sold businesses before, not some wet behind the ear dot.com trendies!
Whilst that may be so, I am sure you could have said the same of the management of M&S, Stagecoach, Tesco, HSBC - and a number of much smaller companies.
I'm certainly not saying they won't/can't succeed - I'm just noting that there should be particular diligence on the structure of the US market and its dynamics, otherwise you may find in a few years time that they have made all the investment in the US but can't turn it into hard cash. OTOH if everything goes as planned/hoped then surely they would be a bid target?
Hi EE,
Synety (LON:SNTY) investment in USA is not huge, it's only about 15 people, of which 9 are customer-facing.
The beauty is that SNTY can leverage their relationships with the CRM cos to encourage them to sell the product for SNTY - because it's an add-on to the CRM systems, and sold within them (such as in Salesforce's app store).
The sales pipeline in the USA is already as big as in the UK, which is remarkable considering they are only in soft launch, with some trials underway. The Chairman is sounding increasingly confident about the USA if I think back to the presentations he gave at ShareSoc, in Brighton, and these latest videos. The tone seems to be firming on the USA potential in my view.
I take your point about mgt, but these guys are entrepreneurs. Different kettle of fish to corporate people at large companies, many of whom frankly are just good BS-ers & players of people politics.
Regards, Paul.
P.S. I should add that my interest in SNTY is long term, so I'm not saying there should be a huge re-rating right now. The share price is probably about right at the moment, reflecting risk & reward as it stands. However, if the USA takes off as hoped for, then you could possibly double or triple the valuation from here over the next six months. Equally, if the USA flops, then you could halve the valuation.
Hi Paul,
I take your points - all well made. But my concern would be whether the likes of j2global might choose to nip their growth in the bud if they start making inroads into the USA. It would be interesting to know how they view the space that Synety (LON:SNTY) are attacking.
Perhaps worth keeping an eye on the exit door, if the short term pans out as hoped? IIRC you made a decent reduction at the £10 highs with Indigovision (LON:IND) (after some prompting ;-)) and this seems to me that it may have similar investment dynamics (ie....good fundamental business and market which is there for the long term but it is important to be alert to exit opportunities).
Good luck.
ee
OsullivanB
Webpax (message 27 above) has provided some notes on Synety. These may assist?
I would also suggest that you look at the websites of some of the CRM providers - ACT, Salesforce, Goldmine etc. These will give you an overview of CRM and it may help you understand how Synety works with these companies.
CRM isnt a new concept and there were many CRM related companies that were over hyped in the tech boom of the late 90's which subsequently crashed and burned. It is wise to be cautious and to understand the nature of these highly speculative investments which consume lots of cash on the promise of future profits.
Thanks, intuitive and Webpax. That is enormously helpful.
Bernard
Thanks MV, no that's the only one at the moment.
Thank you Jon. I will try and reconcile your useful info with the KPIs given on the 8th July.
No problem intuitive6191. My full write up of the presentation is here http://www.webpax.co.uk/snty.pdf
- you may find it useful.
Kind regards
Jon
Webpax,
Those are excellent notes
If you do similar for any other meetings would gladly read
(Anything current? I couldn't access your main site - Perhaps DM if your inclined to!)
MV
"Their retention rates are very high"
This is quite an important statement. Are there detailed figures for customer retention? Any information or link would be appreciated.
Hi inuitive6191
Re retention rates. Quoting Simon Cleaver again from the Sharesoc presentation in May in the Q&A session:
What is customer retention rate?
"Retention rate about 94-95% - lost 23 licenses last month (one went bust which was 9 licenses) – they analyse all lost customers. However on a net basis they actually have negative churn as a lot of customers are increasing the number of licenses they take up."
Regards
Jon
Webpax,
Major point here is that they are "not going after CRM companies" .... yet!
Barriers to entry are being eroded every day - competition is coming
This is why I think Synety is an excellent trade - they will dominate early doors - but no staying power
As I said in previous discussions - I think they are a takeover target form SalesForce, Google
MV
MV
I disagree I think they will have staying power. Their retention rates are very high. If you're using their system and it's working well why switch? Their pricing is very competitive particularly around call costs as they are a telco as well as a software house. They make the bulk of their revenues from software so can afford to set call costs very low - in some cases companies can save more on call costs than the software is costing.
Also, If you already had a year or twos call records on the Synety platform imagine the hassle and cost of extracting all those call records and migrating them to a new platform.
I do agree though that they may well get taken over.
Regards
Jon
Hi MV,
Thank you for pointing out Torpio, while they have a lot of CRM's they only have one VOIP Company onboard (Twilio), who makes up these names? Twillo are a US based company with US based partners who use their API to create integration solutions much like Synety, to name a few partners:
www.datalot.com
www.ringdna.com
www.velocify.com
So Synety are by no means alone in this market place but it remains that you need a solutions provider to hook you up, you can't expect Joe to visit Torpio.com and integrate his CRM with his hosted PBX (if he even has one yet).
By the way, this is a speculative investment and I have invested accordingly.
Interesting that Twilio is mentioned. At the Synety Sharesoc presentation on the 8th May Simon Cleaver made reference to them when discussing competitors.
He said (from my notes): "They (i.e. Synety) are a level below that – non heavy call centre businesses – no one really in that space except perhaps Twilio in US (just raised $70m) they have API layer and you could build what Synety has on the back of it but they don’t have the sophisticated functionality – they are nearest competitor but they are not going after CRM companies."
Just my view on Synety
I own an IT Support business so have quite a wide understanding of how different SME's use CRM's. My view is that its a very untapped market, I know a number of our clients who have spent a lot of money integrating their physical phone systems with their CRM's. Even once this has been setup the problem is that your are at the whim of either party who may upgrade their software and inadvertently break the link between the two.
Synety puts this all under one roof and removes buck passing if problems occur, you should be able to use whatever CRM suits your business not the one which happens to work with your phone system. There's no doubt that hosted phone systems are the future, there's no doubt that CRM use is here to stay.
Key to success will be the integration with more CRM's although there's some great names already compatible. The other point will be marketing the business benefits to senior staff within organisations, the integration will save countless amounts of employee time and allow for a more flexible workforce (e.g. take your phone home and just plug it into the internet off you go) (a good plus for Disaster Recovery too).
Oh and on data protection which was mentioned, the customer has already migrated all their data to Salesforce etc not with Synety and therefore the customer is already "into" cloud and shouldn't be deterred.
Competitor hosted phone companies will need to start from scratch to integrate, this involves hiring programmers and forming relationships with CRM companies, something some wont have experience with.
Thanks Simon, that's very useful stuff.
I sometimes wonder why it's so difficult to convey to investors what a great product Synety have, people seem to have a blind spot when it comes to this company. Whereas to me the business case for what they are doing is a complete no-brainer, both for customers, and for investors.
Regards, Paul.
In my case the blind spot is caused by the fact that although I have read every post about Synety (not just today's) I still have absolutely no idea what this company does beyond the fact that it involves phones and the cloud.
I think that's where DYOR comes in.
One of the ways I DMOR in any sphere (not just shares) is to ask those who know what I do not. I had the vain hope that my confession of ignorance might elicit some information.
Simon / Paul
I gave some opinions on Synety the last time it was covered here.
Simon - For exactly the reasons you outline -
"I know a number of our clients who have spent a lot of money integrating their physical phone systems with their CRM's"
"you should be able to use whatever CRM suits your business not the one which happens to work with your phone system"
Products like Torpio were created (no link, but please dyor) - which quickly allows one to integrate ANY CRM with ANY cloud based phone system.
Where Synety is unidirectionally disruptive now, products like Torpio will mean that users have a choice to disrupt the market however and wherever they need. Costs for integration are coming down - fast.
My conclusion is that Synety are the first in. It's a great trade. But when the music stops - there are zero barriers to entry - you better be the first money out.
MV
Hello all,
good trading update from XPP ( XP Power) today, although sterling strength impacting results.
Key comments:
"Order intake in the second quarter was robust and we therefore reiterate our
guidance that we would expect to grow revenues again in 2014, although this
underlying growth is expected to be impacted by the currency translation
effects discussed above."
Net debt down (again) to £1.6m from £3.7 at y/e.
"Net debt continued to reduce and was £1.6 million at 30 June 2014 compared to £
8.5 million at 30 June 2013"
- co pays divs quarterly also, slightly up..
- very favourable stock rating in 90s, with 4 screens met.
looks like a good company, with A- on magic score..
Edison had a recent video interview with CEO, which was mildly interesting..
Any thoughts ?
Hi Paul, Cambria has been delivering very effectively but what price to pay? It trades at a slight premium on almost all measures to the much larger Lookers. 13x seems fair value (at best) for a cyclical and low value added business. It is highly reliant on acquisitions for structural growth.
On the positive side, there is probably upside to the numbers as historical acquisitions have depressed the operating margin. Cambria makes 1.15% while Lookers makes 2.3%. The gearing to a very small change in operating margin is remarkable. But assuming 500mn of sales in 8.15, and an operating margin of 1.2%, together with 600k of financial costs and 600k of tax, gives an eps of 4.8p, or 11.2x. This is quite a long way ahead of the Stockopedia consensus, but doesn't offer quite the margin of safety one might like.
There is one quite odd anomaly in the otherwise very clean accounts (few exceptionals, no pension issues, decent balance sheet, positive w.c), which is note 25 which shows that all the directors buy and sell cars with the company. This may be explainable but it looks weird.
Hi ONB
From experience/guesswork I believe note 25 may refer to a LLP structure which provides cars to the Directors in a tax efficient manner.
Cheers
I am one of those who fret when companies buy their freeholds when (it is the more usual case) those freeholds are for offices or multi-use light industrial/ warehouse space. The downpayment funds are much better used on working capital expansion and if the company really wants property then it is highly probable that their own premises are not the best property investment for the money.
BUT I have no problem with companies buying specialist premises, which I would argue garages are. These are in a sense tools of their trade and they are very likely to have a good understanding of their value. Cambrian is not buying a back street lock-up/repair shop, but full on showroom and workshop with serious installed equipment and a key location. So by all means buy the freehold to protect your principal business.
Hi Paul.
Yes, I am assuming an almost exponential growth this year by assuming ARR in HY2 to be double that in HY1.
Basically I don't think we disagree. The only difference is that I am looking for further proof before I will invest.
Regards,Ram
Hi Paul -
Re Synety. Got interested in this company following your write-up; so I ran a few numbers. The Annualised Recurring Revenue (ARR) to end June is £1.72m. Let's assume a very optimistic scenario, i.e they double their sales in the next following 6 months. So ARR at 31.12 is 1.72m + 2*1.72M = 5.16m . To translate that into bookable revenue I take the 31.12.13 proportion of reported revenue 0.55m to ARR of 0.87m which comes to 0.65. So the expected reported revenue on these very optimistic assumptions is 5.16*0.65 = £3.4m. Broker forecast is £2.4m. Currently broker forecasts are of a widening pre tax loss of £5.1m and widening eps loss of 62.6p. How much of this potential extra revenue will go into reducing the eps loss is difficulty to say without further modelling.
My personal view is that this share looks promising but it is high risk. What makes me nervous is that the salesforce tie up was first announced almost exactly last year with little impact on revenue. Given the current general stock market nervousness, I think I'll pass on this one.
Regards, Ram
Hi Ramridge,
I didn't quite follow your figures - it looks like you have tripled sales, not doubled them?
The CRM market in the USA is 10 times the size of the UK, and Synety (LON:SNTY) has been pulled into the USA by their UK customers. So that says to me that there should be a step change in growth once the USA market kicks in. Note from the BRR Media interview with the Chairman today, he says that sales leads in the USA are already exceeding those in the UK, so it doesn't make sense to use linear growth rates extrapolated from the past. A step change in growth could be about to happen from the USA, which is why today's report is useful for the positive comments about growth there & increasing confidence that it's going to work.
I'm not trying to persuade anyone to buy this stock, indeed it's too speculative for most people, but merely explaining my reasoning for why I think it's an exciting growth stock. With this type of company you really need to dig into the company, it needs a lot of research. Then the bottom line is you either trust management & think they can deliver, or you don't. I do, on both counts, but that's just one person's opinion.
Regards, Paul.
Paul, did you notice the Cambria Automobiles (LON:CAMB) trading update and other news this morning, which all looks positive?
I particularly liked "The Board is also pleased to report that the Group's trading continues to perform well in a strong new car market and that it remains on track to at least match market expectations in the current financial year. "
The Stockopedia scores for Synety (LON:SNTY) look dreadful, as they often do for a Story Stock.
I wonder what IP they have that would protect them against competition (and more importantly whether they have the resources to defend their IP if they need to do so). If integration with a CRM is easy, then switching to another cloud services provider should be easy too. And, as with all Cloud providers, there will be questions of cybersecurity, the location of the data centre and local data protection laws (and "safe haven" status), resilience, and what happens to the customers' data if the business is sold or goes bust, all of which may fragment the market or cause later problems.
It's not one for my portfolio.
I was amused to see that Stockopedia's map of their Leicester address places them just South East of Kuala Lumpur!
Hi FREng,
Synety (LON:SNTY) is not a story stock - it's delivering real sales, and rapid growth, albeit fairly early stage. Whereas a story stock is usually a company with little to no sales, relying on hyped up expectations of what it might achieve in future. Big difference in my view.
There will be competition, that's true, but once Synety has customers signed up, there is no incentive for them to move - because the SNTY service is cheap, pays for itself in savings on phone calls, and it works. So why would anyone change?
I recognise that it won't appeal to most investors here, but as you probably gathered, it ticks all the right boxes for me, and reminds me of the early days in IndigoVision, when I spotted sales taking off there, and that was a 30-bagger from that point.
Regards, Paul.
It is a story stock in so far as they're claiming to do a "land grab". My impression is that the land is already very well settled and they're just grabbing a few remaining peasant areas that are too small for the incumbents to bother, through heavy sales regardless of long term profitability, so as to spin the story and pave the way for a timely exit.
No position. (But great spectator sport!)
I have a few Synety - i have to say the numbers announced as split into 3 monthly comparatives are not as impressive as the headline figures. There may be reasonable reasons for this (new office,US pre-prep) - but these are the most important comparisons if we take the viewpoint that there is no seasonal element. I have borrowed these figures from the other place so they may need checking.
Obviously at some stage growth rate must slow but i was kinda hoping with US presence appearing they would not be at that stage yet or in the near future - hopefully this will be reversed when US kicks in.
Note there is a huge element of growth already priced in to this share, so i think healthy skepticism is the order of the day.
From the other place
In Quarterly terms Q2:
No of End Users +25% (Q1: +44%)
Av. New Users Per Month ?????? figures corrected this am so i dont know this figure
Number of Licences +37% (Q1: +52%)
Av. Users per Customer +4% (Q1: +12%)
ARR: +34% (Q1: +47%)
RRPU +5% (Q1: +4%)
Hi millaree,
True, but as mentioned in today's report, quarter on quarter growth rates are ridiculous, as they inevitably slow almost immediately, due to compounding.
34% Q-on-Q growth, if maintained for a year, is the equivalent of 222% annual growth!
So I think, with respect, that quibbling over the precise Q-on-Q growth rate is missing the big picture - which is that they have a product that is clearly in the early stages of taking off, and are building a high quality recurring revenue stream.
Cheers, Paul.
"After all, if a company has sub-£1m turnover, and cannot generate 50%+ sales growth from that level, then what they are selling probably doesn't appeal to potential customers" - Paul, what a great "rule of thumb" for us investors to remember to apply when we find ourselves getting carried away with the story!
Congratulations to you on Placing Watch, you are a champion for the private investor.
Kind regards, Neville