Small Cap Value Report (8 Oct) - AEO, TRAK, QPP, SNT, GRA

Good morning! US markets dipped yesterday evening, so that is feeding through to the UK, where the FTSE 100 is expected to open down about 10 points at 6,423. I like market sell-offs, as they present buying opportunities, especially in smaller caps where it only takes a few clumsy sellers to knock the price back 10-20% in particular stocks, so it usually makes sense to have kept some powder dry, or at least have a bit of gearing available if you don't like leaving cash on the sidelines. Personally I think a modest amount of gearing is fine, providing you're well diversified, and only invest in decent quality companies with sound Balance Sheets. The key driver for me is whether the stock is good value.
The US Govt partial shutdown & debt ceiling negotiations is rumbling on as an issue. Investors may be sanguine for a while, but as it continues, the more likelihood there is of a sharp market sell-off. Hence why I have personally bought some short-dated Put Options on the US market (which drives the UK market), just as an insurance policy to protect myself against the (admittedly small) risk of a big sell-off. It's cheaper to do that then to exit small cap positions, and have to buy back in later at a higher price, and absorb another set of bid/offer spreads, which can routinely be in the 3% area with small caps.
Options are expensive, and usually expire worthless, so I only ever use them rarely, for a specific risk. However, in this case where a resolution of the specific political issues would in all likelihood drive a large rise in markets, I want to remain invested, but also want insurance to protect against a crash. I'm also being wary about opening new positions.
It's a real tiddler, at only £3m market cap, but the final results to 30 Jun 2013 from Aeorema Communications (LON:AEO) look pretty impressive this morning. It's a corporate communication & events company. Turnover has risen from £2.8m to £4.0m, with a profit delivered of £359k, against a £36k loss the prior year. Looks good.
They also have net cash of £1.6m, which is about half the market cap! A maiden dividend is being paid, of 1.5p per share. As is usual with companies this small, several individuals have colectively got controlling shareholdings, and I note that the Director salaries look low, at £50k each for the top two. Although they did whack up their pension payments to £52.5k each, doubled from last year. So my worry would be that Directors & staff will want increased pay if performance continues to improve.
The company has reduced overheads by relocating its offices, obviously a positive factor. I can't find any meaningful outlook statement. On the negative side, they are heavily reliant on one large customer, and there seems to be very considerable dilution in the pipeline from share options - there are 8,037k shares in issue, and in the money Options outstanding of 1,613k, so that's dilution of 20% in the pipeline, which is too high. I regard a sensible level of share options as being around 5%, anything above that is getting warm, and anything over 10% is a red flag.
Also, the higher the level of share Options in issue, the more moderate I would expect salaries to be. That is the case here, but it's not always the case - plenty of greedy Directors load themselves up with cheap (or even free) share Options, and then take huge salaries as well. Executive remuneration in this country really is scandalous - an absolute disgrace in my opinion, that the managerial class just help themselves to larger & larger salaries/bonuses, which are not really linked to performance at all in most cases. Twelve month notice periods are also a disgrace - when have you ever seen a departing Director serve more than about 3 months maximum? These are general comments by the way, not directed at Aeorema.
I believe ShareSoc are lobbying Govt to give shareholders more say in setting Directors remuneration, which has my full support.
Going back to Aeorema, I won't be buying any shares in it personally, as it's too small & illiquid, but thought it worthwhile to mention it here, as an interesting set of results, so that any micro cap investors in the readership might want to follow it up. I could see the shares go up say 10-30% today on the back of these strong results.
Well, Aeorema has certainly sparked some interest so far this morning, I see the shares have been gradually rising to 41p, up 21% on the day, in the first 6 minutes of trading this morning. It didn't happen in one go either, so if you were very quick and nipped in at 8am, then you would already be decently in profit. The early bird & all that! I hope one or two readers jumped in & made some money, if so then you can buy me a pint next time you see me!
Sticking to the micro cap theme, Trakm8 Holdings (LON:TRAK) has issued notice of its intention acquire a competitor, which is being financed by a new £2.5m debt facility, and a subscription by the Directors for £720k in new shares - that's a very good sign in my view - Directors putting in a decent slug of their own money, and at a small premium to the market price. I'm impressed. Other investors are stumping up the balance required for working capital, of £1.35m.
I had a conference call with the Directors of TrakM8 last year, and was very impressed. I tried to buy stock, but was thwarted by an almost complete lack of liquidity and a hideous bid/offer spread, so gave up. However, I like the company, think the Directors are sensible, competent people, so am pleased to see them enlarging the company with what looks like a decent acquisition, although very few financial details are published about trading of the acquiree, although I suppose one could download their accounts from Companies House if needed.
TrakM8 is a niche telematics company, which makes specialised equipment for the vans market, with most of the features of high end equipment, but at a much lower price. It is sold primarily to fleets, such as utility companies. They have good recurring revenues, and high levels of client retention, but the company was sub-scale. So this deal seems sensible at addressing the scale issue.
Certainly one to watch, although I see that the shares are now up 38% to 28p - so another good example of where someone who moved fast at 8am would have made a tidy profit in less than an hour. I do think there's a lot to be said for being ready-prepared by understanding a lot of companies fairly well, then you can move really fast when announcements come out, and make an informed judgment.
It's also making we wonder about dropping my lower limit of £10m market caps, as that has lost me some good money-making opportunities lately. When these micro caps move, they really move, so if you pick the right ones, then plenty of money to be made. Set against that is of course the awful liquidity problems & hideously wide spreads on quiet days.
I see that Quindell Portfolio (LON:QPP) shares have been soft recently. I suspect that's probably because the company's latest clever little wheeze was to issue its own shares in a swap for shares in Nationwide Accident Repair Services (LON:NARS). Of course the first thing the recipients of the new QPP shares are going to do is sell them! Even if there is a lock-in, they are so easy to by-pass, that they're pretty meaningless. All people do is open themselves, or through a third party, a CFD or Spread Bet account, and then open a short position. This then locks in that price as a sale, as it offsets their ownership of the shares.
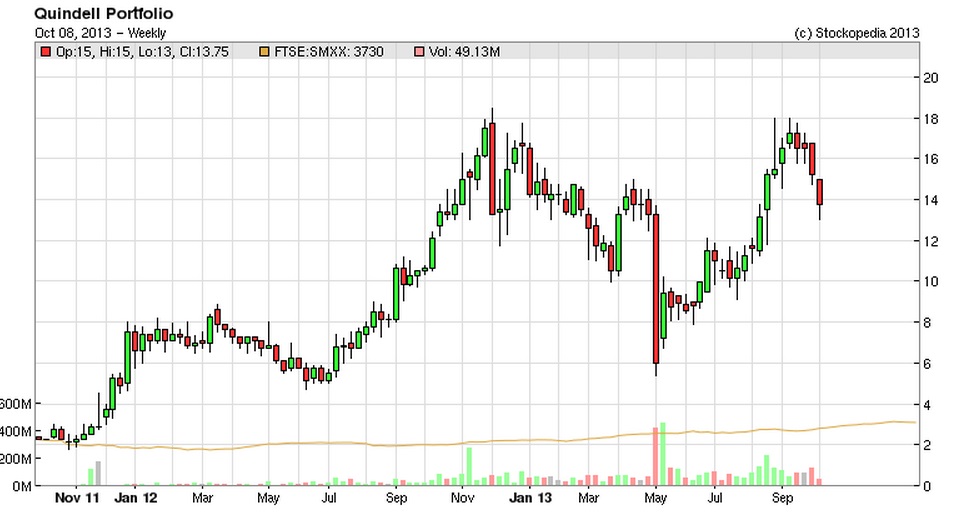
The trouble is, QPP has thrown around its own shares like confetti in numerous acquisitions, each of which creates a fresh overhang of sellers & potential sellers. Hence why they're always so desperate to drum up investor interest in the company, as it needs a continuous flow of new buyers to absorb the selling overhangs. It will be interesting to see how it pans out, but I remain deeply sceptical about the long-term sustainability of their earnings, and whether those earnings really can turn into cashflow. Remember that other companies are now setting up their own ABSs under the new regulations, e.g. Helphire (LON:HHR) (where I do hold some shares), so it's possible that Quindell may have had some first mover advantage, but others will surely chip away at that?
Anyway, it's a free market, so bulls & bears will just slug it out until the outcome is obvious. I don't & have never held any long or short position in QPP, as there are too many red flags for me to consider it, despite the apparently cheap valuation.
Just a reminder, it's Mello Central tomorrow night, Weds 9 Oct 2013. These are quarterly investor events, kindly hosted at FinnCap's offices in New Broad St, London. The organiser is ShareSoc Director, and investing stalwart David Stredder. The event is almost full, but David tells me there are a few places left for standing room at the back.
To book yourself a place, please use the contact details (scroll down to the "Reservations" section, underneath the calendar) on this link, and follow them carefully.
Arrival time is between 5pm to 5:30pm, with drinks available, and the company presentations start promptly at 5:30pm. There are four interesting small cap companies each doing a short presentation, then Q&A. Afterwards we enjoy complementary drinks & nibbles, and having a good chat. They are very friendly, so don't be shy about coming along.
A reader asked me about Sabien Technology (LON:SNT) yesterday, which issued a major contract award statement. I had a look at the company last night, and think it looks interesting - very small, but excellent profit margins. It makes control systems for commercial boilers, which save fuel by stopping them running when there is no underlying heat demand from the building.
If you like more speculative small growth companies, then this is certainly one of the more sensible ones I've seen - it's already profitable, has enough cash, and generates high profit margins already. So growth should see profits soar. There's no guarantee they will achieve growth of course, that's the speculative bit!
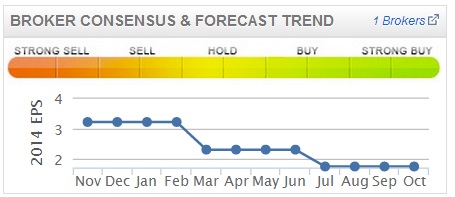
Printing.com has changed its name to Grafenia (LON:GRA). It's quite interesting to note that a domain name as the company name, which seemed so modern a few years ago, is now being changed for something more fashionable! Their trading statement today is a profit warning for both the full year (ending 31 Mar 2014) and H1. So it sounds like their interim results, to be published on 4 Nov 2013 are probably going to look pretty grim.
One crumb of comfort is that they say that whilst sales disappointed up yo July, an improvement was seen in September. You would expect a printer to be a beneficiary of the improving economy, as small businesses start doing more promotional activity, etc. However, they're always going to be up against a headwind of advertising efforts moving more towards social media online. Print is so competitive too.
They use the dreaded "second half weighting" for profits is expected, which is often a precursor to another profit warning. So I can't see any reason to warm to this one. The dividend yield is very high, but it's probably not sustainable in my view, so therefore is not something to chase.
Note how broker forecasts have been steadily dropping this year:
This latest Blog post from investing legend Guy Thomas is an absolute must-read - some really clever insights that are as much about human psychology as arithmetic. Well worth a read.
 Finally, another huge thank you for your wonderful donations to my Scope fundraising effort after Sunday's Half Marathon. There were loads more donations yesterday, and I'm thrilled to see we are now only 7% away from the £3,000 target, with Gift Aid on top of that! So well done to everyone who has contributed. Here's a photo of me with my medal for finishing, and yes I know the mirror needs cleaning lol!
Yes, it was a personal challenge, but I wouldn't have pushed myself anywhere near as hard without all your sponsorship. Here is the official result from their website with my time on it, for those cynics who want documentary evidence!:

Regards, Paul.
(of the companies mentioned today, Paul has a long position in HHR.
A Small Caps Fund to which Paul provides research services also has a long position in HHR)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
it was a great call Paul and a turning point for me in terms of trusting my own analysis and insights versus the "experts" (that is a bit of a weird back-hand compliment I guess). By that I mean that IC and Simon Thompson had backed this as a bargain share and it did indeed enjoy stellar performance following that recommendation in Jan 2014 ( I had it on my wishlist then but was operating on the principle that if it looked THAT good and all....). I mean no disrespect to Simon Thomson nor to IC - we all make mistakes. The big difference is that mistakes like this can be costly and are eminently avoidable: Simon still gets paid, investors don't.
I tracked NBU as a case study from my own point of view: when it played out as you called and as many of these Chinese shell companies behave, it was to script
I don't pay for IC any more..I'd rather pay myself and screw-up my own biases all by myself...
That said, I read your small cap reports daily and like your style and idiomatic take: you deserve the credit you get.
Cheers John. I couldn't find the options I was looking for so will go for the warrants instead. Don't worry, I'm not planning to do it until we see a break of a major support and have my own plans! Was just trying to find a suitable vehicle, didn't fancy spread betting (though surprisingly this isn't a bad option at 1.5% p.a. financing for a short position and under 50 points spread on a long term bet).
Does anyone else share my view that we may be approaching the end of the cyclical bull, once support breaks I think we're in for a good 1-3 years of falling prices. I daresay we get down to 4,500 on the FTSE.
I have bought some FTSE covered warrants. Epic SC40. 6500 strike price March 21st. About 13 x gearing. Purely telling you what I have done; not a recommendation! DYOR etc.
Could anyone please suggest FTSE 100 options contracts with smaller contract sizes. I am looking to buy puts to hedge against downside risk on the FTSE. I have been unable to find the contracts I need but I know they exist as I used to trade them!
The Liffe contracts are not that big (£10/pt).
Excellent summary as always Paul on stocks I've never looked at before & read your comments on executive remuneration with interest.
Hi Paul,
THE RUN: Congratulations on a marvellous effort!
THE PHOTO (above): Your bathroom mirror needs a wipe.
THE SHARE ANALYSIS: Excellent & well done, keep it up!
Campbell
I am always on the lookout for micro cap companies that have something special to offer. I particularly like Quadrise (QFI) and Westminster (WSG) which look very good for growth in 2014. However, the doom and gloom merchants at Money week are still predicting a calamitous collapse of our financial system in the not too distant future, which kind of makes investing in shares a waste of time. Do you have any views on this please?
Hi Paul,
Just a word of caution there, Paul... Your comment is exactly what I thought in 2011, when I held puts as the US approached its debt ceiling limit at that time. If you recall, a deal was cobbled together at the last minute and disaster was averted... so I closed my puts. Then the market promptly tumbled by several hundred further points, after the ratings agencies downgraded US debt!
So, the market makes fools of us all! I have therefore taken out December dated puts this time, and will close them only cautiously, even if the issue is resolved before October 17th. If the market does subsequently recover strongly, I shan't mind taking the hit, as I'd expect porty gains to outweigh the cost of the puts. NB I started building my put position back in July (as I tweeted at the time), when the market stood at high levels, in anticipation of this problem - plus the Eurozone issues which haven't really been resolved and could creep out of the woodwork, now that the German election is out of the way.
Cheers,
Mark
I don't know about QPP, but if their model is a good one it could be a good time to get in whilst the share is depressed by an overhang. Nationwide Accident Repair Services (NARS) looks a better bet IMO. The QPP involvement should increase business and, since NARS is currently working well below capacity, transform the bottom line. NARS sp has retreated recently and I'm tempted to add ahead of the fog and ice season.
Hi Paul,
With respect to domain names such as printing.com ... I think this trend was driven by Google's search engine algorithms. Previously you'd receive an improved Google search engine position if your domain name included the search terms. So for a printing firm it's customers are going to be searching for 'printing' and therefore printing.com receives a higher score. That's why my the home domain for my business is counselling-cardiff.com as 'counselling cardiff' is the search term that the majority of my potential customers use.
I received a report today that surveys Search Engine Optimisers and the results suggest that this feature carries less weight in the current version of the algorithm and that might explain why they have rebranded themselves.
Hope that helps
Phil
Search engine optimisation can only explain the branding of the customer facing service, there's no imperative to name the listed PLC the same. I bet this was just to ride the .com bubble when people bought any Internet-related shares regardless of price.
Hi Paul,
What do you think of Robbie Burn's use of ETFX FTSE 100 Super Short Strategy (2x) Fd as a hedging strategy? The ticker is SUK2.
It's an exchange traded short fund that moves twice as fast as the FTSE 100. It can be purchased into ISA's and SIPP's. Obviously the downside is if the market continues to improve, however we're more likely to see sharp spikes down than sharp spikes up in the FTSE 100.
I'd appreciate any comments
Thanks
Phil
Daily leveraged ETFs are more complicated than options, the way you pay for volatility is counterintuitive (google it) and they require much more capital. Options are OK in SIPPs, if all else fails in listed warrant form (at a cost).
Hi Paul
Your comment on QPP is more or less exactly why I decided to take the nice gains on it and dumped our position at over 16p. There's just too many deals and too much paper being issued. Evenif the deals are good value, the sheer number makes me acutely wary of the high execution/integration risk. Our was also interesting to hear one fund manager that I really respect state it as his number 1 short but couldn't get the stockto borrow...
As I said at the time when I posted about our sale, I may be wrong but I just feel that much more comfortable being out than in.
cheers
A good balanced article. Gives me a clearer view of what to look for.