Small Cap Value Report (9 Feb 2016) - CMBN, XSG

Good morning!
It was a Duvet Day yesterday, so my apologies for any inconvenience. Perhaps the whole market needs a duvet day, given how negative things have been so far this year?
Cambian (LON:CMBN)
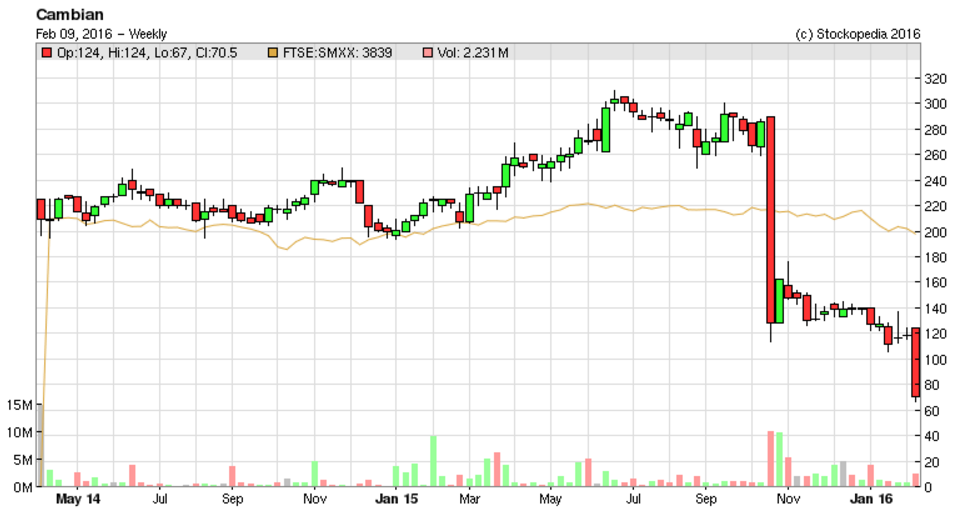
Share price: 74.4p (down 37.8% today)
No. shares: 184.2m
Market cap: £137.0m
Trading statement - this company has slipped through my net, in that it floated in Apr 2014, yet I haven't reviewed its numbers here before. The company seems to deliver outsourced care services for Govt & Local Authorities;
The Cambian Group is one of the UK's leading specialist behavioural health service providers. Founded in 2004, it has grown to become a significant partner to the UK Government. The Group's services have a specific focus on children and adults who present high severity needs with challenging behaviours and complex care requirements. Cambian employs approximately 7,000 people across a portfolio of over 300 purpose-designed facilities and 10 fostering offices located in England and Wales.
I normally run a mile from shares like this, after a bad experience a few years ago with Southern Cross Healthcare (I tried to bottom-fish, and thankfully realised just in the nick of time that it was doomed, getting out days before it went bust).
This situation doesn't look anywhere near as bad as that, but with public spending being squeezed, profit margins must be under pressure. Plus it has a lot of debt, although Cambian seems to own the freeholds of most of its sites - which makes it potentially interesting, so I'll dig a bit deeper (it was leases with ratcheted rents, combined with LAs refusing to agree to fee increases, and inadequate occupancy (combined with fixed costs) which killed off Southern Cross).
Profit warning - today's announcement has quite a few moving parts, this is the key section;
On 22 October 2015, the Group indicated that adjusted EBITDA for the year to 31 December 2015 would be not less than £49m. Cambian now expects that, subject to audit, revenue and adjusted EBITDA for the year will be approximately £292m and £46m respectively. During the year ended 31 December 2015 occupancy increased by approximately 260. Since the previous announcement, revenues and wages have been broadly in line with expectations, but due to weaknesses in our cost management processes, it took longer to identify and manage down other costs.
So the EBITDA reduction doesn't look too bad, from £49m to £46m. The main consequence of that is in terms of bank debt, since one of the bank covenants is that net debt should not exceed 4.95 times adjusted EBITDA.
Net debt is said to have been £241m at 31 Dec 2015 - I make that 5.24 times the revised EBITDA figure of £46m, which looks to have breached the 4.95 times covenant. However, the company today denies this, saying;
The Group traded within its bank covenants at that date and are entering into discussions with its lending banks to agree revised future covenants.
Checking back to the last interim results, I might have found what the difference is;
For both covenants, Adjusted EBITDA is calculated after adding back development losses of up to £3m per year.
So if we assume that the full £3m adjustment is being made to EBITDA, then that would increase adj. EBITDA to £49m, and the net debt:EBITDA covenant would now become 4.92, a whisker below the 4.95 maximum.
Suffice it to say that the company is clearly dangerously close to breaching its bank covenants (or one of them anyway), which is tacitly admitted with this comment today;
Group net debt as at 31 December 2015 was £241m. The Group traded within its bank covenants at that date and are entering into discussions with its lending banks to agree revised future covenants.
The Board is confident that it will achieve a satisfactory outcome, given its trading outlook and the substantial value of its mainly freehold properties which were valued at approximately £577 million by Knight Frank LLP at the time of its IPO in April 2014.
So a company about to breach its banking covenants is a dangerous place to be, therefore this has to be seen as a high risk special situation.
However, banks are usually relaxed where they have security against freehold properties, as in this case, and my eyes nearly popped out of my head when I read the £577m figure noted above for Knight Frank's valuation on the freeholds in Apr 2014.
In a fire sale, the properties might fetch a lot less than a bull market valuation from a friendly valuer. But even if you halve the Knight Frank valuation above then £288.5m would still give the bank headroom against a £241m net debt.
So it seems to me that the bank are very likely to be supportive, due to the substantial freeholds which Cambian owns. Although I note from the last accounts, the book value was nowhere near £577m. Actually total property, plant & equipment book value was £371.9m. So that point needs clarifying - perhaps freeholds are in the books at historic cost, rather than valuation?
Cost control - the company seems to have lost control over its costs, to a certain extent, which again sounds rather scary. The CFO has gone, and they are seeking a permanent replacement, with an interim CFO currently in place.
Since the previous announcement, revenues and wages have been broadly in line with expectations, but due to weaknesses in our cost management processes, it took longer to identify and manage down other costs.
That really worries me. Managing costs is just a basic part of running any business. So a business that is weak in terms of cost control may not survive for much longer. Today's announcement also says that PWC has been hired to do a review of Cambrian's supplier management systems. What a waste of money! If you need to spend a lot of money on expensive consultants (most of whom have never actually run a business themselves!) to tell you how to save money, then you're putting the cart before the horse, and absolving yourself of responsibility, in my view.
A decent FD should be able to properly manage the purchase ledger, so this again seems to just reinforce management weaknesses, so this can of worms could get worse before it gets better perhaps? I imagine there will probably be a lot more exceptional costs in 2016, on top of the £3.5m indicated for 2015.
Current trading & outlook - sounds reasonably alright;
The Group has had a satisfactory start to 2016. Demand continues to be strong for the specialised services which we provide and we are confident that we shall be able to increase prices in line with the net cost of the National Living Wage introduction on 1 April this year.
We anticipate we will deliver modest growth in adjusted EBITDA for the year ending 31 December 2016, reflecting a lower first half result, with improving revenue momentum in the second half.
Overall this doesn't sound too bad to me, although has to be read in the context that management always try to show things in the best possible light, and there could be more bad news to come (very likely, I would say). The H2-weighted year comments for 2016 are also a classic sign of probably more bad news to come in the future.
My opinion - overall I think this looks a potentially interesting special situation. The key thing is that the company probably isn't going bust, due to having freeholds to support its bank borrowings. The EBITDA miss is not large, and current trading sounds reasonable.
Therefore I could see good potential upside here once the bank(s) have relaxed the net debt:EBITDA covenant, or perhaps pushed the company to reduce debt by disposing of some freeholds? An RNS confirming that the bank(s) have relaxed covenants could put maybe 20% on the share price? So that could be a nice little trade at some point perhaps?
Maybe the group grew too fast? It's very difficult to keep control of a business that is growing rapidly, so sometimes growing pains do happen to a business that may be fundamentally sound.
Am I going to catch the falling knife? Not at the moment, no. On balance, there are probably better opportunities elsewhere - with the market throwing out the baby with the bathwater, in some cases - so if there are bargains to be had with companies that are trading well, why bother getting into a problematic situation like Cambrian, that may get worse before it gets better?
It's definitely going on the watch list though. I shall also start watching the TR1 forms, to see what major shareholders are doing, If any are selling in disgust, then the share price could continue plummeting. However, if major shareholders are supportive, and buying in the open market, then that can often be a good signal that it's safe to venture in behind them.
Dividends - note that the final dividend has been passed, so this share must (for now) be considered to have no dividend yield. That might induce some more shareholders to sell, so another reason to wait for the share price to stop falling, before buying, in my view. It's a wise move by management though - to continue paying divis when you're asking the bank to relax covenants would be crazy.
Have any readers looked at Cambrian? If so, I welcome your views in the comments section below. I think at some point it might be an interesting turnaround, but perhaps not just yet?
Xeros Technology (LON:XSG)
Share price: 186.5p (up 2.9% today)
No. shares: 85.1m
Market cap: £158.7m
Xeros signs major laundry deal - wow, what a title for an RNS! This must be a really serious contract, so even though this company is too jam tomorrow for my liking (and the market cap seems nuts), I'll take a look anyway.
So is it $50m, or $100m deal? Err no, it's $1m. Over 8 years, for 8 washing machines. What a joke! Mind you given that the company's entire turnover was only £480k last year, then maybe this does seem like a big deal to the company?
Trouble is, look at the cash burn - it burned through about £12m last year. So it actually needs 20 or 30 "major deals" like this, just to start moving the dial, let along getting it anywhere near breakeven.
Shareholders stumped up £40m in a recent fundraising at 225p per share, so there's no immediate issue with cash, but there will be in a couple of years' time if the company doesn't deliver very much better performance.
My opinion - this does seem interesting technology (washing laundry using polymer beads, and very little water), so who knows it could be the next big thing?
But really, to claim that a trivial contract of $1m over 8 years is a "major deal" is just laughable. Shareholders should throw a bucket of cold polymer beads over management, and tell them to stop putting out daft announcements.
I'd say that the £158.7m market cap here is extremely vulnerable to a sharp correction down to a level that would better reflect risk:reward. Jam tomorrow shares hardly ever meet expectations in the long run.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Hi
The beads referred to in the articles above are microbeads in personal care products. I am fairly sure that Xeros beads are substantially larger and are recycled (at least, according to their web site http://www.xeroscleaning.com/xeros-sustainability). The problem with microbeads is discharge to a water environment and Xeros beads are not, it seems, discharged.
John
Not sure if anyone has mentioned it before but polymer beads are likely to be banned worldwide very soon, so I'm thinking that Xeros soon won't have a viable product to sell.
Hi Investimouse
Can't find any reference via Google to a polymer bead ban. Can you expand on your comment.
I don't hold and don't expect to.
I may be wrong and Xeros is using some other sort of polymer bead, but here's a couple of links about upcoming and existing bans on the stuff in personal care products:
http://www.pri.org/stories/2015-09-30/why-canada-b...
http://www.rsc.org/chemistryworld/2016/01/us-bans-...
Looks like a different product to me. That said the whole saving water thing in the domestic environment (small cisterns, don't run the tap while brushing your teath etc) is a complete non issue and just about making people feel good. Water problems are caused by industrial water use by goods manufacture and industrial meat and food production.
Xeros may or may not have a workable business plan but it is certainly not one I would back with my money!!
HI Paul, I recently listened to your interview with Somero in which the CEO mentioned he would be in the UK in the first week in March and open to meeting investors. I wondered if you had any information on his visit, or if you would pass on any information when you get it. I tried contacting Somero through their website but so far no response
Many thanks!
Re Cambian
I looked at this in detail last October on the first profit warning. The key reason was that they did not have enough qualified staff in the right units. The whole sector is struggling to recruit.
IF the company can successfuly recruit, train and retain the right staff then it could be interesting. Until proof that this is being achieved then , to quote Dragons Den, I'm out.
Re ridavies request for other contributors:
Re Cambian - know them a bit from "real life". They offer rehabilitation-based services within a hospital environment i.e. locked and open rehabilitation wards and, I think, are focused more on mental health services. Their estate therefore has value for others operating similar services, but not, I would think, in the properties themselves for alternative use. Re Paul's point re Knight Frank valuation - I wonder if this is a trading valuation i.e. what the properties are worth for their income-generation (explaining the difference between the book value in the accounts and their valuation?). However, this should be reflected in their market value as it links to trading (if the case)?
I would imagine much of their income comes from the NHS as opposed to social services (again they would be clear on this).
Re Caretech, I understand they have a range of community based services including residential care, but for both mental health and learning disability. Re their freehold estate, I would think that this has more alternative use as it could be more readily converted into domestic dwellings i.e. is underpinned more in reality (in terms of downside property fundamentals).
Hope that's helpful in prompting further research/questions!
Doug, personally I'd say it is general market malaise... its price seems to go up and down a lot according to sentiment
Would be interesting to see what Kabouter, who hold 8%, do
Any view on why Zytronic (LON:ZYT) (Zytronic) might be down 5% today?
As far as I can tell there is no news, and none due until an AGM update at the end of the month.
I hope it's not bad news leaking out as I have topped up (or averaged down, depending on your take)
Fun fun fun 'til Dady took the T Bird away!!!
It seems to me that CTH (Caretech) are in a similar market situation, but are clearly - to me - much more successful and professional. Their PER is very low, but they are of course under constant pressure from spending cuts in local authorities. On the other hand, LAs are responsible for their clients in a way they do not seem to be for say the aged so their - CTH - finances are likely to be more secure. Thoughts on CTH please, both as a company and a an investment at this time? From Paul especially but also from other contributors?
Hi Paul,
In light of recent market volatility, would you fancy doing a piece on your "trading" portfolio as you have mentioned previously?
Would be great insight as to how different your approaches are to the different folios objectives etc.
I know you put a lot of effort into the SCVR so maybe an oversight, or say a weekly summary or something would be a great starter for ideas etc.
What do you think?
If others think it would be useful then give it a thumbs up.
Regards
mrwhits.
RE. Cambian (LON:CMBN) Worth mentioning that this is their 2nd profit warning in just over 3 months, revising their EBITDA down again. The last profit warning was in October and it led to a 50%+ fall over the next 2 days.
Catching a falling knife in today's market environment is definitely not a good idea. Besides this management just cannot be trusted, so for me it goes in Room 101.
Room 101, I'd agree... yet another company that's into profit warning territory less than two years after it floated... and it's already in danger of breaching banking covenants despite raising money in 2014 in coming to the market? Doesn't look a pretty picture to me :-/
.