Small Cap Value Report (9 May 2014) - AMA, NET, SNTY, C21

Good morning! Sorry I'm late today - had one too many ice cold pints of Peroni at the Lord Aberconway last night, after an excellent evening hosted by FinnCap and ShareSoc, where four companies presented. Brief impressions;
Amara Mining (LON:AMA) - I'm not interested in resource sector shares generally, but found this a surprisingly interesting presentation from the company's FD, Peter Gardner. They have recently raised enough money (from a Placing at 17p) to progress their main African project to feasibility study, and it has considerable cost advantages, being located near a hydroelectric dam, hence has cheap power and water available - both being key cost considerations for gold mining. Although as David Stredder, the host, commented, it might be an idea if the CEO changed his surname from Spivey to something less appropriate for the resources sector! The company also has some gold producing sites, but these are small, and near the end of their lives.
The internet is full of pictures of cats, for some unknown reason. Actually, it's probably because they are the epitome of disdain and indifference. Here is one that made me laugh considerably this morning, and I hope it brightens up your day in a small way :

Netcall (LON:NET) - This really is an excellent company, and I enjoyed the presentation from its charismatic CEO Henrik Bang (great name too!). I felt there was a bit too much management speak in the slides, so I was finding it difficult to understand what the company actually does. However, three brief case studies were given about how their software helps eradicate 700 years waiting time on corporate phone lines, by calling customers back, instead of putting them on hold and making them listen to musak. Also the company has done well selling software to the NHS, which reminds people of appointments, since scandalously about 10% of appointments are missed by people who don't turn up for them. If it was down to me, I'd put them in the stocks and hurl rotten vegetables at them, but apparently that's not politically correct these days. It's a pity the shares are so expensive, otherwise I would buy some.
Synety (LON:SNTY) - Executive Chairman Simon Cleaver gave an interesting presentation which explained how their integration of CRM software with cloud based telephony is giving SMEs a full call centre style telephony system, embedded within their existing CRM systems, at nil capital cost, and about £25 per month per user. I make no secret of the fact that I really like this company, and it's my second largest holding, although the shares are expensive for a low turnover, loss-making company.
For anyone who missed this presentation, I've invited Simon Cleaver to present at my next ShareSoc Brighton event, which is being held on Thu 26 Jun 2014 from 6pm. We're also going to have a group debate on "shorting shares - good or bad?", so attendees are invited to prepare short (2 mins max) talks giving their perspectives on shorting. Then we'll have a before & after vote, to see what people think overall. Should be interesting.
Unfortunately I missed the presentation for Harvey Nash (LON:HVN), as the room had become so hot & stuffy that I felt close to passing out, so had to leave the building to get some fresh air briefly. Unfortunately the Reception staff had gone home, so I couldn't get back in once I'd returned my oxygen levels to normal, so I had to pop over the road for a quick half at the Lord Aberconway. Suitably revived, I waited outside FinnCap's offices until the Polish cleaners turned up, and talked them into letting me back in, just in time for the excellent buffet.
21st Century Technology (LON:C21)
I bought some more of these recently, but without much conviction. It's a CCTV equipment maker that specialises in public transport, but has experienced a few bumps in the road recently with profit warnings - an occupational hazard in the small caps space I'm afraid.
New management (formerly from a larger competitor, Synetics, if my memory serves me correctly) took over about six months ago, so I've been half expecting them to kitchen-sink things - i.e. have a good clear-out, and write off anything dubious, etc.
As you can see, headline results for the year ended 31 Dec 2013 are not only very late, but are also poor (although not disastrous);
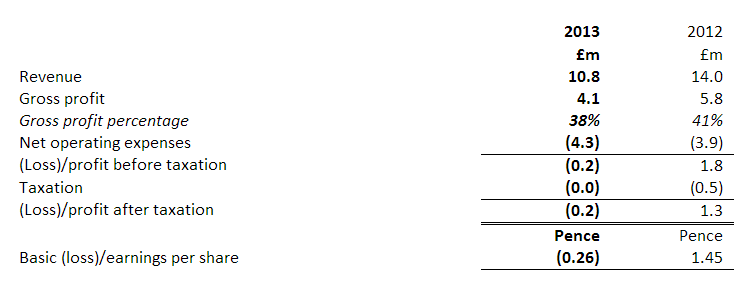
The commentary says;
The outcome for the year is broadly in line with our statement at the half year. However, it is a disappointing result after the hard work and investments made, particularly in our product based expansion into continental Europe, this was compounded by Go-Ahead's decision not to renew our contract in mid-August 2013.
Oh dear, doesn't sound very good, does it? That said, at 4.6p per share, the market cap is buttons, only a bit over £4m! So if they turn things around then the upside could be pretty good. Are they likely to go bust? Let's have a look at the Balance Sheet. With £3.2m in net current assets, the Balance Sheet is pretty strong, so I think they are OK for the time being, especially as costs have already been cut with a 17% reduction in headcount.
On current trading & the outlook, the following extracts sum it up;
The expectation for the current year is for revenues to be similar to 2013 although, as already stated, revenues are sensitive to the retention of the customer accounts mentioned above.
We are currently trading in line with Board expectations and every effort is being made to develop new lines of business and secure positive outcomes from the important contract negotiations and renewals due later on this year.
Reading between the lines, it sounds to me as if they are preparing the ground for more customer losses, so I suspect this won't be the last profit warning. This is potentially disastrous, as the notes to the accounts show how reliant they are on one key customer in particular;
Major customers
In the year the Group had two customers that each accounted for over 10% of the revenue at 54% and 24%. In the prior year there were three customers that each accounted for over 10% of the revenue at 60%, 19% and 12%.
Because of that, I think these shares really have to be seen as very high risk. Accordingly, I've decided to take the hit, and have sold some of my shares at a loss, to reduce my position size down to a level where it wouldn't hurt me if they go bust. Maybe that is a mistake, but risk management is paramount with investing, so one has to size positions at a level which is appropriate to the risk involved, and this one is starting to worry me. I'm happy to run with the remaining (smaller) long position, and hopefully management will be successful in their turnaround strategy.
The maiden dividend paid in Jun 2013 is not being repeated.
There's not much else happening today that interests me.
I see that a lot of overvalued tech stocks are really taking a battering at the moment - WANdisco (LON:WAND) is collapsing, not before time - I tried to short this one a while back, but couldn't get a borrow unfortunately. I must open some new short positions - this feels every bit as bad as the sell-off in 2000 when the TMT boom finally burst. I'm amazed at the speed that overpriced large cap stocks like ASOS and Ocado have dropped - the latter has more than halved from its peak. I'm not currently short of either, so can comment on them here. I'm sure there will be other casualties, as investors are far less inclined to support mad valuations now. It's the people who have fallen in love with the overpriced stocks who end up losing their shirts when the market corrects back to sensible valuations, as it's doing now, so I hope no readers here have fallen into that trap.
Speaking to my brokers yesterday, they said it's gone quiet, and there's very little new buying going on now, so I think this could well be a year where "Sell in May & go away" could be a very wise move. Thankfully as I only hold value & GARP stocks, this doesn't matter to me, in fact several of my positions are going up nicely at the moment, and if they drop I just buy more, when the price is right.
I think the market has been rewarding bad investors making bad decisions for too long, so it's about time that normality returned. So opening some new short positions is definitely top of my agenda. This not only protects your capital, by hedging your longs, but also means you have more firepower to buy the bargains at the bottom of the market.
Sorry for being a bit late this morning, back to normal on Monday. I wish you a pleasant weekend.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in SNTY, C21, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
I see the price for AMA is in the gutter. If the directors' reporting is to be believed, this share should come good eventually (2017?). I notice directors buying recently and JP Morgan increasing their shareholding above 14%. Any thoughts on where this could be going?
Hi
I attended the excellent Sharesoc Synety (LON:SNTY) presentation and I have now typed up some notes on what was said. They are posted here if anyone is interested:
http://webpax.co.uk/snty.pdf
As usual all imo/dyor.
Kind regards
Jon
Many thanks for the update on what was discussed at the recent presentation. I was hoping to attend but had a prior commitment, I hold shares in this company and have done so for past Year. I was thinking about selling these shares in the next couple of months as I have made a decent return of my investment but may now hold them for another year or so to see where they end up. The key to this companies success in how quickly they can sign up US seats.
Kind regards,
Russ
Re c21 and recent management share purchases ........
Robinson, Glenn Financial Director 11/10/2013 bought 994,817 £ 59,689
Singleton, Russ Chief Executive Officer 11/10/2013 bought 1,500,000 £ 90,000
Totally agree with you on the cat picture....
Regarding 21st Century Technology (LON:C21), what do we know about the new CEO renumeration? I see they were given options at 6.x pence when they joined and that 'Russ Singleton and Glenn Robinson have made irrevocable undertakings to acquire £90,000 and £60,000 worth of shares in the Company respectively'.
The dependancy on a couple of big contracts is worrying but it seems to me that there must be opportunities to expand this portfolio. For example, i saw last night that the MET police and trialling cameras on their officers so that live action can be recorded, and its possible that 20,000 officer will have this if the trial is successful. All this is becoming possible with the reducing price and miniturisation (sp?) of the technology, so one would imagine other opportunities in new areas opening up too. Can 21st Century Technology (LON:C21) get a slice of the action?
I really dont like it when companies dont look after their websites. Synety (SNTY) is one of them. Have a look at their website here: https://www.synety.com/
scroll to: What our clients think. (click on more if you want even more testimonials!)
I don't know which is worse having a blank section after the above words or just not having any comments from clients!
uuurrrgggghhhh
Dont Hold.
Not sure if this is a browser issue Chillax but on my Mac running Firefox the link works fine and displays 19 different company testimonials.
Cheers
Jon
Chillax, I totally agree with your sentiment about sloppy and unloved websites, but — I'm puzzled why you should pick on Synety, whose site is superbly designed! I can't think of a quoted company of any size with a better looking site.
I clicked on the link "Customer Success Stories" at the foot of the home page, which goes to a page headed "What our clients think." (If this is what you mean by scrolling to.) This page has 19 beautifully executed panels, with client logos and their respective comments.
If I were to make my investment decisions based on website quality I'd be increasing my Synety holding right now.
Mind you the stockpedia data itself could hardly read much better. A lot of green and money in the bank .
Now might be the time to buy rather than sell
Phew, sold 21st Century Technology (LON:C21) a few weeks back. Nice to have avoided the falling knife for once, rather than have it land in my eye as seems to have generally been the case recently!
Re Synety, the product looks interesting but one really needs to see a cash flow forecast to determine what the outcome may be of heavy investment in sales and marketing. How much does it cost to acquire customers and how long is it before they become profitable are a couple of other key questions.
It's so easy to build an unprofitable software business by convincing folks you have a great product that everyone needs. Also reliance on third parties to market your product (CRM companies seemed to be the main marketing/sales channel) is fraught with potential problems. What if they lose interest? Lack of channel control can be problem.
Possibly some questions for Brighton unless Paul already knows the answers?
I sold my 21st Century Technology (LON:C21) shares today on the same reasons as bsharman mentioned - lots of talk of working to retain 2 major clients, the French subsidiary ceasing trading and no clear vision for the future. Coupled with the results being very late, it doesn't fill me with confidence. I had hoped that with Peter Gyllenhammar having finished dumping his shares a few weeks ago, the share price would move up with some positive news but it now feels more like gambling than investment. Glad I didn't have a large stake but wish I had sold last week!
Hi, I don't have a large holding in 21st Century Technology (LON:C21) but I am hoping that the new management team can turn things around - or perhaps it will get taken over? They are relying on 2 customers, having lost the Go Ahead contract last year. As you say, there does not seem to be any strategy to grow sales. However I do know that some very influential investors are on board including Mark Slater, who I believe holds around 16% in his fund. I would like to see the C21 management attend some of the investor events such as Sharesoc and Mello or Equity Development in the very near future to explain the strategy, R&D, new products, markets etc.
Regarding the Synety presentation, did they provide any indications as to how their USA expansion is going, this being an important step for the company.
Hi man741,
Yes, Synety (LON:SNTY) did mention their USA expansion - they are going into America because customers (CRM software companies) have demanded it. So an office in Boston has been opened, very close to a big existing company, and apparently it is a good telecoms hub.
It took them 6 months to get their USA telecoms licence, which they now have. Sales are starting imminently, with a team having been recruited, and being trained up. Senior UK staff/Directors will oversee the US office initially, in Boston.
We'll have to wait and see what happens, but I think they are right to deliberately step up the cash burn, to take advantage of the opportunity they have created. There is about £7m cash in the bank currently, and cash burn is running at about £250k per month. As the Chairman commented, he could make the company profitable overnight, but it's not about profits in the short term, it's about driving sales growth. Given that sales are recurring, and high margin, I think this is absolutely correct. It could be an exciting company in 1-2 years' time if things go well.
Regards, Paul.
The 21st Century Technology (LON:C21) results did not fill me with confidence. The emphasis on the retention of two major customers and the reduction in international sales efforts seemed to me to be very negative. It's as if they are working flat out just to retain their customers and not grow the business.