Small Cap Value Report - ELTA, W7L, UPGS

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
A quick reminder, can people please remember to put the company name or ticker in your comments. We're still getting orphan comments, where e.g. people say how much they like the company. The trouble is, many readers won't know which company you're referring to, so the comment is completely wasted. Maybe there's only one company in the article when you leave the comment, but please remember more sections are added during the morning, Thanks.
Agenda -
Paul's Section:
Electra Private Equity (LON:ELTA) - it's demerger day! ELTA shares now become just Hotter Shoes, and ELTA shareholders will receive newly listed Hostmore (ticker: MORE) shares, 3 for every 1 ELTA share. Now the market will decide how much each company is worth separately. Expect considerable short term volatility.
Jack's section:
Warpaint London (LON:W7L) - continuation of improving trends and FY results expected to be ahead of expectations. Strong momentum here after a couple of setbacks, and the founders and major shareholders remain in charge, so worth assessing the longer term prospects.
Up Global Sourcing Holdings (LON:UPGS) - supply chain issues are being mitigated and the growth prospects continue to look attractive. The recent moderation in sentiment means you can buy a growing company with a forecast dividend yield approaching 4%.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Electra Private Equity (LON:ELTA)
This is it. It’s what I’m calling price discovery day. I hope nobody has got a stop loss order on ELTA shares, as it’s likely to plunge to c.100-150p today due to the demerger of Hostmore.
ELTA is a breakup situation, with its main investment, casual dining chain TGIs, becoming a separately listed company called Hostmore (new ticker: MORE) from 8am today. ELTA shareholders will be credited with an entitlement of MORE shares - apparently it’s 3 Hostmore shares for each ELTA share held, which will get credited to our accounts in the coming days I would imagine. So don’t panic!
Electra Private Equity PLC ('Electra', the 'Company') is pleased to announce the successful completion of the demerger of Hostmore plc ('Hostmore') and provides an update on strategy, Board composition, Hotter Shoes trading and the appointment of a new corporate broker.
I’m expecting the share prices of ELTA and MORE to be highly volatile, as the market goes through the process of price discovery to determine what it thinks each share is now worth.
Summarising the new situation from 8am today -
ELTA shares now contain just the Hotter Shoes business, and will be renamed “Unbound”, and will move to AIM, ceasing to be an investment trust, after a (formality) shareholder vote. This is all exactly as expected, there’s nothing new here.
MORE (Hostmore) shares are new, and we will get 3 for every 1 ELTA share held. This is the TGIs restaurants, and 63rd+1st new brand of cocktail bars beginning its roll out. This is the most valuable part of ELTA, so it will be interesting to see how the market values it. There should be about 117m MORE shares in issue. I’ve no idea what the starting price will be, nor where it will go, we’ll just have to wait and see. Hence I’m going to ignore the price gyrations that are likely, seeing both Unbound and Hostmore as longer term investments - they’re both excellent businesses in my opinion, that I want to hold. It could take some time for them to settle at a rational valuation, and that depends on how the market sees their prospects as independent companies, but in the short term, anything could happen because individual trades are not necessarily driven by rational calculations of the companies’ value, as we know from the markets generally - people buy & sell for all sorts of reasons, not valuation.
Hotter Shoes (to be renamed Unbound) - looks like a mini Saga (LON:SAGA) (I hold), for shoes! This could be quite a nice little share to hold, you know. Time will tell.
Unbound will initially be based on Hotter Shoes ('Hotter'), the main remaining investment owned by Electra. The transformation of Hotter over the past few years has led to a digital first proposition that has returned to growth, is profitable and cash generative. Hotter now sells to almost 30% of the female population of the UK over the age of 55 underpinned by a strong British heritage brand.
The strategy is that Hotter Shoes will broaden out into other product/service areas, targeting the over-55s, on a low-risk, partnership basis.
Board changes - not important, see RNS for details.
Hotter Shoes trading update -
This sounds good - I think it’s in line with expectations, judging from the last sentence -
Current Hotter trading has been strong and extremely pleasing in light of the market wide supply chain issues and other headwinds facing ecommerce businesses.
In H1 FY22 (ending July '21) Hotter generated EBITDA of £2.5m from revenue of £25m. As at the end of October 2021, over the prior 12 months Hotter generated revenue of £50.4m with gross margins and costs consistent with those envisaged in giving medium term guidance at the Unbound Group Capital Markets Day on 15 September 2021.
Supply chain - I can’t recall other companies saying it’s improving, so interesting to read that Hotter is seeing problems reduce now -
Hotter is seeing a reduction in the supply chain disruption evident at the start of the Autumn / Winter season in August and September. Hotter's UK manufacturing facility has provided some resilience and the reopening of supplier factories following Covid lockdowns in India and Vietnam has allowed product availability to recover in October, with further progress expected before the key November trading period.
Product demand has remained high during this period of disruption and Hotter's direct-to-consumer focused model allows some level of back-orders to be accumulated that are being satisfied as components and finished goods become available.
Recent results include higher air freight costs, which should reduce as normal sea shipping costs reduce in future. Hence higher margins in future, once costs reduce.
Note that Hotter Shoes has an interesting business model, where it imports the shoes components, and then does the final assembly in the UK. Hence product is shipped flat, i.e. compact. Whereas competitors shipping finished products are paying mostly to ship boxes with plenty of air in them!
My opinion - I’m not doing anything, will just watch with interest as price discovery for MORE & ELTA begins!
EDIT at 08:29 - I've done a very simple spreadsheet to give me a ready reckoner for how the prices of Hostmore & Unbound will compare with the old ELTA share price. I thought this might be useful to readers.
Many thanks (and my apologies) to readers Boilermaker & SurreySteve, for pointing out that I'd picked up the wrong figure for number of Hostmore shares in issue. I've now corrected the spreadsheet screenshots below, and included the Googlefinance live price look up formulae, now they're both working. Much obliged!
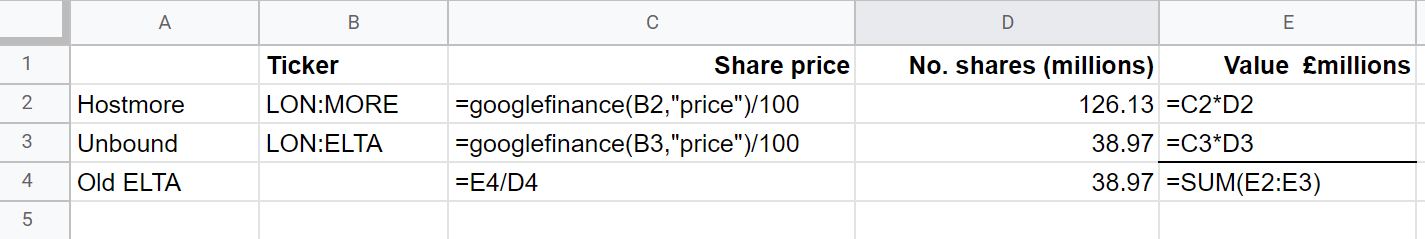
.
And here's what it looks like in normal view -
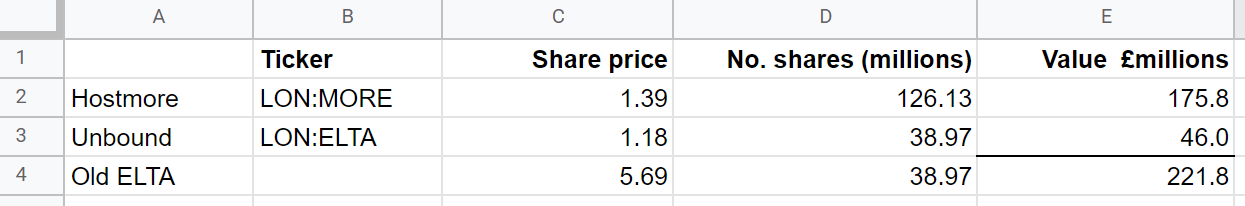
This is now automatic, so it updates itself with the prices of MORE & ELTA (which will be renamed Unbound shortly, so the ticker will need to be changed).
Day 1 was certainly a flop. So clearly the broker (Numis) has not done a proper job in lining up buyers, and matching them with sellers. Pathetic, considering £11m was extracted in fees, in total. Also Numis are notorious for completely ignoring private investors. What are they thinking? Well, they're not thinking, obviously. Since these are consumer stocks, then promoting them to private investors was a key element of floating them, I would have thought. They've not done anything on that. I did explain to ELTA management that they would need to promote the shares to private investors, but that's been ignored. As a result the price flopped on Day 1. Never mind, over time it's the performance & prospects of the two businesses which will determine their share prices, and I'm not in a rush.
.
Jack’s section
Warpaint London (LON:W7L)
Share price: 176.85p
Shares in issue: 76,752,355
Market cap: £135.7m
Warpaint has been a volatile share since listing, with a period of disappointing trading and a tricky US expansion responsible for its initial falls back in 2019. It’s come roaring back in 2021 as it’s been one of those companies that has used Covid to improve its cost base and accelerate positive change.
The share price has moderated slightly after sailing past 200p a few months back, but the underlying momentum is favourable here.

The valuation is fairly pricey: a forecast PE ratio of 33.1x falling to 27.6x (after this morning’s share price rise), so the company needs to grow but its collection of affordable cosmetics brands stand a good chance of doing so in my opinion. Earnings per share forecasts for the next two years will likely soon be upgraded, bringing those prospective PERs down.
The improving trends seen in the first half of the year have continued and the group now expects its results for the year ending 31 December 2021 to be ahead of market expectations.
Sales for the year ending 31 December 2021 are expected to be similar to those achieved in 2019 (2020: £40.3m, 2019: £49.3m), meaning an almost immediate recovery in trade. This has been driven by growth both from new and existing customers, and is despite continuing disruption earlier on in the year.
Gross margins are being maintained ahead of those achieved in 2020 and 2019 (2020: 31.1%, 2019: 33.5%), despite some increased costs in the supply chain, particularly with freight. Adjusted EBITDA (2020: £4.2m, 2019: £7.0m) and adjusted profit before tax (2020: £2.3m, 2019: £5.2m) will be ahead of 2019 and current market expectations.
‘Adjusted’ PBT accounts for exceptional costs, amortisation of intangible assets, and share based payments. The group says it is closer to the underlying cash flow performance of the business.
An interim dividend of 2.5p per share will be paid on 26 November 2021 and the shares will go ex-dividend on 11 November 2021.
Group CEO Sam Bazini says that growth in the UK is ‘particularly strong’, with ‘significant growth elsewhere internationally and further increases in online sales’.
In line with our stated strategy, we have significant opportunities for further growth, both with our existing retailers, those such as Boots where we are expecting to launch soon, and with others that we are in discussions with. I look forward to the remainder of the year and into 2022 with a high degree of confidence.
Conclusion
The group’s own measure of adjusted earnings per share in FY19 was 6.3p. This was significantly different to the reported level of 1.8p as a result of exceptional items, amortisation costs, impairment charges, and share based payment costs. Free cash flow was healthily in excess of net profit for that year due to nearly £2.5m of amortisation, so the adjusted measure looks understandable on the face of it.
FY21 adjusted earnings per share of 7p would put the company on 25x earnings per share after this morning’s 15% rise, so still on the pricier side but not exorbitant for a small, growing cosmetics company.
The group has had its share of setbacks over the years but shareholders can be rewarded for patience as management find their feet as listed operators. That might prove to be the case here, as revenues are now growing and net profit is forecast to bounce back strongly (in fact, the forecasts will be upgraded after today’s announcement).

The StockRanks have also markedly improved. All in all, it’s worth assessing the future prospects of the group as it has shown it can adapt in the face of adversity. Current trading and the outlook appear positive, the group’s founders remain major shareholders and continue to operate the company, and it is turning out to be a strong cash generator and dividend payer.

Up Global Sourcing Holdings (LON:UPGS)
Share price: 185.5p (+7.23%)
Shares in issue: 89,312,457
Market cap: £165.7m
UPGS has been on an exceptional run since its initial Covid fall as more investors cotton on to the group’s growth track record and competent management. Multiples have expanded but not as much as you might think. Earnings continue to rise, so the shares do not look too expensive.

Investors are much more focused on growing supply chain issues now, and UPGS’s business model relies on sourcing product from China, which means that sentiment has taken a bit of a hit more recently.
Nobody knows for sure how this will all play out and how well various management teams will be able to handle such issues, but it’s worth noting that brokers continue to expect earnings growth this year. There’s every chance the market has overreacted, although that’s far from certain and will likely only be clear in hindsight.

Highlights:
- Group revenue +17.9% to £136.4m,
- International revenue +4.4% to £43.5m; online revenue +23.2% to £20.6m,
- Underlying EBITDA +28.3% to £13.3m,
- Underlying PBT +36.6% to £11.2m; PBT +13.7% to £9.5m,
- Underlying EPS +34.2% to 10.6p per share,
- Net Debt amounted to £18.9m (FY 20: £3.8m), with a Net Debt/Underlying EBITDA Ratio of 1.4x (FY 20: 0.4x); financial headroom of £16.2m (FY 20: £21.3m),
- Full year dividend up 26.9 % to 5.020 p per share.
10.6p of EPS is marginally above the consensus forecast and puts the group on 17.4x falling to 13.2x.
The Salter purchase from FKA Brands Limited was completed on 15 July 2021, is now fully integrated, and is ‘expected to be significantly earnings enhancing in FY 22’. PETRA, the German kitchen electrical brand, has also been acquired and will be relaunched and refreshed, before initially entering the German market, followed by launches into other territories.
Current trading remains in line with expectations, with growth expected in FY22, despite the ongoing challenges of shipping availability and cost.
UPGS’s CFO Graham Screawn is to retire after eleven years with the group.
Commenting on the results, Simon Showman, Chief Executive of Ultimate Products, said:
As restrictions ease, it is becoming clear that the pandemic has ushered in structural changes to consumer behaviours, which are to the benefit of Ultimate Products and that we believe are here to stay. More home working and home cooking, a greater emphasis on hygiene and cleanliness, and a more considered approach to spending all complement our long-standing strategy of developing and building our portfolio of brands that focus on mass-market and value-led consumer goods for the home. The Board therefore remains confident in the Group's long-term prospects.
Conclusion
There’s not much comment on the supply chain situation, which is why sentiment moderated here in the first place, but perhaps that should be taken as a positive given the expectation of continued growth.
The folks over at Equity Development have a new note out and a fair value target of 275p. They expect adjusted earnings per share to continue increasing, from 10.6p this year to 14.1p next year and 15.3 the year after that. It’s a comprehensive note and well worth the read, far more thorough than you might see elsewhere for other companies.
There have been two recent acquisitions, with Salter looking particularly sensible. It’s a sizable and significant purchase that means UPGS shares continue to look reasonably valued even after the recent increase. It’s worth remembering that despite clocking up double digit long term growth CAGRs, the group is forecast to pay a 3.7% dividend in FY22 at the current share price.
M&A might well become a more regular feature in future as UPGS continues to drive growth. Online is performing well and the group’s move into supermarkets could see its branded products take share. International will also likely become more significant in the years ahead.
I would view any freight-related disruption as a temporary headwind that UPGS, as a quality operator, is able to navigate. Reports suggest these issues could last into 2023, so the problem should not be taken lightly, but I suspect the negative reaction to supply chain fears might end up proving to be a reasonable entry point.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
Fd Technologies (LON:FDP), formerly known as First Derivatives. Any opinion on this company. Reasonable set of half year results announced today and positive outlook for full year. Share price has almost halved in recent times, now £20
Not looked at Fd Technologies (LON:FDP) before but I note that the eps forecasts, for the next 2 years, have roughly halved this year, which may explain the share price fall.
can any one offer any views on the Pro Cook IPO (via Primary bid) 137-185p per share - expected market cap of 150-200m. It’s a family run and so far successful business, they’ll retain 60% of business. Or is it best to just stay clear of IPO’s all together and let the dust settle ?
Sadly my most immediate reference point for the Pro Cook IPO is the Parsley Box (LON:MEAL) launch earlier this year. Family owned business with a strong recent growth record and high expectations brought to the market with a fair element of founder shareholder capital being taken out from the sale proceeds via Primary Bid …. Currently down about 74% from the issue price. Not necessarily all the company’s fault but in the words of Mr. Lydon in The Great Rock ‘n Roll Swindle “ever got the feeling you’ve been had?” I’ll look at the numbers (albeit with a very wide price range being suggested) but not starting from a position of great enthusiasm.
Gus.
Thanks for your reply Gus, yes parsley box a good example of why might be best to stay clear….
I haven’t had chance to look more closely at Pro Cook website / details or figures yet (with my limited knowledge) but will feed back if find anything interesting !
BTC is nonsense...regardless of the price appreciation. There is no real world use/value case. Its just a fantasy for people who once would have been gold bugs, hard money devotees, 'Austrian' economics fans, etc....the endless myth that value can be captured in a means of exchange and value storage. The denouement when it comes will be a financial supernova like no other...no idea whether that's at $60k or $600k or $6m...the price can be anything as it is an irrelevance powered by its own world...a money virtual reality game.
That said, if you want to play it with extra steroids rather than the drugs already powering the mighty virtual coin ....then just own the 'physical' with a bit a of leverage. Not too much obvs as it is volatile...or time it if you can. Don't go dodgy Argo Blockchain (LON:ARB) whatever the hype merchants on fintwit and in here say.
Owning ARB or BTC brings the same dilemma...how to trade and entry/exit. Then ARB has the extra negative that it can never realise high BTC prices as it cannot merely "mine" hahaha / produce at high prices and will mine equally at relatively bad prices. That brings an impossible trading overlay....if you are interested in its Bitcoinness rather than just trading volatile counters Obvs if you believe you can HODL your coin and not trade and that is superior too.
In addition, mgt at ARB are dogs. Most people promoting BTC are clueless or cynical.
mojo word, out
BTC is such a waste of energy, so much for saving the planet. It should be banned on environmental grounds. We should be reducing our energy consumption not increasing because of crypto currencies.
:D Gotta love your conviction
The thing that always amazes me about anything crypto is how certain so many people are that they are right, in both camps. Believers and non believers - so polarised it's almost "unbelievable"! The other side of the trade is always apparently an idiot........
As venn diagrams go I sit somewhere in the middle and seem to find that's a very small space to squeeze into.... My view is BTC currently behaves like an asset class, so trade it like an asset class until / if it doesn't. Argo Blockchain (LON:ARB) is just an operationally geared play on that - there are merits and demerits.
Okay...you are clearly correct as you state you are more reasonable than me...and everyone in here knows I'm an unhinged madman.
But brushing aside your semantic play, you own the assets so actually you are the high conviction one. If the argument is to own anything that trades like an asset then why not all the other coins? NFTs too. Wine. Etc. Just as something is asset-y I fail to see how I'm extreme for not being involved. In fact, I'm uninvolved in most things as, extremely, I choose not to be everything.
I see the errors in my drive by banalysis of Argo Blockchain (LON:ARB) above on reflection...so I'm surprised not to be pulled up analytically on them and instead getting some semantic fluffing about...maybe you don't know what you are invested in and why ;)
Have fun staying rich
I don't have you down as an unhinged madman, nor did I say you were extreme for not being involved.
The certainty I refer to are the use of words like "nonsense", "fantasy", "financial supernova like no other" in your description around any ownership of BTC. It's interesting that crypto draws out this type of extreme reaction on the naysayer side and equally vice versa on the "believer" side. You are not alone in your view but I find myself in a very small crowd sat somewhere in the middle. In the main the middle bit of the venn diagram will be largely populated by neutrals whilst the believer/non believer will be a much smaller %age (often sub 10%). Not many (if any) asset classes draw such polarisation across such a large community.
I'm certainly not high conviction by owning a little crypto. It's a very small portion of my portfolio. But yes, wine I own too - I collect it; cellar it; like to drink it and make a reasonable annual return on it by knowing broadly what to buy and when. At least when Armageddon comes I won't be thirsty ;)
The burden of proof remains heavily on crypto to prove its a durable and significant asset class. It hasn't yet had to endure a significant economic downturn (covid just doesn't count) or a sustained period of reallocation away from it (as happens to all asset classes over periods). Yet 'reasonable' people attribute all sorts of established properties to crypto...got love financial shaman.
Big finance always jumps on something that can make some money regardless of its value. Big hedge fund guys that support crypto...do they really?...or are they jumping on a momentum trade and using their cred to pump the trade. There is nothing more beautifully reflexive as an 'asset class' than unreal crypto at the moment
A speculation in crypto I respect. An investment in it stretches credulity. What's the asset backed by other than hype of the great unravelling of fiat and the coming rapture of real money/value that a dude called Satoshi saw...
Its a millenarian cult. Now some of these cults go on to become established durable sects through history...they stick the narrative...but most just wing nut into obscurity taking down their followers.
I await the rapture / supernova implosion. Its clearly absolute nonsense as a genuine economic linked asset class...it just may take a while to realise this in our hyper inflated asset class world.
I know nothing. I'm just a sceptic. Unless you can meme surf or trade very well, scepticism is the only way through financial markets.
PS The only reasonable guy in the world stuff drinking fine wine as you sagely place yourself in the middle of your venn diagram of reasonableness that you have constructed as the measure of reasonableness....<yawn>...tedious self aggrandisement
Ya see - there you go again. can't help with the "PS" abuse - you're a charmer I must say! and self aggrandisement?.....ha! pot and kettle springs to mind.......
I didn't purport that the middle of the venn was the reasonable or even correct place to be: just pointed out the quite strange phenomenon of finding the middle being sparsely populated. The polarisation is unusual. You made up the rest all by yourself ;)
I first heard about BTC back in ~2010 when it was around $10 and decided it was for criminals and illegal purchases of stuff (anyone remember the silk road).
Very little has changed since then other than a lot of other people with debatable moral values have piled in.
...and others for whom it does make sense.
I am lucky enough to live in a country where the currency gently depreciates and the govt does not suddenly declare the £50 note to be 'not legal tender anymore' at short notice.
Those living in parts of s. america / africa or india and possibly china have no such luxury.
I think BTC is evolving towards a global "distrust of my govt / currency" index that is being driven by the wisdom / stupidity of crowds.
Will its value persist? I think so. Will that be higher than today? No idea.
Do I regret not getting some back then, no, but I would have liked the money.
so, yes then :D
Did you know the world wide web broadly gained acceptance and popularity because of pornography.......without it the widespread adoption of the internet may have taken a different course, but here we are........ often these types of changes are invented with good intention, used nefariously and then once they gain widespread adoption are used for the purpose they were originally intended.
Probably a dumb question, but if there can only ever be 21 million Bitcoin and about 18.9 million have already been mined (about 90% of the total) is Argo Blockchain (LON:ARB) running up against diminishing returns as it gets harder to mine new Bitcoin as the residual stock of to be mined Bitcoins is depleted? Not sure if the figures from this site https://www.buybitcoinworldwid... are bone fide but at the indicated newly mined global Bitcoin rate of 900 per day the residual 2.14 million will have been mined out in about 6.5 years. How can a miner trade on a p/e of 8 to 9x with a global resource life of less than 7 years?
Gus.
The bitcoin mining output halves every 4 years so the last bitcoin isn't expected to be mined until 2140.
Also, the value of transaction fees for mining a block is increasing so expected to become a larger source of income for miners over time.
Just wondered if any more knowledgeable folks had any thoughts on Chemring (LON:CHG): rns released today to say figures will be in line with expectations price has ticked up slightly.
There are a lot of take-over bids happening in this sector at the moment all be it not many have yet been waived through/completed.
It also has a cyber security arm called Roke which many think is the jewel in the crown.
what do you guys think of TCAP and their trading statement? Isn't LON:TCAP a stock that will benefit from increased volatility and more trading of commodities?
Up Global Sourcing Holdings (LON:UPGS)
I've held for a few years and really like the company and think the stock has been ridiculously cheap (32p) to underpriced for prospects and quality (at c.230p) over the period. My view is that its never really been 'fully discovered' by investors in that I don't think its business model and strengths have been recognised.
My two key factors that I think are under appreciated (there are many other important things but I think investors have better handle on them):
There's perhaps a third point which is their product design, ownership of each piece of 'IP" per product and oversight through the manufacturing process. But I think this is more recognised now and is at best a point 2.5 (though I'd still say its underpriced).
At 200p its not OMG cheap...but its also not expensive and has a long runway to keep on creating further value.
A negative? Well if the growth in 1 above comes through more strongly then the biz will need to update infrastructure inc potentially UK haulage relationship. This is a good problem from growth...but obvs investors like their miracle costless growth.
Jack, thanks for the notes on Warpaint London (LON:W7L) , which I currently hold.
I wonder if part of the reason that Revenue is either more modestly up (versus 2020) or flat versus 2019, but margins are up, is that the "close-out" business (which I read as flogging off other companies excess inventory) has dropped versus both periods, albeit more significantly since last year. I suspect that a little pivot towards their own sales has helped overall margins up and is producing higher quality Revenue. This was not specifically mentioned in todays update, but would at least partly explain some of the trends seen.
In the discussions of Hotter/Unbound (Electra Private Equity (LON:ELTA)), little has yet been said about the potential for the proposed leverage of the Hotter database to create a more general 50+ e.marketplace. Management seem to be getting on with it - first new product aimed at over 50s is due H1 2022. When the market starts to think about Unbound separately, I suspect this potential may generate almost as much interest as the shoe business
I just want to say thank you to Paul and everyone else in the comments for the information/thoughts on £ELTA. This is the sort of share I wouldn't have touched before joining Stocko as I would have seen it as too complicated, the opinions/research has really helped an inexperienced investor to take the plunge on such a company.
In case people arent aware, for Electra Private Equity (LON:ELTA) , =googlefinance("ELTA") in a cell in Google Sheets should bring in the up to date share price automatically. It's not working yet for Hostmore though.
Yes that works for Electra Private Equity (LON:ELTA) but I have tried =googlefinance("xxxx") on a folio and 6/20 were incorrect, problem seems it will pick other stocks with the same ticker, so it pays to double check the prices. Some of the ones that were incorrect are £TMRM, Sdi (LON:SDI), Solid State (LON:SOLI) and £RIO.
You put in column A say 'LON:ELTA' and then in the next cell you can put: =GOOGLEFINANCE(A18,"price") and that will bring up the price. The 'LON' ensures it's from the LSE.
Thanks, I will try that.
Sometimes it doesn't like XX. (dot on end) or ABCD (4 letters). You can use "LON:"&A2&"" to build the code when Cell A2 is the ticker ref only. So ELTA in CellA2 and CellB2 =GOOGLEFINANCE("LON:"&A2&"","price"), you don't need to add "price" as that is the default attribute. For a full list of attributes see https://support.google.com/doc...
Please follow the simple instruction to put the ticker so we know what you are talking about.
Would love your thoughts on Argo Blockchain (LON:ARB) results today. Yes, they mine a volatile asset, but their numbers are seriously impressive (full disclosure, hold a long position).
@Mnomis - Me too (long on Argo Blockchain (LON:ARB)) but the wait for share price recovery will likely be a long one. NASDAQ listing was a damp squib in the end and has failed to match value multiples of its competitors. CEO Peter Wall a very astute communicator but the 'Argonaut Army' appear to be deserting him. He has been less than transparent about machine acquisition too. With Bitcoin looking bullish (price wise) one would hope that we would see more support. It feels as though the 'crowd' has moved on.
Lol Mnomis - if you are a regular reader you will know that Paul thinks Bitcoin is a bubble and virtually worthless so unlikely he will be interested in Argo Blockchain (LON:ARB) as a miner.
There was definitely a crowd in Argo Blockchain (LON:ARB)
I was long pre-IPO and sold 80% of my holding around an average of 200p (my best return all year) and I know a lot of early investors were doing similar. The placing at 180p (I think) did generate a lot of interest though and some were keen to put money back in at that level. I think the NASDAQ listing was a damp squib because it was already on the OTC market and I suspect many US investors that wanted to be long already were.
In my view the problem is that Bitcoin is a bit like marmite. If you believe in it as a long term asset that will effectively continue to increase as supply gets smaller and smaller then the results of Argo Blockchain (LON:ARB) look excellent and they should continue to benefit both from price appreciation and mined coins particularly as new machines and the 100% renewable energy comes online. In that case valuation could be construed as cheap. If you believe Bitcoin is a bubble then Argo Blockchain (LON:ARB) is well overvalued
I think as quickly as the FOMO crowd leaves, they will be back when BTC hits new ATH's and clears the $60k's. PW is building an impressive company imho.
If you believe in Bitcoin, then to my mind, it would make far more sense to simply buy some Bitcoin. If you buy into Argo Blockchain (LON:ARB) then you have the Crypto risk sitting atop some potentially dubious governance risks. Whatever your view on the motivations behind the recent short attack, I don't think anybody should consider buying Argo without reading the entire Boatman Capital paper (https://theboatmancapital.com/...) and researching the history of the founders (which from memory is also a bit dubious although I forget where I read it).
I don't have any position and the best lesson that I've learnt from using Stocko is to always give the widest possible berth to anything remotely racy, exciting, blue-sky, jam-tomorrow, fashionable and most especially anything that smells funny and Argo stinks IMHO.
Like I said - Marmite....... :)
but the founders aren't there so that's not really relevant and the business model completely changed from a MaaS (mining as a service) concept when they started it to a pure miner when Peter Wall took over. The short attack was opportune and not unexpected.
Argo Blockchain (LON:ARB) mine around 200 bitcoin a month (+/- 40 depending on difficulty) and are in the process of expanding that to 300-400. Once the new Texas facility is in place all energy will be green renewable which alleviates some of the concerns around it contributing to emissions, which will help.
Assume 300 BTC p/m at current price $62k at a margin of 85% is £11.5m of gross profit p/m or £138m p/a less corporate costs and tax circa £100m PAT. current consensus for next year is £63m for reference on less BTC mined and assuming a price of $50k.
Should have around £75m in net cash post US IPO so at a market cap of £600m it's on a PE of sub 10 for next year and around 5 or 6 for the year after.
If the price of BTC doubles then Argo Blockchain (LON:ARB) should go up well over 3* at a relative valuation so there is a strong operational gearing effect of owning Argo Blockchain (LON:ARB) versus BTC itself.
That's the Bull case. Should it be worth 8 or 9 * PE multiples? I don't know. That's cheap for the market itself but if, as a good number of people do, you think BTC has a very limited shelf life and will collapse to low prices then it's expensive.
Great comments thanks. 1. Are you bullish BTC - Y / No. If Y, how best to play as a UK investor? My money is mostly on Argo (some in BTC, but tax issues).
I try not to get too carried away with BTC because crypto is such a polarised topic. I get both sides of the argument so I try and look it based on its behaviour as an asset rather than as a believer or non believer.
Given the way it has traded over the last 10 years I tend to think it will stick around as a digital store of value if nothing else. By that I mean if you look at how it has traded it has all the hallmarks of an asset class; an immature and therefore volatile one, but an asset class nonetheless. You have seen it bubble, crash, rebase and rise again numerous times with an upward slopping curve over the period. I see a number of wealthy investors putting 1% of their wealth in it - hedge or genuine belief I don't know but I suspect that's likely to continue for the time being. There are ETFs, Funds, Derivatives in the market adding to liquidity and credibility. All of that plus the finite and decreasing supply suggests to me that over time it will rise but quite possibly with crashes along the way.
I own a bit ; some BTC and also ETH as long term holds. I bought Argo Blockchain (LON:ARB) at around 8p pre IPO and cashed out 80% around 200p. The rest I'm happy to run as a play on the theme because I think it might well be very cheap. But I am also very conscious that my view is from a position of having had a very good return on the stock, so I am both biased and hold a natural affinity to it anyway.
Well, the point is, based on the results, this is a jam today company (and was massively mispriced a year ago). The Boatman Capital report was pretty poor and showed a complete lack of understanding IMHO (confirmed by a Nasdaq listing process handled by reputable IB's post). If you forget about the underlying for a minute, and just look at the numbers, it looks interesting.
Electra Private Equity (LON:ELTA) how are people adjusting the price if it’s in their folios?
Couple of comments in the thread about this
Yes I have just seen them now, thanks. I think I will sell Electra Private Equity (LON:ELTA) in my Sotockopedia folio yesterday and buy back today, then add MORE when it on the system.
I did that but the folio is still wrong, I will report it. I see what Stockopedia is doing but it's not right, it should work off the price I paid for the shares today, not apply the fall in price to my holding, had this issue before when buying shares after a fall.
I have deleted my purchase today, I will add tomorrow or later.
When will be able to sell Hostmore?
yeah - wouldn't it be better to sell the whole Electra Private Equity (LON:ELTA) at original cost to generate a nil return and then buy 1 Unbound and 3 Hostmore at the relative share ratio?
ie if you bought Electra Private Equity (LON:ELTA) at 400p then you would buy 1 Unbound at 100p and 3 Hostmore at 100p
it's not exact on capital gains as they increased share count in Hostmore by 9m shares but it is close.
The folio shouldn't be wrong, not withstanding the fact you can't input Hostmore yet.
The daily / rise gain figure is fairly irrelevant - the total holdings value and the individual stock line profit / loss should be correct. If it was possible to put in the Hostmore shares the gain/loss across both Hostmore and Electra would balance out.
Tomorrow it will look ok, but nothing will have changed in your total portfolio value (notwithstanding the movements in share prices).
On odd days like this one has to be wary of the daily gain figures - it is necessary to be mindful of this whenever one adds a buy or sell transaction of a share that has moved significantly - the daily gain seems to work by summing the individual gain/loss of each share which is determined off one static price per day (I've never worked out if it's last night's close or this morning's open, but to be honest it doesn't actually matter) so isn't a highly reliable figure. The total portfolio value is live though and in my experience is always correct within the bid/offer spread aggregate.
You should be able to sell Hostmore as soon as your provider puts them in your portfolio. To the best of my knowledge (happy to be corrected as always) there's no lock up period on this stock.
Electra Private Equity (LON:ELTA) Well it is now showing +9.57% instead of - 78%. If I had some spare folios I would experiment with prices to see the effect of buying stocks after a large decline or gain. I'm not convinced it is based on values as otherwise the folio would correct after close? If it was 10% of my folio, I would have been down around 7.8% today.
I can't sell Hostmore yet, pity as the price keeps falling, now 136p.
Thanks Paul, was just doing the same... for ease im going with 100 and 150. None of my platforms will let me deal More.... looks like its a bit better at 160 ish.... bit of a false market at the moment, my guess is institution's can Buy/Sell Electra Private Equity (LON:ELTA) and Buy MORE....and private clients can Buy Electra Private Equity (LON:ELTA) depending on your platform of choice. IG is possibly better. I wouldn't have thought there would be sellers of MORE anyway....
sorry It's Petrofac Petrofac (LON:PFC)
£pfc Would appreciate some knowledge from the more experienced investors in Stocko on this:
I received a corporate action notice saying I could buy £pfc shares at £1.15 but the market price has remained roughly 10p higher. Why would that be? As normally on take overs etc, the market price adjusts straight away to negate any possible value left for the small guy!
sorry Petrofac (LON:PFC)
Hi dennis carr.
This is part of a refinancing of Petrofac (LON:PFC) after their recent settlement with the SFO over historic fraud carried out by former management. This included a rejigging of both their debt and a discounted equity raise through a combination of a Placement to institutional investors and an Open Offer to existing shareholders. You (and I, I hold Petrofac (LON:PFC) too) are being offered some shares at a discount on similar terms to the institutions albeit it takes longer to do this for the PI than the II placement that was all tied up in a single trading day last week. Taken together the two placements are similar to a Rights Issue where equity is raised at a discount and everyone gets offered the same terms at the same time. With a rights issue, the new market price is a function of the original price, the discounted price and the proportion of the new to old shares. For example, if a company’s shares are valued at 150p and it offers new shares at 115p in the ratio of 1 new for every 4 old held, the new market price would be ((150 x 4) + (115 x 1))/(1+4) or 143p. Unless there is other news/negative sentiment driving the share price down, the new combined price is usually higher than the discounted price of the new shares as is the case with Petrofac (LON:PFC) .
What it means in practical terms is that you (and all the other shareholders) are being offered some new shares at less than their current market ex-rights price. Logically, you should buy all the shares offered and either hold them if you want more Petrofac (LON:PFC) exposure or sell them at the prevailing market price and take the “profit” from the purchase/sale. (It’s not actually a profit, it’s monetising something you already own but that’s quite an esoteric point) The main risk in doing that is that the market price falls below the new share price between deciding to take up your shares and then being able to sell them. Hope that makes sense.
Gus.
Thats an excellent explanation Gus. Thanks for your time in doing this.
KR - Dennis
Electra Private Equity (LON:ELTA)
Thanks Paul. The new number of shares in Hostmore is 126,127,279, per their RNS this morning. Slightly higher than the 117m in your table above.
I would reinforce this point. The Hostmore prospectus https://www.hostmoregroup.com/...
lists 126.1m shares being in issue; 9.2m shares being issued to management + 39x3=117 being distributed to existing ELTA shareholders.
I see on Sharepad level 2 that Electra Private Equity (LON:ELTA) has opened @ 125-135p bid/offer.
Hostmore price showing as £1.56 per share (on their website - share price page)
Electra [price is £1.13 according to HL
So closing price ELTA (£5.50)
Combined now - £4.68 + 1.13 = £5.81
Link to the Hostmore share price page:-
https://www.hostmoregroup.com/...
Gus.
Somewhat unsatisfactory update from Gaming Realms (LON:GMR)
They’re making good progress with getting licences for their gambling games. Michigan licence is now upgraded to a full licence and application for a licence from Ontario has been submitted.
They are confident of meeting full year targets. However, I think that given the momentum that they should have from new licences in NA we could have expected that they would achieve a little more. We’ll just have to wait and see. Q3 revenues up 35% year on year.
But a key thing to consider here perhaps is that they should move into profitability by the end of the year. That, coupled with strong growth and a P/E ratio forecast to be about 23 in 2022 should make for a reassessment of this stock by many who wouldn’t touch it so far.
So, still quite nervous times but I am happy to continue to hold even though it is currently on a sucker stock rating according to Stocko.
Hi Paul
What are your thoughts on the Cambridge Cognition Holdings (LON:COG) CFO suddenly stepping down? Sounds like he was sacked.
SP now below 130p. Potential top up opportunity ?
apologies seen comments below. Can’t delete the comment from my mobile. Please ignore.
Hi Paul
What are your thoughts on the Cambridge Cognition Holdings (LON:COG) CFO suddenly stepping down? Sounds like he was sacked.
SP now below 130p. Potential top up opportunity ?
Electra Private Equity (LON:ELTA) thanks for posting your thoughts Paul. How is everyone going to manage their portfolios? I’m thinking assign an Elta dividend and use that to “buy” MORE shares, it’ll mean an unrealised loss on Elta that doesn’t really exist and throw out my dividend average but I can’t see any other way of doing it other than a fake sell of Elta and a fake buy of Hostmore.
I wonder when Stocko will get updated and we can add the Hostmore shares to our portfolios
Morning IGPJ.
I had the same question about how to account for the Electra Private Equity (LON:ELTA) split. I think both your approaches work although it’s not really a cash dividend, not least how and when do you ascertain the cash amount being distributed? I think I’ll probably go for a notional sell of Electra Private Equity (LON:ELTA) at last night’s close and a buy today of MORE and a purchase of residual Electra Private Equity (LON:ELTA) shares pending their rebrand as Hotter. It may take a bit of number fudging to get the ins and outs to match to avoid any leakage/artificial gains. As the shares are in my ISA, no CGT considerations as such so possibly the cleanest way of doing it.
Gus.
Ok, I think this makes the most sense over the dividend plan, the numbers are cleaner, but I guess I will have to “sell” all the elta at the previous close and “buy” both “elta” and “more” this morning. Like you say it’s going to be a fudge as there’s a 30p discrepancy between the closing price and the opening price. What I am going to do to manage that is - I have 3x more shares for each elta share, thus I will divide last nights closing price by four, allocate 1/4 of the cash to Elta and 3/4 to More. Should work out about right.
re Electra Private Equity (LON:ELTA) - do any of the holders know what proportion of bookcost of Electra Private Equity (LON:ELTA) passes to Hostmore for CGT purposes? many thanks
I wonder how much more Thg (LON:THG) will drop today!
The drop is truly staggering! I think this has to be targeted short selling.
I thought the same thing about Thg (LON:THG) but so far the disclosed short positions seem moderate given the steep and continued fall in the share price. Is it just a massive down rating of a former glamour stock?
Gus.
I like the advert at the top, how to cut your electric bill on a shorting site, haha.
Wish I had shorted this when it was at the 700p+ mark! Utterly insane valuation.
It was a fantasy valuation of Thg (LON:THG) from the start. Wish I'd shorted it, as the valuation didn't make any sense whatsoever. It was all hype in my view. It's still very expensive for what it is, but they managed to convince some gullible fund managers that it was some kind of tech platform.
It's still very expensive for what it is
At 1x NTM revenues is it still expensive, even for a bog-standard e-commerce operation? Core business still growing at c20%. Valuation now looks about par for the market and the (dubious) tech platform now comes for free.
It's still very expensive for what it is
At 1x NTM revenues is it still expensive, even for a bog-standard e-commerce operation? Core business still growing at c20%. Valuation now looks about par for the market and the (dubious) tech platform now comes for free.
Do you feel there will be a similar situation at DARK (LON:DARK)? I know this has entered the FTSE 100 but I cannot understand the valuation at all? This is still a loss making company and with the end of the insider lock up tomorrow there could be a big sell off potentially? I think the investment case for the future is very strong as cyber is going to be critical to the digital economy but at current valuation the investment case looks a bit weak.
Darktrace (LON:DARK) looks expensive compared to $MIME which is London based but listed on NASDAQ. MIME results are out today but it does a make a profit. Looking at some reviews of both, DARK does seem to have some advantages and is well rated but as you say the stock valuation is a problem.
Re. Darktrace (LON:DARK) , worth visiting (if you haven’t already) this thread and reading up through the timeline. https://www.stockopedia.com/co... . The share price had a very strong run from the IPO taking it into the FTSE 100 index but much of the puff has been taken out of its sails from a recent Peel Hunt broker report. The report raised a few pointed issues on valuation and called a target share price of 473p when the shares were at about 900p and several other brokers had targets north of 1,000p. Tied in with the ongoing Mike Lynch (Autonomy/ Hewlett Packard fraud allegations) extradition saga to the US and the possibility that he may have to sell his substantial holding to raise a war chest to fund his legal defence you have the toxic mix of a potentially over valued emperor with no clothes and a substantial distressed seller lurking in the background. Those in the know seem to suggest Darktrace (LON:DARK) has a good underlying product but maybe not good enough earnings potential to prop up the very high recent valuation. No position.
Gus.
I have been watching Thg (LON:THG) crash and wondering if there is any price that might be considered a buy. I am unsure how to value it personally. BlackRock's announced sale of 58 million shares at a discount to market price further undermines the investment case. At -75% of ATH I'd be interested in Paul's/ other investor's views are on this. I don't hold.
It looks like lots of Stocko investors have been buying Thg (LON:THG) all the way down over the past 3 months, judging by the community buy/sell rating. 41%, which is one of the highest readings I've ever seen.
Mind you, the sell rating of 14% is also higher than most other shares at the moment. So looks like a bit of a polarised view in the community.
This is not buying, it is just put in a folio. 41 is quite high but I have seen one` in the 90s which did not seem credible. Most of the shares in my folios I don't actually hold so it's not very accurate.
I thought that holdings in"watchlist" folios were excluded from this calc? That the only holdings included are those that ££ and shares inputted into the folio?
Obviously holdings in "fantasy" or "simulated" portfolios will count, as Stocko as no way to verify those trades were actually executed by the user.
What do they mean by watchlist? Presume holdings with no monetary amounts (empty). Nearly all mine have bought amounts, same as my actual holdings, then I can judge the performance. How do you judge performance if you don't put in buy amounts? I have several NAP type folios set up.
If I had a spare folio I would try it. The new site has screwed up some of folios as you can't hide empty holdings, you can only hide closed stocks, unlike the old site.
Just had a look at the C-Suite experience. CFO sticks out as way out of his league. Joined 2004 as CFO to THG. Obviously much smaller company then. Only prior experience was Head of Finance for a small company, and as an accountant in PwC, guessjng quite junior.
No wonder Thg (LON:THG) are unable to put out a convincing and robust financial and numbers story.
Along with a new chair, they should refresh the C-Suite with experienced, FTSE100 management to add credibility.
Potential MBO at Sensyne Health (LON:SENS) (I hold) announced this morning. This is a new one on me, so will be interesting to see how it impacts SP. It will have to be at quite a premium to wipe out my current loss.
Can't say this update from Cambridge Cognition Holdings (LON:COG) makes entirely comfortable reading:
Directorate Change
Cambridge Cognition Holdings Plc, which develops and markets digital solutions to assess brain health, announces that Michael Holton, Chief Financial Officer, will stand down from the Company's Board with immediate effect to focus on other opportunities.
The Board is looking to appoint a replacement Chief Financial Officer, further details of which will be announced in due course. In the intervening period, Nick Walters, Cambridge Cognition's former CFO who stood down earlier this year, will support the Company during the transition.
https://www.investegate.co.uk/...
Yes, the new CFO at Cambridge Cognition Holdings (LON:COG) (I hold) clearly hasn't worked out. It's always a bit unsettling when this happens, as companies don't announce the real reason when Directors leave unexpectedly. Were they no good, and have been sacked? Or did they find something they don't like, and have left? We don't know.
The figures are very simple at COG, and the newsflow has been excellent, so personally I'm not overly concerned by this.
Regards, Paul.
many thanks for your thoughts Paul. I also have a meaningful stake in Cambridge Cognition Holdings (LON:COG) and don't plan to do anything on the back of this update. Just noteworthy I think that the departing CFO was not thanked, so probably not entirely amicable parting. Like you say, as outsiders we will never know for certain.
How does Cambridge Cognition Holdings (LON:COG) recognise revenues (and profits) from multi year contracts? Could there be something in there for a CFO disagreement?
Re Cambridge Cognition Holdings (LON:COG) . Never a good sign when a CFO leaves with immediate effect and isn't thanked.
Up Global Sourcing Holdings (LON:UPGS) full year results out. Roland sold them from his SIF portfolio only last week due to the company no longer meeting his criteria, I couldn't make my mind up, due to shipping issues, as they still meet mine (Slater screen , plus a few stockranks for added comfort)
Can only see the word UP in the results
· Total revenue increased 17.9 % to £136.4 m (FY 20: £115.7 m)
o International revenue up +4.4 % to £43.5 m (FY 20: £41.6 m)
o Online revenue up 23.2 % to £20.6 m (FY 20: £16.7 m)
· Underlying EBITDA^ up 28.3 % to £13.3 m (FY 20: £10.4 m)
· Underlying Profit Before Tax^ up 36.6 % to £11.2 m (FY 20: £8.2 m)
· Profit Before Tax up 13.7 % to £9.5 m (FY 20: £8.4 m)
· Underlying Earnings Per Share^ up 34.2 % to 10.6 p (FY 20: 7.9 p)
Mind you so is net debt
· Net Debt amounted to £18.9 m (FY 20: £3.8 m), with a Net Debt/Underlying EBITDA Ratio^ of 1.4 x (FY 20: 0.4 x)
But this UP is comforting.
· Current trading remains in line with expectations, with growth expected in FY 22, despite the ongoing challenges of shipping availability and cost
Who got it right? I suppose we will find out what the market thinks in 53 minutes. Any thoughts from the experts?
ps. Found another UP
· Full year dividend up 26.9 % to 5.020 p per share (FY 20: 3.955 p per share)
i think both can still be 'right' regardless as to the Up Global Sourcing Holdings (LON:UPGS) share price movement today.
to me, the most important thing is to have a strategy that works for you, and stick to it. there will be many many share price moves that one's strategy misses and can be left for someone else.
disc none in Up Global Sourcing Holdings (LON:UPGS)
Up Global Sourcing Holdings (LON:UPGS) results seem to be slightly ahead of Stocko forecasts. Debt is up because of Salter acquisition, which I think is a good one. I bought back in on the recent dip. This was featured at the recent Mello presentation.
CFO is retiring next year.
And that Up Global Sourcing Holdings (LON:UPGS) full year divi is twice covered. Our full thoughts in the note here:
https://www.equitydevelopment....
And you can join us at 1.30 today if you want to quiz management further:
https://www.equitydevelopment....
Demerger today for Electra Private Equity (LON:ELTA), going to be interesting to see where Hostmore and Unbound go from here
Certainly interesting day ahead although the final section in the Electra Private Equity (LON:ELTA) update stood out.
* HOTTER IS SEEING A REDUCTION IN SUPPLY CHAIN DISRUPTION
EVIDENT AT START OF AUTUMN / WINTER SEASON IN AUGUST AND SEPTEMBER.
MORE listed at 150p first thing. I guess that is 450p of the ELTA share price yesterday which means the Unbound / ELTA part is going to be around 100p.
From the Electra website the listing change for Unbound (main market to AIM) is due 22Q2 when ELTA will cease to be an investment trust.
What's the easiest way of finding out Hostmore market cap? I see it's currently trading around 150p but I am not sure how many shares are in issue.