Small Cap Value Report (Fri 1 Mar 2024) - AVO, ITIM, ITV, ORCH, EAAS, FDP

Good morning from Paul!
That's it for today, have a smashing weekend.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
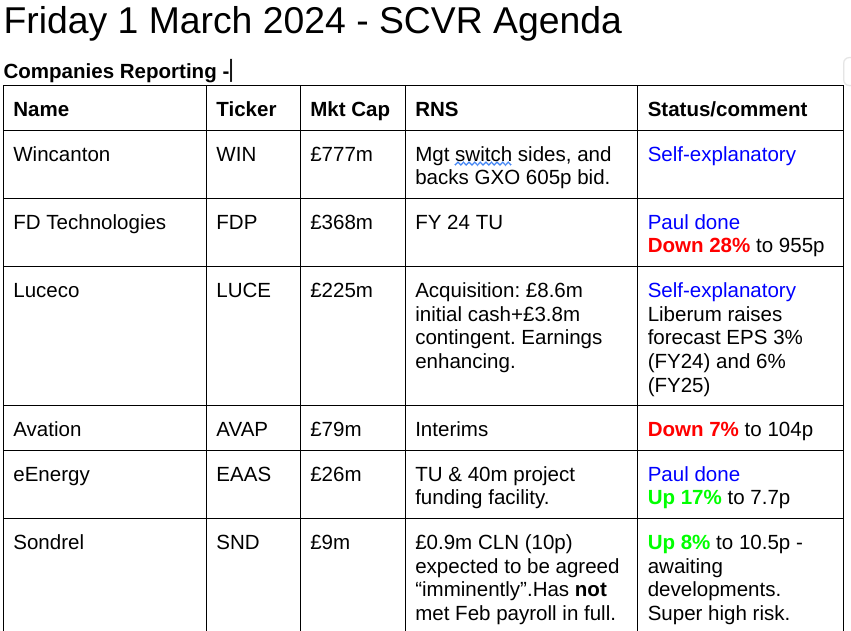
Other mid-morning movers (with news) -
ITV (LON:ITV) - up 15% to 64.3p (£2.6bn) - Sells stake in streaming service BritBox Intl to JV partner BBC Studios for net proceeds of £235m cash. “The Board intends to return the entire net sale proceeds to shareholders through a share buyback which it expects to launch imminently after the full year results on 7 March.” - that’s 9% of the market cap, impressive. StockReport shows fwd PER 6.8x, and 8% yield. Cash-hungry pension deficit. Worth a closer look maybe? 8-year downtrend on chart.
Orchard Funding (LON:ORCH) - down 24% to 18.5p (£4m) - specialist lender says it has been hit by a £500k fraud. Reviewing all remaining loans & introducers. FY 7/2024 “material adverse impact “. Previous profit warning on 2/2/2024 due to 20% of its business being withdrawn (re GAP insurance) - also said to have a “material adverse impact”. Historically it’s been profitable & dividend paying. So now, at a quarter of NAV, it’s either cheap, or a can of worms. Controlled by CEO, holds 54% - delisting risk? AMBER.
Quick backlog comments -
Advanced Oncotherapy (LON:AVO) - shares still suspended - PAUL - an ominous update yesterday said there have been delays to its attempted refinancing. Now has “negligible” cash, and “significant debt”. Discussing a short-term bridging loan, but warns insolvency is looming. Paul’s view - I very much doubt this share will come back from suspension, looks increasingly like a zero, so holders need to prepare for the worst, and hope for a miracle.
ITIM (LON:ITIM) - up 8% to 32.5p (£10m) - Trading Update [ahead] - PAUL - AMBER - I mentioned this retail software company here (for the first time) 3 days ago, on news of a big contract win with QUIZ. Still loss-making & cash-burning. Yesterday’s trading update for FY 12/2023 is quite good - revs up 15% to £16.1m, ARR exit rate £13.2m (82% recurring revenues), EBITDA £680k (ahead exp of £300k). Cash £1.9m as expected, down from £2.7m in H1, so it’s still burning cash. Note it capitalises c.£2m pa costs, so EBITDA is not real cashflow. Paul’s view - I’m intrigued, this looks potentially interesting, but updates might be pumping share price ahead of a fundraise, as I think bal sht needs reinforcing. Founder owned/managed, with small free float.
Summaries of main sections
Eenergy (LON:EAAS) - up 27% to 8.35p (£32m) - Trading Update & Nat West deal - Paul - AMBER/GREEN
I've previously been negative on this energy services group, as it had a horrible balance sheet, and looked precarious. However, it has since disposed of the core business (positive, as I didn't like its business model at all), paid off all debt, and is now expanding other energy projects, using a new funding facility from Nat West. I need to do more research, but my initial inkling is that there might be an interesting punt here? So it's worth a closer look I suspect.
FD Technologies (LON:FDP) - down 28% to 955p (£268m) - Trading Update & Structure Review - Paul - RED
A very confusing update, but the market clearly hates it. A year-long strategic review has now concluded that it should separate its 3 businesses. I don't see how that will add any shareholder value. My reading of the numbers shows that this seems a poor quality collection of companies that don't generate any real world cashflows. So the market cap still looks extremely generous to me. Although tech investors may see things differently.
Paul's Section:
Eenergy (LON:EAAS)
Up 27% to 8.35p (£32m) - Trading Update & Nat West deal - Paul - AMBER/GREEN
Checking my previous notes for this energy consultants, I’ve only looked at EAAS twice before -
29/9/2023 - RED - Good: 12m interims break into profit. Bad: horrible balance sheet & cashflow.
8/11/2023 - AMBER/RED - said in talks to dispose of core business for £30m. My view - it badly needs to refinance. Luceco “invests” - query over unpaid invoices.
22/1/2024 - says it has “entered into an agreement” to sell for net £25m.
9/2/2024 - disposal completes, and cash received.
That’s brought me up to date, and has addressed my concerns over the balance sheet & funding.
On to today’s news -
£40m Project Funding Facility with NatWest and Trading Update
eEnergy Group plc (AIM: EAAS), is pleased to announce it has entered into an agreement with National Westminster Bank Plc ("NatWest") to provide up to £40 million of project funding (the "Facility") to finance energy efficiency and onsite generation technologies for the Group's public sector customers.
The Facility is a new financing solution created by both parties. The Facility has been designed exclusively for the funding of public sector energy transition projects across the full range of eEnergy products. The Facility will be deployed through a newly-formed special purpose vehicle ("SPV") owned by eEnergy, with eEnergy becoming the operator and retaining ownership and interest in the economics of each completed project.
The Facility is available for a period of 12 years with investment planned over the first 24 months. The Facility is split into two equal tranches to match the expected profile of drawdowns and optimise fees. The second tranche will become available to draw-down once 75% of the first tranche has been deployed, subject to customary final approvals.
The Board believes that this new Facility gives eEnergy a unique, compliant off balance sheet solution for public sector customers and will strengthen eEnergy's competitive position in tendering for large multi-site contracts. The Facility will lower eEnergy's cost of capital, delivering an attractive financial return on the retained project interests.
I would need more information to properly understand this. Surely if the new SPV is owned by EAAS, then it would be consolidated into the group accounts? That seems to conflict with what it says above the project being “off balance sheet”. OR maybe that means it’s off balance sheet funding from the customers’ perspective?
We need more details to understand this properly, so I cannot express any opinion on this specific deal for the moment. I shall await updates hopefully from Canaccord and Equity Development, who have covered EAAS before.
Trading update - this sounds like a profit warning below, but given the post period end disposal of its main business, then I would need to see accounts adjusted for discontinued operations -
Trading in the 6-month period ended 31 December 2023 was impacted by the Group's balance sheet constraints which have now been alleviated as a result of the sale of the Energy Management division. In addition, management have chosen to re-profile solar project revenue and adjust the FY23 results for the Energy Management division in relation to its subsequent disposal. As a result, the Board expects, subject to completion of the audit process, to report Group Revenues for 18-months ended 31 December 2023 of £46 million with Adjusted EBITDA of £5.1 million - £5.3 million.
All the debt has now been repaid from disposal proceeds, as expected.
Webinar - this could be useful in helping to explain things a bit better. Also with this type of share, working out if management are capable or not is vital, so I like to see them present - it doesn’t have to be polished (too polished can be a red flag!) - but for small caps I want to see entrepreneurs from any background, who can explain the business properly, and are on top of all the detail, rattling off facts & figures, and answering questions directly & honestly -
Harvey Sinclair, CEO, and Crispin Goldsmith, CFO, will be hosting an online presentation for investors on the 7th March 2024, to provide an investor update on the Group following the sale of the Energy Management division. Presentations will be held via the Investor Meet Company platform at 11:00, and the Equity Development platform at 15:00. Both presentations are open to all existing and potential shareholders.
Paul’s opinion - I don’t have anywhere near enough information to make a properly informed view on this. However, the positives are that it has comprehensively fixed its balance sheet, eliminating debt. Also it has sold the part of the business I really disliked, the energy consultancy bit with a horrible extended receivables book. Similar companies have gone bust in the past and have opaque accounts. So EAAS now looks completely transformed, with debt eliminated, and an interesting project with Nat West (which could presumably be scaled up a lot if it works well, given their financial size?
At £32m market cap, I reckon EAAS could be an interesting punt, so I’ll go up to AMBER/GREEN, but please bear in mind that’s not a detailed analysis, or a conviction view, more an inkling that there could be something interesting here, that needs a lot more work to confirm. I look forward to reading reader comments on EAAS.
Note the founder CEO of Luceco (LON:LUCE) has joined the Board as a NED, which I like a lot - he must think there's something interesting here, and LUCE bought 35m EAAS shares at 5p late last year in a new issue - details here.
A nice trend emerging in the last year -
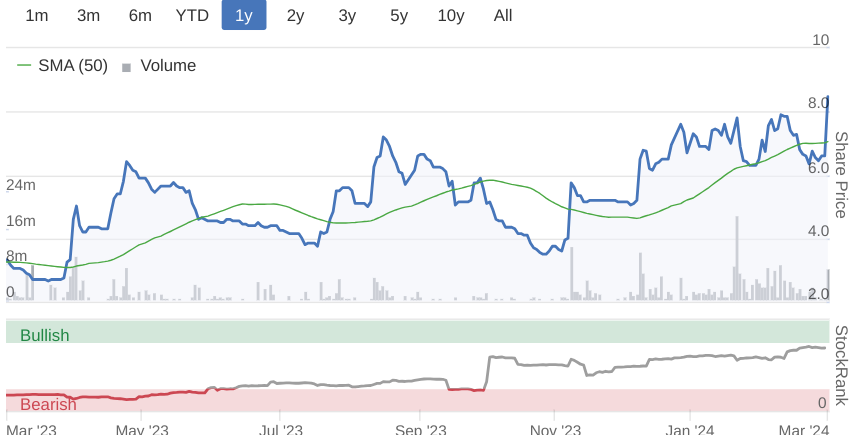
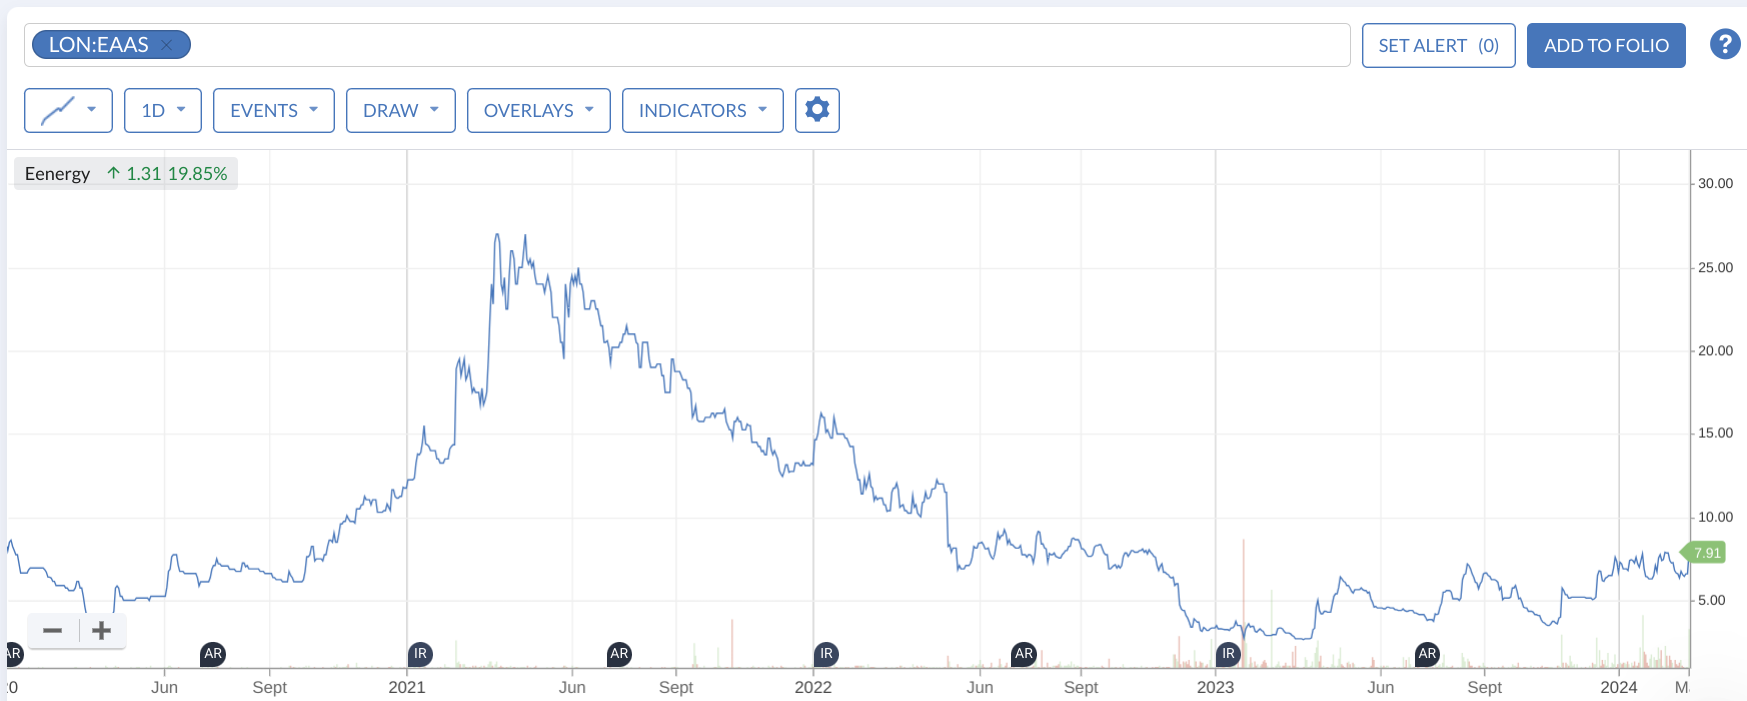
Zoom out on the chart, and it's not so good. Note that EAAS reversed into a cash shell previously called Alexander Mining, so the chart prior to Jan 2020 is nothing to do with EAAS - I've rejigged the chart below so it's a custom range from EAAS's first day of dealings on 9/1/2020 -
FD Technologies (LON:FDP)
Down 28% to 955p (£268m) - Trading Update & Structure Review - Paul - RED
We’ve only looked at this company once when I reviewed it here on 24/10/2023, since Graham’s last review in 2018. I was distinctly underwhelmed, on 24/10/2023 when it issued a profit warning with H1 results, and I noted its weak balance sheet, customer caution, and negative cashflow.
Slower than expected growth at its KX business seems to be the main problem reported today, although confusingly it also says -
We anticipate that Group revenue will be slightly below consensus at not less than £247m, and adjusted EBITDA will be in line with consensus at not less than £22.5m*
Although that excludes MRP, which it has decided to merge with something else, and make it an associate in future.
KX isn’t growing as fast as expected.
Management has decided to separate its 3 businesses in an attempt to create shareholder value.
Paul’s opinion - I’ve just been looking at the last H1 results again, and FY 2/2023 FY numbers, and I don’t think this group makes any real world profit at all! It’s quoting fantasy EBITDA numbers, but check out the cashflow statement to see that nearly all the supposed cash generation is spent on capitalised R&D costs.
So I’ll leave this share to tech investors, who often value things completely differently to value investors! And we are in a tech boom of course, thanks to excitement over AI.
For me, on fundamentals, this looks a low quality business operating around cashflow breakeven.
Management seem to be flailing around trying to figure out how to create shareholder value. I’d say the £268m market cap is already very generous, and splitting up the group might make people realise more readily that it’s a collection of low quality companies that don’t make any money at the moment. That could improve in future of course, I’m only looking at things as of today, not trying to imagine what the future holds.
This is a great example of how EBITDA can present a wildly distorted positive picture for software companies that capitalise a lot of their payroll. Hence valuing shares on a multiple of EBITDA in this sector can result in absurd over-valuations.
I could be wrong of course, but that’s just my reading of the figures.
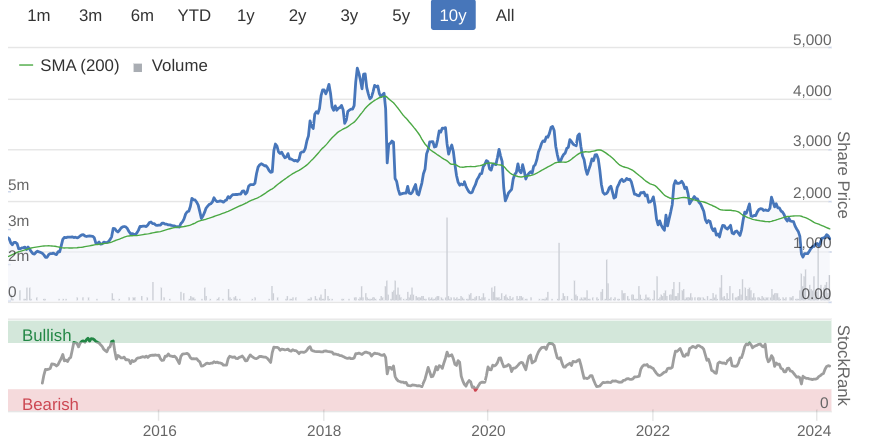
FDP shares peaked in June 2018, and have been in a declining trend ever since, losing over ¾ of their peak value - so I’m dropping my view of this to RED, now it has another disappointment under its belt -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

105 comments
Eenergy (LON:EAAS) - We hosted an Investor Presentation with eEnergy. Harvey Sinclair (Chief Executive Officer) and Crispin Goldsmith (Chief Financial Officer) provided viewers with an update following the disposal of the Energy Management division. The team discussed their simplified business model, the strengthened balance sheet, and details of the new £40m facility with NatWest to provide firepower to enhance growth and increase their recurring income stream. Management also answered a range of questions from the viewing audience. Full video is available below:
?si=tX57t9SZCVuTLm44Eenergy (LON:EAAS) "New £40m facility to drive growth in Energy Services" (new research report accessible here: https://www.equitydevelopment....)
eEnergy has announced (1st March) a new £40m project funding facility, which will support the Group’s public sector customers with their energy transition projects over coming years. It is an innovative arrangement, which will see eEnergy retain an interest in the economics of each completed project, enhancing margins and driving growth in Energy Services revenue.
A brief year-end trading update indicated that trading in the 6-months to Dec ‘23 was impacted by balance sheet constraints (prior to the c.£30m disposal of the Energy Management division). This had already been signalled in January and we update our forecasts accordingly.
The disposal of Energy Management leaves the Group in a strong net cash position and wholly focused on its high growth Energy Services business. Our confidence in growth prospects is strengthened by the new project funding facility. We therefore reiterate our Fair Value/ Share estimate of 13p, before factoring in potential contingent consideration from the Energy Management disposal, which could be material (£8m to £10m on management estimates).
Well done Paul for getting this weeks podcast out despite the technical challenges - just listening to the 2nd version of the 2nd part
Btw I'm standing outside my local Tortilla and it's busy, was yesterday as well
Agree Trustpilot (LON:TRST) aka Trustpaylot is useless. Muddy Waters should take a look!!
I recognise the negative opinions of Trustpilot’s product/business model here.But if more people clearly like the product than not and the business clearly isn’t a fraud or involved in accounting regularities.There’s nothing to see here for short sellers, unless growth and the figures start deteriorating imo.
Carlson Block made his name shorting Chinese frauds and sees uncovering frauds/financial irregularities as his mission (from interviews I’ve heard with him).
Vertu Motors (LON:VTU) Much needed uptick today, breaking through 50dma, presumably due to change of advisor to Stifel ? Notably active in merger/acquisitions, as mentioned by Yiannos this morning.
Avation (LON:AVAP)
A few thoughts:
The company would then switch their expensive unsecured debt to less expensive secured debt.
The key fact for me here is that 15% figure.
However, if there was a 15% drop from a once-in-a-century global pandemic, then I believe the chances of 20% drop in the next few years is minimal.
If we then factor in 95% of the current value of planes (for prudence), the finance lease receivables, unrestricted cash balances and the total debt repayable, then the company is worth significantly more than the current market cap implies.
I don't have a very large holding as I'm fully invested already, but based on the numbers alone, there seems to be a lot of upside.
Sadly, I don't think a lot of this will be realised until the 9% unsecured debt is paid off in 2026.
Having said that I think it's worth holding in case someone comes along and tries to the company on the cheap in the meantime.
A
Avation (LON:AVAP) thanks for the analysis abtan, very helpful. The share price has recovered today too.
Just a hat tip wolf your volume ramble a month or so back highlighted ME International (LON:MEGP) I topped up off the back of it and think i'm up about 25-30% off the back of it, so enjoy the whiskey.
Nice one Phoenix, glad it was some help.
Avation (LON:AVAP)
Paul I was responding to the 8 comments today on the SCVR.
All I can add really is that I concluded it was a share that was so unloved that I gave up. Not much more I can say.
I saw a link by Paul Hill earlier in the week to an interview with Paul Scott, but I can't find it anywhere now. Does anyone have the link please?
goto YouTube - search Vox Markets and its in there!
Thank you Gimmers - it most certainly is!
Paul Hill interviews Paul Scott
The core of the Eenergy (LON:EAAS) business model is that it provides financing to enable customers (e.g. businesses, local authorities etc) to acquire green energy assets (e.g. EV chargers, solar panels etc.), thereby avoiding the need to either pay for the assets upfront or to take on debt.
This is more important than thinking about it as a business that simply sells green energy solutions.
So, a key question for me is how much revenue and profit the recent disposal proceeds and the new £40m Natwest financing facility will generate, both this year and in the future.
The natural follow up question is, what funding is available once current funding facilities are fully utilised: from where and at what cost? This will determine future revenue growth and profits.
I think it’s also important to understand who takes the credit risk. It looks to me like Eenergy (LON:EAAS) takes the credit risk to enable the debt to remain off balance sheet for clients. So how does Eenergy (LON:EAAS) manage that credit risk both by client, by sector etc and will it seek insurance to reduce that risk in the same way that banks and other financing institutions do?
I think this perspective may help to explain why institutions have not been excited by the value of the disposal, despite its size relative to market cap.
Eenergy (LON:EAAS) - Save the Date! As touched on by Paul above, we're pleased to host an online Investor Presentation next week, on Thursday 7th March at 3.00pm, with eEnergy (AIM: EAAS), the net zero energy services provider. The registration link is here: https://www.equitydevelopment....
Harvey Sinclair (Chief Executive Officer) and Crispin Goldsmith (Chief Financial Officer) will provide an investor update following the disposal of the Energy Management division. Management will answer questions submitted by viewers. The webinar is open to all existing and potential shareholders, and registration is free. You can sign up to register at the below link.
Avation (LON:AVAP)
I have traded the share twice in December 2022 and July 2023 and both times it hit my Stop Loss so I rather lost patience. I also decided there were too many better oportunities.
portugull - can you tell us something interesting about Avation (LON:AVAP) perhaps?
ITV (LON:ITV) Buy back will help but must admit apart from the divi Ive never understood the investment appeal here with a horrible long term chart and falling EPS. Tight spread so OK for trading but has the look of a declining value trap.
A very good RNS reach announcement (proper use of it imo) on 4Basebio (LON:4BB) - this type of validation is important for scaling the business and valuing the IPR.
But for heavens sake the spread is almost 10%. I know it is illiquid but come on !!!!!
Some good sized trades in Focusrite (LON:TUNE) today, which I have just completed building into a position. If it's an insti buyer they obviously haven't heard about the BnB curse.
I've been debating whether to take a position in Focusrite (LON:TUNE) after the recent falls but was put off by their Jan AGM update - trading inline but with a dreaded H2 weighting. Difficult to calculate how much stock their customers are sitting on after the Covid induced spree for home audio related products (Martin audio the exception).
Good luck with your purchase
I've been debating whether to take a position in Focusrite (LON:TUNE) after the recent falls but was put off by their Jan AGM update - trading inline but with a dreaded H2 weighting.
Very fair point. Although it's worth noting that the SP has fallen by nearly 20% since that announcement. The chart appears to show strong support at current levels. But the market is unlikely to take those mitigating factors into consideration if trading worsens. And if it breaks that support there's a long way to go. Yikes :-|
Avation (LON:AVAP) ( I hold) down today. Any holders here? Net asset value per share at £2.56 yet price now is £103 to sell. But a share can remain undervalued for a very long time. Losing patience.
I also hold Avation (LON:AVAP) . I find it bizarre - no other aircraft leasing company trades on such a wide discount to TNAV though of course they don’t trade on the UK market which appears utterly useless at valuing these types of businesses.
Avation (LON:AVAP) has the benefit that the planes it leases are in very high demand from a future perspective and current lease renewal rates are well in excess of current rates so as leases roll off there should be a very strong uptick in revenue against a declining interest curve.
Net debt down another $30m in the half year and should come down a not dissimilar amount for the full year. TNAV was adjusted 5% down but frankly that’s all a bit arbitrary. There is hidden value in the balance sheet too I believe as the $130m maintenance reserve (basically airlines pay into that to cover plane servicing) should far exceed the actual maintenance amount, so that reserve should get released over time.
Starting to grow again - new planes on order.
The fly in the ointment holding back the share price may be the refinancing of the bonds, but I suspect when that’s done it will make little difference. Gut feeling is that this is unloved and has no UK buyers (seems to be all small retail holders bailing) so is just moribund. Don’t know what drives this back to trade at NAV (which historically is where these businesses trade) but I am not keen on selling out at 40p in the £ either frankly.
Avation (LON:AVAP) has a higher cost of capital than larger aircraft leasing rivals which is all important in this business. The planes simply aren't as profitable in their hands as they would be for say AerCap Holdings NV (NYQ:AER) because their debt is more expensive. It's a bad business model to have a sub scale aircraft leasing company , but all that being said the planes are still worth more to somebody else, so ripe for a takeover
Avation (LON:AVAP)
is there a catch here ? that seems very chunky discount - is there any hint of reason as to whyb the market thinks its not worth the sum of its assets?
Perhaps gearing is the issue here ?
Ahhh on quick glance i suspect that is the case - so if excess asset value if £100 mill - they have pleanes vlaued at over £1 billion. so 10% writedown in value of fleet would wipe out the discount to nav here.
So main question is is how conservative is the valuation of the planes on the balance sheet ?
i know the specific types of planes airlines like can fluctuate over time so you dont wnat to be holding the wrong type if no one wants to lease or buy them.
As you have rightly pointed out they have been in the game a long time so its clear that they should know their stuff. all i know is that i wouldnt have any details if there could be possible nasties that would be hard to forsee coming - eg rogue country simply stealing the planes they have on lease or airline bankruptcy at wrong time with planes that wouldnt be highly wanted by others.
One would expect if they have no specific concerns they should be in reasonably sweet spot right now with covid firmly in the rear view mirror and travel pretty much back at normal levels mostly. Not sure if their customers will be as solvent as they would have been pre covid though ?
But second hand plane values (particularly the type Avation (LON:AVAP) )have are going up and not down.
The maintenance reserve is hiding additional NAV in the b/s
Plane values in NAV are very conservatively set
Debt is being reduced at $50-60m p/a
The rest of the industry operates in the same way yet generally trades at 1* NAV (and arguably has less favourable aircraft demographic)
Avation (LON:AVAP) don’t lease to rogue countries. And mainly national flag carriers
Interesting on the management call Avation (LON:AVAP) addressed my question on discount to NAV and what they are doing about it. They made the same point I made earlier which is they have the widest discount to NAV of any listed aircraft lessor.
Answer along the lines of share buy backs, dividend reinstatement in future - won’t be investing in investor roadshows as see little value! That surprised me as they historically have - tells you the moribund state of the market. They no longer think there is a sufficient audience to bother talking to outside of IMC type meetings.
As an aside I agree with Katie below about the UK market - a listed market is supposed to be a facility to raise capital but right now it is just fundamentally broken. I really hope the government get their act together and start forcing ISAs and Pension funds to hold a certain %age of assets in the UK listed markets. That will do 2 things - (1) increase existing share valuations and (2) encourage more capital raises supported by institutions. As the pension funds are demanding over quality then over time that will improve the level of companies listing.
Avation (LON:AVAP)
with the stark discount on NTAV and high debt and interets rates being higher than average - it would seem strange to me that they would plan to buy back shares now. Note i am a fan of share buybacks in general - but in some respects with the debt as it it that seems like they are doubling down with buybacks rather than derisking as they would be by reducing debt.
Not saying it doesnt make sense buying back shares - it probably does if the "debt isnt an issue anyway". there was one coment earlier their cost of borrowing is higher than similar companies so if nowt else paying down debt rather than buybacks would presumably help in that regard.
It does certainly seem to be the case there are no obvious nasties in plain view here - so hopefully for holders the value will out.
Hi David,
I will certainly be selling everything listed in the UK and closing my ISA if they force me to invest a certain percentage in the UK market.
Last month I did share it here that the iShares Bitcoin Trust (NMQ:IBIT) represented an excellent opportunity at $23 but I was not allowed to buy it in my ISA but I could buy if I wanted the likes of Chill Brands (LON:CHLL) and Supply@Me Capital (LON:SYME)! Had to buy it in my shares account but I guess the tax man is going to be very happy as I sold for a 50% gain. Same with Banco Bbva Argentina SA (NYQ:BBAR) I was not allowed as it is trading in ADR’s.
If they introduce such a law it will be the complete downfall of UK shares and an exit for UK fund managers at the expense of UK taxpayers!
Hi Yiannos,
I don’t really agree with this. I’m not advocating that they don’t allow foreign shares in ISAs or pensions just that you couldn’t have a full overseas allocation and still get full tax benefits. We have to push more money into the UK markets as this has a massive long term effect on capital investment and subsequent growth. Doing that through making it tax beneficial is the most efficient way. For example they could change the ISA allowance to be £15k at today’s rules and £5k in a UK only ISA where you get back 20% income tax on top. There are lots of ways to do it but we have to stop the exodus of money out of UK capital markets.
This year alone according to Bloomberg UK investors have exited £3bn from our capital markets. Fundamentally unsustainable if we want to have a capital market of any note and given the level of GDP the city generates across the entire UK the implications are stark.
In my opinion it’s game over. In February only the options market in the US recorded an average of 48.7M! contracts per day.
Everyone is celebrating about all these acquisitions Wincanton (LON:WIN) etc but the truth is simple : the market is not efficient.
From the start of the year the FTSE100 is still down and the DAX is about 8% up. Same in the US. That’s only in two months and the reason is the quality and growth of the companies listed in these markets. The LSE needs urgently quality companies to be listed and not Yiannos or David’s ISA money. That will only drive the prices up for a couple of months and then they will collapse again on the new earnings cycles that will follow.
Personal opinions based on a similar situation I have experienced 20+ years.
Let’s be honest-we are talking about many different companies every day here -most of them in five years will be forgotten and only a few will survive.
All the best
Well in terms of the small caps if these continue getting taken out then over time the quality will reduce as the good ones will either be bought up or outgrow the index.
On the other hand even the US is not really having a lot of new listings (so I hear) . The Private Equity funds are sitting on their holdings but will need to sell some on before too long according to their own business plans.
Large cap index you make some good points but they do say value will out......
Policing a % of the ISA to be UK stocks would be absurdly complicated, especially as prices varied. But perhaps introduction of a separate BISA (British ISA) of 10k per year might be a good way of encouraging UK based investment perhaps? I'll chat to Jezza....
Changing ISA rules going forwards so 10K in international and 10k in UK only would be one approach. No doubt if that takes place the ISA will be renamed.....
Yes I hold Avation (LON:AVAP) and have done for many years. Frustrated at the moment over the SP and the lack of communication from Jeff. I missed the IMC meeting today . When i looked at 9am today it was down 9%. Now up 1%. Was Jeff throwing money to holders
Bank of Georgia (LON:BGEO) Georgia Capital (LON:CGEO)
Big move by Bank of Georgia today.
Georgia Capital's stake in the bank has risen over £20m today but its share price is flat.
The unlisted part of Georgia Capital (LON:CGEO) is at a heavy discount when you take out the £460m represented by its Bank of Georgia (LON:BGEO) stake.
Hold both so I'm biased, but it is quite a valuation anomoly even allowing for their trading location.
A
Maybe the recent director sale in Georgia Capital is holding it back:
http://newsfile.refinitiv.com/...
Nah - it’s just a fairly typical lag in Georgia Capital (LON:CGEO) - it doesn’t trade in line with movements in Bank of Georgia (LON:BGEO) despite the high correlation to NAV. Has a surprisingly low beta correlation.
Eagle Eye Solutions (LON:EYE) Capital Markets Day given to analysts last week video & podcast.
They outline their ambition to get to a £100m revenue & 25% EBITDA business. No time in which to achieve this was given but their excitement was palpable. Already working globally they will focus on expansion in the US (23: 49% rev it is the largest loyalty and promotions market globally); UK (23: 37% revenue), EMEA (23: 3% rev) and APAC (23: 10% revenue, APAC is the fastest growing loyal market globally).
They have an enviable client list, for example in the UK Pret, Asda and Pizza Express. US: Loblaws, Staples. APAC: IKEA. EMEA: Carrefour, Auchan, E.Leclerc. They have low customer churn and each £1 revenue spent with them incrementally grows to £3 over time, so a model that drives ARR growth.
Untied Nots has integrated well and is integral to the newly created EagleAI. This could be the engine of their future organic growth. Ongoing they will get to the £100m revenue by organic growth and more acquisitions.
I like Eagle Eye Solutions (LON:EYE) and it is one of my larger holdings.
The company came across very confidently in the capital Markets presentation and what was new apart from the (undated) £100m and £2% adj EBITDA margin targets was: (1) the depth of the management bench presenting, with around 5 non-board members presenting as well as founder, CEO, CFO and new Chair and (2) the re-emphasis on the culture of the company and staff satisfaction. There are 3 client testamonials as well focusing on the “teamwork” ethos of Eagle Eye.
The one fly in the ointment for me from the investor day was the focus on M&A. While they stated their confidence in continued organic revenue growth of 20%+ (and hence confidence in continuing to meet the rule of the 40), I always worry that a company with lots of organic opportunities would see M&A as a distraction.
Sometimes its the little things. On a previous presentation the boss of Untie Knots introduced himself as the one that came free (without bitterness) and I thought that comment suggested it would go well.
ITV (LON:ITV)
jonno I think like you the value in the Company is the Studios without any doubt. In the last 2 years since the Dividend was restored I have received £5.5k giving me a return of 7%.
The key with ITV is to buy the dips and my average cost is 65.7p. One day they will be bought out but in the meantime I am content to be patient.
I've been a holder within The Boon Fund in the past and this is my investment case for ITV (LON:ITV) too.
That their studios, sold, are worth quite a fair chunk of the current market cap.
Then if you look at their broadcast channel, it is protected by regulation (until that changes), with a cartel between ITV and Channel 4 as the only ad supported channels. You might add in BBC (no ads) as competition for eyeballs. That still leaves 3 parties only.
Channel 4 is being starved of investment and likely to be in terminal decline, in terms of programming quality and therefore eyeballs. BBC is also seeing big real-money cuts to funding in the next few years. Both of these leave ITV to get a bigger share of free broadcast TV eyeballs. Albeit, that has been a declining market.
However... with Netflix and other streaming services pushing prices up to generate more profitability, there will be a tipping point where Free with Ads becomes more attractive.
ITV still not cheap enough for me to consider buying. But now its a much simpler business without BritBox, it might be coming into M&A play. Someone to buy out ITV Studios, and a bigger broadcasting company to gobble up ITV channels.
Good discussion right now on You Tube - Vox Markets with PMH and Roland Head.
ITV (LON:ITV) sells its 50% share in Britbox to BBC for £255 million in cash SP up 13%. I hold.
Obviously not a small cap but a big holding for me at 10% of my portfolio.
Yep, I am REALLY heavy into ITV with 35% of my portfolio, having topped up on the drop over the last few days. I am not usually this lucky with investments !
9 percent dividend, and plenty of technical support around 55p, definately worth a trade at those levels.
ITV (LON:ITV)
Has sold its 50% stake in Britbox International to BBC Studios for which it will receive £255m. It intends to use the money to continue its investment in ITVX and ITV Studios.
ITV has been an awful investment over the last 4 or 5 years due to investors fixation with its dependence on advertising revenue, especially analogue advertising. There is a lot of value, particularly ITV Studios but when and how will it be recognised. I have held the share on and off because of the inherent value but have ended up selling in frustration, albeit the dividend income has provided some solace.
ITV
The only hope for ITV is a take over offer by Netflix or Disney because of its content.
I would welcome thoughts on the update from Eenergy (LON:EAAS)
If you enjoy a big picture view of the investment world, have a read of Bruce Stout’s final commentary in the annual report of Murray International Trust (LON:MYI) today . He’s always been exceptional value as a commentator. I hold. I’ll miss him.
Murray International Trust (LON:MYI)
I noted :
Overall UK exposure declined to its lowest level in over four decades based on adjudged better growth and income opportunities elsewhere in the world.
Summary of Investment Changes During the Year
Valuation
Appreciation/
Valuation
31 December 2022
(depreciation)
Transactions
31 December 2023
£'000
%
£'000
£'000
£'000
%
Equities
UK
68,771
3.9
(14,378)
2,212
56,605
3.2
Europe ex UK
448,335
25.1
67,350
(19,266)
496,419
27.8
North America
468,484
26.2
8,975
(6,853)
470,606
26.3
Asia Pacific ex Japan
444,303
24.9
(8,732)
(9,145)
426,426
23.8
Latin America
218,800
12.3
17,598
(12,307)
224,091
12.5
Africa & Middle East
12,439
0.7
(1,803)
(10,636)
-
-
1,661,132
93.1
69,010
(55,995)
1,674,147
93.6
Portmeirion (LON:PMP) showing signs of life yesterday. Fun fact for a quiet Friday…. The annual board fees are an astonishing ~£2m, worth £20m in perpetuity at 10% rate. Market cap of £30m. Someone in the same sector could buy it for 66% premium at £50m, get rid of the board (who I doubt anyone would notice were missing on a day-to-day basis), and basically have paid no premium at all. Bit simplistic, ignoring tax and no doubt other stuff. Or put another way, the value of the business is £50m but shareholders are accepting to give 40%/£20m of that to the board to manage it for them, pretty inefficient set up.
For me, this puts it in the ripe for takeover camp. I tried to screen for this type of set up but I had to start doing it manually going to the annual report for the board fees figure which became a pain unless someone knows a database that captures the data?
Morning M48,
That's a really good point. With small caps, the costs of listing and an expensive Board can often be highly material relative to profit/cashflow. So getting rid of these costs and going back to being a lean private company, could well be part of the calculations in determining a takeover.
It's was noteworthy that in GXO's bid for Wincanton (LON:WIN) it bases the bid on stripping out a huge amount of costs, nearly £50m pa from memory. I would be fascinated to see a breakdown of that number, as GXO is basically saying it can double WIN's profits once they take it over, hence the wilingness to pay a generous premium at 605p/share. Plus of course its own equity is much higher rated, since it's US listed.
At this rate, the UK is going to be owned by the Americans and Chinese! Still, for our purposes here, each takeover bid is yet more evidence that the UK market is too cheap hence rich pickings for investors are on the cards from more takeover bids, and eventually a re-rating of our market as demand/supply rebalance. I find it all tremendously exciting, and cannot understand why some investors are so gloomy when we have such a golden setup on our hands. The market is offering us £1 notes for 70p, which is incredibly exciting I think!
Regards, Paul.
Hi Paul
Maybe more akin to £1 IOUs for 70p - which may / may not be honoured!
I agree re the undervaluation - but it's pretty grim sitting watching one's portfolio becoming steadily more undervalued.......!
Thanks for the excellent SCVRs that you & Graham produce.
Andy
I'll second this because if the Government doesn't wake up and do something loyal for the UK I can see my savings going down the drain, in fact I've been seeing this for at least the past year.
I'll second this because if the Government doesn't wake up and do something loyal for the UK I can see my savings going down the drain
The real question is why are you staying loyal to the UK - if that is indeed where all your investments are based – when there are much stronger companies to own in safe jurisdictions such as Europe and USA.
Think I’m more optimistic that there could be some near term tailwinds in the UK small cap space, but selectively
1) I’d be amazed after the hype if the Budget doesn’t include some measures like the Brit ISA and off the back of that I see fund managers (e.g. JP Morgan after their perhaps fortuitously timed merger of their smaller and mid cap investment trusts) ramping up the marketing.
2) Takeovers of things like Wincanton (LON:WIN) means there’s cash to recycle, I think I’m right Aberforth have about 16% of it across their funds/trusts, that money has to go somewhere.
3) sentiment from 1) and 2) puts an end to fund redemptions. Even a small amount of marginal buying could shift a few needles.
But it will be selective, there’s too much overhyped, overpromoted, overvalued, horrible stuff meaning I don’t think in aggregate the small cap space is undervalued at all.
"But it will be selective, there’s too much overhyped, overpromoted, overvalued, horrible stuff meaning I don’t think in aggregate the small cap space is undervalued at all."
One issue is that of AIM itself. In my view, instead of attracting small quality companies to grow in a lightly regulated low cost environment it has now got a growing base of poor quality companies with dubious management.
And when the dubious management cross over the line to fraud, they get away with it. Or, it takes years for anything to happen. Justice delayed is justice denied.
But, in fact, it takes years for anything to happen in the UK, which is a major problem IMO
Think I’m more optimistic that there could be some near term tailwinds in the UK small cap space
I'm optimistic - or I wouldn't have 20% of my assets in UK markets. But diversification is just plain common sense - and that doesn't just mean owning dollar earners listed here.
Hi BnB, can I ask ...what has your performance been like on your US stocks compared to S&P Index over the years?
Im the opposite way round - 20% in US stocks- but im lazy so just use a tracker.
Hi BnB, can I ask ...what has your performance been like on your US stocks compared to S&P Index over the years?
I'm tempted to reply that I follow the Nasdaq on down days and the S&P on up days!! That's certainly evident in that I have underperformed both over the last 5 years. But I am somewhere between the two since the market bottomed in Oct 22 with S&P up 40%, me 50%, Nasdaq 60%.
Why the upturn in recent comparative performance? In spring '22 I was too heavily in sectors that got smashed when interest rates soared - unprofitable tech, genomics etc. and that wipe-out has skewed my long-term performance. I rebalanced* into established positions in cash-generating tech (the usual large software and cybersecurity names) more tech industrial compounders like Eaton and Trane Tech, and in particular into SEMICONDUCTORS. I cannot stress how long-term bullish I am on that theme. It's a horribly cyclical area to invest in but it's helped keep me up with the AI wave without even owning Nvidia until this January, after it had already tripled. I still think it's undervalued, by the way. I own very few semiconductor designers but a lot of capital equipment makers like ASML and KLAC and many obscure ones across the niches of semi production. I am underweight Mag7 because my fund is broadly equal-weighted across about 100 US names and would otherwise have outperformed both indices - I'm too pigheaded, which is called "disciplined" when it goes well.
*Ironically I would probably have performed better to have ridden those unprofitable tech names back up in '23 but I was happy to take the hit to have a better constructed, less volatile portfolio. Every day is a school day!
Thanks BnB, thats a good result since the market bottomed. Well done, anyone would be happy with that!
1 word per line please
O
K
!
I did a backtest earlier this week of 60% of funds in S&P 500 and 40% in ten year US treasury even allowing for 2022 you would still have made tad under 40% over 4 years ,which sometimes does make me think why do i bother with putting my own portfolio together and maybe the 15-20 hours per week I spend on stock research would be better spent elsewhere.
Thanks Paul, yes it was a commentator on Twitter saying the Wincanton (LON:WIN) premium was ‘huge’ that sparked me. Once someone has decided they want to buy a business/asset, it’s not difficult to justify a wide range of numbers.
It is incredible that the FTSE100 was 7,000 at the end of 2000, 23 years ago. Eventually it will have to re-rate.
Epitychia - not necessarily with the outflows to the USA and elsewhere - but let’s hope so and i might repatriate some of my modest funds!
FTSE100 looks better if you look at total return
Can you post that chart every week !
I find it all tremendously exciting, and cannot understand why some investors are so gloomy when we have such a golden setup on our hands. The market is offering us £1 notes for 70p, which is incredibly exciting I think!
Hi Paul, I completely agree with you, except I think the market is offering us £1 notes for 50p (ie - 100% gain over two years from start of recovery)
During the last 70 years there have only been 14 bear markets in small caps, and only 3 of those lasted over two years. The following recoveries were all very strong, and the competent Investment Trusts covering small caps made 100% gains over the following two recovery years.
So you are right in that we all need to try and be less gloomy and more excited by this outstanding opportunity.
I am now positioned at 100% fully invested, in 100% UK smaller companies. I hope that time will prove that I was bold and brave rather than mad.
Best regards Neville
Vertu Motors (LON:VTU)
I do not hold.
Change of advisor to Stifel!
Hi Yiannos, excuse my ignorance but what could be the significance of this? Thanks
They are usually involved in mergers/acquisitions.
Advising and covering companies of larger market cap. Not usually involved in small caps.
Interesting, thanks!
MrC's Smallcap Sweep. Set up to flail
◄SND,LVCG,NFX,FDP,EAAS,ORCH,HUD,SDRY,ARTL,RQIH,4BB
◄Sondrel (SND)► cash-strapped co's talks "at a very advanced stage" re £0.9m secured 15% convertible, needed for Feb payroll. Would immediately convert at 10p if co raises c.£6m+. [SP=9.5 Cap=8m]
◄Live Company (LVCG)► £200k loan from chmn by converts (strike 3p). Negotiations with two separate strategic investors. Remains suspended. [SP=2.08 Cap=5m]
◄Nuformix (NFX)► £150k placing at 0.2p, a 23% discount, to further advance its NXP002 programme = keep the lights on. Btter buy some 2 watt bulbs. [SP=0.26 Cap=2m]
◄FD Technologies (FDP)► FY-Feb trading: rev slightly below consensus at £247m+, adj EBITDA £22.5m+, in line. KX subs annual contract value only £14m. Blames lower conversion ratio and longer sales cycles plus delayed decision making on a small number of larger contracts. First Derivative rev down 7%.. Also structure review: first step is all-share merger of its MRP biz with CONTENTgine, a provider of B2B technology buyer insights and lead generation. "Board will take a measured approach to the separation of KX and First Derivative." [SP=1324 Cap=372m]
◄eEnergy (EAAS)► Guides FY-Dec (18 months) rev £46m and adj EBITDA £5.1-5.3m. Co has "re-profiled solar project revenue and adjusted the FY23 results for the Energy Management division in relation to its subsequent disposal" Westminster Bank to provide up to £40m of project funding. [SP=6.64 Cap=26m]
◄Orchard Funding (ORCH)► makes provision of c. £500k for fraudulent credit agreements. Co making "a thorough review of its wider lending book and introducer network to satisfy itself that no fraud risk exists elsewhere in its current loan book". [SP=24.84 Cap=5m]
◄Huddled (HUD)► gets $1.325m in settlement of the loan note from Immotion, the purchaser of LBE. RNS wrongly titled 'Receipt of Loan Note'. [SP=2.55 Cap=8m]. I hold.
◄Superdry (SDRY)► PUSU deadline extended to 29 Mar. [SP=39.4 Cap=39m]
◄Alpha Real Trust (ARTL)► NAV at end Dec 213.2p, down 1.1p over 3 months. [SP=140 Cap=83m]
◄R&Q Insurance (RQIH)► re press speculation: co expects closing of Accredited sale to occur in Q2 2024. Co " continues to evaluate any and all options so as to realise value from its Legacy Insurance business". [SP=5.65 Cap=21m]
◄4basebio (4BB)► wins tender to deliver research and GMP-grade synthetic DNA. No £££. [SP=815 Cap=104m]
Article about how "the UK stock market isn't working", referring to undervalued small caps being taking over at large premiums. Not much in the way of solutions or even reasons mentioned though.
https://www.theguardian.com/bu...
Don't think I would look to the Guardian for solutions to capitalism 's problems!
nor anyone in the city, it seems
I thought it was actually a good article - makes some good points
I feel Katie Potts has got it absolutely right:
“There is no doubt that the UK public market is in a more fragile state than during any previous downturn in living memory. The question is whether this is cyclical or whether the damage is more structural. The UK public market is currently a fairly difficult environment for entrepreneurs to raise capital and I am saddened by how much management teams have been diluted by fund raisings at distressed levels. I believe that value in our portfolio will be realised through takeovers but that the costs incurred by listed companies in the UK, with the recent added burden of ESG and auditing requirements, has become too high to attract new companies. Similarly, the costs for managing small investments have increased considerably, with additional ESG and regulatory costs. Unfortunately, active investment management does not scale, and it is conspicuous that larger players have withdrawn and funds have shrunk. There are now too few players in the UK to have an efficient market, and too few co-investors. It is a pity because public markets have provided long-term risk capital for the benefit of the wider economy, but the skillset is disappearing rapidly. It seems the UK will inevitably shrink as a percentage of the Company’s assets.”
as long as it is the undervalued stocks which I hold, being taken out for large premiums, I would be perfectly content!
He does have a point though:
"It’s hard to disagree. A pitch for London is not compelling if it involves paying your advisers a small fortune to get listed and then being ignored for years until a foreign predator turns up."
Thank you for the link. Interesting short read, if nothing really new -
liquidity problem in UK markets,
It was interesting to listen to Vin Murria at this weeks Mello, when asked if she could repeat levels of growth seen in her previous companies with Advt.
Confident she and her team will execute but did hint that the market in its current state may not recognise its true value.
The us and eu economies are much bigger than the uks. So their stockmarkets are much bigger than the UKs. So more liquidity. London used to be Europe's financial capital. Not any more. The uk has a record of underinvesting in itself. So less money here less liquidity here lower perceived growth prospects here. Many international companies listed here because it was better - more liquidity etc. That has changed so some of them will change.
My key point is listings follow money and the money is in the eu and usa. Deregulation wont help. Getting institutions to put money in the stock market will - *but who buys fhe gilts they will sell to do that*
Happy to be told i am wrong.
Theres lots of moaning around just now about UK small cap markets, but people have short memories. A couple of years ago Frontier Developments (LON:FDEV) was valued over 50x , boring legal service companies like Knights group (LON:KGH) on 25-30x and fast fashion retailers on 50x. But somehow NVIDIA (NSQ:NVDA) is insane on 32x forecasts. Today Pennon Group is 65x, Trustpilot 113x, Flutter 34x
Seems to me many of the people/funds doing the complaining are the same people who've caused much of the problem. They were falling over themselves to buy over hyped crap like made.com and yet theyre dumping supposedly long term holdings at capitulation prices. Theres countless small caps prices being suppressed and walked down by market makers as funds dump them at basically any price, just have to look at the many daily volume spikes we're seeing. Youve Buffetology talking positively of Quartix Technologies (LON:QTX) then within days dumping large amounts of their holding.
Right now its a large blocked drain, overhangs need clearing but this will take time, stale bulls need replaced by new holders.
Wouldn't surprise me if a short selling firm did a hatchet job on TRST at some point. Very easy to fake reviews and scammers who pay for TRST's services can even get negative real reviews removed.
Hi Michael, have you some evidence of what you suggest I.e. fake reviews and negative reviews being removed, or is it anecdotal?. Can I also ask have you a position in TRST. Thanks
I don't have a position in Trustpilot (LON:TRST) .
But, if you go back a few years, there was a lot of comment, correct or otherwise, around Purplebricks challenging negative reviews and them disappearing.
Trustpilot (LON:TRST) business model is to let people post bad reviews on a company unless they pay them for the right to stage manage their reviews. If you post a negative review a client can challenge it as a fake review and get it removed unless you provide documentary evidence of everything that happened to Trustpilot (LON:TRST) , which very few people will bother with . It's a rotten business model to the core
It has a very nasty business model which competitors such as reviews.io use to their advantage and share scare stories from customers of TrustPilot.
I am sure these reviews are fake aside from the 1-star ones. Of course, it's possible that that an instagram trader who poses in front of flash cars, spends money on advertising, and shares all his trades for for free really does make money in trading and not commissions from his affiliate broker that gives him kickbacks when his followers trade on his 'signals', but you can check the evidence for yourself. https://uk.trustpilot.com/revi...
I have a friend who reported Trinity & Partners to Action Fraud and the FCA. Neither were interested because he hadn't suffered a loss (he didn't fall for the scam). He posted a review on Trustpilot and this was removed at the request of Trinity & Partners.
I don't have a position in TRST - if I talk about a stock I'm long/short of I'll say so!
Yes - at a personal level I never believe a word that comes out of Trustpilot and have now stopped even looking at the reviews. As I understand it the “review” model generally works like this…….most people don’t leave reviews unprompted - so you will find even quite large brands with low trustpilot ratings, but also very few reviews (absolute numbers relative to sales). Why - because only people with something to vent will go online unprompted and put 1*. Sales then ring the company up and say they can get you more reviews and help “manage” the rating up - for a nice fee of course. You refuse and the negative reviews remain. You pay up and suddenly your rating becomes much better because they then actively target your customers for reviews and help you remove the detractors. So basically I have come to the conclusion that low ratings mean the company in question hasn’t paid and high ratings mean they have. Does that give me unbiased and relevant information on a service/product or is it just paid for marketing? Ie as a consumer can I really “trust” the ratings at all? From a personal perspective I have decided I can’t.
So it would not surprise me either if a short selling firm did a hatchet job at some point. I don’t have any position, never have and for my reasoning above never will. Feels to me like a bit of a house of cards although clearly somewhat lucrative (for now at least).
Trustpilot (LON:TRST)
the flip side here is they are clearly a leading brand in this space and they are growing income levels - i dont really have view on this company , but with well established brands with growing income i would expect them to grow into toppy valuations generally rather than regress - as long as its clear they are making real profits or have capacity to do so (made.com pretty much ran out of money despite sales growth being good)
obviously one can have issues with their buisness practices and the accuracy of their scores - imho thats kind of missing the point that their customers are paying to give the impression they are a trusted brand the detail of how truspilot works is probably of little relevance to them - i guess most companies that pay are trying to provide decent customer service and in that regard truspilot wont be screwing them over with too many fake bad reviews if they pay i guess? Cherry on top is that sometimes clear negative feedback if sorted in the right manner thereafter can improve the business overall. So scope to use this as tool to up customer service levels if its a fact that peps like to bitch about what they perceive as being poor service.
So the point here rmillaree is that the business practices significantly heighten the risk of a targeted short attack. In the event that happens you could see a 20/30/40/50% jerk to the downside.
If that short attack damages reputation (and as we’ve seen a number of times mud sticks almost irrespective of validity) it will impact the “Trust” in review that trustpilot conveys. That in turn could easily lead to marketing departments not renewing and a general slide in business.
The trend for “Reviews” also seems to be diminishing - this is purely anecdotal but I’ve noticed that 20 somethings dislike the concept much more than I anticipated. So is this a real long term business or just a relatively short term fad? I can’t tell but the combination of factors puts me off the stock. Do I need to take the risk of a very heavy pullback when there is so much out there offering as much upside.
Trustpilot (LON:TRST)
So the point here rmillaree is that the business practices significantly heighten the risk of a targeted short attack. In the event that happens you could see a 20/30/40/50% jerk to the downside.
I wouldnt disagree with that line of thought - so you could be right. would be slightly surprised to see anyone take on trustpilot but perfectly possible - any company on premium rating could easily lose chunk of its valuation if things go wrong or the mood swings against them..
I agree with rmillaree’s comment that negative reviews properly sorted can be a positive. I hold Trustpilot (LON:TRST) and spent a long time looking at it before buying in. PlanetX was/is very negative on Trustpilot saying that he never bothered with them and had a low rating whereas the current management did engage Trustpilot on a paid basis and now has good reviews. I looked at their site and found that all the negative reviews had been dealt with very carefully and fully responded to. Many of the problems had little to do with PlanetX directly, more the courier services that they had been using. I came away with a very favourable impression of the company, given the effort they had clearly spent on resolving all issues (surely also a good company to start with thanks to PlanetX…).
I spent a long time reading online reviews of Trustpilot, positive and negative. The two main negatives were fake reviews and negative reviews being removed as mentioned in today’s thread. I addressed my concerns to Trustpilot and the Head of Investor Relations replied that they were acutely aware removing negative reviews was not what they wanted to be doing. I expect this to be addressed if it has not already been addressed.
One other factor for my purchase was the appointment of Zillah Byng-Thorne as Chairman. Now Saatchi has a new CEO she will be able to spend more time on Trustpilot. I also rate highly the new CEO Adrian Blair, whom I regard as having high personal integrity. I don’t know the guy, this is just the impression I gained from online presentations!
You’ve obviously done your research so I wish you luck with the investment on Trustpilot (LON:TRST)
Fundamentally for me it comes down to two things
1) I’m not convinced the Review culture will persist - so I don’t really see this as a business I would be paying more than 10* PER for
2) Feels like a prime short attack target so don’t think the risk/reward is there. Marks and Spencer (LON:MKS) for example feels like it has similar upside without the binary downside.
I’m not moralistic about the business practices per se. I don’t like them but that wouldn’t necessarily stop me investing. The other 2 issues would and do.