Small Cap Value Report (Fri 1 Oct 20210) - MEAL, Supply chains/inflation, AO.

Good morning, it's just Paul here with the final SCVR for this week. I was travelling back from Madeira yesterday, so of course my largest position Boohoo (LON:BOO) put out a profit warning. Such is life. Think I'll book weekend flights in future.
Today's report is now finished. Wishing everyone an enjoyable & relaxing weekend, which I think many of us need!
Agenda -
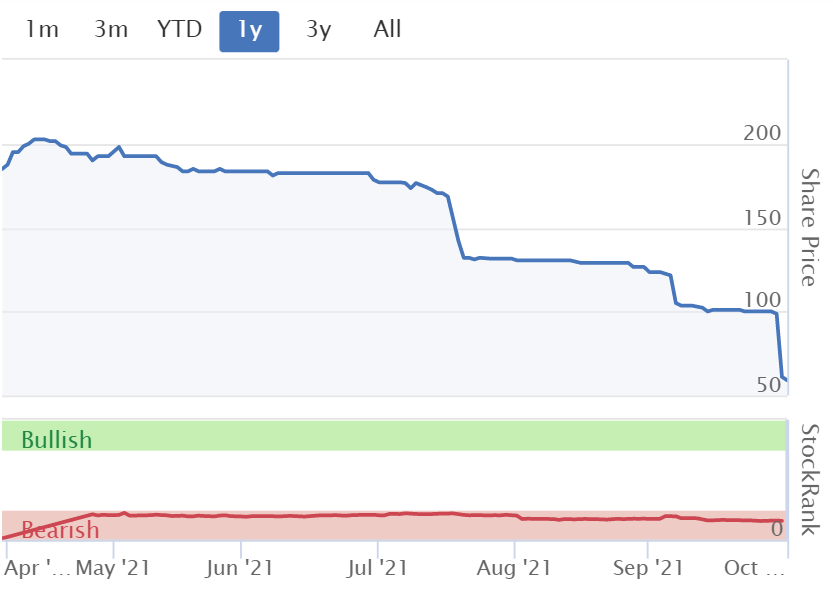
Parsley Box (LON:MEAL) - my take on yesterday's profit warning. Even though the share price has crashed, I see little to no attraction in this share at 60p.
Supply chains/inflation - as it's a quiet news day, I've decided to have a ramble about these very important current topics. I foresee many more profit warnings, bringing some potentially good buying opportunities for the remainder of 2021.
Ao World (LON:AO.) - profit warning. I've never been impressed with this company, which has a poor business model in my view, and in reality generates little bottom line (post tax) profits. Shares have dropped heavily, and are down another 24% today. They still look far too expensive to me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Parsley Box (LON:MEAL)
60p - mkt cap £25m
Profit warning (yesterday)
I was going to write a full section on the profit warning from MEAL, but just spotted that Jack wrote about it yesterday. Reading Jack’s review, it sounds grim. I’ve been sceptical about this recent IPO from day 1, because it looked like an opportunistic, over-priced IPO, based on a one-off good year aided by the pandemic. Or rather, that was my suspicion, and it now looks to have been correct. Also there’s been a question mark over the effectiveness of the heavy marketing spend.
MEAL is an eCommerce business selling specialist food/drink mostly to the elderly, with its key point of difference being that many meals can be stored in a cupboard, and don’t require refrigeration or freezing.
I reviewed the interim results here on 7 Sept 2021 (when it was 110p), concluding that I’d only be interested if it fell further to 50-60p. Now that the share has hit my buying range, am I tempted to buy? With 42.2m shares in issue, at the current price of 60p, that’s a market cap of £25m, so very small (and illiquid) now.
H1 revenues were £14.0m (averaging £2.3m per month)
This has since increased to £17.8m for the 8 months to end Aug 2021, so £3.8m in July + August (averaging £1.9m for the 2 months, down on H1 run rate)
The latest guidance (from y’day’s trading update) is FY 12/2021 revenues of £25.0m. That’s £7.2m for the last 4 months (Sept-Dec 2021), a run rate of £1.8m per month.
That’s a big reduction in revenues, and a serious setback. It’s down to supply chain problems, but it’s not like MEAL is importing from the Far East with ready meals stuck in the Suez Canal or similar. It blames labour problems.
What I reckon is this - as a small producer, outsourcing production to factories that probably have much bigger & more important clients, then it seems likely MEAL is near the back of the queue. Hence it’s taken a production hit. Maybe that’s a problem with outsourcing - great when everything goes smoothly, but no control over production when things get difficult.
Thankfully, marketing spend is being slashed, so the cash pile of £5.7m at 31 Aug 2021 should last longer.
Finncap’s latest forecasts show a huge loss of £(8.3)m for FY 12/2021, at the adjusted PBT level. Checking the interims, it seemed to make a £(4.0)m adj PBT loss (I’ve worked that out manually, by deducting exceptional IPO costs). If marketing spend is being slashed, then why is the H2 loss slightly worse than the H1 loss? That doesn’t seem to make sense to me.
For the following 2 years, Finncap forecasts revenue growth largely stalling (makes sense given slashed marketing spend). Guidance is for smallish losses of £(0.65)m in 2022 & 2023.
My opinion - it’s very difficult to see any reason to buy this share, other than the bombed out share price. The business model doesn’t seem very good to me, and the story sold at IPO seems to have pretty-much collapsed. That leaves institutions with large, lumpy holdings that they’d probably rather not hold. So who’s going to buy the shares in sufficient size? Or will institutions sit tight and wait for a recovery (if one happens)?
All the marketing spend to date has not all been wasted. Consumers have very long memories, and brand building from advertising lasts a long time. So I do see some value from the sunk marketing spend.
How to value this share? No idea. The business model has fundamentally changed for the worse, so the shares should be cheap.
For me, it would only ever be a really distressed purchase - if institutions smash the price down to a market cap of say under £10m, that’s the level where I perceive risk:reward to be better balanced than the current £25m.
It joins the very long list of IPOs that, in hindsight were opportunistic sales, with the growth story exaggerated, and the pricing far too high. It makes me wonder how long the IPO gravy train can keep running before investors tire of the losses?
.
Supply Chains & Inflation
It’s fair to say that supply chain disruption & increased costs are now the main investing themes - more so than covid I reckon.
We’re already seeing profit warnings, and it seems clear that every business which imports goods or components from the Far East, is likely to be impacted to varying degrees by delays (I’ve heard it’s now 80 days to import, as opposed to 40), and increased costs ($20k+ per container, as opposed to less than $2k).
A key question to ask companies on webinars, is the value of their goods in a typical container. I asked Portmeirion (LON:PMP) (I hold) and they replied that it’s about $100k per container. So previously the freight charges were under 2% of cost. Now it’s c.20%. That’s a massive impact, and means that companies have to either increase selling prices, or take a hit to their own margins. Hence the ability to raise selling prices is another key question to ask management on webinars - e.g. how much of increased costs are they passing on to customers?
I think it also reflects on the general competence of management. Did they build up buffer stocks when the problems began? Or have they just run into trouble with apparently no effective planning for disruption in advance? (e.g. In Style (LON:ITS) )
Is there flexibility in their supply chains? Can they re-shore production to the UK, or somewhere nearer (e.g. Europe)?
It seems obvious now that we’re heading for numerous profit warnings in the coming months. For long-term investors, does that matter? Not really, as with the pandemic, long-term holders can effectively ride out a period of disruption where there’s an end in sight. We don’t know when global supply chains will be sorted out, but they will be sorted out.
Which means that people holding cash, should have some lovely buying opportunities to buy great companies at discounted prices in the coming months. That’s quite exciting to a value/GARP investor, since I’ve turned away most shares this year as looking over-priced. Maybe I'll get a chance to buy some excellent companies at bargain basement prices?
Another key question, is whether it’s worth selling things now, in the hope of buying back cheaper, when (often inevitable) profit warnings come out? I think that depends on a few things, for each share individually -
Broker forecasts - how aggressive or cautious are they? I’ve been criticising analysts this year for being too cautious in many cases, leading to actual results often thrashing forecasts. However, with quite severe supply chain problems now impacting practically everyone who sells physical goods, then investors need to check forecasts again, to ensure they are prudent, and not overly optimistic. Going back to Portmeirion (LON:PMP) I challenged mgt as to why the bar had been set low for H2 2021. They replied that supply chain issues mean they want build in plenty of allowance for those costs/delays. Very sensible. We can no longer assume that companies are going to beat apparently cautious forecasts. So is that high PER really justified, for your favourite share?
De-rating - many shares have already de-rated. We never know why anyone is selling, but it’s safe to assume that e.g. Luceco (LON:LUCE) has crashed from a peak of c.500p to little more than 300p, despite strong figures, and a reasonable outlook recently. It did mention supply chain issues, but sounded confident in being able to handle them. Despite this, investors have severely punished this share. A Director repeatedly selling recently hasn’t helped sentiment either.
I thought LUCE was starting to look attractive at 380p, and began buying. I only dipped my toe in with a small initial purchase, thank goodness. A recent book I was reading (can’t remember which one, it might have been 100 Baggers) suggested buying in 3 stages, so that you can average down if the price falls (providing the fundamentals are sound). That stuck in my mind, so that’s what I did with LUCE. At 320p recently, I pushed the button again and bought stages 2 & 3, so am now up to a full position size on that one. So expect a profit warning any day!
Holding fire? - many shares are de-rating now, in expectation of supply chain problems, but then tend to lurch down again on the actual profit warning due to supply chain problems. Shareholders are therefore punished twice for the same issue.
For that reason, I’m now thinking in terms of building up cash, and waiting, rather than steaming in and buying shares now which have fallen a lot. I’d rather wait for the next trading update, and assess things at the time, with probably no rush to buy shares where sentiment is (for now anyway) very negative.
Rebounds - as we saw with covid, markets sold off very rapidly & deeply, but when it came, in late March 2020 I think, the rebounds were also very rapid, and large. I wonder if we might see a similar situation with supply chain problems? Maybe not such a large fall as with covid, but my hunch is we could see bigger drops in many shares over the next 4 months, as no doubt the media will be full of stories about shortages in the shops, etc. (a cynic might imagine possibly planted stories, to help stimulate earlier Xmas spending?!)
Cash? I know several shrewd investors/traders who have been moving into cash, which I think makes sense, if you’re good at market timing. That means side-stepping the inevitable profit warnings which we all know are coming. Then you can pick your moment to go back in. This strikes me as a good strategy right now, if you can execute it well, and there is the risk of missing out on takeover bids if you're sitting on the sidelines.
The trouble is, I’ve observed over the years, that people who are so cautious that they prefer holding cash, rarely deploy that cash at the market bottom, because they’re too scared. Hence they avoid the big downturns usually, but often also miss out on the big rebounds.
Personally, I prefer using index shorts (I tend to use the US indices, as they set the direction for UK markets) in times of uncertainty. That is working quite well at the moment, with my profits on Dow, Nasdaq & S&P500 shorts recouping all my current losses on Boohoo (LON:BOO) (I hold) and numerous other losses which have emerged in recent days. The trouble is that US markets tend to be so volatile, that the repeated “buy the dip” buyers often snatches away my shorting profits, whilst UK shares in my long portfolio don’t seem to rebound as much. Hence I need to give more thought to my strategy here.
Portfolio review - I’ve thought about all the shares in my portfolio, and tried to imagine how their supply chains might be impacted at the moment. Also it’s worth revisiting my notes here in the SCVRs, as I’ve been reporting on supply chain outlook comments for a while now, so it should all be here in the archive, for individual companies (access company comments here under the "Discuss" tab on any company's StockReport).
Anyway, pleasingly, there’s not a huge amount of stuff in my portfolio that is at risk, or at least wouldn’t hurt me that much, if say the price drops 10-20% on a profit warning due to supply chain problems. These are, after all, temporary/fixable problems, so the impact should be less than the company-specific, generic profit warning share price drop of c.30%.
When we buy shares, we’re not buying this year’s earnings only. We’re buying all future earnings forever. Therefore one bad year (OK, 2 bad years!) due to the pandemic & its aftershocks, should not impact profits from say 2023 onwards. Often companies emerge better, stronger businesses, from a crisis.
I’ll go through my portfolio again, and see what other things I might trim back on. For example, I've reduced my position size in Gear4music Holdings (LON:G4M) recently, as it imports most things from China, so is bound to be seeing some supply chain impact. There again, the forecasts seem cautious, so it could already be factored in somewhat, maybe? I can always buy them back later, if it’s a false alarm.
Holding shares is not a binary decision. I often trim positions, if there’s some uncertainty, keeping a core, smaller position, and building it back up again once I’m happier with the fundamentals, and uncertainty has receded.
What we need to avoid, is having large overweight position sizes in companies where it was fairly obvious in advance that supply chain problems would be having some impact (e.g. my position in Boohoo (LON:BOO) !)
Services sectors - I’m wondering if it might be best to avoid companies selling physical goods that are made in the Far East, for the time being? Instead, I might focus more on services companies, that don’t have any issues with importing goods.
Inflation - my hunch is that this is a more serious problem than central banks, Governments, and investors seem to currently think.
The trouble is that supply chains are disrupted, causing widespread shortages & delays in practically everything. Plus, labour disruption also exists in many countries, not just here - often because people needing work don’t have the right skills to fill the vacancies.
Then there’s the matter of arguably over-stimulus by Govt policy, with Bank of England data showing households & companies swimming in cash. So there’s demand for things like home improvements, and pricing is going up.
Anecdotally, I tried to book a decorator, who declined, because he’s booked up for the next 6 months. We’ve just had our carpets cleaned, which usually costs £60. We had to pay £130 today, the new going rate, because they’re booked up due to strong demand.
Put all that together, and it seems to me a recipe for longer-lasting inflation, maybe? Once companies put their prices up, and discover that customers are prepared to pay more, they’re not going to voluntarily reduce the prices in future, are they?
Conclusion - nobody knows what’s going to happen in future, so as always with shares, and economics, it’s little more than educated guesswork.
What we can say with certainty, is there is elevated uncertainty at the moment! Hence why I think it’s more important than ever not to over-pay for any share.
For new purchases from now on, I really want to see -
- A bang up-to-date trading update (so no guesswork, just recent facts)
- Strong balance sheets (as always) so insolvency/dilution risk is minimised
- Attractive valuation - so a PER in the low teens maybe, or high single digits, not mid to upper 20s or above
- Cautious broker forecasts, that already factor in supply chain disruption.
- No large scale recent Director selling - they know the business better than us, so if they’re cashing out in size, that tells me things are not looking rosey.
Profit warnings - I’d like to see the share price really smashed down, after having already de-rated, before committing new money, and it’s got to be a high quality company. New purchases have to be compelling value, for me to take the risk at this point in time, of buying something new.
That’s all I can think of, off the top of my head, and no doubt we’ll be revisiting this theme probably on a daily basis, for the rest of this year, at least.
Situations like this do create opportunities, and the profit warnings of today, could be the lucrative investment gains of 2022-2023, once supply chain issues begin to correct. In terms of timing though, I think we could see the news get a lot worse, so it’s probably too early to be opening new positions, as they could have further to fall maybe? Who knows, that depends on market sentiment in the short term.
EDIT: one final point. I've noticed that some small caps have been falling in price sharply, which are services companies, hence have no supply chain uncertainty. If they've put out positive recent trading updates, then I would be prepared to buy more. Examples that I particularly like are Beeks Financial Cloud (LON:BKS) and Cambridge Cognition Holdings (LON:COG) (I hold both, and am buying more). As always, please DYOR, because some of my ideas will be right, and some will be wrong, same as everyone. End of edit.
.
Ao World (LON:AO.)
166p (down 24%, at 13:03) - mkt cap £768m
By the way, I always manually adjust the market caps here, to reflect today’s price move. Remember that the data on the StockReport is all updated overnight, so will reflect the previous day’s data, including market cap. That’s important to remember, especially when looking at shares that have moved dramatically in price today.
Trading Statement (profit warning)
AO World plc ("the Group" or "AO"), a leading European online electrical retailer, today issues a post close trading update for the six months ended 30 September 2021.
Company’s summary -
Continued growth in a challenging operating environment
Slow revenue growth in H1, only +5% against strong prior year comparatives (in lockdown 1). “Challenging market dynamics”
UK - revenues up 6%, growth impacted by supply chain problems, and shortage of delivery drivers.
Germany - revenues up 3% (constant currency) in competitive online market.
Two year like-for-like sales growth is very strong, demonstrating that all the growth was packed into last year, due to lockdowns, and it’s now more difficult to beat those exceptionally strong prior year numbers (similar to what Boohoo (LON:BOO) (I hold) said yesterday.
… on a two-year like-for-like basis, Group revenues grew c.66%, with our UK business growing c.63%. Like-for-like revenues in Germany grew c.84% over the same period.
Supply chain - I would have liked more information on this, instead it’s rather glossed over, possibly because it’s commercially sensitive? -
Whilst we continue to see industrywide issues relating to ongoing supply chain disruption, we have implemented measures to help mitigate these challenges in our logistics operations.
It sounds like they’re on top of the issues though, if this forward-looking statement turns out to be true. Q3 is Oct-Dec 2021 (March year end) -
Whilst the macro-outlook remains uncertain, we have confidence in the proven resilience of our business model and are well placed to meet customer demand in our peak third quarter sales period.
Guidance -
… anticipate that Group Adjusted EBITDA3 for the full year to be between £35m and £50m, with profits more heavily weighted than usual towards the second half of the year driven by the peak trading period…
3Group Adjusted EBITDA is defined as profit/(loss) before tax, depreciation, amortisation, net finance costs, and other adjusting items.
Diary date - 23 Nov 2021 for interim results.
Valuation - I can’t find any broker research, so let’s look back at previous company results, which are as follows -
FY 03/2020 (pre-pandemic): adj EBITDA £22m
FY 03/2021 (pandemic): adj EBITDA £64m
FY 03/2022 (company guidance): adj EBITDA £35-50m (significantly down on prior year)
My opinion - AO World has enjoyed a high rating on its shares for a long time, because strong growth was worth more to investors than modest profits.
Now that it’s becoming clear last year was an exceptionally good year for online businesses, and they’re struggling to generate any further top line growth, many have de-rated significantly (e.g. Boohoo (LON:BOO) (I hold), Asos (LON:ASC) (I hold), and many others internationally too, not just in the UK).
I think it’s probably fairer to average out the growth over the last 2 years, which looks a lot more impressive. So it could be the case of one amazing year, one lacklustre year, and then in future growth might settle down somewhere in between? That’s my guess. Therefore, we might possibly see eCommerce businesses re-rate back up again, at least partially, once they’ve passed through the current period of exceptionally strong prior year comps?
The problem I have with AO, is its business model is just not very good. It sells other companies brands, at low margins, against lots of competition, with quite high delivery overheads. So they have to shift a huge amount of goods, to eke out a 5% EBITDA margin.
The EBITDA margin doesn’t stand up to scrutiny, because depreciation/amortisation, and finance costs are quite high, so last year's £64m of adj EBITDA only flowed through to £17.1m of profit after tax. Not much really is it, and that was in an exceptionally good year.
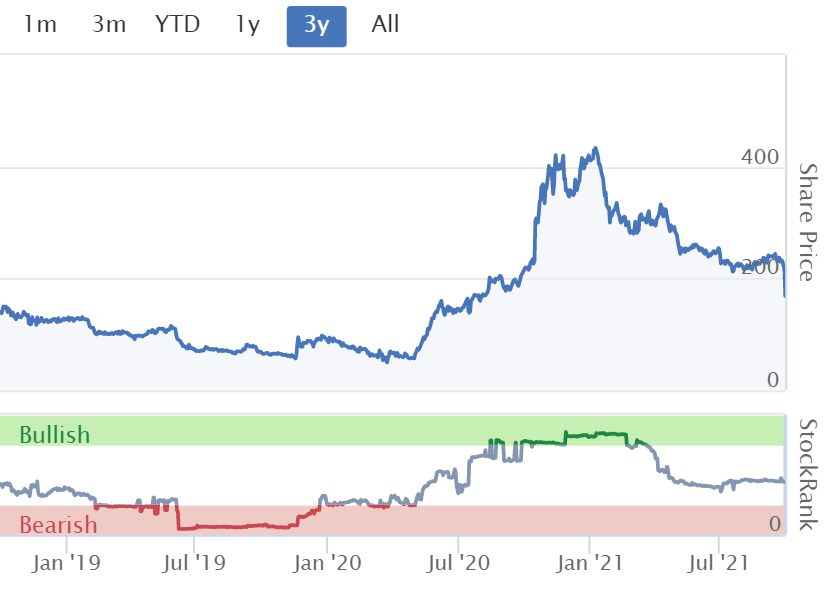
Given that this year’s adj EBITDA is going to drop considerably, then at the profit after tax level it might only get to breakeven. Yet this business is still valued at £768m, despite having fallen in price a lot (see chart below).
Therefore, the way I look at the numbers, it’s a long way from being a bargain, for a not very good business, who are arguably busy fools - generating a ton of revenues, for very little bottom line profit.
As you can see from the 3-year chart below, it has now scrubbed off more than half the speculative boom which was triggered by the onset of the pandemic. Rightly so, as the fundamentals don’t justify that move at all.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
i like the look of £luce but still it heads down
£BOO..Guys am I being thick but does anyone seem to know if Paul has written an update ( I hold) on BOO?..FWIW, I am not concerned long term about the fall since Thursday, as very few investors liked Amazon on days of its massive losses and falling share price..look at it now.I still would not buy Amazon but I want more Boohoo (LON:BOO), as it will get the recognition eventually for the investment into their future business.
He has written something on Boo, best to click on his profile and then see his recent posts.
If the energy crisis leads to rolling power cuts and 3 day week then Parsley Box (LON:MEAL) might make an excellent investment.
Paul, excellent preamble / commentary on the outlook for supply chain and inflation issues, very useful thanks
Any one have views on Tmt Investments (LON:TMT) ? It’s a tech investment/early stage VC fund that is doing a small fundraise including a retail piece via Primary Bid at a 7.5% or so discount to market (but about a 13% premium to NAV). Not looked at it before but it’s ranked here as a Super Stock and appears to have a pretty good track record with consistently high ROC/ROE. Wary of buying in at the top of a frothy tech market but thinking it might be an interesting way of getting a diversified spread of exposures to a high growth sector that’s not readily accessible.
Gus.
https://www.morningstar.co.uk/...
Many thanks Paul for all your thoughts on Supply Chains and inflation.
I wondered if you had a chance to look at Revolution Beauty.
A trading update was released by REVB on Monday 27 September 2021.
Zeus have done two research notes on Revolution Beauty. One on 24 September 2021 and the other on 27 September 2021.
I see the Soros Fund invested £20m in Revolution Beauty's IPO.
I would appreciate your thoughts on Revolution Beauty when you have the time to do this.
SHORTING NASDAQ / S&P ?
Thanks Paul - you have confirmed what I've been thinking all month as I have steadily unwound all but my top 3 holdings and even top sliced them. I bought a tiny stake in £3USS and £QSSS today as I'm convinced we are going to see more inflation than the central banks will admit to. I'm a newbie at shorting & don't do spreadbetting, so ETF's are my only option - but the daily roll over can negate profits in a downward trend if there's volatility. Anyone know the best trade for a longer term short - say 3 months?
I briefly dabbled with the 3x leveraged ETFs to go short a couple of years ago but (to state the blindingly obvious) they are incredibly volatile so found them too uncomfortable. They are also useless if held for long term periods - due to the maths of how they work (which I went go into here) they are almost certain to deliver negative if held for more than a few months (they are designed to be held for a day). They can however deliver explosive compounded returns if markets really tank - 3USS roughly doubled in March 2020.
.
Thanks Paul - interesting comments
On whether supply chain issues create buying opportunities and whether these issues are fully priced in, I thought yesterday afternoon’s RNS by Character (LON:CCT) was salient.
On 5 July Character Group said it would do a tender offer in future for upto 3.2 m shares (15% of company).
On 15 Sep, because of supply chain issues, it warned on the profit level by 10% and said issues were continuing but the underlying business was strong and an announcement on the tender offer would be made by end Sept. The shares fell by a quid to 590p and subsequently drifted to 550p by yesterday afternoon.
Yesterday at 12:24, in a very short RNS, CCT said supply issues were continuing and that “in the circumstances”, the tender offer would not be announced until after the announcement of the prelims in Dec. The shares have now fallen to 460p.
I think the most plausible interpretation (only my guesswork), is the board thought there was no value being created by buying backs shares at 550p or higher - and had expected a greater fall on the initial announcement on 15 September.
Other interpretations are perhaps even less bullish (eg with the critical Christmas period coming up, the Board no longer felt comfortable spending this excess cash on a tender offer).
I don't think either. The board have always been highly conservative and are very protective over the business. They will have decided that until the supply chain issues show signs of being over there is no point throwing cash at tender offers as it won't help the share price anyway. So the sensible thing to do is hold the cash for a few extra months and do it at a more appropriate time.
This is a very well run company as time has shown. Supply chain issues will subside and the business will at that point look very cheap. As usual this is really MM driving stock on teeny tiny volumes. Suck people in to sell and buy them back cheaper. Winners all round - well the MM are :)
The last "profit warning" was for a 10% change in this years profit. That has driven the stock down by 40% - it is hilarious. I'm waiting to add more. Next year this will do over 40p eps and trade on a cash adjusted 6 or 7* earnings with strong yields.
Christmas will be another ridiculous "petrol panic" mania. People are already trying to buy their toys in case the shops run out. Character (LON:CCT) will have pricing power so as long as they've got the supply ordered early and it seems they have managed this well enough so far then they will be able to pass a chunk of current costs on to the consumer. Ok for Character (LON:CCT) not so good for inflation.
RE: Character (LON:CCT)
They will have decided that until the supply chain issues show signs of being over there is no point throwing cash at tender offers as it won't help the share price anyway. So the sensible thing to do is hold the cash for a few extra months and do it at a more appropriate time.
I don't understand that.
Surely undertaking a buyback at a lower price means more shares are retired and means that remaining shareholders benefit even more from future earnings? When the share price recovers long-term shareholders - who presumably are what the board would like to encourage - would benefit even more at the expense of short term sellers.
I don't know anything about CCT but in general buybacks are all too often associated with financial engineering to the benefit of the executives. As buybacks will normally push the share price up (assuming earnings stay constant) this can often be very helpful for executives looking to hit share option exercise prices.
Alternatively the management don't think the finances are strong enough to handle the buyback and the supply chain issues. In which case they shouldn't have been considering a buyback at all. Let's face it, once in a lifetime events in markets happen all the time, managements should always ensure that they have finance in place to deal with that.
But as I say, I don't know anything about CCT. This may be some kind of outlier situation. Maybe they have some indication that a buyback would fail anyway?
timarr
its not a buy back it is a tender offer. Therefore the intention was for investors to tender their shares at a higher than market price. ie one more aligned to what the board considered fair value. Net result is that all shareholders get the opportunity to exit 15% of their holdings at a higher price. The shares are then retired and earnings are enhanced by 15% due to less shares in issue with cash balance reduced.
This type of scheme benefits all shareholders equally but unlike a capital return allows any shareholder who so wishes to not tender their shares and hold onto them or inversely offer more than 15% to do so.
But that was when the share price was 700p. Now it may make more sense to do a buy back in the market to take out loose shareholders that are allowing the MMs to keep bashing the price on no volume.
I don't get why Character (LON:CCT) needs to wait till mid-Sep to warn of supply chain issues.
Surely all the toys are ordered by June/July?
And around the same time, they should be locking in shipping capacity for Sep/Oct.
So that the stock arrives well ahead of Nov, Black Friday, Christmas for the key sales period.
Either they leave things to the last minute (not good management) or they sat on material non-public information for longer than they should have (not good for corporate governance).
I have vaguely remembered that in previous years they've been prone to several profit warnings, so maybe it is the former.
they didn't!
they warned that the costs associated with the global supply chain issues (that they also said they have navigated their way through) meant that EPS would be 10% less than they had anticipated.
Very different thing and one of the reasons investors really should spend more time on what is actually going on rather than making wild stabs in the dark about supply vs cost whilst paying no attention to the actual statements. Best to actually read and take in what they say before commentating!
Perfect Friday wider picture summation today Paul - many thanks for it on your 1st day back in the office!
Angle (LON:AGL)
Update from Trinity Delta giving a target of 248p ps before FDA approval.
https://www.trinitydelta.org/research-notes/poised-to-disrupt-existing-tumour-assay-protocols/
Yesterday’s interims Webcast by Angle was recorded and will be on the WEB site soon.
Vertu Motors (LON:VTU), I don't think it is down that much, down 14.4% according to Stocko but that may not inc. todays 1% fall.
Scs (LON:SCS) a candidate. Has re-rated to a reasonable 274p support but was 250p back in 2020 so will set an alert there. Has loads of cash down the back of the sofa.
Dunelm (LON:DNLM) and Luceco (LON:LUCE) £FAN will also hold fire following recent falls
Interesting times.
Scs (LON:SCS) - with prices of petrol, energy, Christmas turkeys, xmas toys, everything going up this year, how many families will have extra money for a big capital expenditure like a sofa?
Plus last year and early this year there was already a splurge on furniture as families saved more than expected, and stayed home more, so chances are a lot of 2021-2022 sales were pulled forwards. People who had a tear or rip in the sofa who would have continued for months/year longer probably changed earlier than expected.
Vertu Motors( LON:VTU) over 30% down since the beginning of the month. Seem to be falling back considerably from the highs.
what is not ? Another great company that I hold and will keep onto for the long haul
I seem to be the only person under 60 who actually enjoys the meals from Parsley Box (LON:MEAL) . As an investment, however, I wouldn't touch it even as its current price. Sympathy to anybody who took part in the IPO at 200p.
Keep enjoying the shareholder subsidised meals! As Parsley Box (LON:MEAL) are still loss-making, every box you eat cost the company more to sell to you then what you paid for it :)
Hi Paul. it’s a sore subject, but what are your plans with BOO?
Still waiting ... I am getting quite despondent. I think if we were to expect any dialogue, the comments would have come yesterday after a short flight. Pity.
Hi drydoc,
Still waiting ... I am getting quite despondent. I think if we were to expect any dialogue, the comments would have come yesterday after a short flight. Pity.
What a ridiculous comment.
Paul.
Hi hampsob,
I'm relaxed about Boohoo (LON:BOO) (I hold). Short term losses don't matter to me, for my long-term positions. The fundamentals are still excellent, and if you read the revised forecasts note from Zeus today, you can see that it's a pretty mild warning. The large additional freight costs are much more than I was expecting, but that's a temporary factor that will reverse in time, and all competition will be subject to the same issue.
On Zeus's revised numbers (10p EPS for this year), it's almost a value share, on a PER of 21, and with seriously big growth in the pipeline from new brands (esp Debenhams, with its marketplace, and was already a Top 10 UK fashion eCommerce site under previous ownership).
Hence I see the sales slowdown in the summer as a blip, with the long-term investing case completely intact. I'll be waiting to see where BOO settles, then will buy more.
My main concern is increased competition, and there's no doubt that is real. In particular, my attention was drawn to Chinese app "Shein" which has hoovered up massive market share in USA, and is likely to want to do the same in the UK/Europe. Hence it's probably wise to trim expectations of BOO's future margins.
That said, BOO is way ahead of competitors in EBITDA margin, so Shein is likely to kill off smaller, me-too competitors, that are struggling to make any meaningful profit, like In Style (LON:ITS) , Missguided, and many others.
Sorry for clogging up the SCVR with comments on BOO, I know it's meant to be on the other board. I was late commenting because I was busy travelling back to the UK yesterday, and didn't get home until about 11pm, and was v tired & mildly sozzled after getting my money's worth from my upgrade to business class for £89!
Best wishes, Paul.
Thanks Paul. Boohoo (LON:BOO) was my largest/2nd largest holding but now my third. I agree with you and have not sold. If it was to fall considerably I might top up but as a 10%+ holding for me it is large enough.
No need to apologise for "clogging" up the SCVR on £BOO.
As an aside sorry about the welcome home comment from drydoc. Hope you had a great holiday. I have never been but my late mother loved Madeira.
Regards
Michael
Kindly refrain, Michael. The absence of a thumbs down is not a licence to troll.
Paul - small point to pick up on about containers. You dont just need to ask about the value a company has within the container but also whether the container is dedicated to them or shared. eg if Portmeiron have £100k value in a container but it tends to be shared with 3 other firms to maximise capacity then your 20% becomes 5% and has rather less of an impact on costs. I agree with the gist of the overall point but need to be careful as a seemingly innocuous assumption can make a big diff.
Hi davidjhill,
Paul - small point to pick up on about containers. You dont just need to ask about the value a company has within the container but also whether the container is dedicated to them or shared. eg if Portmeiron have £100k value in a container but it tends to be shared with 3 other firms to maximise capacity then your 20% becomes 5% and has rather less of an impact on costs. I agree with the gist of the overall point but need to be careful as a seemingly innocuous assumption can make a big diff.
Yes that's a good point, so we should re-phrase the question to include the words "a full container with your stuff in it only". I think that was implied with PMP, so I doubt very much the CEO would have quoted numbers for partially filled containers.
Another way of phrasing the question would be to ask what freight costs are as a % of the production cost, now, compared with previously. I might do that instead.
Cheers, Paul.
yep agree Paul - that's probably the better way of asking the question. The directors should know that off the cuff. Not only does it prevent us from making assumptions that may be incorrect, but also if the directors don't know that number given the current circumstances it should raise amber flags as to how well they might control the situation.
Reasons to be cheerful? an interesting IPO next Friday for Tortilla a fast food outlet approx £70 m market cap. Admission document on tortillagroup.co.uk http://tortillagroup.co.uk/wp-...
It is a weird old market at the moment and quite schizophrenic. Really there is little direction so what tends to happen in these sort of times is that professionals sit and wait for the direction of travel to reveal itself. Perhaps neither buying nor selling much. Retail investors on the other hand tend to be too quick to hit the trade button and follow each other in and out of positions. The relatively low liquidity means the market exacerbates the move and causes other weak retail hands to also move. That's generally why you see what appear to be fairly irrational mark downs.
This is often how retail tends to lose money. The other way is buying high and selling low - ie being slow to protect portfolios in a big market move down and then capitulating when there is blood on the streets or FOMO on the way up when everything is frothy.
At times like these I find it generally best to ignore the daily volatility and try to focus on fundamentals medium term. ie Not get swayed by the short term media frenzy on, for example, petrol pump shortages but to look a year out. Remember that when you buy into a company you are buying earnings into perpetuity not just the next 6 months, so if there is a very short term trend putting pressure on earnings that alone shouldn't carry too much weight on an investment decision if you consider it will ease in 3/6/9/12 months etc.
Gulf Marine Services (LON:GMS)
Would be interested in anyone's opinion of this company. I've had a quick look at them this morning after they released a trading update and they look strikingly cheap although not without risk due to heavy debt and a poor long term track record.
A market cap of £38 million looks too low with H1 revenue increased to $51.4 million resulting in a return to profitability and what looks to me to be a positive outlook for H2. It has also had recent director buys and a strong pipeline of future revenue.
It's not a sector I know anything about though so would welcome any comment. What am I missing here?
Massive debt
Hi CliffW.
I’ve dabbled in Gulf Marine Services (LON:GMS) a little in the past. Historically they were essentially a leveraged play on the Oil and Gas Capex sector but have since extended their business to include a lot of work related to renewable infrastructure especially offshore wind turbines. I think I bought into them originally as part of a NAPS based selection in 2016 (stock rank in the 90s as I recall) but sold out at a reasonable gain as the ratings dropped.
It’s quite a tough business requiring very high investment in specialist service vessels for both initial fit out and ongoing maintenance which are then leased as and when required by an O&G industry that can be pretty fickle about when and how it manages its own Capex. Vessel utilisation rates are the key value driver. When the sun shines they make hay but in the down times the very high financial leverage is a killer to the equity value. They nearly went under in the recent COVID/oil shock downturn but were bailed out by a big equity raise in June this year supported by their main shareholders which recapitalised the business but still left it with a fair bit of debt. I bought in again at about the 3p placing price taking the view that we are in a good, early stage of the O&G Capex up cycle, that the renewables business gives them decent diversification and that the recap gave them an improved if still slightly fragile financial position. Only a small position that could easily come unstuck but to my mind offering the possibility of a substantial upside. Not one to bet the shop on though and needs careful watching.
Gus.
Cliff
I agree with Yiannos that you have to feel happy understanding the debt on Gulf Marine Services (LON:GMS)
The new management (backed by Seafox) came in with a mandate to take a much harder line with the banks. They got some concessions. But the bank agreement still required that the $25m equity raise needed to be done by June 2021 (now done) and a further $50m raise needs to be done by Dec 2022 as well as a repayment of $75m of bank debt by 2022. If either of these two is not done, then the banks should get warrants which will massively dilute the shareholders.
I think it is a very interesting situation - too complex and the jurisdiction to difficult for me - but where I think realistically the situation is binary either the banks own the company or shareholders do very well - it is trying to work out the probabilities of the two options.
The higher oil price will clearly help the operating business in the gulf and if there is a pick up in the North Sea (particularly in wind farm construction) then there could be an opportunity to reposition some of the higher spec vessels back to the North Sea.
The other things I found difficult to get comfortable with was (i) the relationship between Seafox and GMS - competitors?/ shareholder/ injecting new management/ previous bidder for the company and (ii) there seemed to be a difference between the book value of the vessels in the Dec 2020 account and the valuation of the independent valuer, which I could not reconcile. In the end, it got in the too difficult pile for me and I diarised it to reconsider in late 2022.
I think it is a very interesting situation and one that could have big upside but very high risk.
Gulf Marine Services (LON:GMS)
Thanks Gus & Wimbledonsprinter. I agree on the worries you have raised concerning debt and you have both provided many interesting points that i had not known, thanks again.
I've bought in a small position this morning even though it is high risk. I just feel the upside far exceeds the downside. Interim results are announced the week of October 11th and I feel now is a good time to enter the market due to todays upbeat update.
Is Paul going to comment on BOO?
See above. I'm relaxed about Boohoo (LON:BOO) - it's a mild profit warning, and the Zeus update note (on Research Tree) trims the forecasts a bit, and it now looks superb value (current year PER of 21, on lowered forecasts). It doesn't matter to me what the share price does, it's a 5-year hold for me, and the fundamentals haven't changed when viewed over that timeframe. Although I am worried about Chinese app Shein, which looks a major competitive threat.
Regards, Paul.
P.S. I've not sold any BOO since the profit warning y'day, and am waiting to see where it settles, when I intend buying more (hopefully sub-200p). Sorry for the short term losses, which are obviously frustrating, but there we go, that's the market.
Thanks Paul
Hi Paul, you don’t need to apologise for any losses, everyone on here is responsible for their own investments.
Hi Ipreidster,
Hi Paul, you don’t need to apologise for any losses, everyone on here is responsible for their own investments.
That's very kind, thanks. However, I think it's just good manners to say sorry to people, when one of my share ideas goes wrong (in the short term anyway - I don't think the long-term BOO investing fundamentals have gone wrong at all, but that could be wrong, and there's always the lurking risk of unconscious bias, in all of us).
Plus of course when people lose money, they often lash out, and attack whoever presented the investment idea positively in the first place - so I find an apology is just courteous, and I'm big & ugly enough to take the flak, if it comes my way.
I think it's better to stick to discussing the fundamentals, which is what is so refreshing about our community here on Stocko. Whereas elsewhere, on free sites, people descend into mindless personal abuse all the time, in fact it's the norm! Here we discuss the facts, and it's nearly always courteous & supportive - which is wonderful. Everyone is allowed the occasional bad day, none of us is perfect.
I've taken some heavy losses in recent months, but also some quite good gains, so overall it's OK. We were very spoiled from Oct 2020 onwards, when the vaccine "everything rally" began. We got used to making big profits almost every day. A lot of shares became over-valued as a result. That phase is over.
As my Aussie mate says, "It's over! O - V - A -H - ovah!"
(imagine that in a loud, raucous Aussie accent, it's hilarious! But as usual, my humour doesn't necessarily transmit in text form to people with no sense of humour, who don't know me - a recurring problem we find!)
Have a great weekend everyone!
Best wishes, Paul.
Interesting update from Iomart (LON:IOM) - yet another profit warning (on a Friday too). They have been a poor investment for the past three years, but, with a new CEO making some apparently sensible changes, things could change.
I see he made a small purchase earlier this year a price of 266, the shares are now down to 181. I don't hold, but I could be tempted at this level.
Might be worth reading the Stocko guide to profit warnings. If I remember correctly, you should not touch them for at least a year after the initial one (but I haven't read it in ages). The take-out for me was get out on the first one.
Hi Funnymoney,
Might be worth reading the Stocko guide to profit warnings. If I remember correctly, you should not touch them for at least a year after the initial one (but I haven't read it in ages). The take-out for me was get out on the first one.
I think that's sensible for regular profit warnings, which occur due to company-specific problems.
However, if some macro factor (pandemic, supply chain issues, etc) is causing widespread profit warnings for many companies, which could be resolved in a reasonable timescale, then I see things completely differently.
When a high quality company issues a profit warning, due to uncontrollable external factors, which should be fixable in (say) a year, then I see that as a potential buying opportunity to research.
Regards, Paul.
Pretty sure it's down because I finally bought some yesterday. Sorry all.
Reading the comments for the last couple of days I sense a lot of panic. If you can't stand the heat get out of the kitchen! You take the good with the bad and never invest what you cant afford to lose. Investing in shares is never easy....but it is always interesting.
A small news on a slow news day from Begbies Traynor (LON:BEG) released as an RCS. £250k acquisition for its property services division.
The interesting bit is the statement at the end, restating the outlook of strong performance in their property services division. Not a full trading update, but a good reassuring statement nonetheless.
(I hold)
Somero Enterprises Inc (LON:SOM) down over 5% which seems harsh even on a down day, has anything happened which I've missed?
US infrastructure bill vote delayed. It's at risk due to brinkmanship by Democratic left.
Nope I have a large holding profit taking I suspect then the stops start clattering, well I hope so
Probably stop losses on other stocks and people just trying to raise some cash
Irrespective of the numerous econometric opinions around this stock, it is very obviously taking a pounding through crisis of investor confidence and negative publicity. The moment to react is when it has a decent reversal in volume to match the downside, which invariably seems much higher.
IMO it's also a victim of being a darling of the retail investor- this leads to more regular participation both in and out. Having said all that I still think that the base is from here down to £1.50...........
My portfolio seems to be in daily decline mode at the moment, how are others doing?
Yes, same. October hasn't started very well, roll on November!
I'm actually thinking past few days of selling up everything and coming back in November/December time. Probably best to just sit it out, tempting as it may be...
It's one of the hardest things to deal with. Do you sell and then hope to buy back later? Then you think, if I sell it will probably rally and then you carry on holding whilst things drop 2-3% a day. Even of you were smart enough to go 50% cash, when do you start buying again?
Yes all mine are down in the last month. NAPS is down about 9% in the last month.
Terrible. Glad I am not alone. Had a very large position in Boo which is now in the red, but it seems it is just plain bad everywhere at the moment. I am in single digit growth for YTD now, I am trying to be pragmatic as last calendar year was over +100%, but its sobering none the less!
Been a total slog this year, not enjoyed it. A lot of work for little reward.
From the August onwards the market often declines until we get into the Christmas rally I think that for many complex reasons the market has got carried away and is now correcting and being more realistic Just looking back at the financial news over the last couple of months we do seem to have a lot more to consider some of which will be a lot more than noise
I am a long term investor and my comments are written from that perspective
It looks as if the next two moths are going to be pretty rough but also presenting buying opportunities IMHO.
Silver
I bought into the "commodities supercycle" - good ol miners always the L in P&L, but the bull case is still is still there.
Just did a Sep month end book-keeping of my portfolios, and only -0.4% down in my ISA, and -0.8% down in my SIPP.
Versus -1.2% down for FTSE All-Share and 5% down for the AIM-100.
So escaped relatively unscathed...
It looks like Stockopedia ‘s performance is inverting again like it did last year, the 90-100 band was the worst performing over the last month. NAPS is down about 9% in the past month.
The FTSE100 has not done so badly because of large oil companies, also the £ is down which will help companies with international revenues. The FTSE 250 is down around 5%.
I sold my shares in Boohoo months ago and put the proceeds into the similar German firm Zalando whose shares are also in freefall so maybe it is a sub-sector to avoid
Oh Messiah (you know who I mean) reveal to us thy thinking, what is written in the oracle of Boohoo, in the words of The Cl;ash - 'Should I stay or should I go'
Oh Messiah (you know who I mean) reveal to us thy thinking, what is written in the oracle of Boohoo, in the words of The Cl;ash - 'Should I stay or should I go'
Talking of The Clash era, in the late 1970s I remember walking back to college with a group of friends after a night out. One of our contemporaries had climbed out of a window on to a canopy above a doorway. "Jump, jump, jump," we all shouted, so he did and broke his arm. He would have been better off ignoring the crowd...
DWit199 / makandy
Oh, how I like your last sentence. Most apposite.
Contributors are great here on Stockopedia but they are not oracles they offer opinions both right and wrong - please DYOR, test out your styles and systems and go over the explanatory notes above.
For example check out the Boohoo opinion Apr 9th on Stockopedia - an opinion that happened to be wrong short term (could still be right in the long term).
Good luck to all - DYOR
the big question is whether the contributors are right more often than they're wrong. Only Roland has maintained a public portfolio.
That's because the new site does not have fantasy funds, so all those have been lost.
I can't see Roland's either.
Avoid the most talked about stocks. Boohoo (LON:BOO) was the top pick in the Challenge. Last years top pick was also a poor performer until it was taken over, even then it was only break even..
dodge1664,
Only Roland has maintained a public portfolio.
Not true. I have run a public portfolio on Stockopedia (called "Beam Me Up Scotty" (Ed chose the name) since the start of 2015. It produced a return of about 23% p.a., compounded, turning £1m into about £4m.
Ed specifically asked me to do this fantasy portfolio (which closely mirrored my main long-term personal holdings) back in 2015, and it proved the point. It beat the Stocko algorithms over that period incidentally, and didn't trade very often.
Maybe it's better to ask a question first, before making a statement that is incorrect? * Otherwise you end up looking a wally when you post something incorrect.
Thanks, Paul.
* = e.g. "Have any other writers on Stockopedia run a public portfolio, apart from Roland?"
(Answer, yes - Paul did from 2015 to a few days ago when the old site seemed to disappear)
Paul - would you mind sharing a link to Beam Me Up Scotty Portfolio, can’t seem to find it on the app. Thanks
Fantasy funds were on the old site, they no longer exist.
If you click on the portfolio link, I had various links to fantasy funds, it just takes you the Stockopedia Home page.
Paul’s candid review of the rise (and fall) of Beam Me Up Scotty can be found here:
https://www.stockopedia.com/co...
Thanks for the link to that; what a great read
Boohoo (LON:BOO) still needs to find a floor and consolidate for a while before it becomes investable - this might be it but too early to tell at the minute and there could be further falls. I will be staying on the sidelines until Boohoo (LON:BOO) comes back to life.
Hi Investornot1,
You said:
Boohoo (LON:BOO) still needs to find a floor and consolidate for a while before it becomes investable...
I would change one word - "investable" should read "tradeable" in your post.
P.
Capital (LON:CAPD) has a great announcement today.
its vestment portfolio is up 23m USD in Q3 to 53m USD. verses MC of CAPD of c.£150m.
the rise due to 2 quoted investments listed in Australia, one of which announced big gold resource discovery yesterday so you'd think that the price lifts might have further to go for their investments when the resource sinks in.
CAPD IMHO is picks and shovels for gold mining in Africa, yet seems to be rated as an miner.
broker note out today with target price of 140p.
chart about to break out of 8 year rising trend.
disc i hold
Re the comments on the separate Boo discussion page, I had the same yesterday, there seems to be a lag loading them, they came up eventually, scroll to the bottom, wait 30 seconds or so, and then they pop up.
I have the same problem, I cannot find Paul's latest comments on Boohoo no matter what I try on my computer.
I don't think Paul has done his commentary yet, he was travelling yesterday. I'd rather he takes his time than gets something up quick.
Re Boohoo (LON:BOO), there were several late references to the |Discussion page and lots of comments on results. I can of course find the Discussion section on the Boohoo (LON:BOO) page but cannot find any recent comments. Help please
yeah where is Paul's commentary or is he too distraught to talk about it?
Take a deep breath, then read it again.
All will be explained.
Sort by at the top ‘latest’.
You should then get the most recent posts at the top.
I had the same problem yesterday when looking at boohoo general discussion - the latest post was July. I tried the refresh option on my iPad and that brought up all of yesterday’s posts
At this rate, Boohoo (LON:BOO) will be back on this thread as a small cap.
The original post was in July but there have been lots of posts since then, you can’t see any of the posts?
Sort the comments by latest
Hearty gratitude for your continued visceral alliteration Mr C - always a morning highlight for me.