Small Cap Value Report (Fri 1 Sept 2023) - TLY, RNO, VLX, LORD, SDRY, AXS

Good morning from Paul!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Here's today's news. I should be able to cover most of these -
Summaries
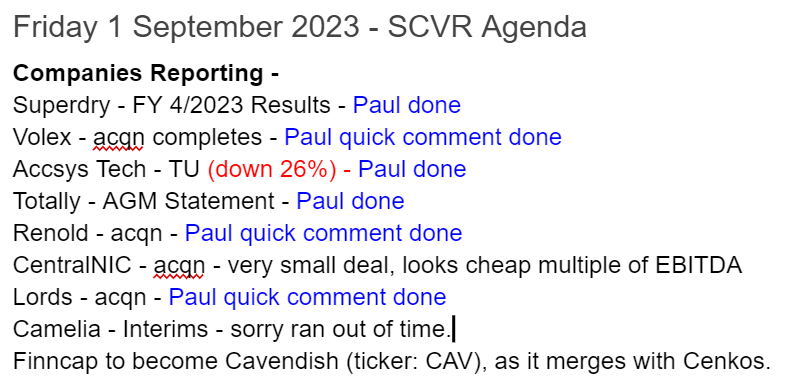
Totally (LON:TLY) - down 12% to 9.4p (£19m) - AGM Statement - Paul - AMBER/RED
An update that seems contradictory to me - mentioning negative factors, but keeping previous guidance. I suspect another profit warning might be gestating. Is this low margin, accident-prone NHS contractor actually any good? I have my doubts. Although the very low market cap could see a bounce in it at some stage, so one for traders perhaps?
Superdry (LON:SDRY) - 56p (suspended temporarily) £55m - Results FY 4/2023 - Paul - RED
Good news (why not announced earlier?) is receipt of £35m net from IP sales in the Far East. However, the results for FY 4/2023 show a move into losses, and Q1 current trading looks very bad, especially wholesale. I think it can survive for the time being, but unless something significant improves, then I imagine it could go bust in 2024. Going concern contains "material uncertainty", so beware, this is high risk. One for traders maybe?
Accsys Technologies (LON:AXS) - down 24% to 74p (£162m) - Trading Update (profit warning) - Paul - AMBER/RED
After a good start to FY 3/2024, demand has now slowed, meaning EBITDA is likely to be "significantly below" expectations. I haven't looked up broker updates, as I've already decided I wouldn't want to get involved here, due to the heavy borrowings from ABN Amro - not a good fit with deteriorating demand & profits. Probable read-across to other building supplies companies, in that it doesn't forecast any recovery until H2 of calendar 2024.
Small cap acquisitions announced today
Volex (LON:VLX) (Paul holds) - GREEN - confirms that a previously announced acquisition in Turkey, called Murat Ticaret, has completed. As expected, so not price sensitive, but reassuring - this is a sizeable deal, and as with all Volex’s acquisitions, seems to make sense (new markets, quality operator), and priced sensibly. I think VLX shares are likely to re-rate to a higher PER in the next bull market. Currently we’re being offered a well-managed, strong acquisitive (and organic) growth group, on a value share rating.
Renold (LON:RNO) (Paul holds) - GREEN - a small acquisition announced (£3m) of Davidson Chain in Australia. Complementary products & geography. High margin niche products. Rationale and price of the deal look attractive, and are well explained. Confirms my view that Renold is a quality business, on the front foot. Yet the market is still pricing it as if the previous problems are still a worry, which they’re not. Big pension deficit suppresses the PER, as I’ve covered numerous times in the archive here.
Lords Trading (LON:LORD) - GREEN - small acquisition of a loss-making timber merchant, Alloway Timber. The strategy seems to be buying up independent builders merchants at modest prices (eg retirement sales), then improving margins, and other synergies, which makes a lot of sense to me. Checking my previous notes, I was GREEN on Lords in both May & June this year - solid trading, cheap valuation. Only negatives are obvious macro worries, and founder shareholding is too dominant.
CentralNic (LON:CNIC) - also announces a tiny acquisition, on what seems like a cheap EBITDA multiple.
Paul’s Section:
Superdry (LON:SDRY)
56p (suspended temporarily) £55m - Results FY 4/2023 - Paul - RED - (suspension should be lifted this afternoon, CFO said on webinar today)
The precise period is the 52 weeks to 29 April 2023, but I’ll call it FY 4/2023.
Just a few quick comments before I get “Dunkertoned” on the 10:30 InvestorMeetCompany presentation.
Good news -
The Far East IP sale completed, with funds received, in May 2023. Why on earth wasn’t this announced by RNS? It should have been, as the silence naturally led me (and others) to conclude that the deal might fall through. A silly own goal there. It’s highly material, pumping in cash of c.£35m in net proceeds onto the post year-end balance sheet, so this is a big positive I think, as it provides a lifeline to prop up the business in the short term anyway. In negotiations for possible additional IP sales internationally.
Cost savings of £35m are being implemented. Seems a huge amount, so I’d like to know what these costs are, and if there are cash costs involved up-front?
Bad news - everything else basically! In particular -
Loss-making for FY 4/2023 - adj PBT of £(21.7)m loss, vs LY profit of £21.6m
Statutory loss after tax is huge at £(148m), but that includes a large tax charge, so the statutory LBT is £78.5m. The main culprit is a big provision for onerous leases.
Lease entries on the balance sheet are probably the worst I can remember seeing for any retailer - RoU assets are only £48.5m. But the corresponding rent liabilities are £60.5m current, plus £127.6m non-current. This is telling us that SDRY has a massive problem, with many, probably most of its physical shops now loss-making. Hardly surprising, given that gross margins are falling, but it will be having to pay staff considerably more. Retail sales did rebound in FY 4/2023, but are now dropping again (in Q1). Wholesale is also a major problem, but at least costs there are mainly variable. Rents are fixed until the next rent review or break clause, when they do drop a lot.
Current trading - no respite here. Q1 sees store revenues down 3.7%, online down, and wholesale down a really alarming -50%. It says this is -30% underlying, due to timing differences, and is influenced by exit from USA. Even so, it’s dismal, meaning that I think losses are likely to worsen considerably in FY 4/2024.
Going concern - contains a "material uncertainty" waring, so read this statement carefully, which confirms the risk.
Paul’s view - I think this is probably likely to go bust in 2024. Unless a genuine and significant turnaround is implemented (instead of it all being talk of a brand reset, to date). I'm listening to the IMC now, so will see if anything new emerges from that. So far, they're being pretty straight, admitting how tough things are, and liquidity having been a challenge, 8 minutes in. There's clearly some value left in the brand, as the £35m cash from selling the brand in the Far East confirms. But it's a race to stem the losses, before it runs out of cash I think. Why get involved? Although it could be a nice share to trade in & out of, for bounces after big plunges. So one for traders only I think. Tenacious management, that's for sure, highly motivated. Can they save it though? I'd be surprised, but it's a possibility.
Totally (LON:TLY)
Down 12% to 9.4p (£19m) - AGM Statement - Paul - AMBER/RED
Today’s update mentions various negative factors, but doesn’t seem to be a profit warning, as the final sentence says -
The Board's outlook for the current financial year [Paul: FY 3/2024] remains consistent with that communicated alongside the full year results of the Company in July 2023.
But this doesn’t fill me with confidence -
"We continue to work within a challenging operating environment alongside the NHS in crisis. The cost of agency staff required to deliver safe services for patients exceeds our anticipated forecasts and many decisions related to the awarding of new contracts are currently on hold.
…we are actively implementing strategies to streamline our operations and to align them with a smaller overhead base which more readily reflects the current contract requirement.
"The Board remains confident in the medium to long term prospects of the business and will ensure that future contract opportunities continue to be pursued and all contracts are managed effectively to support the achievement of Totally's goals.
Paul’s opinion - a fairly negative-sounding update, hence shares have dropped 12% this morning in early trades, which seems a sensible reaction to me.
I’ve not seen any broker updates yet. TLY has form for sounding chirpy in its updates, then slipping out lowered forecasts via broker notes, as it did on 10 July. Therefore I don't particularly trust the company’s commentary. Indeed today’s sounds contradictory, mentioning negative factors like higher contractor costs, and new contracts on hold, whilst saying no change to guidance, which doesn’t make sense to me. It sounds as if another profit warning could be gestating, so I’m not tempted to bottom fish, despite the share price having fallen a lot.
Fundamentally is this business any good? I’m not sure, but previously gave it the benefit of the doubt, being amber from Dec 2022 to 22 May 2023, but my patience ran out on the profit warning of 10 July, where I shifted to AMBER/RED. I’ll keep that view today, although I’m inching towards just going fully red on it.
The fundamental problem with TLY, is that it’s doing quite big, low margin contracts for the NHS, but seems to have a fair bit of risk within those contracts - both cost over-runs, and uncertainty over renewal. I’m therefore coming to the conclusion that it’s really not a very good business, with not much visibility over future profits.
As a short term trade, there might be a bounce in the share price at some stage though.
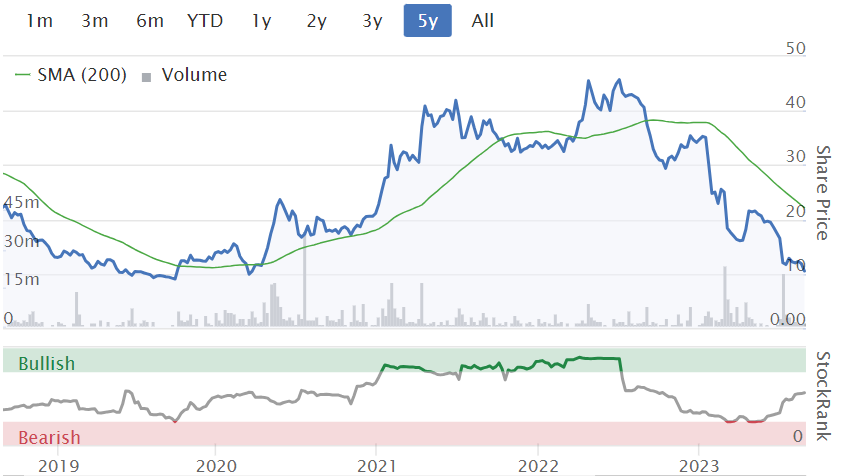
Shares found a floor around the current price of 10p pre-pandemic, but bear in mind that since then the share count has quadrupled! So drawing lines on the chart isn't comparing like with like at all.
Another problem in the current, illiquid bear market for micro caps, is that companies which under-perform like this one, could have a huge overhang of institutional shareholders who would like to sell, but can't, as there aren't any buyers. That can lead to a share price in perpetual decline, punctuated with the occasional sharp rally, that sellers quickly snuff out. The 5-year chart below very much confirms that is probably the case here.
It also means that the funding window has been slammed shut for a while, so the market isn't performing its function of providing cash for expansion (unless there's a really compelling story), and if they run out of cash, they're in big trouble.
Accsys Technologies (LON:AXS)
Down 24% to 74p (£162m) - Trading Update - Paul - AMBER/RED
As you can see from the 12 month chart below, AXS shares seemed to form a nice base, and then put in a strong rally. That’s gone wrong today unfortunately, with a trading update that has displeased the market.

This is the company that’s been developing high performance wood products, with seemingly strong demand, but never-ending production delays and problems.
Here’s a summary of today’s update -
“Strong start” to FY 3/2024 (Apr, May, Jun, Jul) - revenues & volumes both up.
Weakening customer demand, blamed on macro factors & destocking.
Mgt taking “immediate & decisive steps” to reduce costs & optimise working capital.
Trying to stimulate demand.
New Kingsport plant should commence in mid-2024 not very helpful timing, to be increasing production when demand is falling.
Profit warning - FY 3/2024 revenues will be below expectations, and EBITDA significantly below expectations.
Outlook -
Challenging trading conditions are expected to persist at least until the second half of the 2024 calendar year.
Paul’s opinion - I seem to recall that the products Accsys makes are quite high end, high spec stuff, eg for architect designed buildings (I could be wrong on that, so do correct me if so). Hence given macro factors, especially much higher interest rates, and housebuilders saying demand is well down, it’s unsurprising that Accsys is also seeing reduced demand.
This share definitely fits into the too complicated category.
It’s a pity, as it’s FY 3/2023 results looked good, in a breakthrough year for profitability.
However, on checking its 3/2023 balance sheet, I’m not happy - there’s far too much debt, which doesn’t sit comfortably with a profit warning today, and no signs of a trading improvement likely for about a year. For that reason, I’m marking down my view of this share from amber, to AMBER/RED - indicating that I see signs of some possible financial distress. It did an equity raise in 2022, and I think it might need another placing, but that depends whether the main lender ABN Amro is co-operative or not, and what the bank covenants are - all essential research. I’m just going to avoid it altogether - why get involved?
This update is further evidence, I think, that it's probably best to steer clear of anything construction-related for the time being, with a recovery seemingly pushed out into H2 2024, and all the signs seem to me pointing towards things getting significantly more difficult in the sector generally - which is what we should expect when interest rates have been hiked so much, after 15 years at near-zero.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
Are you sure about the big pension deficit in Renold? Pension deficits have been reducing substantially recently due principally to the rise in bond yields, thereby reducing the cost of meeting the liabilities.
Are you sure about the big pension deficit in Renold?
Most pension schemes have also seen large asset losses, as they were mainly invested in bonds. So theoretical liabilities have fallen due to discount rates falling, even though the actual liabilities have risen.
So this is a key area of uncertainty, and most schemes still require big cash deficit contributions, even when they show an (artificial) accounting surplus.
So it needs very careful research, on a company specific basis. Don't just assume pension deficits have vanished.
you also need to consider how much LDI matching each scheme has done as this portion, if managed correctly, will also not benefit from rate changes.
you have to do specific research on the company and each of its various schemes unfortunately and it can be quite complex.
https://www.bbc.co.uk/news/bus...The UK economy made a stronger recovery during Covid at the end of 2021 than previously estimated, according to sharply revised official figures.
Data now shows that the economy grew by 0.6% in the final three months of 2021, rather than shrinking by 1.2%.
Seems these estimates require a lot of guessing and a long wait for the Actual.
Exactly right jon. Could easily find in a years time we are in a recession now or things might be much better, they're just guessing. Think it was 1987 or 88 when the recession was finally announced months or a year after it actually happened. By then the markets were way up.
I think I managed to get through the whole of August without reading or watching any financial news (opinions really) and its no loss at all.
So a simple question on income sustainability as thinking about my mum's portfolio this afternoon as you might have guessed.
If I look at the likes of RM Infrastructure Income (LON:RMII) GCP Infrastructure Investments (LON:GCP) GCP Asset Backed Income Fund (LON:GABI) all of which are offering a good headline income level, reasonable discount to declared asset value...but
When you look at the basic numbers, the income is not covered by current earnings not the future forecast, and there is net debt on the balance sheet not cash, so where is the dividend coming from in the future?
Whereas say Phoenix group (LON:PHNX) as an example, putting 2021 and 2022 down as shockers, net cash and this years and next years dividend is covered, ok not great cover but covered.
Is there something obvious that I am missing on these infrastructure funds?
Thank you
Tommy
I would say the devil is in the details.
If the debt is long term, fixed rate (at a very low rate) and their revenues are inflation-linked and long contracts, then it might be attractive. But this won't be apparent just looking at the headline numbers for the last few reporting seasons.
However, many infrastructure / real estate funds might be exposed - either short term debt that needs refi soon, floating rate. Short contracts, inadequate revenue increase mechanisms.
Some of them - they're no longer the "stable" investments that they were in a benign and steady interest rate environment. I think investors may have yet to wake up to this, and we probably need to see one or two blow up spectacularly before it sinks in to the market.
Thank you Boon
I am getting that niggling feeling about a few things, such as energy generation, great when prices going up, government policy based on the worst spot price and everyone else getting out a big rake to enjoy...
I have held the infrastructure in the past, and still have a couple of small holdings, but just getting nervous that there will suddenly be a "Crunch", the fact that many are talking about being too small, amalgamation to return cash and such like...someone knows something more than I do.
Cheers
Tommy
Indeed. And the problem with a highly regulated, lightning rod industry like energy is that politicians can easily use it as a scapegoat when they need to drum up popular support.
Look at Drax (LON:DRX) - made a financial killing last 2 years with the high energy prices. Now facing pressures politically, especially around biomass, and them benefitting while energy bills are sky high. Share price has dropped like a stone on the uncertainty.
I think the likes of Gresham House Energy Storage Fund (LON:GRID) is a big risk for political focus. They also made a massive killing in the last 1-2 years. All legal of course - all within the contractual terms with national grid, etc. Maybe the SP weakness currently is already pricing this in?
I think the likes of Gresham House Energy Storage Fund (LON:GRID) is a big risk for political focus. They also made a massive killing in the last 1-2 years. All legal of course - all within the contractual terms with national grid, etc. Maybe the SP weakness currently is already pricing this in?
I think the analogy with Drax (LON:DRX) isn't particularly useful - the problem there is the whole question of whether the biomass in question is actually sustainable at all. There's an Ofgen review into this and if they find against Drax then not only are future subsidies in question but past ones might need to be repaid.
Still, there's no doubt that there's going to be reform to renewable energy pricing - that's part of what REMA is about. However, the stated goal of ...
"...reforming the capacity market so that it increases the participation of low carbon flexibility technologies, such as electricity storage, that enable a cleaner, lower cost system."
https://www.gov.uk/government/...
... doesn't particuarly sound ominious for GRID and its cohorts in the short-term.
Generally, though, most infrastructure funds have seen their share prices slashed and discounts to NAV rise in line with rising interest rates - as discount rates rise the projected future returns get reduced while investors require higher dividends to compensate for the risk, when the risk free asset becomes cheaper. At some point that will at least partially reverse.
Investing in renewables is a bit of a minefield, frankly, but pure play energy storage companies are probably the safest way to do it. Of the three trading in the UK probably Harmony Energy Income Trust (LON:HEIT) is the best value right now - but this isn't going to be a short term trade however you look at it.
Generally, though, there's lots of value in infrastructure funds right across the board.
timarr
Not sure if you're referring to Stocko data here, but things like earnings and dividend cover don't really work or indeed even apply for investment trusts, nor life insurance companies for that matter. It's a case of going to the source I'm afraid and digging through the company accounts - that's the only way to get a sense of how secure the dividend is.
In the case of Phoenix group (LON:PHNX) the company is expected to through off shed loads of cash from its life book which should comfortably cover the dividend for foreseeable future. Don't think these cashflows are treated as earnings as such, so this probably won't be reflected on Stocko data.
Hi Bouden
I start with the Stocko numbers as my basic do I go and look for more, or do I just say no, or too complicated, the joys of being an Engineer not an Acccountant by trade.
Thanks
Tommy
Just to say thanks for all the Spirograph diagrams today, I really wish I could make head or tail of them. Maybe Stocko needs to put a Spiro for dummies video up. Didn't Ed promise or canvass one some time ago, albeit it at a charge?
MS International (LON:MSI) must be decent news if they're RNSing it
CONTRACT TO MAINTAIN THE MSI-DS 30mm WEAPON SYSTEM FOR THE US NAVY
The Company is pleased to announce that a maintenance contract has been awarded by the United States Navy ('NAVSEA') to our wholly owned subsidiary company, MSI-Defence Systems US LLC, which is based in Rock Hill, South Carolina, USA.
The contract is on a sole source basis for the procurement of supplies and services to maintain the US Navy Mk38 MOD4 weapon system (which is the US Navy nomenclature for our MSI-DS 30mm naval weapon system). The contract commences with immediate effect, with a budget ceiling of $49.8 million over the period to 30th June 2028.
In the Company's annual financial report for the year ended 30 April 2023, the Chairman, Michael Bell, stated "Regarding the ongoing opportunities in the US, we cautiously believe that we are well placed to be awarded a contract to supply our MSI-DS 30mm naval weapon system to the US Navy."
The Company has yet to be awarded a production and supply contract related to the US Navy Mk38 MOD4 weapon system but the awarding of this maintenance supply and service contract substantially increases our confidence that we shall also be awarded such a production contract from "NAVSEA", shortly.
Very good MS International (LON:MSI) news just now. Clearly releasing on signature which is what you’re supposed to do!
This bodes very well for that division and EPS growth going forward.
Given earnings (absolute and growth) plus the net cash position and quality of client base the current share price looks well under baked to me. But then I hold so maybe I’m biased.
I agree, very good. It's a pity more companies dont RNS when signed rather than airy fairy possible future contracts.
Shooting up.
Very illiquid - tends to go up in steps so wouldn’t surprise me to see it hit £8-9 off back of this and then drift back a bit over few weeks as people get bored waiting for next announcement and settle in the 700’s. Has taken that path from about 200p.
I think 100p+ Eps on this is not far away so be disappointed not to see £15+ share price (PER of 13 + £1-2 net cash) though who knows. My crystal ball appears to have snowflakes floating around in it atm!!!!! :D
Thanks! Sorry the news from MS International (LON:MSI) (I hold) missed the cut-off for today's SCVR, as I was busy getting my daily 10k steps up Essex Road (N1). So a nice surprise, when I sat down for a coffee and carrot cake at Angel! :-) Debits and Credits, as they taught me, have to balance! We looked at MSI here earlier this year, looks intriguing I think (I hold).
Reminds me a little of Avesco - retirement sale, maximising hidden value over several years in advance, possibly? That one was a low-risk 6-bagger, but we had to be very patient.
Re Volex (LON:VLX) Continued confidence shown by the directors with some buys yesterday.
30-Aug-23
Volex
VLX
Murillo,Amelia
504 @ 2.85p
£1,435.90
30-Aug-23
Volex
VLX
Rothschild,Nathaniel
409,391 @ 2.85p
£1,166,354.95
30-Aug-23
Volex
VLX
Westmacott,Peter
16 @ 2.85p
£45.58
45 quid is perhaps not such a show of confidence but maybe Mr Westmacott is just not quite as wealthy as Mr Rothschild???
They were scrip dividend purchases,(i.e. receiving shares in lieu of a cash dividend), it shows how large Mr Rothschilds holding is .
44,859,906 as far as I can make out Hevellyn. I hold a few, just over half of those last 3 digits.
Volex (LON:VLX)
No, the directors did not buy to show confidence - this was automatic as a result of them being signed up to the scrip dividend scheme and so the numbers were proportional to their holdings on the record day.
Please do not have a go at Sir Peter. A lot of non-executive directors in other companies are there for the ride or to make up numbers. However I suspect that Sir Peter has been absolutely key to the Murat Ticaret acquisition (completion announced today) as well as the integration of De-Ka Elektroteknik Sanayi ve Ticaret Anonim Şirketi (his appointment to the board was announced on the same day as that acquisition). He was HM Ambassador to Turkey and is fluent in Turkish.
Noticeable that some of 2022 big winners, mostly defensive plays have or look like rolling over into stage 4 downtrends. May just be a temporary thing but looks like a rotation into more cyclical businesses
H & T (LON:HAT)
Telecom Plus (LON:TEP)
Bloomsbury Publishing (LON:BMY)
Hi Wolf
I am trying to get better at the Stage 1 to 4 thingy, I read Michael Taylors free books again whilst on holiday, is there any other reading that can be shared as a starting point?
So holding Legal & General (LON:LGEN) within a couple of the family portfolios, so classic trader this would be "Stage 4" since March 2023, but as a income e.g. Mum's ISA (aka pension for an 81 year old) this would be a starting to become a buy more and take the 9+% yield on offer...
Sorry what is the question.
Simple one is assume this is Stage 4 if you put the magic lines on it?
Then I make the decision on "long term income holding just sit tight", "long term hold, watch and add more when gets to something like a Stage 1" or "sell and buy back further down the ladder if it still passes the tests".
Obviously this does still fit in the buy high, sell low strategy, but not yet in the second part of the strategy of buy even higher, then sell even lower.
Cheers
Tommy
Tommy I'd go straight to the main man here. It's no magic bullet but its useful to step back, you'll see trends/cycles repeat every few years. Americans have the advantage of thousands of stocks to choose from but same principles everywhere.
Thank you!
A whole load of companies due to give updates in the next 3-4 weeks, its been interesting to see which have held up 2nd half of August in what was a pretty awful month. Some profit warnings are being used as a buying opportunity. Eneraqua Technologies (LON:ETP) for instance was down 35% I think at one point, but rallied back to almost break even in 2 days
Housebuilders looked wobbly 2 weeks ago but theyve held up OK considering. Higher lows still in place
Things like Saga (LON:SAGA) looking better. First time in 1.5 years the 200d m. average has turned up. Doesnt mean it'll hold of course but its at least going in the right direction.
J D Wetherspoon (LON:JDW) with a lesser-spotted cup + handle, bounced off the 200d from August pullback.
Plenty others showing some tentative strength. And for straw graspers like me the AIM All share has a RSI divergence. Could be a big month coming up.
Eneraqua Technologies (LON:ETP) back up past where it was pre profit warning yesterday.
Crazy market, not complaining mind, 70p was a nice price yesterday
Its exactly what youd want to see near a market bottom newinvestor. At the top good news won't have the same effect as it did previously. The same in reverse is true at the bottom. Not to say some unexpected bad news won't set the markets back again but for me it's a good sign. Some people were extremely negative during August, which again is a good contrarian sign.
Sorry I didn't get around to looking at Eneraqua Technologies (LON:ETP) - violent movements up & down, well done to any traders who made the most of it!
Some comments on the @Volex acquisition... I've mentioned this before but worth sharing again.
I've worked directly with volex in the past, as part of the electrical/electronic development team for a large OEM.
They were always very good to work with, but at the time had very long lead times as parts were shipped from China by boat. i.e. if you had a urgent change, it was very difficult to get updated parts quickly... typically 10 weeks or so lead time. But they did provide on-site support and almost a co-design approach to ensure issues were minimised.
They were replaced by a competitor, who effectively implemented whatever designs they were given, warts and all, with very little filtering, questioning, or suggestions on how to optimise the design. Despite the long lead times (which may now have been addressed - I'd need to check), Volex were much better to work with.
Murat seem a perfect fit, as their cables were, and still are, used on the vehicles in specific areas e.g. Battery cables.
With the acquisition of Murat, Volex have taken over a well-known cable supplier within the industry and it will give them access / engagement to a wide range of off-highway OEMs, which I expect they will leverage to set up sales meetings and promote other products in their portfolio.
Paul says - "Shares found a floor around the current price of 10p pre-pandemic, but bear in mind that since then the share count has quadrupled! So drawing lines on the chart isn't comparing like with like at all."
I think we can all see youre wrong on this Mr Scott.
Totally (LON:TLY)
I don't see, and I'm sure "we all" don't see from your chart how Paul's conclusion of not comparing like with like is wrong. Your chart tells me nothing other than you started in the wrong place. I remember it well as I moved house in 2019 so Pauls pre pandemic year being 2018 seems valid. The number of shares was 51M then and in 2023 it is shown as 194M. I also note that EPS was 3.54p falling to .9p so a chart that today shows a price equal to what it was 4 years ago is as much use as a chocolate teapot.
Haha, on reflection you're correct.
So pleased we now agree. I've got a headache looking at that chart :-)
It looked like a slam-dunk to me so I quickly moved on. Comments make sense now
Hilarious chart!! :-D Gave me a belly laugh! (rolls!!!). I have no idea what the replies mean! Do they realise it's a joke? Are they doubling down on a joke that has gone over my head? Who can say?
Ha, I thought it was a simple, witty little joke Paul....but then it got weird :-)
I thought the chart was hilarious. It reminds me of what my ftse chart looks like sometimes after having 15 years of trading the ftse. Though I do delete the odd line now and then!
Anybody following B.P. Marsh & Partners (LON:BPM) ? Has been a great investment for me until past month losing 10% - wondering if I should cut losses or hold on... any insight very helpful.
stockorocko,
1) BP Marsh regularly grows it's NAV. Currently 516p, (according to the last announcement) so up over 50% in last five years. Currently on a near 30% discount.
2) It has not been rerated. i.e. if the share price performance was because it had gone from a 30% discount to NAV to a 30% premium, then it might be worth selling.
3) The Company is buying back shares at a discount to NAV thus enhancing NAV to shareholders.
4) Look at the chart and compare it to, say the FTSE250 (MCX) over any time period. It is a consistent outperformer.
I used to hold, stupidly sold, can't remember why.
Seems to me, a good quality, long term outperformer, at a reasonable price. So unless you need the cash, why not just keep holding?
Best of luck whatever you do.
Chris
wow thank you! that is much appreciated. I will hold!
I bought B P Marsh some years ago I paid 98p for my first tranche I have increased my holding several times on pullbacks I have also worked in the industry which makes “March” easier for me to follow
The company has put together a first class management team that has and in my opinion continues to deliver I am a buy and hold long term investor I think that the current price offer a good entry point
thank you - great too to have the industry knowledge.
B.P. Marsh & Partners (LON:BPM)
I am slightly annoyed at myself that i didnt get around to selling at the recent peak - the fact the shares got where they did eluded me.
I wander if its no coincidence that the max price they were buying back shares was 420p so perhaps that level was some sort of cieling.
I have noticed though that there has been a hatchet taken to eps estimates for this year and next - i am guessing that cant help.
Not sure excatly what the hatchet was for - all i can guess is that with the large business sale they had expectations are that earnings will be lower short term . In some respects its not all bad if that money is sat in the bank earning decent interest.
At 365p i make it that company is trading at 72% of latest published asset value so i will be continuing to hold at current prices.
I bought into Renold because the new management team had a clear vision for the company which focussed on getting rid of unnecessary cost and enforcing price rises. The team have been successful and therefore I feel I must continue to support them as they try to draw together through acquisition a global offering within the chain industry. They state the acquisition will immediately enhance earnings per share and be accretive to the groups operating margin. All sounds good but I cannot help but feel nervous when management teams build their business through acquisition. I am sure we have all heard of the famous JPMorgan study which identified acquisitions are often more about egos than the bottom line. I suppose what I am really saying is I was happy with the progress being made not sure we need these distractions.
I think those reservations about Renold (LON:RNO) are fair but I think the risks associated with smaller bolt-on type acquisitions are imo lower than bigger platform type ones. Also that without acquisitions I don’t see how the size of both the pension scheme and central overheads can be diluted down any time soon, so as a strategy it makes sense to me. Good acquisition integration is important though for sure. The capital markets day presentation on their website is worth a watch for anyone with 2 hours to kill.
Frasers ups Boohoo (LON:BOO) stake to over 10%. Wonder what Ashley's end game is?
Making a monopoly of the high street and internet and then setting his own prices?
He sees a bargain. Boohoo is a steal at the price
2 massive egos - Mike Ashley and Kamani at BOO - they'll fight over it all, just don't expect small shareholders to be the winners.
Really off topic but let's talk Tesla (NSQ:TSLA) my biggest and best performing share by far this year, rescued my pf tbf.
Marmite I guess but what a company. I'm pretty sure it will be the biggest company in the world within a few years.
New Model 3 launched today looks epic, Cyber Truck roll out this Month, plus FSD is almost solved, V12 using AI.
Exciting company for sure
Yes, definitely an exciting company. But should it’s market cap be more than Toyota+BMW+VW+Mercedes+Honda+Ferrari+ford+GM, etc,etc combined? Any advantage they had is disappearing fast.
Good Bear point for sure. I'd say yes. They are the Apple of the car/energy world. A forecast/target of 50% compound annual growth, up to 2030, sometimes a bit more, sometimes a bit less. All profits going back in to achieve these targets. Worth a deep dive.
Just came up on my news alert funnily enough https://www.stockopedia.com/share-prices/tesla-NSQ:TSLA/news/buz-zapos-turbulent-landing-aheadapos-renault-falls-on-ubs-downgrade-urn:newsml:reuters.com:20230901:nL8N3AD18J
Yes. Look at growth rates, debt levels and Tesla are not just a car company - they are spending $2billion per year on compute to train their AI.
I am also a holder and have been for a few years. It has been a rollercoaster!
This company is often mistaken that it is just about the cars, but the Energy storage, Full Self Driving (FSD), make this company a very interesting mix. I would say that FSD is far from being solved, it is in a continuous improvement process (forever BETA :) ) But the recent leap forward with changing large chunks of the code to use more neural nets, will see a significant processing speed increase.
Also good to hear this week, that their recent large purchase of Nvidia GPUs has boosted the processing power for their AI training facilities for FSD. Oh and yes the new Model 3 not only looks great, but great progress to not only improve technical performance but also manufacturing cost savings.
There is always alot going on with Tesla (NSQ:TSLA) !
Good Morning Elon ;-))
Good point, can't talk Tesla without Elon. I've followed him for years, and got talked out of buying Tesla when the MC was about $25 billion. My partner hated him since he called the cave diving guy a paedo.
Still happy holder now, I took advantage of the drop at the start of the year
The big problem now is that Tesla (and other EV manufacturers) are creating a problem down the road for themselves.
By slashing prices so quickly, they're going to spook the leasing market to not stock their models. Leasing companies heavily depend on residual values (after 24m, 36m) for their profitability. If you don't know how much Tesla is going to slash the price of its new cars over the next 36 months, you are taking a big gamble as a leasing company.
Also, private owners are going to wake up to the fact that their Teslas will depreciate much quicker in the first few years than they originally thought. Doesn't concern buyers who plan to "hold to maturity" (to borrow a term from the bond markets) but for most drivers that are "traders" (anything from 2 years to 10 years usage) this is a big consideration. Or should be. If buyers are financially astute.
Already we have seen used car dealers waking up already to this, and being very cautious about buying and stocking used EVs. If dealers en-masse stop buying nearly new EVs, you can't see this ending well for new EV sales, given the deluge of negative press to come about owners being stuck with cars they can't sell.
It's a dangerous game Tesla is playing. Juicing short term sales, and strategically trying to whittle down the competition. But the bullwhip effect will come back in a year or two...
Their mission statement is really simple “to accelerate the world's transition to sustainable energy.”
To do this they need scale, to do that they need a fantastic product that holds its value, brand recognition etc. The Model 3 for example holds its value really well, with over air updates the car actually gets better over time, the updated version looks an exceptional car. The Model Y has been the world’s bestselling new vehicle of 2023, any car, not just electric.
All car companies discount but Tesla is naked, as it's all B2C and the same price for everyone (as soon as MSM pick up a discount they are all over it with Tesla). It's done away with haggling, dealerships playing with the margins etc that you usually get at car dealerships.
Completely agree on Tesla, likely to be the largest company in the world within 5 years as they are miles ahead of the competition in cars, their energy storage business is growing over 200% (and will eventually be bigger than auto in sales and margin) version 12 of full self driving appears the real deal and will only improve being trained on $2 billion worth of compute power. Not to mention cyber truck
* I Hold! Largest position
they are miles ahead of the competition in cars
Compared to the quality German quartet, sitting in a Tesla is like sitting in a waiting room in a pre-fall-of-the-wall Bulgarian dental surgery. Amongst electric competitors, Taycan and BMW iX are several generations ahead in comfort and finish.
"Amongst electric competitors, Taycan and BMW iX are several generations ahead in comfort and finish."
I dont think anyone would disagree with you there particulalry - where Tesla do excel is at the engineering level with regard to how they put their cars together with regard to quality of tech and overall planning of how to build an efficient car. Look at a few of Sandy Munro videos to get an idea of how far ahead they are in the areas that matter (that gap might start to close at some stage i must admit) . One might expect finishing quality to catch up with the others eventually but the proof of the pudding is the fact that they sell the volume they do despite their finishing touches often being mocked.
Well done on picking Tesla (NSQ:TSLA), one of the mangificent 7 - its certainly been a fantastic journey of late and you will probably have out-performed anything in the UK!
Tesla is definitely Marmite - personally, I think its still ludicrously valued in a very competitive industry with no real long-term winners...>5x BMW enterprise value is crazy! + that's for a car with poor build quality, bland looks and no speedometer or controls in the line of sight which is a major safety hazard (with drivers playing with their screen whilst they are driving along)...haven't they heard of a standard heads-up-display?! You can tell I don't like Tesla's...but, to be fair, I can see why many people do like them and Elon Musk should never be under-estimated. What he has done at SpaceX is even more impressive than Tesla.
The major threat to all the automotive companies in the West, in my view, is China dumping millions of cheap EVs which will massively lower prices and profitability. There are about 20 new Chinese companies entering the UK market in the next year or two.
Just curious have you driven a Tesla recently? Agree that the build quality wasnt great 5+ years ago but my new Model Y is by far the best car I have ever driven and the tech inside it is amazing.
This is how sad I just got. I've just put a picture of the new model 3 on my office wall, a red one. Motivation as this will be my next car in 2 Years or so.
Topvest - I think you’ve understated some of the major threats to Tesla going forward. The number of investigations opening up against them is increasing, their sales are struggling, inventories are increasing and the basic question in my mind is: how can Tesla have such superior margins? Are they producing in low cost locations? (Austin and Germany not so, China yes), do they have any revolutionary production process? Are they experts at it compared to decades of experience of someone like Toyota - nope. Are they being cheap and economical with their components - yes. Do they build their own battery tech? No.
History teaches us that when something seems too good to be true, it almost universally is. So called stock market pundits central tenets are that Tesla can withstand a price war because its margins are high. What if the margins aren’t real? What if their accounting is riddled with errors and lies?
Tesla fandom will brush off all these comments. They’ll ignore all the evidence out there that says their autonomous driving doesn’t work. That it can be done with cameras alone (with no perception of depth).They’ll believe anything that comes out of Elon’s mouth is true. They’ll believe the cyber truck can be produced at a profit, they’ll believe that the competition won’t catch up etc etc.
Yes I’m sure you can make money trading Tesla. Would I trust Musk with a penny or a dime of my money? No way. He’s a serial liar, of questionable morals, a criminal (he was fined by the SEC and barred from being chairman, so yes he’s a criminal - i.e. guilty of a crime) and his troubles are only just beginning as asleep-at-the-wheel regulators have finally woken up and seen the mounting evidence of issues and started investigations.
The worst thing about the whole Tesla scandal- which I believe it will become - is the number of participants supporting it. Absolute charlatans like Cathie Wood, Keith Fitz Gerald etc, they’re all out there to fleece investors from their funds and drive up their fees.
So please, anyone out there who’s investing long term in Tesla - just have your wits about you and question the assumptions that many have made and assumed to be fact.
Now there is the Bear case :)
None of those points worry me tbf, and I have looked very closely into each one. There has been more FUD written about Tesla than any other company, for many reasons but predominantly as they are driving the EV revolution against big oil, they don't advertise and there is always plenty of short sellers in looking for the bear case.
I'm V comfortable with 40% of my pf in Tesla (NSQ:TSLA) Let's see where we are in 5 years though, you are right it's a risky strategy but it works for Buffet.
This one is a perfect example, the SEC looking into Tesla misappropriation of funds to build Musk a glass house!
I mean come on now, surely they must know someone is feeding them rubbish, so funny!
https://www.cnbc.com/2023/08/3...
I’m going to stick with my old landie, to much tech to go wrong in these techie cars. And what if they give up doing updates on your model when they want to sell you the next… or go out of business? What do you need your car for, me I just like to get from A-B. Nothing fancy and easy fixes.
As its Saturday please forgive my digression - but I'll end with a genuine automotive investment question.......
'I’m going to stick with my old landie,'
Well good on you. I'll join you there. I claim to have paid £800 for the capstan winch. The landrover came free. That was decades ago. I hear capstan winches are much more expensive now, especially with a SII LWB 1960 ex BBC outside broadcast wagon attached. Cheapest vehicle ever and never goes wrong. As long as I don't use it mind :-) Zero emissions as well! As long as you don't count my exhaled swearing underneath it. And I like to consider the fact that I help to keep a myriad of small UK parts firms profitable while I'm at it :-)
I fully expect that by the time they put me into a nursing home, I'll be able to buy/lease/book a self driving shopping trolley that will pick me up outside the front doors, take me to the pub. And then deliver me back to the home.
Which leaves me with a quandary. What to do with all the landrovers? Oh yes. You see 1 old landrover isn't rational. But having more does help :-) Preferably one for each day of the week? Anyway I could put a battery in? Or run it on Scotch when the petrol runs out? But that would be a waste of whisky?
Despite my fascination with the UK automotive industry I've never been tempted to invest in auto makers. If owning old British cars is a way to rip up £20 notes, then it strikes me that owning the manufacturers has mainly been a way to rip them up faster?
The founder of Renishaw (LON:RSW) seems to have acquired the habit with the McMurtry Speirling .... https://mcmurtry.com/speirling...
Always fancied Ricardo (LON:RCDO) for a picks and shovels automotive engineer, but never quite got there yet. Looking cheaper now. But so is everything else.
A bit above the SCVR and well above my usual levels - but Dowlais (LON:DWL) (ex GKN and MRO spin out) has piqued my interest. Why so cheap on Tangible book value at 0.3x price? And is Arthur Keen happy or spinning in his grave at the moment? I may just have to do some research here. Any fans of Dowlais here?
cheers
Mark
Camellia CAM
I took a starter position in this couple months bsck after stocko reviewed it .
Seems a relatively poor company totally at the mercy of commodity prices (avocados / macadamia nuts etc) which is not great
But absolutely stuffed with legacy non core assets that I susiect are on book at significant under valuation .
Also seems to have a very conservative CFO who has stuffed through very high provisions that he can then release at this mercy to give better headline numbers .
EG today a provision release of circa 18 million makes a 12 million loss into a 6 million profit (or thereabouts) .
I’m torn on this though now leaning towards this is a “special situation” with management now committed to realising non core understated assets .
Given company is at around 50% of asset value and given the CFO seems to have provisioned / written off a lot of stuff which can magically be “released” when needed .
I remember when I recruited my first good CFO he insisted on provisioning our stock and we had a 1.5 million provision which in that first year gave us a rubbish headline number but whenever we sold that “obsolete provisioned stock” effectively 100% profit after back .
I think his rule was
- over 2 years 100% provision
- 1 year 75%
- 6 months 25%
Bizarrely when we announced a huge drop in profits the first year of the new accounting policy we got hammered
None of our competitors were doing this and their stock was always overstated, ours was probably understated due to that being agressive write downs but for 100% sure better to be overstated than understated .
I always asked about provision policy in trading companies
Could not agree more. Writing down obsolete stock properly gives the “incentive” to move it on and deal with the underlying problem, refusing to provision gives the incentive to hide it until the next management team “discovers” it, exacerbating the problem.
I too was attracted by the hidden assets on the Camellia (LON:CAM) balance sheet, and started a position a month or two ago.
The bear points are clear - they seem to have very weak operational management in their agricultural businesses, with problem after problem, declining profit margins, etc. However, I somewhat suspect that the sustained prince inflation in food commodities we will see means there is now some light at the end of the tunnel, from a macro perspective. Sure, labour costs will rise too, but as their operations are based in countries with weak labour laws (and this may prevent some from investing in CAM), they should be able to generate a good margin.
Annoying that the BF&M sale has not been completed / finalised, with a hiccup. And also, their property sales (of which one they are looking to fetch £32m+ gross) is not completed yet, and likely to meander given the poor state of the UK property market currently.
But if this company can be run well, a diversified food grower, both in terms of crops and geographically, is somewhat of an interesting play. Especially given that it is trading at more than 50% discount to TNAV.
I'm going to do a bit more of why I invested in Camellia in my next Boon Fund post.
(I hold in the Boon Fund)
Interesting that the price of macadamia nuts is down 50%
Yet in uk high street prices are as high as ever !
Sold out of Camelia today
Decided as still a small position couldn’t be bothered to do the journey .
Also sold all Titon holdings as I think there are sone weird family shareholder string pulling / control not necessarily in shareholder interests .
Easy company to turnaround Titon but only with new management not historic family fortunes .
Actually needed a big chunk of cash out so also trimmed 10% in vertu
Feels good to have a bit of cash !
Superdry (LON:SDRY) "The good news is that despite the external turbulence, the brand is in sound health and has momentum.".
Its certainly got momentum, just not in the direction Julian thinks.
Frasers not on the big holders list. Wonder if Ashley will muscle in Superdry (LON:SDRY)
Ashley's MO is to wait for them to go bust and buy ALL the stock from liquidator for peanuts.
I had high hopes after listening to JD and his return to the Co. but the design/style is at odds with their target market.....I knew that when my teenagers laughed at me flexing in my Superdry Polo shirt
This morning announcement - Pan African Resources (LON:PAF) advises shareholders that its headline earnings per share (HEPS) for the current financial year are expected to be between US 2.95 cents per share and US 3.35 cents per share, compared to US 3.93 cents per share for the previous financial year, a decrease of between 15% and 25%. Earnings per share (EPS) for the current financial year are expected to be between US 3.00 cents per share and US 3.39 cents per share respectively, compared to US 3.90 cents per share for the previous financial year, a decrease of between 13% and 23%.
Pan African Resources (LON:PAF) It looks to me that the decrease is mainly due to the USD/ZAR exchange rate
This appears to be what Pan African Resources (LON:PAF) is saying but if oil producers can sell in dollars so why doesn't Pan African sell gold in dollars? It seems to me that what it is doing is inflating away the value of its gold and the company along with it. I hold.
I am not convinced anything has changed here, and the SP hasn't changed much either. The main reason for the drop in profit is lower gold production, something already announced. This TU appears to be required under South African company law.
@SDRY results announced at 07:21
My morning smallcap tweet: Wood rot for holders of Accsys
EnSilica (LON:ENSI) Accsys Technologies (LON:AXS) Verditek (LON:VDTK) Colefax (LON:CFX) Johnson Service (LON:JSG) Libertine Holdings (LON:LIB) One Media IP (LON:OMIP) RC365 Holding (LON:RCGH), Totally (LON:TLY)
◄EnSilica (ENSI)► gets $2.4m follow-on contract with majority booked this FY. [SP=66.9 Cap=52m]
◄Accsys Technologies (AXS)► warns FY-Mar rev below current market expectations and EBITDA likely to be significantly below. Blames weak mkt and destocking. Cost cuts. [SP=97 Cap=212m]
◄Verditek (VDTK)► £500k subscription at 0.45p, a 40% discount, to keep the lights on. [SP=0.7 Cap=3m]
◄Colefax (CFX)► tender to buy up to 14% of cap. Price is lower of: (i) 700p or (ii) 105% of the average SP on five days immediately preceding the Take-up Announcement Date. 700p is a 7.6% discount! [SP=775 Cap=56m]
◄Johnson Service Group (JSG)► acquires Celtic Linen for €31.5m. Will be immediately earnings enhancing. [SP=119.36 Cap=501m]
◄Libertine (LIB)► MAHLE Powertrain work has completed, late. Further performance and durability developments are now planned during Q3-Q4. Co has pre-funded the build of a small number of prototype hardware units. Also completed Phase 1 of the engineering development with Hyliion. Warns that if further fees from Hyliion not occur as originally expected FY will be materially below current market expectations. [SP=4.5 Cap=6m]
◄One Media iP (OMIP)► renews partnership with its distributor. $1m recoupable advance to OMIP. [SP=5.95 Cap=13m]
◄RC365 (RCGH)► following Letter of Intent, signs exclusive 10 yr rights agreement to market, distribute and resell YoouneeqAI's Platform in UK. [SP=79.15 Cap=99m]
In line: TLY
Colefax CFX
Somewhat bizarre tender offer for the company to buy 14% back from its shareholders at the lower of 700p or 105% of its share price on 31st August .
This has me a bit perplexed as to why ?
Maybe a way for the management to cash in sone chips without spoiling the market ?
Maybe a way to continue reducing share count and increasing long term value .
Would have been super nice if they had included a clear reason for doing this in the release .
I was thinking of going to the AGM in a few weeks might have to go now to see if this is a serious long term company interested in its shareholders or a company run by a seemingly pretty well paid top group who want to get hands on to as much of the cash in the coffers as possible ?
Bit concerned I have a decent holding in a company with a Dick Turpin business management strategy .
Will need to have a think on this . Confused
At an average age of 75 years I'd say the boardroom is fossilised and won't be surprised by anything it does and I speak from my own experience.
Renold (LON:RNO) and Volex (LON:VLX) both announce acquisitions. The Volex (LON:VLX) we knew about, hadn't heard about the Renold (LON:RNO) one before today.
I hold Renold (LON:RNO). Another acquisition, without having to ask shareholders to dip into their pockets, is a sign of a confident growing company.
Both acquisitions look very positive. I don't hold Renold (LON:RNO) but will have to do some research, as it seems to be on the up.
As for Volex (LON:VLX) it is my largest holding, I have listened a couple of times to the full year results webinar where the acquisition of Murat Ticaret is discussed in some detail. It seems an excellent fit for Volex (LON:VLX).
According to Nat Rothchild it should lift operating margins close to 10% from the current 9.3% and will result in a sizeable increase in revenue. On the basis that Volex (LON:VLX) continues to trade well, which the recent trading updates confirms, Murat should make a very positive contribution to the bottom line.
Just had a quick look at Renold (LON:RNO) Stockreport, barely enough column width!