Small Cap Value Report (Fri 10 Feb 2023) - MEX, ZYT

Good morning from Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
There's nothing of interest today in company news. Thank goodness, as I must admit to being a bit tired out, after the crazy avalanche of news in the first 6 weeks of the year, so it's pleasant to be taking things at a more gentle pace this week! Also great to be seeing so many strong recoveries in small cap share prices, although I'm still wondering if these will stick, or whether we should be banking some profits?
I might call it there for today's report, and go for a nice long walk & listen to some podcasts. Then I need to update my summary & watchlist spreadsheets, and prepare for tomorrow's small caps podcast.
Sections below -
Tortilla Mexican Grill (LON:MEX) - notes below from my company visit to its Head Office yesterday. Cautious thumbs up from me.
Zytronic (LON:ZYT) - a quick review of its trading update earlier this week. Thumbs up from me.
Company Visit - Tortilla Mexican Grill (LON:MEX)
I can’t remember the last time I visited a company, it was so long ago, pre-covid. These days, almost all contact I have with companies is on zoom-type calls. Yes, it’s more efficient for everyone, but lacks the human element of a face-to-face meeting, and seeing people in their own environment, interacting with colleagues, etc.
So I was delighted when the PR company for casual dining chain Tortilla contacted me, to ask if I’d like to meet management at their central london Head Office, yesterday afternoon.
I met the affable CFO, Andy Naylor, and did a Q&A for about 45 minutes, covering lots of topics. Here are the main points I took away with me (not verbatim, this is roughly what I remember being said, so may not be exactly right on everything) -
Rapid growth in site numbers, reached 82 most recently. What’s the total market size? We’re expanding outside of London now, so think there’s room for at least 300 sites. In London people are more familiar with Mexican-themed food (with several competitors). Outside London, less so, and it takes maybe 18-24 months for business to build in new sites.
Your balance sheet shows a deficit of about £5m on the IFRS 16 asset/liabilities, which suggests you have some loss-making sites. Are these problem leases? No, not really, there are only 2 loss-making sites, and they’re not losing very much, and we think they can be made profitable over time. We’re not keen on IFRS 16 (nor am I!) and it isn’t something that we use to run the business. It’s just a year end audit matter.
Deals on new sites - were very generous throughout the pandemic, could be reverse premiums (cash from landlords) of up to £250k per site. Typical capex is £400k per site, so that made a very good impact, and return on capital employed is incredible on those sites, under 1 year payback. But higher interest rates have impacted landlords’ willingness to offer such generous deals, and reverse premiums are now typically c.£100k. Long rent-free deals are still available. Expansion is self-funded, from EBITDA.
EBITDA isn’t really profit though! Charlie Munger described EBITDA as bulls@#t earnings I think, and quipped that the tooth fairy doesn’t pay for capex! That’s true, but EBITDA is a good approximation to cashflows. After the float in Autumn 2021, we were guiding about £7m EBITDA, but were hit with several headwinds - most noticeably £2m additional cost of meat, caused by the Ukraine war, prices just suddenly went up 40%. We shopped around, but it was the same everywhere. That sort of increase can’t be passed on to customers in one go, and our focus is on offering everyday value for money, e.g. to students (we do well in university towns). Also energy costs went through the roof. We weren’t hedged (a mistake, in hindsight), but that’s now peaked, and we’re benefitting from falling costs, whereas some other competitors are locked into higher deals. In future we’ll be hedging more.
Managing the lunchtime rush is the difficult bit - very condensed selling, with queues, then it goes quiet again. We're looking at ways to use technology (e.g. self-ordering/payment at kiosks) to increase throughput at busy times. But smaller sites can be difficult to fit in self-service machines.
Head office team seems very small - it’s just maybe a dozen people, for accounts, IT, and marketing. The office is the 1st floor of a small office building in Fitzrovia. There is also a central procurement depot in North London, which supplies stores with ingredients ready-prepared. Other than that, stores are managed locally, and overseen by a team of Area Managers out on the road (typically c.10 sites each). That's getting more efficient as the store estate grows, so bunching together site visits becomes easier.
My opinion - I think the IPO in 2021 looked over-priced at 181p, and the share price of 117p is now well below. That’s partly because expectations were lowered from £7m EBITDA to £4m due to cost inflation, and the cost-of-living crisis. But the way I see things, is that MEX remains profitable, just (currently around breakeven really, once depreciation is taken into account), which isn’t bad when they’ve been hit with both unforeseen higher costs, and reduced demand. So I think the way to look at this share is as a recovery situation, once the consumer is spending more freely, and maybe costs are falling, or maybe just not rising any more (they’ve seen inflation moderate more recently). Another round of price rises to customers is to be implemented shortly, and the company hopes to rebuild margins gradually.
There will also be a roll-out of more sites nationally, and MEX has demonstrated it can handle a fairly rapid pace of growth in site numbers.
Overall then, I think this share could be a good one for our watchlists. At £45m market cap, I don’t see it as particularly cheap, as I’m not inclined to value shares on a multiple of EBITDA. I prefer proper profits. Also, the balance sheet is a little thin, so I’d prefer to see that strengthened over time from reinvested profits. So the dividend-paying potential is limited at the moment.
Near the start of my investing career, roll-outs of retail/hospitality chains was quite a lucrative area. If you spotted an early stage, successful format, then you could buy the shares, wait 2-3 years, and make good money, as they grew, and re-rated at the same time. Turbulence from online competition, and then covid, has taken away those opportunities. However, newer chains, which are opening sites on newly competitive rents, and don’t have historical baggage of loss-making over-rented sites, could rejuvenate this investing theme perhaps? I've mystery shopped Tortilla about 5 times, and been happy with the quality/taste, and value for money. So I think this is likely to be a successful chain, in a niche that it has largely to itself at the moment - outside of London, there are not many other Mexican-themed burrito restaurants.
So this one gets a cautious thumbs up from me.
Zytronic (LON:ZYT)
132p (down c.12% yesterday)
Market cap £13m
AGM Trading Update & Board Changes
Zytronic, a leading specialist manufacturer of touch sensors…
The current financial year is FY 9/2023, so this update covers the 4 months to Jan 2023.
It’s a bit lacklustre, hence the share price dropping c.12% yesterday.
What surprised me was the comments that supply chain issues are still having a significant impact, with shortages of components causing it to pay more for unofficial supplies, and cannibalising finished goods for the components, which sounds a bit extreme, and would presumably involve extra labour costs (and maybe having to write off other inventories?). It’s not good anyway.
Monthly order intake similar to H2 last year. That’s not good, as H2 LY was only £4.9m order intake, suggesting that the current revenue run rate could be as little as £10m annualised.
Pipeline - sounds more encouraging, with £61m in lifetime value of contracts, although that’s multi-year, and not all of it will actually turn into contracts. I prefer firm orders, to numbers on pipeline of potential opportunities.
Although this all sounds rather negative, the good thing about Zytronic is it has a proven ability to operate around breakeven, even in very slow years. In good years, it has been highly profitable. Plus of course there’s pots of cash in the bank, relative to the size of the company.
Net cash is now £6.8m, just over half the market cap. It’s genuinely surplus cash too, if you look at the last balance sheet, net current assets was £9.8m, with no significant long-term liabilities.
So this share tends to attract value investors, who like the strong asset backing, and you’re getting the business thrown in for very little extra - a nice combination I think, for patient investors.
Outlook - a stronger H2 expected, although it cautions that pay rises for staff are likely to be more than budgeted.
My opinion - this is an interesting little value share. You have the comfort of strong asset backing, supporting most of the share price. Then you get upside from a possible recovery of the business, on top of that.
So a thumbs up from me, as a value share. Note also the consistently high StockRank.
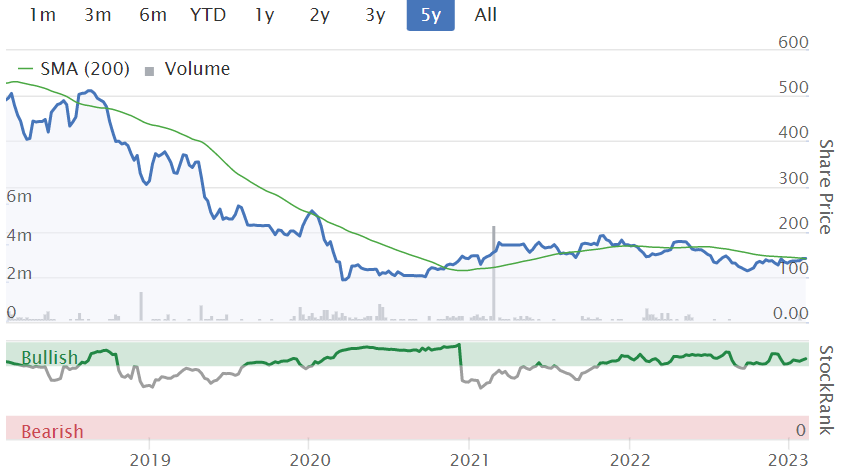
It's interesting to note a permanent de-rating of this share from the 5-year chart below. That came about because, as it turned out, the company had a number of key products that reached end of life, with repeat orders drying up. That's the sort of thing that only insiders really know about. We always think we understand companies we invest in, but the reality is that outside shareholders usually haven't got a clue about the inner workings of any companies we invest in.
The number of shares in issue has fallen from 16m to only 10m, following large buybacks. So theoretically, if orders recovered to previous levels of profitability, this share could not just recover to 500p, but go considerably higher. So there's an opportunity here, we just don't know whether that positive scenario will play out, or not.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
Many thanks davidjhill for your lucid response on Entain (LON:ENT) .
I bought my opening position in October 2020 and took a 5 year view based on the premise that virtually all US States would legalise betting which given the size of the market meant Entain, previously GVC, would be in a very powerful position.
I concur that in 3 years Entain will be a very valuable business and I have a target price of £28.
Thank you for stating why you do not expect an RNS from Entain on the price drop.
I will not be adding as I am already at my maximum in any one share.
Is the link to the webinar
How To Read A StockReport - Forensic Stock Analysis in 2023 | Login to this event (webinarjam.com)
Thank you for your efforts as always gents.
Hi Scott, welcome to Stocko. I see you have just joined and this is your first post.
Entain (LON:ENT) my largest holding is down nearly 16% in 2 days as a direct result of a remark in an analyst briefing by the CEO of MGM that MGM had "moved on" and would not be bidding for Entain. They had made an all-share offer for Entain in January 2021.
I feel pretty miffed that the CEO dropped this comment seemingly off the cuff which was very damaging to the SP of Entain their 50/50 JV Partner in BetMGM.
Surely Entain should put out an RNS given the very sharp drop in the SP. I would appreciate any comments from Subscribers to this situation.
MGM were deluded in trying to bid for Entain (LON:ENT) in the first place. In reality they couldn't afford it as they would have to give too much of their own company away to get it. The low ball bids initially were laughable.
Entain (LON:ENT) is capable of generating cashflow of £800m p/a and in 2 or 3 years time this will be circa £1.2 to £1.4bn by my calculations. Although they have £2bn of debt they are highly cash generative and if they don't acquire anything else this will be gone in 2 years time if they want to do that. That makes a fwd EV of £7.5bn look cheap in my view. I think the US business will also be extremely valuable over a 3 year time horizon.
As I understand it the JV is exclusive to the US and neither party can sell out of it without the other party agreeing and neither party can do their own venture that competes with the BetMGM business. The MGM CEO did also say that they highly value the US JV with Entain (LON:ENT. The drop was bizarre as there wasn't a 15% bid premium built into the price, maybe 100p as some bid talk swirled around and I suspect some investors may have been spooked at MGM saying that they were going to use their acquired swedish vehicle to globally expand. Again in my view thats just fanciful. Both Flutter Entertainment (LON:FLTR) and Entain (LON:ENT) are global leaders in this space - others will have a hard time trying to compete.
Always some regulatory risk but Entain (LON:ENT) know what they are doing and only operate in regulated markets. They are adept at changing with the rules and expanding in other markets. the UK market is much less important to them than it used to be from a diversification of revenue and profitability.
I doubt Entain (LON:ENT) would see the need to comment on MGM saying they aren't bidding. They've only just issued a trading statement which was good and the BetMGM JV will move into profitability this coming year so no further capital required in that business either. They believe they can more than double the valuation over the next 3 years and are heading in that direction so I don't know why the market got so spooked over the MGM CEO saying he didn't plan on bidding. Big overreaction me thinks.
Has the link for the webinar that happened this Wed been sent out yet? I haven't seen anything or recieved an email?
Yes I had an email, think yesterday, will check.
Yes, yesterday.
Thanks mate, have messaged the team.
Journeo (LON:JNEO) as there was a bit of interest in this yesterday I see new broker research out today.
expects revenues of £33m for YE23 and EPS of circa 18p with net cash of £5.8m
balance sheet looks pretty strong with net current assets of about £7m. Looks like payables and receivables are about equal too.
so on a PER of 7 or cash adjusted 5* and trading on half the valuation of peers.
Im long but starting to think I should be upping position size. Feels like it is the wrong price to me.
Building boom predicted for the UK as planning applications take off:
https://www.propertyreporter.c...
tinyBuild (LON:TBLD) Any thoughts from more experienced investors?
I have been looking at Tiny as the gaming sector is in a bit of a downturn and so there may be value here. The CEO holds 37%, they have cash in the bank , a strong culture that results in high staff retention and don't adjust eps.
But there has been regular selling since mid December that continued throughout January and into February. Then on Wednesday with the price at 73p there were sells for 3.7m shares at 50p crashing the price. Followed by yesterday 16.5m at 55p. A quick email to the Company and they say they would have reported it if it had been the CEO.
So the question is if the market makers are holding 20 million shares in a company where there is normally very little activity would that mean there is a floor to the share price and that it has been reached. If it drops lower they will be taking big losses and so I assume, but have no experience, that they have the ability to control the price and even walk it up to create momentum.
Anyone have any thoughts?
TR1's will soon tell us. Im pleased to hear its not the CEO that's been doing the selling. I suspect the selling is from one of the pre IPO investors who will still be in the money even selling as low as 50p. From where I'm sitting it looks like the buyer has named their price and was happy to do business at c 50-55p. Looks like they have purchased >5% of the business. Lets face it, if you are going to make a transaction of that size, you will have done your due diligence. I don't think there is anything untoward going on here
The company who sold out, Netease its believed to be, a Hong Kong based firm bought in lower than the price we see today at 43p, pre IPO, they've made a profit. The TR1's are not out yet, but there is suggestion Swedbank (big major shareholder with 17m shares) hoovering up the shares sold by Netease. Whomever it is would not have done this without positive inside info.
Thank you both, I was looking at the buy and sells and using guesswork it seemed that the market makers were left holding millions that they would need to offload but I guess they could have flipped them for a low margin and some of the sells were actually buys.
Paul, thanks for sharing your interview and thoughts on Tortilla Mexican Grill (LON:MEX). Was there any comment or discussion on the success story across the pond - Chipotle Mexican Grill (NYQ:CMG)?
Could MEX be a multi-bagger in similar vein? Or will CMG eat their lunch? Or could we view MEX as a potential takeover target for CMG?
Further to Alan Partridge 's comment to Paul, I have another comment to Paul
If I remember rightly, you said (Paul S) that Tortilla Mexican Grill (LON:MEX) was rubbish until they bought another company which on the basis of your eating visits was much better. Cant remember the absorbed company but it has presumably done the Tortilla Mexican Grill (LON:MEX) total figures some good, and the total group have learned from the acquisition? Did you cover any of this in your conversation?
Further to my comments on Tortilla Mexican Grill (LON:MEX) I would be interested if you could have the same sort of discussion with the top people at Loungers (LON:LGRS) which seems to have a better handle on all day food. Footfall much better balanced, and ambitious expansion programme from a much higher base than Tortilla Mexican Grill (LON:MEX) of course.
Thanks again Paul S for the Tortilla Mexican Grill (LON:MEX) review.I think the absorbed restaurant chain was Chilango - a hipster chain that received millions - https://www.crowdcube.com/comp...
The Saga (LON:SAGA) news has been well received.
There is still a long way back to it's highs last year. However, the charts look much better than they did.
Saga (LON:SAGA)
as per page 41 in their 2022 accounts, the underwriting division made £54.1m PBT and now they're selling it for £85m?! This seems like a rock bottom sale price and absolute bargain for the acquirer. The division would make more than the sale price in less than two years! Surely I am missing something here
I think it is the reserve releases from prior year being reported as PBT in the accounts which accounted for £42m of the profitability.
Looks like the core underlying profitability was about £12m so not such a rock bottom price if they achieve £85m.
Assuming the combined ratio of 97% targeted that suggests underlying profitability is expected to be just £5-6m p/a by looks of things.
Paul, if you ever get a quiet day, I wonder if you could post your thoughts about selling. I freely admit it's what I find hardest, and my best results have been when I've been nudged into selling for one reason or another after a decent rise. I've lost count of the number of times I've ridden a wave up and then come down again because I've lacked this nudge. Do you only sell after a change in fundamentals, or do you keep an eye on prices and sell after a certain rise or fall?
Have a listen to Ed's Webinar from Wednesday. He gives some advice on sell timing based on 90/70 'rule' linked to the stockopedia rankings.
Not seen that part of the Webinar yet, but won't that only apply to high ranking stocks? I think many of Paul's already below these rankings. MJ GLEESON (LON:GLE) for example has a M score of 18, yet is up 20% in the last month. I have noticed this year many of the big share gainers are low ranked Momentum stocks.
Yes I think it pre-supposes that your entry level is on a plus 90 ranked holding and that to some extent means it is likely to be a larger cap company. Certainly when to sell is harder than when to buy.
Hi Fishcake
Simply this is all very personal and there is no right or wrong answer.
To be honest I would typically joke that I am almost an expert at my trademarked "Buy High, Sell Low, Buy back Even Higher, Sell again Even Lower" strategy, most importantly keep on repeating and be very emotional about it all!
Firstly, I am not always able to see information during the day, so I don't read 07:00 announcements, I do not see rises or falls within the day, I do not have time to go through the charts and movements on a regularly basis. I admit that I can be very emotional about it all, especially with the Olds money. I look after my own money as well as 7 family members, try to be a son to the olds, parent to the kids, husband to my wife and hold down a job and be a house elf, and sometimes even get time to breath.
I would describe myself as an investor, rather than a trader. But I would recommend reading some of the trading information available as this really helped me. The key one to me is two parts, what is your trigger to buy, but when you are buying you also have your trigger to sell. So yes I love the concept of "Coffee Can" and "NAPS" but to remove some of the emotion what is the sell.
For me selling this looks something like
The harder part is what I have read in some literature regarding what is my target sell price. So partly this could be a valuation, so I think this is undervalued currently and £X is a fair value. Part of this is a charting approach, I want to catch the upward trend and exit as you say before it goes all the way back down (and beyond), learn to accept that you never get the absolute bottom or the absolute top.
The hardest part is sleep at night. So for example I sold Smiths News (LON:SNWS) when it dropped below 50p (down 10% from peak), booking a capital gain and dividend. Now I believe it is a good company, and is a good longer term investment, so it went back on the watch list. Obviously it starts going up again the next two days and you then go into the could or should have. But then a different example is I sold Warehouse Reit (LON:WHR) ~£1.50, having bought as income at ~£1.10, obviously why did I not sell at ~£1.70, and is now back at ~£1.05. This is part of the what can I do better next month.
Simply the sleep at night strategy is be in the game tomorrow. There is always going to be another opportunity and you have to have money to be able to do that. So taking a profit is always a right decision, and cutting loss is always a right decision. We could all be better, and there are always those who will tell you of the I bought at 5p, sold at £2, bought back at 25p, sold at £1.50. What I really appreciate here is the honesty, I bought at £4 and it is now 35p. Covid taught me sometimes you lose the bounce HSBC Holdings (LON:HSBA) three years later, but I also miss this how do I make back a 75% loss, which then requires a 300% gain. Do not fight Mx Market, they are not rational just do your best in your time.
Sorry longer than planned but very long meeting on the other laptop.
Good luck and happy to discuss more if you want
Tommy
Thanks all. I think the 90/70 rule is a good one if you're following the buy by high stockrank system, as Rusty2 says. Selling on the first real profit warning is also good advice. As Tommy says, there is no 'right' method, but I'd be interested in any views, eg what do you do if you get a quick 50% gain, but it still doesn't look overpriced.
I typically try to buy stocks that stand a chance of doubling within the next few years, backed by decent fundamentals, but always agonise in the cases where I get a quick 50%, or where I keep hanging on to get 200%, at which point it often seems to fall back again. Classic greed and fear on my part I'm afraid!
selling at a loss when the share price drops is painful but necessary. That is what I did with Adidas today. I lost 21% in this investment.
I tend to sell any share if it drops 25% from peak.
I sell if any shares rockets 25% in two weeks.
You can make your rules but sticking with it is difficult.
A wise previous broker once said to me "Pull out the weeds, fertilize the flowers". This accurate and splendid metaphor has stayed usefully in my head.
I put it alongside Benjamin Graham's famous metaphor which ran something like "In the short term a share's price is a voting machine, in the long term it is a weighing machine"
It is fun to study charts, strategies, economic forecasts and so on. But those two metaphors are all you need to know to be a successful investor!
Ed Croft briefly covered this in his latest seminar. Buy when the stock rank is above 90 and sell when it falls below 70. Pretty mechanical and I am not sure it is backed up with statistics.
Mark Simpson wrote about this recently. https://www.stockopedia.com/co...
I think it's always worth top slicing to at least lock in some gains, especially if it's gone up on no obvious news. Ultimately you have to try and assess how much further upside you see - if you think there is more upside in other shares then logically would make sense to switch into those. I personally sold MJ GLEESON (LON:GLE) today after quick 30% rise - rationale was that it had lagged the rebound in other housebuilders but now largely caught up. On the other hand I sold H & T (LON:HAT) way too early last year and still kicking myself.
As Buffett said “ whenever anyone mentions EBITDA, I tend to zip up my wallet”..
Not related to any news today, but just something I stumbled on - Shepherd Neame (OFEX:SHEP) might be worth a look as it seems to have been somewhat forgotten about and as a result has so far not participated in the ‘everything rally’ since October.
They last updated back in late Sept.22 when they reported reasonable recovery figures in line with market expectations - the market shrugged and nothing happened. However, industry figures have continued to be strong since then and the market has taken notice of others in the sector.
Paul last had a look at these back in June 22 when he gave a positive review, since which time the share price is now down another 20%+ from then for no readily apparent reason - and all the potential bull points still stand.
https://www.stockopedia.com/co...
In fact, what has really pulled my attention to these is that all the competitor pub/brewery stocks of Marston’s, Mitchells, City Pub etc. are all up usefully YTD anything from 4% to 12% but SHEP is down 2% on no news. See chart below:
This is even more stark if you take the chart further back to the October ’22 lows – many of the competition are up by 17% to 50% but SHEP is down 7%. Why? No reason that I can find, and in fact the others have all given a more recent market update since Xmas which for all of them has been largely positive improvements and uplifts over last year (resulting in share price rises) and they have reported better footfall and spend over the festive period – no doubt spurred on by festive spirit and the World Cup. I can’t find any reason why SHEP will not report along the same lines when it updates the market (likely next month based on history of their announcements). I can only assume that the lack of any trading announcements, combined with them being Aquis listed has just resulted in them falling off the radar.
They are now trading pretty much where they were in the very darkest days of the 2020 COVID market crash when it felt like nobody would ever go to a pub ever again, which seems slightly crazily pessimistic given where we are now in comparison and the trading environment being reported around them.
Debt does not seem to be the differentiator as others in the sector are similarly indebted and have still attracted good rises.
The big headwind for all these companies is energy costs of course. SHEP have got theirs hedged below market rates until later in 2023 for the pubs and until 2024 for the brewery so this won’t impact their upcoming results or trading update. City Pub and others have already had to bear rises and it didn’t impact their overall improved results (in fact City Pub reported that since the start of this year, these costs have started to reduce, although they are still high by historical standards). So if anything this is another win for SHEP vs some competitors whose share price has risen. Longer term such costs could become a concern of course but this will be across the industry but one would imagine everyone will be upping prices to at least partly deal with this.
Whatever your view of the long term prospects, there seems a clear opportunity for a short term modest jump here, likely with limited downside (as ever, in the absence of an entire sentiment about turn towards stocks generally).
Interested in any other thoughts/views. I do not currently hold, but I might well do shortly.
BIACS
I've looked at Shepherd Neame (OFEX:SHEP) Similar conclusions. However I invest with HL. They won't allow me to invest it in my Sipp, only my isa. Also won't allow stop loss either. Not asked HL the reason.
Probably because it is on Ofex. I would be very wary of investing in pubs at the moment, so many headwinds, I can see a lot pubs closing this year. I know Shepherd Neame (OFEX:SHEP) their estate is spread wide, don't know why they have odd pubs in Suffolk.
Ofex is considered more risky than the AIM, I have never traded on it, I imagine liquidity could be a problem.
I have asked the question.
I'm gradually beginning to dislike the HL platform.
OFEX (or Aquis) shares. I hold National Milk Records via Interactive Investor and recently successfully Bed n SIPP it from my Trading Account into my SIPP.
Those that like Shepherd Neame (OFEX:SHEP) may also like Daniel Thwaites (OFEX:THW) also quoted on Aquis. They are a beneficiary of rising interest rates via interest rate swaps, very straight forward, good quality business. Which even used to deduct it's pension fund deficit from NAV ! It does not anymore as it no longer has a pension fund deficit.
The price stands a very big discount to NAV, could be in a good business with UK hotels now able to raise prices, and with higher occupancy levels. ( According to Whitbread who own Premier Inns ).
Just a warning these shares likely to rise substantially as market makers hike prices before you can buy any as they were tipped as this year's IC Bargain shares. Lucky me holds GATC. Be aware they will only be higher on the tips and some of the spreads are large.
Arix, Gatc, ckt,cml,ctl, ldg,nsci,tmt
I hold Logistics Development (LON:LDG, tempting to sell.
I was looking at Gattaca (LON:GATC) yesterday and decided to finish off today. Too late! I won't chase it, but it is irritating because I had a very good run with it from 60-ish to 180-ish.
Lucky me holds GATC
I wouldn’t be so sure, Robbie. The Ben Graham case lacks the small matter of a moat. This isn’t a matter of waiting for improving market conditions to float the profits. Recruiters have been making out like bandits while Gattaca (LON:GATC) languishes. It’s very hard to turn around a recruiter that has lost its core of top billers and the current attrition rate of 40% doesn’t shout “recovery” to me. Meanwhile, new management is in-house with no experience of the challenge in front of them. My view is that the company is a long-term loser, scrapping around for the lowest margin opportunities that the genuine specialists eschew.
But the trade could be profitable if enough punters believe in it. And you know how to make that work for you.
Hi BnB Yes, when I said lucky I meant I got lucky because of the tip giving an immediate 20% lift....
My story of buying Gatc: It came up on a screen (can't remember which), I had a quick look and noticed for a market cap of 20m, it had 12.5m net cash and said it was going to declare a 2.5m profit. I just thought to myself that seemed cheap but wasn't sure as too cheap often means something rotten! I did think maybe too cheap for a reason and kind of dismissed it.
But I put it on a watchlist anyway and I saw on Monday a buy of 50,000 shares. Looking back I noticed one or two bigger buys on Friday - out of nowhere it seemed there was some interest and someone wanted to buy in size. (Conspiracy theorists welcome).
I had a vacancy for a higher risk buy - I only allow two shares of under £50m market cap in the isas and thinking the buying interest might signify something better was on the way bought 5,000 and 10,000 shares at just under 72 and the day after I bought another 20,000 at just under 74.
I bought a fair whack as I noted the shares were surprisingly liquid and I could buy or sell in size. Now Simon T has given me a free £5,000 profit! Do I say thanks very much and bag said profit? Or do I continue to hold as Simon T reckons upside is 100%? Or sell half?
Time for a vote! Call 0898166777 for take profits. 0898166778 for sell half or 0898166779 for keep holding. Calls are £50 a second. More dull stories from me of buying shares available at 0898166790. (Stories last about an hour)
Do I say thanks very much and bag said profit? Or do I continue to hold as Simon T reckons upside is 100%? Or sell half?
I wouldn’t presume to advise you on trading, but, as a long term buy and hold investor, with additional insights in the recruitment sector, I’d be swapping my Gattaca (LON:GATC) for Robert Walters (LON:RWA), whose share price has languished while China re-opens. Nearly half of RWA’s business is in the orbit of China. It’s priced for a coordinated global recession that may already have been averted. I’ve loaded up a full position at current levels and would happily sit through any volatility -20% lower is conceivable - for the potential recovery.
I did quite well trading Simon Thompson's tips, but only when I waited for the price to pullback after the tip, and then when he tips it again which he invariably does (whenever there is new news about the company), it often goes up again. I would keep holding until it stops rising then sell, because it will drop back soon enough. Of course, Robbie, not for me to tell you have to trade this as you already know. being a Market wizard yourself.
Out of interest, how much of your trading/investing is fundamentals and how much is technicals? It used to be 10/90 for me a long time ago but now its flipped to 60/40(60 fundamentals/40 technicals) since I started using Stockopedia. Earnings is Queen, then technicals is the rook.
GATC was a great lockdown stock and i also made a good return on it during that time. i work in the tech sector and recruitment is well down for January compared to previous years. i have lots of friends/ex colleagues that have been culled and unable to find positions for a good few months due to the cut backs in the tech sector.I agree its purely based of the tip in IC, so am steering clear this time.
Watch the SPs bouncing like springs here http://webmashing.com/charts-f...
Click the L button for larger charts.
Buy the market maker's share instead. Close brothers (CBG) which own Winterflood , the main small cap market maker. Low rating, good dividend and down recently due to making provision for a lending company they bought some years ago.
Crazy true, all the 8 shares are flying (4 of them over 15%+) today.
At 2pm average gain of these shares are 12%...
Crazy but some of the spreads are quite wide. Problem is you can't often buy at the tip price. I found ST tips a mixed bag, some good ones with a load of lemons. I don't follow him anymore, I think Globo was the last straw, not that I ever invested in it.
Ruffer January report -not everyone's cup of tea but always a fantastic read.
"The market is salivating at the prospect of Federal Reserve interest rate cuts beginning in the summer; it might be right, but the rally means that it will now be painful if the cuts aren't delivered. We remain defensively positioned and think it prudent to watch proceedings from the sidelines: our focus is on balancing the portfolio to make sure it retains its ability to protect capital in the drawdown that we expect will be visible later in the year. Better to live to fight another day"
Ruffer are the hawkish Kings of macro. They aim to make be positioned to cover every worst case scenario whilst simultaneously hedging every position they have. They aim to protect capital also make at least twice the rate of return against cash in the bank.
Investegate |Ruffer Investment Co Announcements | Ruffer Investment Co: Monthly Investment Report - January 2023
Ruffer Investment (LON:RICA) is a classic 'sleep safely at night' investment. It will never blow the lights out and it usually performs best when markets are in freefall - total return last year was 9.1% whilst it was up 20%+ during the 2000 TMT crash and in the GFC. Occasionally, the premium rises above 5% and when it does it's worth looking at the LF Ruffer Diversified Return Fund, which has a very similar profile as it's also managed by Duncan Macinnes.
I would suggest everyone has a very, very careful look at what Ruffer were doing in Bitcoin and what it says about how they manage governance & risk.
I would also want to know whether they really have the ability to match the investment banks when it comes to the scarce expertise needed to accurately price those deeply-out-of-the-money options & swaptions they trade in....
Good morning Paul,
I would be interested to know your thoughts on Cinch taking a 3.1% stake in Vertu (VTU) on Wednesday. I'm a happy holder.
DH2.
Saga (LON:SAGA) - Sky News broke the story as is customary these days:
https://news.sky.com/story/australians-open-to-takeover-of-saga-underwriting-arm-12807085
My morning smallcap tweet: Friday fluff
ITIM (LON:ITIM) Saga (LON:SAGA) Ince (LON:INCE)
◄itim (ITIM)► guides FY-Dec rev c.£14m, in line but EBITDA onlu c.£0.2m (£2.2m), below market expectations. Blames slow enterprise contract conversion. [SP=47.2 Cap=15m]
◄Saga (SAGA)► confirms exclusive discussions with Open Insurance Technologies on sale of underwriting business. [SP=170.9 Cap=240m]. I hold.
◄Ince (INCE)► the late FY-Mar audit needs two more weeks work. [SP=4.95 Cap=19m]
Happy Friday all! If you haven't yet listened to it yet I recommend Paul's podcast of last week if just for the moment when he mistakes Kathy Burke (Waynetta) for Cathie Wood (of ARK Invest). He saves it brilliantly though by saying Cathie Wood appears to be a bit of a berk. Bravo Paul!
UK avoids recession. So much scare mongering by the mainstream media. Unemployment is low and there's high number of vacancies.
A few years ago I completely stopped paying attention to or reading financial news. At best its backward looking, at worst its completely uselss opinion from confident sounding individuals with no apparent skill or talent.
Take latest Nonfarm payrolls estimates. Around 20 huge banks and investment firms predicted the number anywhere between 150k-305k. The actual number was 517k!
Factual economic data and individual shares/main markets price action and company trading is all im concerned with now. Personally for me at least its removed all the confusing background noise and made decision making so much easier.
What you said goes beyond the pundits.
Didn't the governor of the Bank of England predict severe recession in UK only two months ago?
he did, but remember that Bailey was previously head of the FCA (financial conduct authority)...
...and he was particularly inept at that job!
Its like the OBR, usually way out in their forecasts.