Small Cap Value Report (Fri 10 May 2024) - ULTP, GDR, TGR, POLX, SFOR, RMV, TTG, MTC

Good morning from Paul!
Today's report is now finished, have a lovely weekend!
I hope you're enjoying the apparently brief spell of warmer weather. I'm off to Gozo again tomorrow morning, so might record the week's summary podcast early, this evening. Or it might be on Sunday, it depends.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
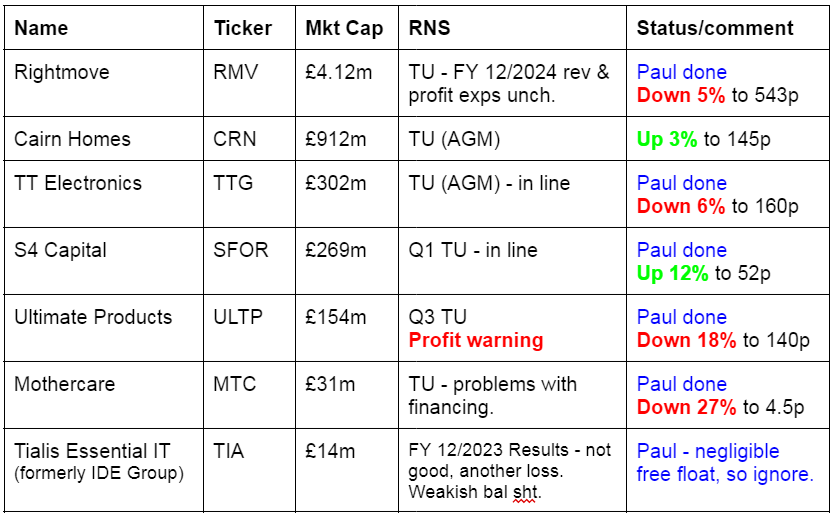
Other mid-morning movers (with news)
Genedrive (LON:GDR) - down 46% to 1.88p (£3m) - Discounted placing/open offer - Paul - RED
Raises £2.1m at 1.5p, a deep discount. Interestingly it’s also using the new REX platform to try to raise a further £3.5m from others (eg retail investors). Good luck with that! I welcome a new platform for us to participate in fundraisings on the same terms as institutions, but can’t help thinking it’s come about by necessity, since the instis aren’t interested in funding micro caps any more, as most of them are utter rubbish. It says that the REX raise has to deliver a minimum of £3.9m, or it won’t proceed. That’s bold. I wonder what their Plan B is?
Paul’s view - I’ve never written anything here about GDR, as the numbers have always looked so awful. It manages to accumulate heavy losses every year, whilst also reporting declining, and miniscule revenues. How do they manage to convince shareholders to keep pouring in millions in repeated fundraises? Always jam tomorrow I suppose, and on the cusp of great things. Yet hardly any of this type of company actually do achieve their goals. I see it did a marvellous speculative frenzy at the covid outbreak, 20-bagging briefly. The sooner all these jam tomorrow things delist, the better. They can probably achieve much higher valuations with private investors, so stock market listings at bombed out valuations are actually a hindrance, not to mention costly. We need a mass exodus!
Tirupati Graphite (LON:TGR) - down 10% to 4.75p (£5m) - Trading Update/Results FY 3/2024 - Paul - RED
Unusual formatting in this RNS, with some partial accounts (unaudited) and lots of bullet points!
Sales are up an impressive 70% to £4.9m, but the gross margin seems to have almost collapsed to virtually nothing. The balance sheet excerpt shows negligible cash, but about £5m tied up in Madagascar & Mozambique in bank guarantees and a pending VAT refund! You couldn’t make it up. Oh and the auditor has resigned because they haven’t been paid!
Paul’s view - as you can probably guess, I won’t be investing here, I’m out!
Polarean Imaging (LON:POLX) - up 26% to 4.35p (£10m) - New Order Received - Paul - RED
Newsflow here is starting to look interesting. A second order has been received, and it says that would result in $2.5m revenue for 2024, with additional orders in the pipeline. It’s starting to look as though POLX might, just might, be gaining traction with its commercialisation.
There’s one large negative though - it’s almost running on empty for cash. An update on 29/2/2024 indicated that cost cutting had extended its cash runway to Oct 2024. Some indications of fresh cash have been received, but the crucial point is we don’t know on what terms. So existing shareholders could get lucky, or more likely are lambs to the slaughter as new equity can dictate the price & potentially large dilution.
Hence at this stage it’s starting to look promising, but I’d only be interested in taking part in a new equity raise, not risk money now on old equity, when you know you’re going to be diluted, potentially ruinously. The value of their existing equity is now almost worthless, so I don’t see how existing shareholders have any incentive to protect the value of existing equity. Better to just put new money in at 0.1p or something like that, and take the company for themselves.
Hence it’s impossible to value right now., and with very high risk of dilution (well, it’s certain that you’ll get diluted), it has to be RED. Pity, as I’ve always liked the potential for this MRI scanning innovation, and it is now at the commercialisation point. But management made the terrible error of running out of cash, and just assuming more funds would be forthcoming - coinciding with a nasty bear market in small caps.
Summaries of main sections
Ultimate Products (LON:ULTP) - down 14% to 146p (£131m) - Q3 Trading Update (profit warning) - Paul - BLACK (AMBER on fundamentals)
Profit warning unfortunately, due to continuing softness in demand and customer de-stocking. Broker forecast is dropped by 21%, quite a hefty miss. Outlook for FY 7/2025 sounds better though, with order books improving. I think this deserves a c.20% drop in share price, as previous growth must have been flattered by customers stocking up.
S4 Capital (LON:SFOR) - up 17% to 54p (£314m) - Q1 Trading Update - Paul - AMBER/RED
Cost-cutting has allowed it to reiterate FY 12/2024 expectations, which also relies on an H2 weighting happening. Why is the technology division revenues down 31% in Q1, when its main US market is in a tech boom? It feels like something's not right here. Add in the terrible equity structure, with Sir Martin's golden B share giving him total control, plus the weak balance sheet relying on debt, and incomprehensible adjusted accounts, and I'm struggling to see any attraction here other than as a speculative recovery type trade.
Rightmove (LON:RMV) - down 5% to 543p (£4.32bn) - Trading Update - Paul - AMBER/RED
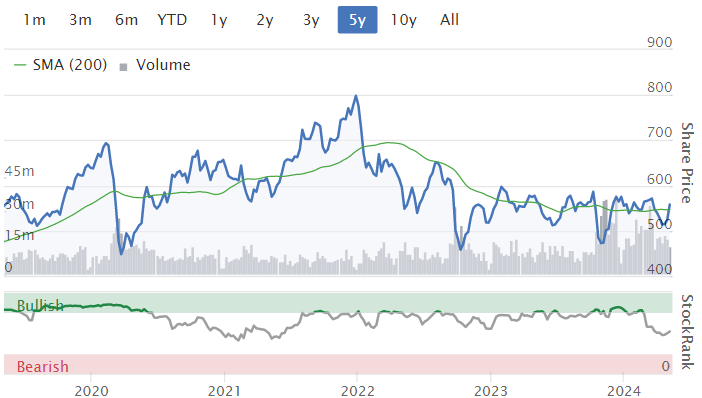
I mainly put this section up below to flag up Rightmove's interesting comments about the property market generally. However, it morphed into a criticism of RMV shares risk:reward, with a high PER, low yield (but buybacks help), and the risks to its price-gouging business model from two well-funded competitors. Can its network effect last forever? Let's have a debate! I see risk:reward as moderately negative overall at this valuation.
TT electronics (LON:TTG) - down 6% to 160p (£284m) - AGM Trading Update - Paul - AMBER/GREEN
In line with expectations, but some signs of softness (eg customer de-stocking). So I can see why recent share price gains have been given back. Graham's more positive on this share than me, so I've moderated it from green to AMBER/GREEN, mainly due to the bank borrowings, which still look too high.
Mothercare (LON:MTC) - Down 24% to 4.7p (£27m) - Trading Update FY 3/2024 - Paul - RED
Trading update isn't bad - in line with expectations, and the newish franchising model is making money. However, the finances are so stretched now (debt, and pension deficit) that is sends a clear signal that an equity raise is now highly likely, and/or bank refinancing & covenant waivers, etc. So the risk is existing equity could be clobbered in a discounted raise. Why get involved with all that risk, when the upside isn't exciting to start with? We'll watch from the sidelines for now.
Paul’s Section:
Ultimate Products (LON:ULTP)
Down 14% to 146p (£131m) - Q3 Trading Update (profit warning) - Paul - BLACK (AMBER on fundamentals)
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its Q3 trading update for the period from 1 February 2024 to 30 April 2024.
This year is FY 7/2024.
Not good news I’m afraid, the reduced sales (4% down) in H1 has worsened to 7% down (vs LY) in Q3.
Blamed on “the broader slowdown seen in retail sales to consumers”, and customer de-stocking.
Expects similar conditions will continue in Q4.
Revised guidance - top marks here, for a footnote which details what previous expectations were, that’s incredibly helpful and deserves a round of applause, I wish all companies would do this, so that we can immediately see the extent of the profit warning -
Therefore, the Directors expect FY24 revenues to be at least £156m, with gross margin being in line with last year, and Adjusted EBITDA to be in a range of £17.5-18.5m.
* Consensus market expectations for the financial year ending 31 July 2024 are currently revenues of £166.7m, adjusted EBITDA of £21.5m and adjusted EPS of 15.6p
Outlook - more encouraging news here, this bit below reassures that this year is probably just seeing a temporary soft patch -
As the year progresses, we are continuing to see the gradual resumption of normal ordering patterns from our retailer customers as the overstocking issues brought about by the pandemic subside. The increase in forward ordering by retailers has primarily been benefitting our forward order book for FY25, and as a result we are already seeing significant growth over the FY24 order book. The Directors therefore have confidence in the Group's prospects for FY25.
Broker forecasts - two helpful notes out this morning, from Cavendish & Equity Development.
ED has reduced forecast adj EPS (my preferred measure) from 15.4p to 12.2p, a fairly hefty -21% drop. Often share prices mirror the size of the forecast fall, or can be worse if the problems are seen as continuing. In this case, the more positive outlook for FY 7/2025 might catch the fall, but it depends on what market participants do.
FY 7/2025 forecast is also dropped by 12% from 17.0p to 14.9p.
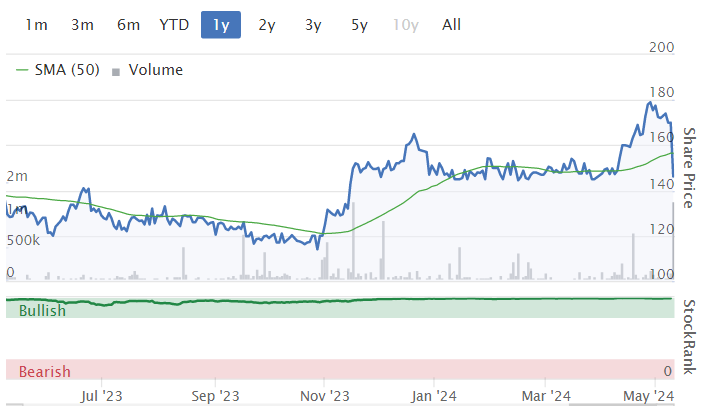
Valuation - the share price has been trending up, reaching 170p yesterday. I’m writing this without having looked at the opening share price (at 08:01), but I’m expecting a c.20% lurch down on the open.
I would have thought we could probably value ULTP shares on 12x reduced current year forecast, which gets me to 146p/share (down 14%) as being a reasonable price. Although profit warnings can undershoot a reasonable price.
Investor presentation - next week at 11am on Tue 14 May. Signup link here. This is good transparency from management, who I generally trust and see as competent. They’re also significant shareholders too.
Paul’s opinion - undoubtedly a disappointment, and I’m expecting a sharp fall in the share price (I’ve still not looked, honestly!). It might be worth waiting for the dust to settle before bottom-fishing here, is my current inkling.
Overall it’s a fairly decent business I think, and I don’t have any worries about solvency/dilution, since the last balance sheet had fairly modest net debt, and positive NTAV of about £13m - adequate rather than strong I’d say.
On fundamentals I’ll go with AMBER for now, and wait to see what happens next. That’s down from my previous view of GREEN, because obviously it’s trading badly, and has lowered forecast by 21% today. Overall - disappointing for sure, but it should regain its composure over time, based on the more positive outlook for FY 7/2025. Providing nothing else goes wrong of course.
Share Buyback launched from today in this separate announcement. Authority to buy (for cancellation) up to 8.93m shares was granted at recent AGM. First tranche is £1m to 31/7/2024, so not material & probably won’t make much/any difference to the share price.
S4 Capital (LON:SFOR)
Up 17% to 54p (£314m) - Q1 Trading Update - Paul - AMBER/RED
Previously - S4 is Sir Martin Sorrell’s revenge company, where he (I think) overpaid for digital marketing businesses, and was in too much of a hurry to create another industry giant. This has resulted in a mess - with a hollowed out, overly indebted balance sheet, incomprehensible accounts full of huge adjustments, poor trading and multiple profits warnings in 2023, plus of course the outrageous B share arrangement (giving him complete control basically, as I recapped on here on 27/3/2024). On the plus side, I didn’t see any immediate worries over liquidity, so for that reason moved up from red to amber/red last time.
There could be a rebound trade here, which is what today’s +17% price move might be indicating?
Today’s update -
Q1 revenue down 12-15% on various measures, but it says this is “as expected”.
Q1 “operational EBITDA” in line with its expectations.
Cost reductions (mainly staff reductions) & focus on gross margin (a good idea when sales are falling)
Full year targets unchanged for FY 12/2024, with “broadly similar” EBITDA, relying on “significant” H2 weighting (which it says is the usual seasonal pattern).
Wants to improve shareholder returns, now “all significant merger payments have been made” - wouldn’t it be more sensible to focus on debt reduction instead, given the weak balance sheet?
Obligatory mention of AI opportunities.
Net debt £206m at 31/2/2024, that’s up a fair bit from £181m at 31/12/2023, not helped by share buybacks, but also some remaining acquisition settlements. It expects debt to fall in H2 2024. It’s long-dated, and with soft covenants, so OK for the time being I think. When refinancing is required, lenders might be more sceptical perhaps?
Broker update - thanks to Dowgate who publish an update today. It points out that as SFOR moves through 2024, the comparatives will get a lot easier. So it could be reporting a return to growth later this year possibly, which might improve sentiment.
Dowgate forecasts adj PBT of £44m (4.8p adj EPS) in 2024, and £69m (7.4p adj EPS) in 2025.
Factoring in all the debt, which is about two-thirds of the current mkt cap, then I can’t see why anyone would want to pay more than say 10x 2024 forecast. So I’m getting to a cautious target of 48p per share. It’s currently 54p at the time of writing, so maybe in the right sort of ballpark?
Paul’s opinion - it all depends how you view the group that Sir Martin has created. Does it have great recovery potential (in which case shares could double from here I think)? Or is it a group of not particularly good companies cobbled together in a rush, that’s now struggling and seeing considerable reduction in demand? To my mind, with the US (by far SFOR’s largest market) economy performing well, and huge interest in AI and a technology boom generally, SFOR should not be reporting declining revenues, and in particular its “Technology Services” division is doing really badly, with Q1 revenues down 31%. Those numbers tell me something is not right here. The business should be expanding, not getting rid of lots of staff to cut costs.
Maybe Sir Martin’s stardust might cause shares to re-rate upwards in future, but on fundamentals it’s currently looking weak. That could change of course. It’s moderately tempting to have a little flutter here, just as a potential recovery trade. However, given that it consistently forecast too optimistically last year, I wouldn’t want to hang my hat on its current forecasts, relying on an H2 weighting which may not necessarily happen. I think on balance I’ve decided not to gamble on this one for now.
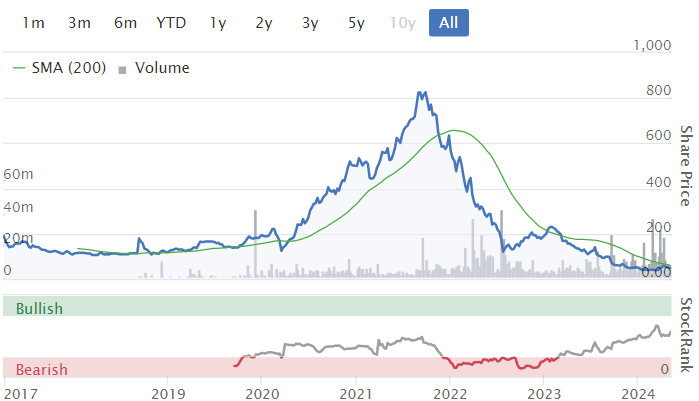
Ludicrous valuation previously, based on Sir Martin's amazing track record at WPP, but it just hasn't worked the second time around, so far anyway -
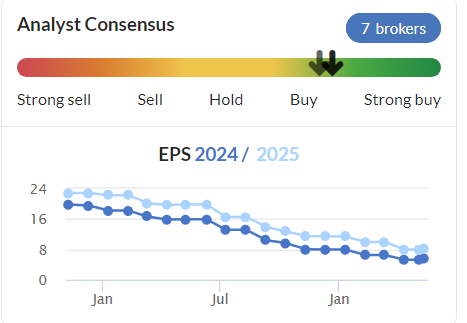
Broker forecast trend seems to be telling us there are deeper problems here too -
Rightmove (LON:RMV)
Down 5% to 543p (£4.32bn) - Trading Update - Paul - AMBER/RED
Trading update is in line for FY 12/2024 -
“Our expectations for revenue and profit for the full year are unchanged.”
However, its market update is interesting for general read-across, which confirms signs of an early stage recovery in the housing market -
“Our most recent monthly House Price Index[1] reported the average asking price for properties coming to market increasing by 1.1% month-on-month, with annual house price growth of 1.7%, the highest for 12 months.
Sales agreed between January and April 2024 are 17% higher than the same period last year, with both sellers and buyers now increasingly looking to transact, and we continue to anticipate total sales transactions of 1.1 million in 2024. Higher mortgage rates continue to stretch affordability for the average buyer, and the market is operating at different speeds across its many segments and areas. Completion times remain lengthy, with an average of five months between an offer being accepted and completion.
According to our latest Rental Tracker[2], the rental market remains very busy, with an estimated 50,000 properties needed to return the supply of rental properties to pre-pandemic levels. With an 18% increase in listings availability in the first four months of 2024 compared to the same period in 2023, rental agents received an average of 14 leads per available property, and average rents were 7.6% higher than the same period in 2023.”
Paul’s opinion - It's a wonderfully profitable business, but I’ve always seen Rightmove shares as potentially vulnerable to unexpected competitive threats, as they price gouge estate agent customers, making excessive profits. So far, the fortress has remained intact against ineffective competitors.
The network effect means RMV has remained dominant, but it now has 2 well-funded competitors, since OTMP was taken private.
RMV shares have oscillated sideways for 5-years, so as a mature, cash cow business has it paid out monster divis? No! They’re rubbish, at just 1.7% yield. It has done a lot of buybacks though, but should a company on a PER of 21 be using its surplus cash to buy back shares? I’d say no. Also buybacks are often a screen for overly generous share options for management. The Directors transactions page shows that management seem to regard free share options as bonuses to be cashed in, rather than their intended purpose to allow them to build up a meaningful personal shareholding.
I know lots of readers will disagree with me here, which is fine, my stuff is just one individual’s personal opinions, frequently the market will do something different. We like a discussion of bulls vs bears, providing it’s kept polite, so I’d be keen to hear more bullish views on why you think RMV shares are a better risk:reward than I do!
One bull point might be that it could attract a US bidder, keen to price gouge customers even more, with aggressive price hikes (as we’ve seen in some horrible cases with important drugs) maybe? On the basis that estate agents don’t really have any choice but to list on Rightmove.
TT electronics (LON:TTG)
Down 6% to 160p (£284m) - AGM Trading Update - Paul - AMBER/GREEN
TT Electronics plc ("TT", "the Group"), a global engineer and manufacturer of electronic solutions for critical applications, publishes the following trading update on the Group's performance for the four months to 30 April 2024 (the "period"), ahead of the AGM taking place later today.
Full year outlook unchanged, on track for 10% operating margin target
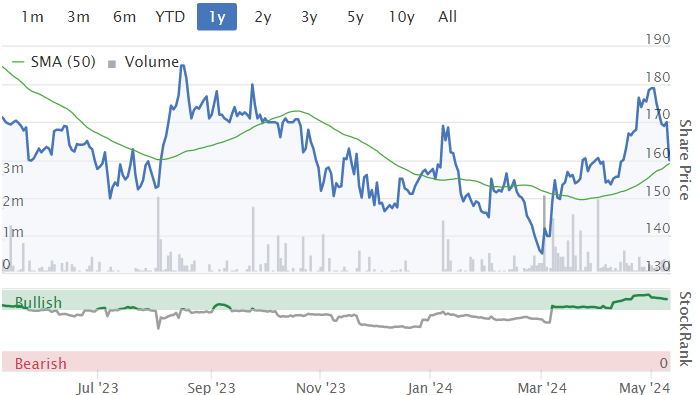
The detail is a bit less positive though, with customer de-stocking mentioned (expected to normalise in H2), and an increased H2 profit weighting, which is bound to unsettle some investors a bit. Hence I can see why the share price has recently given up its sharp gains of the previous month.
Paul’s opinion - Graham normally covers TTG, and he’s been positive recently. The StockReport metrics look good, with a forward PER of only 8.4x, a reasonable yield of 4.4%.
Could it become a bid target maybe? Cheap, decent quality companies with fragmented shareholder registers often do.
My only reservation with TTG is that I think it made too many debt-fuelled acquisitions, but has been taking steps to reduce its rather toppy bank borrowings more recently. Hence perhaps it would make more sense to pause the divis to focus on debt reduction instead? Actually, I might moderate a little from green to AMBER/GREEN, let’s hope Graham doesn’t mind too much! (whoever writes the report gets the crayons to do the colouring-in!)
Mothercare (LON:MTC)
Down 24% to 4.7p (£27m) - Trading Update FY 3/2024 - Paul - RED
I last looked at this on 24/11/2023 - H1 results were better than I expected, but the debt & pension deficit are the big issues on which the survival of the company hinges.
Sales are now through franchisees, and fell 13% ni FY 3/2024 - not a healthy position.
Adj EBITDA is OK though, in line with market expectations and flat vs LY at £6.7m.
Net debt is now £14.7m, and pension deficit (accounting or actuarial?) unchanged at £35m. Note that H1 results contained a “material uncertainty” over going concern, specifically mentioning the willingness of the existing lender to continue supporting it.
Today’s update points very clearly towards the likely need for an equity placing -
With interest rates remaining at an elevated level, the interest rate on the Group’s existing loan facility is currently approximately 19.2%, which coupled with the extended time to return to pre-pandemic retail sales levels, particularly in our Middle Eastern markets, highlighted above, means the Board’s current forecasts for continuing operations show the Group requires waivers to our covenant tests.
We have therefore commenced refinancing discussions with our lender to vary, renegotiate or refinance this debt facility.
Additionally, we are well advanced in looking at various financing alternatives (including equity and equity linked structures) to give us both additional flexibility and reduced cash financing costs. For the avoidance of doubt the Group does not require (and is not seeking through this refinancing) additional liquidity.
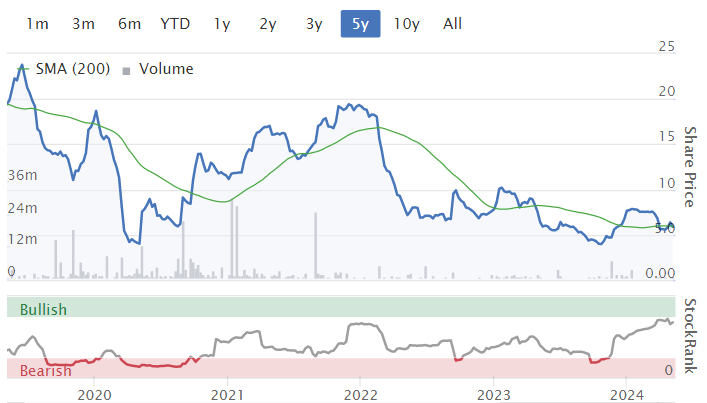
Paul’s opinion - you know my view on struggling micro caps that need more equity! Why get involved, when you often end up being a lamb to the slaughter, powerless as new equity providers just name their price, and can easily largely wipe out existing holders. What’s the betting we end up with a 1p equity raise here, and existing holders then feel forced to average down, sucking you in deeper than you ever intended?
I actually think this is a salvageable business, because the newish capital-light model, where MTC doesn’t buy any stock, just charges franchise fees, is actually quite good. Although franchisees might go bust or close down unprofitable sites, so it’s not a long-term solution if sales continue falling.
If it manages to refinance, then shares could be worth considering, but for now there’s too much risk for fairly limited upside, even if things do work out, you might only value it on an EV of say 7x EBITDA, so maybe £50m debt-free, less the debt is £35m for equity - which isn’t much above existing equity of £27m. And that doesn’t even consider the yawning pension deficit. Risk:reward just isn’t right for me, so I’ll watch from the sidelines thanks.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

117 comments
Ultimate Products (LON:ULTP) - Q3 Trading Update - Investor presentation video recording now available:
?si=56MwdK71_E8WWX4YUltimate Products hosted an Investor Presentation for retail investors following the company's recent Trading Update for the period from 1 Feb to 30 Apr 2024. Andrew Gossage (CEO) highlighted how trading has been impacted by a slowdown in near-term sales from landed stocks, typically at higher gross margins, reflecting the broader slowdown seen in retail sales to consumers. Updated expectations for FY24 have now been communicated, but management outlined reasons for confidence in the Group's prospects for FY25. There was also a detailed Q&A session with numerous questions having been submitted by viewers.
Classic podcast Paul, informative and amusing.
On a different mater , I’m on two week trial , on occasions company information is blocked from me , there is a padlock sign everywhere. Why is this ??
Are they UK listed stocks?
Not sure how the trial work, long time since I used it.
I get that on stocks in areas, l'm not subscribing to, such as Europe, Asia and Canada.
Yeah it only happens when you aren't subscribed to the specific regions data feeds.I only have UK and US as an addition.Everything else appears padlocked.
Despite holding Ultimate Products (LON:ULTP) and TT electronics (LON:TTG) managed to eke out a profit today.
Other portfolio shares came in with 2%+ increases - Begbies Traynor (LON:BEG) , Bodycote (LON:BOY) , Castings (LON:CGS) , Jupiter Fund Management (LON:JUP) and Cairn Homes (LON:CRN) .
I only mention it because the London market finally seems to have a tailwind looking at my stats. The FTSE All Share is only slightly behind the S&P YTD - although the FTSE 250 and AIM have a bit of catching up to do (but at least they're not negative anymore).
About time !
Or have I just jinxed it.
GLA
Here's hoping the Invesco QQQ Trust Series 1 (NMQ:QQQ) s are finally fairly valued.And finally time for some sector rotation, including to the UK's home companies.About time!!
Boohoo (LON:BOO) ASOS (LON:ASC) London Stock Exchange (LON:LSEG).Reuters recently reported tha Shein is preparing for an LSE listing following further US regulatory issues and pushback from US lawmakers.It still needs China's approval.Plans to file with the London Stock Exchange (LON:LSEG) as soon as this month reportedly.Latest private fundraising round valuing the company at $66 billion.
And according to the Sun ,the boss of Boohoo (LON:BOO) has urged the Government to plug a tax loophole exploited by Shein — before it attempts to list in London.Good luck there mate.
Is it just me or have the last few days been full of RED rated companies in the SCVR!
Hi Nanotrader09,
Is it just me or have the last few days been full of RED rated companies in the SCVR!
Bear in mind that's probably because I look at the big percentage movers in my fairly new "mid morning movers" (MMM) section. Lots of those are utter crud, but I'm trying to get something into our archive for quick reference in future, and to widen our coverage from last year's 609 total unique companies.
Also occasionally I do unearth something interesting that's moved on an important announcement. Or more importantly, I can warn people away from jam tomorrow rubbish that are trying to ramp up their share price before the next placing.
They don't take me long to do, so it's additional, not instead of, the other companies.
P.
Hi Paul, just wanted to clarify I didn't mean any offence, just a reflection of the crap announcements coming out. I love the SCVR, it's officially a must read along with your podcasts (only last weekend my wife moaned "not this guy again" when I was listening to your podcast out loud whilst folding the clothes!)
LOL I might have been a bit prickly in the past, but am much more chilled out these days, so it's fine to query or discuss anything :-) Good to hear you like my podcasts (sorry your other half doesn't share your enthusiasm! It is rather dry material. I might have to dream up some new features to spice it up a bit possibly - leave it with me!
Ultimate Products (LON:ULTP) Sorry to be a bit late to the discussion today. I had hoped this would be a little peach. A GARPy little backwater stock that was, until today, negotiating a tricky consumer downturn with great aplomb. Instead, only a month after being told all is well in Oldham, we find the progress has hit a major obstacle that will not only hit this year's profits by 20%, but next by 10% as well. That, to me is not the definition of a bump in the road - because it's hitting two years of profits, not just one. And I see next year's profit at risk against the revised numbers because instead of rising 10%, they now have to increase from this year's lowered output by 20% (numbers somewhat simplified - but please get my drift). All companies hit difficulties. But I'm not prepared to own something that is so easily and significantly knocked off course by small hitches.
OR Management was lying to us in mid-April.
Either way, I'm oot.
BnB
‘Either way, I'm oot.’
Me tae, Jimmy – selt this mornin. Likely to add the funds to my existing Volex (LON:VLX) holding.
Ultimate Products (LON:ULTP) Completely agree BnB, I do feel a bit conned by management. I'm now out, and used the cash to top up elsewhere.
I’m not sure I will ever understand how private investors can invest their hard earned cash in a company without understanding it properly or the industry it’s in. Ultimate Products (LON:ULTP) value lies in the brands they own and manage. Nothing in their statement undermines that. The sector they operate in is essentially retail. By nature, this is capricious and target misses are to be part and parcel of the industry, particularly with the expectation of year on year increases.
Ultimately, they manufacture mass market, popular products and sell them. They have a reputation for doing that effectively and profitably and their products (brands) have a reputation for being well made at their level. I see nothing in the announcement this morning that makes me think any of that has changed. Of course its a shame they will be making less than anticipated this year, but who makes investment decisions on the basis of one year’s profits?
If your investing on the fundamentals of the business, nothing has changed.
Don't want to argue, but Paul downgrading Ultimate Products (LON:ULTP) from Green in his last report to Amber, DOES suggest the fundamentals have changed. We all invest differently, and in this case I'm with Bnb and JimMcLad on this one. I dont want to be aboard the rollercoaster ride!
Agreed. I held this but sold a few months ago having come to the conclusion that it’s a nice business but perhaps not the acquisition machine that I had hoped. There don’t appear to be any Salter type deals in the pipe., and without that one is reliant on growth in Europe of which I am a little sceptical. I would still buy it again at cheaper levels as I think it’s a very well run business with mgt holding significant skin in the game. Just not sure it’s a growth compounder.
I’d be interested to know in what way anyone thinks the fundamentals have changed. I’m not averse to changing my mind on an investment if I have missed something, but as far as I can see it is just an earning miss - a temporary blip and not symptomatic of a deeper malady.
In more general terms, fundamentals suggest Ultimate Products (LON:ULTP) will compound healthily over time, though probably not in the shoot-the-lights-out 100 fold sense. But if that’s what you are after (with all the attendant risk) why would you be looking in the UK market?
Hi RB, I sold last week after holding for many years, mainly due to the fact, in April everything was in line, one month later, profit warning, how did management not know?
It now puts doubt about anything they release, so in this market where any bad news is hit hard, I decided to sell up, what is it they say about profit warnings, come in 3s?
Ultimate Products (LON:ULTP) the point is that management have lost our trust. The business itself is fine. A month ago it was all dandy and now they give us a profit warning and announce a buyback at the same time, with the share price 25% lower. This has been choreographed and I don't like it. Which means I'm no longer a holder and am now unlikely to be one again.
Or, to put the same point another way, investors believed they owned a mini Diploma (LON:DPLM) but now have fled because of the similarities to XP Power (LON:XPP.
I’m pretty sure it’s not as stark as that and that Ultimate Products (LON:ULTP) will steady the ship. But sudden and surprising reversals in fortune are kryptonite to investors.
RE:Ultimate Products
Clearly something has changed since the April Investor presentation which didnt obviously hint at a reversal of fortunes.
An issue for UP is that it is a fairly small supplier to larger retailers with a market cap of only 127 million. I would suspect that it has limited bargaining power if the retailer decides to change its ordering agreements and schedules.
There would also be some difficulty in giving a specific reason for any slowdown which might suggest a slowdown in any particular quoted retailer. Hence a possible reason for the vague out of the blue announcement.
We know that airfryers have likely peaked and probably inflated turnover for a while. Any additional slowdown is another drag on performance.
I dont think that this is a bad company, but it's position in the supply chain looks at bit vulnerable to trading fluctuations from its retail customers.
Dont hold
Afternoon all,
Tirupati Graphite (LON:TGR - thanks for the IMO entirely correct quick synopsis above. Commiserations to any holders.
I first encountered Tirupati Graphite (LON:TGR) after a Daily Telegraph "Tip" on Oct 2021. The price was in the 90's but falling steadily. I merely tucked it away to watch and see.
In Nov '21 a rampy tipster (I won't name) described it as "most oversold at 66p". I set a price alert.
Price alerts are not to trigger a buy (the way I use Stocko), but just a trigger to take another look. 99% of (falling) price alerts with me are reset - lower.
In March 2024 I used the notes function here to record (note to self) "Very "cheap" now but project funding needed..."
Kept setting it lower and lower, almost now for fun. It alerted again today.
Why this post? Just to highlight that in the last couple of years, the main investing game for me has been dodging bullets like this. I haven't by any means dodged them all but this was a particularly harsh and egregious one, although I'm sure many here will say it's was obviously a bargepole. Tips and the like should at best be considered ideas for further research.
What bullets have you dodged lately? And what bullets hit their target and caused damage (hopefully not fatal)?
One of mine recently was James Fisher And Sons (LON:FSJ). Ouch.
For those of us following Volex(LON:VLX) - I see that it has broken a major resistance level of 400p today and had an above average volume of 1.5mill on the 7th may ( although it did not significantly move the price.) Revenue for 2023/24 was $900mil, an increase of 25% on 2022/23. This revenue includes 6 months of sales from Murat Ticaret (acquired in September) According to the original RNS for the acquisition Murat Ticaret had recurring revenue of $172mil/annum so there should be an additional circa. $80mil of revenue from Murat in 2024/25. Estimated profit for 2023/24 has increased to $53mill, +31.2% on 2022/23.
The company set out a five year plan in October 2019 to achieve $650 million in revenues and $65 million of underlying operating profit by 2024 --- It looks like they have achieved these goals plus some....
At the end of FY 2022/23 the company set out a new revised five year plan from 2023 to 2027 with the goal of achieving revenue of $1.2mill, underlying profit of 9-10% and revenue from acquisitions of €200mill. - All things being equal they are well on their way to achieving these goals also.
The share price peaked at 480p in Sept 2021 and then declined sharply with the rest of the market. IMO, if Volex can do a good job at integrating these acquisitions and achieve its goals it is difficult to see how it will not at least get back to this level and potentially higher, but time will tell..
Interested in alternative thoughts (I Hold)
I hold Volex (LON:VLX) where are you seeing 400p? I wish it was but it is around 343p on my screen.
Deleted
Hi Rambo,
i hate to disappoint you but the Volex (LON:VLX) sp is 343p today.
Sorry everyone, I meant to write 340p for VLX but must have got over excited - I believe the rest of the text is correct.
20% drop in Metals Exploration (LON:MTL) over the last few weeks
not seen any end updates or things which could have prompted this
thinking this may be a good entry point for a stocko 99 ranked share
Metals Exploration (LON:MTL) There was a RNS, yesterday: http://newsfile.refinitiv.com/...
about some dispute over the interest rates charged on loans. Lets hope it does not go to court.
I had a quick look at Metals Exploration (LON:MTL) yesterday when it was on the top % fallers list. Didn't publish anything, as I normally avoid the resources sector. But the numbers talked about in the dispute over mezzanine loan interest rates are quite small relative to the massive cashflows it's generating from gold production. Also it seems to be prepared to pay half the disputed amount, if I understood the RNS correctly?
The rest of the debt seems to have mostly been paid off.
I hesitate to offer a view on a sector I don't normally get involved in, so perhaps any readers more familiar with MTL could confirm if this is right or wrong? But my reading of the RNS, is the amounts in dispute look small, relative to the profits/cashflows, suggesting that this doesn't sound a major problem, just a dispute that MTL could probably fund whichever way it's resolved. Also, a previous RNS had disclosed this dispute already, so it wasn't a new issue.
I remember MTL from old, it's been around donkey's years as a jam tomorrow junior resource share. So quite nice to see one that has actually managed to progress to significant production, and lucky timing with the price of gold being high, substantial profits too. StockReport has it on a low forward PER.
I think Ed's system picked this one for his 2024 NAPS, which has worked out great!
Regards, Paul.
I agree appear small amounts in dispute but like me it is tempting to take profits
Thanks Paul. Yes it was included in Ed's NAP selection. I had a quick look but the spread was 769bps and it is small goldminer in the Philippines, so not for me. As the share price has gone up the spread has narrowed.
Yes the amounts in dispute look small, if the forecasts are correct. There are a lot of legal cases in the Philippines, their legal system is similar to the US.
Random fact... if I download from Stocko the top 200 UK shares with the highest price movement in the last month, it implies they today have an average Quality Rank of 46. The average Value Rank is similar at 45 but this would likely have been quite a bit higher one month ago (maybe in the 50's, I'm guessing). Looks to me as if the current (relative) euphoria in the UK market is not benefitting the higher quality shares so much.
Maybe the above makes sense. But the cynical part of me thinks there is probably quite a bit of smart money selling out into the current burst of excitement to then sit with their liquidity on a nice beach somewhere during the summer. None of the big geopolitical/macro financial issues have gone away last time I looked. Time to tread carefully I think rather than be too exuberant. If I'm wrong, why?
M48
Perhaps this is because it is the Ftse 250 and Small Cap/AIM stocks that have started to bounce back after eons of underperforming. One could take a view that the financial macro is improving as the inflation rate has dropped substantially year on year virtually everywhere, energy prices are significantly lower and recessions have been marginal if at all in ma y economies. Interest rates will be lower in almost if not all leading economies by year end too. If markets look ahead as they are presumed to and the Small Cap arena is set for recovery perhaps next year we can afford a better beach?
Not sure I under understand your point. I posted yesterday that the screen of top stockranks is up 15% ytd, 25% over 1year and 30% off the Oct low. I see no sign of this changing yet and in some cases the sp seems to be rocketing higher. All round Quality and value is very much what you want to own IMO. Don’t sell quality stocks that are just getting going.
Revs8 - I think the point, or really question, I was posing to myself as much as anyone else is whether the rally in the UK indices is going to prove sustainable or whether come the summer we find liquidity has dried up and/or we’ve walked all the way back down the wall of worry. I’d feel more comfortable it was sustainable if higher quality companies were driving what’s happening. My suspicion is it’s more the lesser quality/higher value type stocks that have recently seen a shift in sentiment.
That is probably the case over the last month but not over the last 3 or 6 months, judging by the StockRank performance history.
While may mean the quality stocks, have risen in the previous months and are now having a breather, but the lower quality stocks are playing catch up.
I would not read too much into 1 months figures.
To Stockopedia Team: Could you please add a required field when posting messages where users have to input the ticker (or 'N/A' if general discussion) for share being discussed, so that when anybody replies the ticker reference automatically gets carried over in any subsequent replies.
At the moment a lot of the replies are a bit cryptic as there is no reference to the original post!
Hi turbo, is this an issue of how some people sort comments? I sort the comments in threaded format, so it’s easy to see what people are replying to and responding on, but I sense others sort unthreaded.
I have previously been asked by another subscriber which stock I was commenting on when I directly replied to a comment and I suspect this was because the subscriber was not reading in a threaded format.
I am sure there are reasons people don’t read in a threaded format, but it seems a request to stockopedia to solve a problem that could be resolved by a subscriber changing how comments are viewed. What do I miss here, because it cannot be that simple I am sure!?
If you check the bulletin board 10-15 times per day you only want to read the new comments please James, hence unthreaded...
Agreed, just can’t cope with unwieldy unthreaded view
My apologies... I obviously wasn't articulate enough... I will use threaded if I have been out all day, but otherwise it has to be unthreaded ( 95 % of the time )...
I hate threaded format, just can't find comments. It is a mess. I want to see the latest comments, in the ordered they were posted. Take Ultimate Products (LON:ULTP) not everyone is replying to someone, there maybe 4 or 5 different threads running or just individual posts. If a recent post is published, l won't see it on threaded, if it replying to some earlier post, to find it l would have know which thread it was on. Far easier to read down in chronological order.
Hi Paul, would it be possible for the securities you mention in the Table show up in the "Securities Mentioned" on the right hand side of Stockopedia? I find the Table a very useful overview of the day and being able to flick through the securities on the right column would be even more useful. Keep up the good work!
Morning everyone. I've done some digging on Bloomsbury Publishing (LON:BMY) (I hold) this week and came up with conclusion that forecasts for FY 2/25 are greatly understated. As this company is well followed here in stocko community, I'll be glad if i someone corrected any mistakes here.
Focusing only on Childrens' Trade (56% of Group Profit). Sarah J Maas (SJM), based on my assumptions, her contribution has now eclipsed Harry Potter revenue. Her contributions growth 2017: £9million to 2023: £53million. FY24 should be above £60million.
Below are my notes for FY25 for Childrens' Trade :
1) SJM released 2 books per year until her kids were born. Now working on getting 1 book per year (interview link) The next release will focus on "ACOTAR" world. She has 6 books in contract for Bloomsbury , so contributions for maybe next 8-10 years.
2) As per Publisherweekly , for Q1 2024 SJMs' two books sold print copies were (868k) Note: This does not include any translated books and BMY holds worldwide release rights for all SJMs books.
3) Most interesting point of my analysis is this one - Circana publishes books analytics but it is paid research. Forbes revealed here that SJM has sold 3.1 million print copies (source circana) in 2024 so far, so i assume roughly 2 million are back catalogue which has higher margin. Not sure how much of this falls into FY 2/24 . But definetly it should be good start for FY 2/25.
4) SJM is now the most followed author in TikTok, most discussed author in "BookTok" tag.
Considering above points and if other divisions perform on par with FY 2/24, i think the forecast should be atleast 40% higher.
Risks :
1) SJM unavailability to write any future books (for any bad situations)
2) Nigel and Penny remuneration is too high and this year will definitely be more.
Nigel will present in mello on the results day 23 May.
Good luck.
Bloomsbury Publishing (LON:BMY)
Thank you for your post AD09 - excellent digging! Aside from one author absolutely smashing it out the park, I also think the general trend for books is positive with more and more content being produced using 'known hits' - e.g. Three Body Problem on Netflix (another Bloomsbury publication which is super popular) or TV series now being based on successful video game titles (The Last of Us, Fallout...) We'll never stop telling stories, and I think writing a book is the most accessible way for people to do that.
On a related topic, something that's been on my mind is the cut to arts & culture courses in the UK and how that might affect their non-consumer income. I believe they specalise in fashion, drama, culture etc. which seem to be the first courses on the chopping block. Could be a good question to ask at Mello if you're attending? (Sadly I can't.) Either way, whilst their most successful author is 'outperforming' it's worth recognising the other half of their business, which I believe is where their recent growth has really stemmed from. (I hold)
Agree Jacxx.
Bloomsbury Publishing (LON:BMY) online academic content is overshadowed by the hype around their authors. It's strength was covered by Paul Hill in one of his Vox Market videos: https://www.youtube.com/watch?...
I agree that it is likely that forecasts for 2025 are likely to be raised with the final results. I have missed out on a fair bit of the share price rise so far as I had misjudged how successful SJ Maas was becoming. Must be more than simple luck to now have two smash hit authors on their books!
However, I don't agree when you say that "non-consumer income is where their growth has come from" Jacxx. If you look closely at previous years you will see that effectively Bloomsbury have been pouring most of their spare cashflow into Academic & Professional acquisitions and by and large achieving little or no organic growth from the division. My original investment in Bloomsbury was predicated on this shift towards the higher margin less volatile A&P sector and the reason that I sold was my perception that this division, whilst not a disaster, was making precious little progress. It will be interesting what they say on 23rd May because I still believe that long-term success depends on this division.
Great post AD09. I have held Bloomsbury Publishing (LON:BMY) for many a year and they just keep on delivering.
AD09,
An interesting Bloomsbury Publishing (LON:BMY) piece of scuttlebutt which prompted me to look back at the last “Significantly Exceed Expectations” covered by Paul in February. Back then it wasn’t at all clear what uprated earnings figures Bloomsbury were alluding to, leaving Paul to make a guesstimate at 40p EPS.
…..It was 36p EPS before today, so significantly ahead could mean say 40p? Maybe more . Well the company knows, they’ve just declined to tell us. Also the company probably wants to keep it vague to allow for any audit adjustments.
Then their broker upgraded FY2.2024 EPS from 36p to a massive 45.8p (Stocko numbers) dropping the PE to a lowly 11.9. Equally strange the broker did not upgrade YE 2.2025 suggesting a EPS of just 32.2p. This just does not make sense with +16% EPS CAGR over the previous 5 years. So it looks to me as though Bloomsbury is set for more earnings surprises and upgrades, and that the forward broker numbers are set unrealistically low.
Looks to me like wonderful opportunity, hiding in plain sight. We will know more on May 23rd.
Bloomsbury Publishing (LON:BMY)
As an aside I was in Waterstones earlier this week and asked how Sarah J Mass books were selling. The shop assistant said that they struggle to keep up with demand. No sooner are they delivered than they sell out.
Anedoctal I know, but adds to the debate that Bloomsbury Publishing (LON:BMY) is performing better than its share price suggests.
I have been invested for a number of years.
Cairn Homes (LON:CRN)
Nice reassuring "in-line" trading update given the high forecast growth.
The 2025 is begininning to look a bit light to me on the basis of this update - but time will tell.
Quite amazing the difference between the UK and Ireland housing markets at the moment.
A.
(I hold)
Agree Albertos. I hold Glenveagh Properties (LON:GLV) . Ireland as a huge housing shortage- as does UK. Difference is the Irish Government has acted. Planning applications momentum has got a lot faster. The government "Housing for All" initiative is designed to meet housing needs in Ireland- they need 33000 house p.a to be built for at least the next 6 years. Sadly the current UK gov seem incapable of doing anything similar.
Re Cairn Homes (LON:CRN) and Glenveagh Properties (LON:GLV) the Irish market is buoyant and positive....and the number you quote does not take account of the housing needs for the flood of asylum seekers coming across from Northern Ireland, currently and due to continue!
A slight humorous inclusion intended,on my part, though not humorous to the Irish government of course.
A lot of asylum seeks are currently in hotels- hence high rates and room shortages in Dublin. I hold Dalata Hotel (LON:DAL) .
Was it Dalata Hotel (LON:DAL) that recently warned that rates in Dublin were very soft, due to too much supply from new hotels coming online recently?
I agree with the optimistic views given on the Irish Housebuilding market.
There is a much younger age demographic in Ireland and immigration is I believe higher in percentage terms than the UK hence the increases in demand. The Irish Government are also providing assistance to potential buyers to buy a home.
Irish mortgage rates are already lower than those in the UK and this could be exacerbated if the expected cut from the ECB happens next month.
I bought Cairn Homes (LON:CRN) about five months ago and it has done well. This company was brought to my attention by an excellent interview that Paul Hill did with John Hughman the former Editor of Investors Chronicle.
It is also good to see that CRN qualifies for the Jim Slater screen which I understand to be the most successful Guru Screen since inception.
My folios all stuck at yesterday's prices. Just me or a wider problem?
Same here. have sent a message.
Hi Steven,Thank you for flagging this, it seems we have a bit of an issue with price data coming through. Our developers are on the case and hopefully the issue will be resolved quickly. All the best, Megan
Same for me.
Some prices were, some were not. Took 70minutes for Ultimate Products (LON:ULTP) to move and 3i (LON:III) but others were only 20 minutes behind live. Prices have been a mess recently on here. Some folios were showing up 7% but then after the close went back to real prices. This was on some large caps, showing +11%.
Re: Ultimate Products
I would be interested to see if reduction of volume is related to B&M European Value Retail SA (LON:BME) and whether this reads across to the retailer.
Dont hold either and would take some convincing to hold Ultimate Products (LON:ULTP) after this announcement.
Ultimate Products
Just think it’s simpler explanation and everyone was getting a bit carried away with them .
Ok Company with good management in an average sector selling average products that have no IP apart from a few brand names probably Salter good .
Old school distribution channels
Nothing at all to stop their customers and competitors jumping on a plane to China and sourcing directly exactly (or pretty much exactly ) the same products and putting their own logo on .
No real competitive advantage means they can’t increase margins .
No IP or brand names of strength means their retailers will simply stock the ultimate products and put their own alongside .
The irony is “ultimate products” implies great world class products not middle of the market Chinese electrical. Fodder being sold to the Uk market .
Nothing wrong with the company and nothing wrong with buying and selling average middle of the road electrical itens that anyone can copy .
Looks ok to me on valuation but it’s just not a company I would ever want to own because it is all just average and predictable making electrical appliances out of China with nothing unique or interesting .
But still a nice company making a few quid return for its shareholders with an honest management doing their best .
But what the brand names? Yes you can copy the products and stick another brand name on it. But many people will buy a well known and regarded brand, these take many years to built up. Cheap Chinese products have a poor reputation.
Yes i think there was a lot of bullish talk about this stock recently, share price went to 180p, where l sold, been looking to get out for some time. I think around 135p the shares are good value.
John Lewis could put John Lewis on , that’s a brand name with heritage
Tesco could put Tesco on
Lidl could put Lidl on
There’s some American tax avoiding bozo who has a brand called Amazon that is well known for selling a companies products then using the sales data to find the best sellers and launch his own brand
I could start and put “Penultimate products “
Chinese products have a good reputation and that’s who ultimate products are re selling Chinese products
Go to decathlon - they are full of “brand names” they started recently that are all owned by decathlon and they sell these alongside the branded products
Point of fact I spoke to a Turkish supplier that was supplying rapha the blue chip cycling brand supposedly thes best of the best , he told me he supplied decathlon also
I said along the lines “crikey how come you supply own brand to decathlon at one end and the kings jewels to rapha “
He smiled “Dave you have no idea the items we supply to decathlon and their tech packs and quality control is by far the best in the industry . Way better than rapha “
Anyway I digress ,
I for one enjoy your digressions planetx, you're a been there done that guy. I tried to sell our Ultimate Products holding at 8.00am after reading the PW but couldn't get a price for 15 minutes on not so smart Barclays Smart Investor. We're still on profit but I think it might recover a bit when the buyback kicks in.
Well you would have to pay me, to have products with Tesco, on my worktop, l would be willing pay a bit more for Russell Hobbs than Tescos. Lidl maybe ok if cheap enough and decent quality. John Lewis ok if not paying too much of a premium.
l'm not a brand name fan but many people are.
If toasters or kettles were in Lidl, surely they'd be called "Bustle Chobbs", or "Dalter", or "Hussell Robbs"?
Re Ultimate Products / B &M Bargains
I think I was looking at this more from a B&M European Value Retail SA (LON:BME) pesrpective.
The last few times I have been in the store it looks quite tired. The whole back ailse of the store is devoted to electricals, many I would guesss are Ultimate Products (LON:ULTP) brands - which seem popular with students around August / September.
Checkout at the store seems down one main counter with a very slow kiosk. Competition from Ald, Lidl and Home Bargains is quite intense in the area (Home Bargains being a privately held regional business). Our local Hoime Bargains store is non electrical but very busy and it occured to me that it must be taking footfall from eleswhere.
I was wondering if the problem was not just a ULTP problem but also a BME problem. Interested to hear views on this one.
No connection with Home Bargains
Ultimate Products (LON:ULTP)
Fair comments here this morning on the company but I rather suspect you'd get on well with the boss there planetx. A pal of mine was a buyer for a major grocery chain in non foods for years. Went to work for Ultimate for a couple of years after and said he learnt more there than in his whole career with the major. Simon may be sharp but apparently runs a very good outfit. Shame they can't manage their investor relations and market expectations as well.
Ultimate
I think you’re probably right it’s a very good trading business established and it’s doing the day job .
I quite like it when management are clearly focussed on doing the day to day .
Honestly always surprises me how a quarterly result knocks 20% off a companies valuation and everyone panics .
I once became drawn to being a leading brand with the high margins that commands and big tick of the ego box as opposed to the wheeler dealer buy cheap sell cheap bottom feeder some industry big wigs would have called us .
It was Dave Brailsford who pulled me back and said we need to dominate the middle ground , that’s lower risk and where our place was and importantly where the money was .
He said “don’t try to be man united be middle of the table “
Of course the industry big wigs invariably disappeared and we kept doing the day job
- stuff comes in
- stuff goes out
- we buy for one , we sell for 2
So back to ultimate , good entrepreneurial company with good management selling electrical products to established channels
If they keep the prices tight and margin tight they’ll keep knocking out the numbers year on year out
But not going to win the premier league and play in Europe .
"But not going to win the premier league and play in Europe ."
Prescient, I think, ... and nor is Manchester United for quite a while, IMHO. Anyway, my interests lie further North (proper North). So what do I care?
I encountered similar with Halifax prices risers/fallers around 9.00 AM this morning so there may be a wider issue.
Hi all and Happy Friday. Yesterday's discussion re: ideal no. of positions got me thinking about my investing journey so far. I started investing mainly in funds when I was in my early 20s, I'm now late 30s and have learnt a lot along the way.
Firstly the most common mistake I did was hold onto my losses - I've had some dreadful losses up to 90% (!!) in some stocks as I always thought "they'd come back" - wrong! As per lot of literature from Mark Miniverni and Bill O Neil, cutting losses is the key to successful investing. I know a lot of people on here have also had massive losses but human nature unfortunately means no-one wants to be wrong and so we stubbornly hold onto them and watch our accounts shrink more and more.
I started to dabble in US stocks over the last couple of years and my returns have vastly improved since that time. Admittedly UK markets, especially small caps which we all follow and love, have been in a turbulent bear market in that time too.
The other thing I've noticed is that my returns have gotten much better since I restricted the no. of stocks I hold. I used to hold 30+, I now rarely allow more than 10 stocks. I prefer to "load up the boat" on my strongest convictions - currently Rolls Royce, TMDX, DELL, NVDA, APP, VRT. I am also paying more attention to charts (I never was a chartist) in order to work out best times to buy / sell. The Stockranks / reports have been invaluable for me too.
Not saying my method is the right way at all - we all have different lifestyles, income situation, risk profiles etc and a lot of the time it depends on the market trend - easy to make money in a roaring bull market after all. But just thought I'd share my thoughts regardless! Have a fantastic weekend all.
Thanks for the update. But holding only 10 shares would be very high risk for me.
Great when you are following the US tech bubble upwards, horrible otherwise.
Thanks for telling us about your approach to investing Dulpesh. Since the late 1970s I have been investing and agree about your comment about including the US in your universe of investing. I also include other developed countries and foreign companies have provided me with some of the best long term returns This is perhaps not surprising when you think of the size of the home market for US companies and the cheapness of energy and land for expansion they benefit from. I would also add that I find quite a few successful serial acquirers abroad and this is a fertile area for multi-baggers. However, perhaps my preference is a reflection of my need to find high quality companies as I am normally a buy and hold investor. Perhaps sticking to the home market may be fine if you are a news driven investor and trade more frequently. I must admit I do hold more than 30 stocks (10 would be too few for me) and have no problem finding good ideas when my investing universe is so large.
Surely Ultimate Products (LON:ULTP) knew Q3 was weak when they announced the H1 results a month ago? That was two months and a week into Q3. Instead, management say nothing then, false market for a month? And then they extrapolate a weak Q3 into Q4 so that their buyback scheme can start when they have given their own SP a good kicking. What lovely behaviour.
All IMHO
Great time for a buyback though. I agree that it does look somewhat fortuitous given large management stake. It beats starting a buyback at the top that’s for sure. As a long term holder (at an average that is a fraction of todays price) I am not moaning. Still think it’s a well run business overall with decent prospects long term. Earnings are always a bit lumpy - it has history, but overall a very cash generative business.
Certainly a jarring and disappointing change of tone since the April RNS. I don't know their ordering cycle and maybe several customers have signaled reduced forward ordering since then? It would be useful for the management to outline why this change has occurred in a it more detail, to avoid any feeling that they should have tempered their more positive earlier release. It wouldn't be difficult to imagine some buying occurred on previous announcements of Buy Backs etc., so there will be some sore feelings for those that were drawn in.
I was nearly bought myself to increment my current holding, but my usual hesitancy for once has saved me that regret at least!
20% fall for Ultimate Products (LON:ULTP) todsy despite their 98 stocko ranking
Never a better time for Ultimate Products (LON:ULTP) to begin its £1m buy back!
"The UK's economy emerged from recession at the start of the year, official figures show.
The economy grew by a stronger-than-expected 0.6% between January and March, the Office for National Statistics (ONS) said.
The UK had fallen into recession last year after the economy contracted for two three-month periods in a row."
Source: BBC https://www.bbc.co.uk/news/bus...
Brickability (LON:BRCK)
559,750 shares bought at 67.49 by Douglas Bryce, MD of the contracting division, who I suspect is not a board member. That is £377, 271 of his own money. Senior management only splash the cash for one reason and it is not because they think the prospects are poor.
Definitely a buy and certainly not beer money. Happy to remain invested.
Ultimate Products (LON:ULTP)
Disappointing near term, but it appears that the business is on track for the year to July 2025. A moderate holding; happy to stay the course, providing the narrative turns out as expected. From memory the company has minimal debt.
On the positive side it is a good time to start the share buy back programme, as I expect the shares to be hit this morning, but if it follows the recent phenomenon insofar as share prices are concerned I wouldn't be surprised to see them bounce back somewhat later in the day?
Funny how this community can work. I read your comment, did a small amount of "research" bought a reasonable chunk of Brickability (LON:BRCK) and am up a small holiday somewhere by 3:30pm. Of course, it can all go to crap in the next hour, but thanks all the same for the moment!
Ultimate Products (LON:ULTP) I hold
No indication of any problem in their interim results a month ago so, for me at least, this has come out of the blue. I really like the management and have high hopes for their further penetration of the European market in due course which could provide years of growth. However, until we see some positive momentum to earnings, probably reported in six months at the earliest, I can't see the shares recovering from wherever they settle in the next few days (My guess would be at about 130 to 140p).
Ultimate Products (LON:ULTP) I must be the worst stock picker on this board, I only bought into these a month ago. Seems to happen to me far too often!
Maybe not. What did you do this morning?
Brickability (LON:BRCK) is that another director sell as they say or a purchase (as they also say)!
Someone's having a bad day at BRCK aren't they, replacement RNS still has sale in the table! Presume its a buy and he previously had no shares. Offset by the sale a day or two ago from another dir
Ultimate Products (LON:ULTP) - "Near term disruption, but growth case remains strong"
Ultimate Products announces today that sales revenue fell by 7% in its FY2024 third quarter and is anticipated to remain in negative territory in Q4. As a result, the company believes that EBITDA will now be in the range of £17.5m to £18.5m compared with a current market consensus figure of £21.5m. Given the 17% cut in current year EBITDA expectations it seems prudent to adjust our fair value / share figure by a similar amount. So, we reduce it by 20% from 250p to 200p.
However, current sales setbacks look likely to prove temporary. The company clearly states its confidence in the group’s prospects for FY2025 as a whole.
UP’s core franchise values and investor attractions remain intact despite recent disruption. The company generates around two thirds of sales from the Beldray and Salter brands and continues to work on the improved messaging around these two important homewares goods names. Additionally, the business is structured as attractively capital light, due to outsourced manufacturing with positive implications for return on net equity and free cash flow.
Link to research note: https://www.equitydevelopment.co.uk/research/near-term-disruption-but-growth-case-remains-strong
I would agree that Ultimate Products (LON:ULTP) management focus seems to be on improved messaging.
Replying to Neville yesterday
“does anyone have any favourites that perhaps have been overlooked these past few weeks please? The only bad thing about sentiment turning is that it's harder to find the really deep value...
The following may fit - Saga(LON:SAGA) Somero Enterprises(LON:SOM) Sanderson Design(LON:SDG) Intercede (LON:IGP) Plexus Holdings (LON:POS)”
SDG for sure which keeps getting dragged back down and popping up and down is the standout .
Add Pennant which has been buyable in the 28s but popped up yesterday not sure if your going to see 28s again
Add Wynnstay but that has just lifted a bit too that’s exceptional value if a little steady .
If you can stomach the geo political noise Georgia capital is arguably pull back opportunity but might be volatile until the elections
I’ve had a very strong move upwards in the past few days with upward moves on Avingtrans , Vertu , Transense , Croma , MS international , Speedy Hire , Filtronic , Hargreaves
So Ifir your list
SDG
Wynnstsy
Pennant
I was vocal about Transense but that’s made its move and now seems to be settling in the 120s .
Morning planetX
From my portfolio, I will be looking to add to Sanderson Design (LON:SDG) and Michelmersh Brick Holdings (LON:MBH) . Both should benefit from improving sentiment in the housing market, have cash on the balance sheet, have yet to go XD and remain under valued in my view.
Super grateful for your help and time planetx... this is very useful and thank you also for getting me into Wynnstay and Transense near the lows ... such a steep learning curve for me and the thoughts of you and others are very insightful... genuinely thank you...
Cancun
Your welcome, I’ll take all the credit on the risers and forget to mention the cock ups (holders )
Glad you caught Transese. . Looks to be a bit frothy right now heading into the 130s
Be careful not many sellers at moment so it’s travelling too fast , I was expecting a pull back after 115 and even trimmed 5% as I needed some cash to pay for the trees that the weevils had eaten .
I'm only ever going to congratulate the winners and not mention the losers... the latter are definitely my fault as I'm the one doing extra research and pulling the trigger ... screens are great, but it just needs a few people prompting ' have you looked at X ' .. I'll try to dig out a couple of suggestions of my own this afternoon when I get a minute, but I don't have the experience/ accounting skills that a lot of you guys do ... many thanks once again...
Cancun
I have close to zero accounting skills .
Wouldbt let that stop you and on occasions it’s actually helpful in assessing a business as sometimes it’s just not about the hard cold numbers (eg Filtronic recently ) .
I’ve made a fool of myself quite a few times so would welcome some company in the financially illiterate oops corner .
I’ve made a fool of myself quite a few times so would welcome some company in the financially illiterate oops corner .
Count me in as another accounting dunce. Ironically, I've just been appointed Treasurer at a sizeable social enterprise where I volunteer. I have found through my various enterprises that good common business sense and a strong feel for margins and cashflow are vastly more useful than understanding depreciation, treatment of leases and, frankly, being able to read a balance sheet (but this last one only because those companies never borrowed a penny from anyone but me).
3 of my holdings that don't seem to have participated in the last few weeks rally that still look very cheap and might prompt further research ... Somero Enterprises (LON:SOM) , Sigmaroc (LON:SRC) and Eagle Eye Solutions (LON:EYE) . Eagle eye had a small bounce on the Tesco news ... but given my inexperience obviously DYOR please... good weekend to all ...
Also looking out for potential bargains that have so far lagged the recent rally - agree on Sanderson Design (LON:SDG) but spotted quite a few decent quality shares which have been pretty flat over the last month or so - the ones I'd highlight are Whitbread (LON:WTB) Newriver Reit (LON:NRR) Henry Boot (LON:BOOT) Secure Trust Bank (LON:STB) Duke Capital (LON:DUKE) Michelmersh Brick Holdings (LON:MBH) and Chesnara (LON:CSN)
Coincidentally, I spent two hours yesterday looking at Sanderson Design (LON:SDG) again, after their FY results. Been a share I've tracked for a while, but was lukewarm at best before. Now much more positive.
I wrote up a short note on my thoughts here, so won't rehash.
But the TL;DR version is that I see the current price as a great entry price point if one plans to hold for at least 1 year... however, I do think they have a mountain to climb to meet market expectations for their HY Jul24, with licensing income being the Achilles Heel in the short term. As licensing drove the vast majority of profits, the EBTIDA, PBT levels are going to look really bad, YoY. So I sense there is an opportunity to pick up even cheaper post H1 results.
Sanderson Design (LON:SDG) Thanks for the write up - any particular reason why you think licencing income will be down in H1? This is obviously key as it has propped up earnings recently. They do seem to be signing a lot of new deals with a wide range of clients both here and in the US. I'm hoping this will provide a bit of diversification and limit any major falls, but not easy to do detailed analysis on this.
Sanderson Design (LON:SDG)
So total licensing income in the last two half years:
The formula used to calculate this is (Underlying licensing income) minus (prior year accelerated income attributed to this year) plus (current year accelerated income booked). The two tables below, from the latest FY24 presentation, is a good illustration.
As you can see, last year was a huge bumper amount of Accelerated Income Booked. £6.5m worth.
However, like amortisation, this then provides a drag in future years ("prior year accelerated income" column above).
I have a spreadsheet where I've tried to model out this for H1-25, too complex to write in text in a Stock comment... and what I get is £3.4m for licensing in H1. So far, including the £2m renewals announced. There's still two more months to go in H1, so assuming another extra £1m contract signed, that would be £4.4m.
Compared to the £6.8m last year.
That shortfall of £2.4m falls straight to the bottom line, so PBT will be hit by £2.4m. Last year was £6.8m PBT, so quite a big chunk out.
And that's before you factor in further revenue and profit declines in Brand and Manufacturing (I'm expecting low single digits? Maybe 1-3% given the moribund state of the UK and EU housing markets, still).
--------
Its difficult to see, if the headline PBT for H1-25 declines YoY, can brokers really keep their FY-25 forecasts as a +15% EPS increase? Or they do, but it comes with the dreaded wording of "H2 weighting" and then there is genuine pressure for the ticking clock. Hence why I feel like I can see some SP weakness after the H1 results are announced.
Many thanks for the detailed follow-up .
Jet2 (LON:JET2) I would add to the list after the fall earlier in the week which seems unjustified. IAG issued an ahead statement today and JET2 recent updates were also positive.
My morning smallcap tweet: Fright Club
Ultimate Products (LON:ULTP) Mothercare (LON:MTC) Ilika (LON:IKA) Polarean Imaging (LON:POLX) Aquila European Renewables (LON:AERS), S4 Capital (LON:SFOR), TT electronics (LON:TTG)
◄Ultimate Products (ULTP)► guides FY-July rev only £156m+ and adj EBITDA £17.5-18.5m. F/C was rev £166.7m, adj EBITDA £21.5m and adjusted EPS 15.6p. Q3 rev down 7% and dirs "believe it is sensible to assume that these trading conditions will continue throughout Q4". Outlook: "Order book for FY25, at this early stage, is significantly ahead of FY24 as retailers continue to increase their forward orders as the overstocking issues brought about by the pandemic subside and consumer confidence builds as we see a return to real wage growth." [SP=171 Cap=153m]
◄Mothercare (MTC)► guides FY-Mar rev only £281m, down 13% (8% at const currency). Blames weak Middle East mkts. Adj EBITDA marginally above £6.7m, in line. Needs covenant waivers, in refinancing discussions to vary, renegotiate or refinance this debt facility. May do a placing. Paying 19.2% interest at the moment! [SP=6 Cap=34m]
◄Ilika (IKA)► £3.4m max placing and OO at 28p, a 5% discount, to keep the batteries charged. [SP=29.8 Cap=47m]
◄Polarean Imaging (POLX)► order for Xenon MRI System, from the University of Alabama. No $$$. [SP=3.48 Cap=8m]. I hold.
◄Aquila European Renewables (AERS)► will not merge with another investment company after shareholder push-back. Will continue to look at options inc wind-down, sale of assets or continuation. [SP=63.8 Cap=241m]
In line: SFOR, TTG
Office for National Statistics confirms UK no longer in recession after GDP grew 0.6% in first quarter of 2024
Red alert - Mothercare (LON:MTC)
Extract from today's trading update "With interest rates remaining at an elevated level, the interest rate on the Group’s existing loan facility is currently 19.2%, which coupled with the extended time to return to pre-pandemic retail sales levels, particularly in our Middle Eastern markets, highlighted above, means the Board’s current forecasts for continuing operations show the Group requires waivers to our covenant tests."
Crikey - who is financing them at that rate? Barclaycard?
The rate alone tells you that the debt is very high risk.
Ultimate Products (LON:ULTP) sounds like a profit warning. Trading in line in April, 7% down in May. When they start the share buyback at least they will get them cheaper now. Held for many years but losing interest now and will off load if my holdings remain in the green following today's news.
Update: just announced start of the buyback, good timing.
Ultimate Products (LON:ULTP) - yes, a disappointing update with turnover c£10m lower this financial year. It's a bump in the road as the long-term trend is sales growth. Not entirely unexpected I suppose given the lack of energy efficiency tailwinds this year (e.g. air fryer sales) and clearing of some over stocking at retailers. Good that they have started the share buy-back and that FY25 looks much better though. There is always some volatility in sales here...its a real business! Anyway, no doubt the share price will be down c20% today, albeit there may be some support from the well-timed share buy-back.
EDIT - it makes you wonder whether a few larger sales moved back into FY25 that were expected to offset the general FY24 slow-down?
Morning Bob, it didn't take me long playing this silly game to realise that when weighing up whether to sell a holding, i should not be influenced by whether that holding is 'green'.
If you've decided the cons outweigh the pros then sell and take a loss if necessary
Correct, will hit the button sometime today, just hope the 34% down bounces a little.