Small Cap Value Report (Fri 10 Nov 2023) - AGFX, W7L, ZTF, SNWS

Good morning from Paul!
All done for today, and the week. Have a smashing weekend!
Podcast is up here - mystery shares (my favourite share ideas of the week) are Warpaint London (LON:W7L) and Zotefoams (LON:ZTF)
My SCVR Summary spreadsheet here is now also up-to-date. It's a quick reference tool, where any company we've covered (588 in total) can be found by searching its ticker via CTRL+F. I use this spreadsheet before writing every section in the SCVRs, to get myself up to speed on this year's previous news from the company in less than 60 seconds. Also it provides a nice visual overview of the pattern of company reporting. You can hover over any cell, to see a pop-up summary of that company's news.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
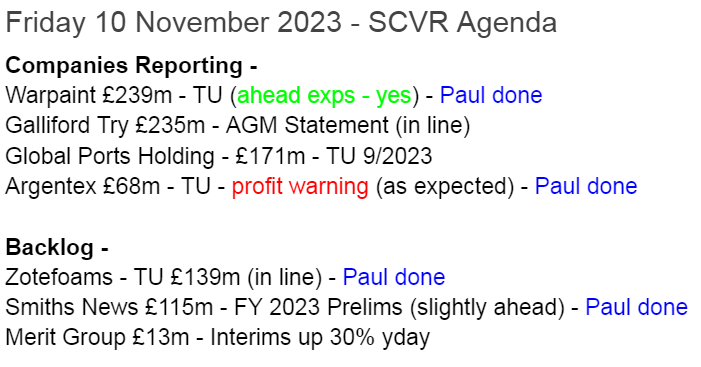
Argentex (LON:AGFX) - 59p (pre market) £67m - Trading Statement (Profit Warning) - Paul - BLACK for spreadsheet, AMBER on fundamentals
Given the recent unexplained departure of both CEO & CFO, it was pretty obvious a profit warning was coming. Good to see some of the uncertainty removed today, with a profit warning that I see as: not as bad as it could have been, in the context of a halved share price. Looks due a bounce (which I wrote before 8am, before anyone accuses me of stating the obvious now it has bounced a little)
Warpaint London (LON:W7L) - up 6% to 333p (£256m) - Trading Update (ahead) - Paul - GREEN - (MYSTERY SHARE for podcast)
Another out-perform update from this makeup company. I remain a big fan of W7L shares, and even after a good run, I think the valuation still looks reasonable. Providing nothing goes wrong of course. One of the best GARP shares in the UK, remains my view.
Zotefoams (LON:ZTF) (Paul holds) - 285p (£138m) - Trading Update - Paul - GREEN - (MYSTERY SHARE for podcast)
I recap on the trading update earlier this week. The share price drop of c.30% recently seemed to imply a profit warning might be on the cards, but it's actually produced an in line update for FY 12/2023. Demand has been a bit softer, but higher margins have rescued the numbers to a very respectable outcome. On a valuation that now looks modest, I am comfortable keeping a positive opinion.
Smiths News (LON:SNWS) - 47p (£111m) - Audited FY 8/2023 Results - Paul - AMBER/GREEN
A quick look at recent results leaves me with a moderately positive overall view. The 9% dividend yield could go higher, if it renegotiates banking arrangements, which are now only showing modest debt. But is it just a cigar butt stock? We discuss that every time, what's your view?
Paul’s Section:
Argentex (LON:AGFX)
59p (pre market) £67m - Trading Statement (Profit Warning) - Paul - BLACK for spreadsheet, AMBER on fundamentals
This is one of several forex dealers listed in London, which seemed to have had a good run of success in recent years.
We’ve been speculating here that a profit warning was probably on the cards, due to the abrupt, unexplained departure of the (12% shareholder) CEO which I covered here on 26 Oct 2023.
Yesterday, the CFO also resigned, which I commented on here, demanding answers.
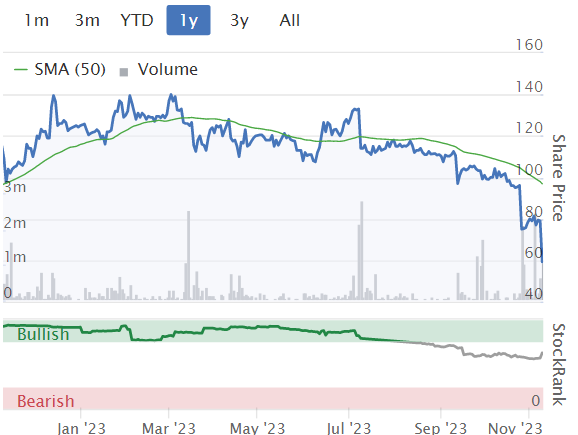
Understandably, some shareholders who could sell easily (a huge advantage PIs have over fund managers in small caps is the liquidity that comes with small holdings), decided to sell up and wait for answers, as evidenced by the plunging share price -
Profit warning
Today, we’re told this -
Argentex Group plc (AIM: AGFX), announces that following a review of its financial forecasts, the Board of Argentex expects to report revenue and operating profit for the year ending 31 December 2023 at approximately the same levels as for the twelve months ended 31 December 2022, which are below current market forecasts.
The interim CEO says -
"Obviously it is very disappointing that the numbers for this year are likely to show little, if any, improvement on last year and current market conditions remain challenging. However, Argentex continues to be a stable, profitable and cash generative business.
We are in the process of concluding a review of our strategy, which we will communicate to investors in the New Year, and we remain confident that there is a significant market opportunity for us to exploit."
My initial reaction is that it doesn’t seem too bad, in the context of a share price that has halved in the last 3 months.
I was struggling to work out the financial effect, because there’s been a change of year end, from March, to December. So we only have 9-month accounts to Dec 2022, and interim results to June 2023.
Ah, I’ve just spotted that they also showed pro forma 12-month figures to Dec 2022 within the 9-month accounts - revenues £50.4m, and adj operating profit of £12.3m. Adjustments boosted profit by about 10%, and finance costs were small at £0.3m, so profit before tax is fairly close to operating profit.
Singers to the rescue! A note has just come through on Research Tree, saying today’s profit warning is c.15% below existing forecasts at the EBITDA level, which is now expected to be c.£15m for FY 12/2023.
Singers has withdrawn forecasts and removed its BUY rating (now saying “Under Review”), until new management is “settled” (implying the interim CEP is staying on?) and the strategic review has been published (in early 2024).
Going back to an earlier Singers note from Sept 2023, its original forecast for FY 12/2023 was: £60.0m revenues, £17.5m adj EBITDA (now expected at £15.0m), and adj PBT forecast was £13.4m. So that’s a £4.1m drop from EBITDA to PBT.
So if I work from the new forecast of £15.0m EBITDA, this implies revised adj PBT of £10.9m, down 19% from the original £13.4m adj PBT forecast.
That’s about 9% down on 2022, at the adj PBT level.
Paul’s opinion - as you can gather from the above, this is a bit complicated to untangle when the clock is ticking, and I have to get this up before 08:00.
So my impression at this early stage is - not as bad as I feared, and I could imagine the shares might bounce at some stage.
I’ll stick with AMBER.
Publishing this just before the market open, so I have no idea what the share price will be, let's find out shortly!
Warpaint London (LON:W7L)
Up 6% to 333p (£256m) - Trading Update (ahead) - Paul - GREEN
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, is pleased to provide an update on current trading.
Strong trading performance continues and results for the year ending 31 December 2023 now expected to be ahead of market expectations
Another forecast upgrade - not entirely unexpected, it has to be said - as flagged here on 20 Sept 2023, it looked as if there was possible upside on forecasts. I’ve just re-read my notes there, which are quite good (even if I say so myself!) as they included thoughts from a quick zoom with management on the day - including the point where they agreed with me that the numbers are still only small for a global makeup brand(s). The answer was yes, to my question that long-term global growth potential must be very considerable.
New guidance FY 12/2023 -
Revenue of £85m+ (up about 34% on LY - all organic too, I think)
Gross margin is “robust”, and above 2022.
Profit before tax (PBT) guided at £16m+ (the LY comparative is stated as £7.7m, but I prefer the adjusted comparative number, which is £10.0m for 2022, per Shore Capital’s note today [thanks!] - whichever number you use, it’s fabulous profit growth, especially considering tough macro.
Operational/outlook comments -
The Group's expansion strategy continues, with further scheduled launches in 2023 and 2024 with new major retailers and the expansion of the range of products stocked with certain existing customers. Launches in November 2023 include a range of W7 products in 400 Etos stores in the Netherlands and 100 Watsons stores in the Philippines, together with a range of Technic products being launched in over 200 Wibra stores in the Netherlands. Further expansion is also scheduled with existing retailers, including W7 being stocked in an additional 372 CVS stores in the US and 102 Boots stores in the UK during Q1 2024.
Shore calculates 16.0p EPS for FY 12/2023 - what’s the betting that the company has left a little reserve within that number, to end the year with a flourish? High, I reckon.
Forecasts for subsequent years show only modest increases (17.3p FY 12/2024, and 19.3p FY 12/2025), again it looks as if the pattern of under-promising and over-achieving might well continue.
Paul’s opinion - my main point is I wish I held this share, after raving about it for ages now! Never mind.
With such strong organic growth, that looks set to continue, is it worth worrying about valuation at all? Yes, because it would probably be a mistake to pay say 40x earnings or more. I’d be happy to value this share on the likelihood that I imagine 20p+ EPS is looking achievable in 2024. Pop that on a PER of 20x, which I think is reasonable, and I get 400p as a realistic price target (providing nothing goes wrong).
At 333p, the price is well below that still. So I see further potential upside here.
Hence I’m happy to remain at GREEN with my view of this share.
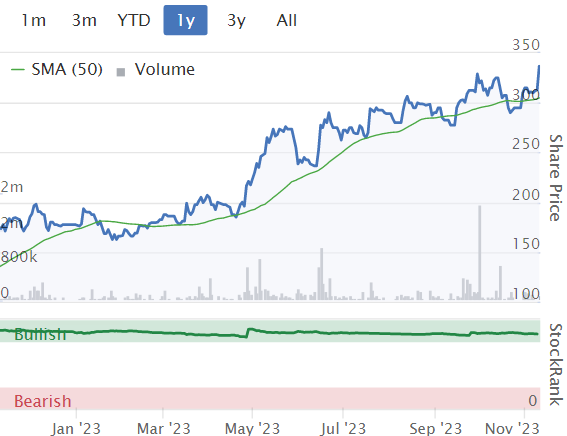
You don't need to read any books to conclude that this is a good chart! -
(lovely StockRank too, and "High Flyer" status per the Stockopedia styles)
EDIT: My interview with W7L's CEO here in Jan 2023 is still very relevant I think.
Zotefoams (LON:ZTF) (Paul holds)
285p (£138m) - Trading Update - Paul - GREEN
7 November 2023 - Zotefoams, a world leader in cellular materials technology, today provides a trading update for the nine months ended 30 September 2023 ("year to date") and in respect of its financial year ending 31 December 2023.
CEO Succession - long-serving CEO David Stirling has announced his intention to retire “within the next 12 months”. This looks orderly, hence not a worry, providing of course a suitably competent replacement CEO can be found. It’s an interesting, and financially sound business, so I would expect it to attract some strong candidates.
Q3 Trading Update - issued much later this year (7 Nov 2023) compared with last year on 13 Oct 2022.
The most important thing is it’s in line -
"Delivering on strategy - profit in line with market expectations"
Other points -
Performance “resilient” despite “challenging economic backdrop”.
9-month sales “similar” to LY, helped by “modest currency tailwind” - suggesting constant currency sales would be slightly down.
Q3 sales down on LY “as anticipated”. “Volatility in demand”.
Good visibility from confirmed orders for the rest of FY 12/2023 - good, as that means little likelihood of a profit warning.
Revenue for FY 12/2023 will be similar to 2022, but with improved product mix (ie more profitable).
Positive factors - strong pricing actions, operational efficiencies, more favourable raw material & energy prices -
...this is expected to drive improved overall profitability, with margins significantly higher than the previous year.
ReZorce update - doesn’t say much really (this is the potentially exciting innovative recyclable drinks carton project) -
The Group has also continued to invest in the development of ReZorce® recyclable barrier packaging technology and, following the signing of a joint development agreement, has made further progress against the milestones set, in advance of commercial trials scheduled for early 2024.
In our MEL business unit, costs will increase as we further invest in ReZorce and address some legacy issues in the licensing and equipment business. The MEL business unit is now predominantly focused on the development of the ReZorce recyclable barrier packaging solution for beverage cartons.
Overall -
The Board is confident in the Group's ability to carry positive momentum through the remainder of the year. Based on its current sales forecasts and foreign exchange rates, and subject to there being no material disruption to the business, it expects adjusted profit before tax to be in line with current market expectations*.
* Current Zotefoams-compiled consensus expectations for adjusted profit before income tax and separately disclosed items, for the year ending 31 December 2022, is £12.5m.
Broker expectations have barely changed for the current year at c.20p EPS, which is not bad going considering tough macro, in my view -
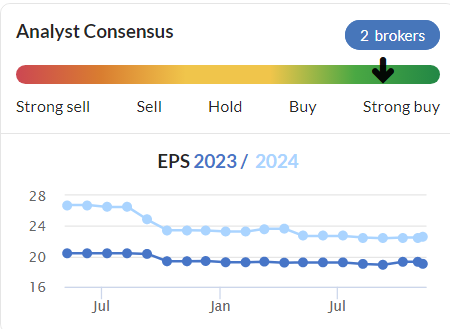
Look at what’s happened to the share price over the last year though - it’s as if the market was expecting a profit warning, which has not happened -
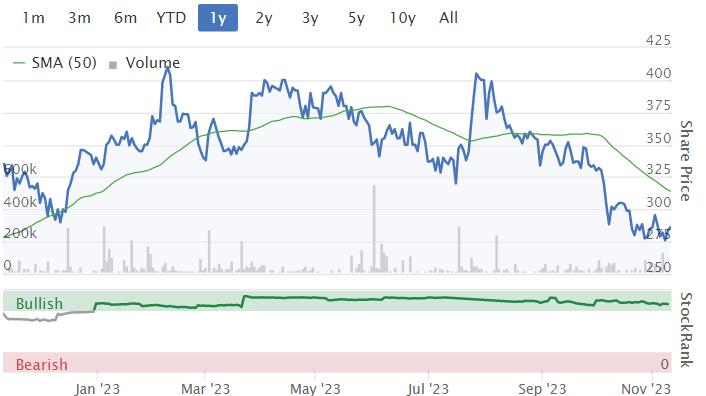
Maybe the valuation got a little stretched, with hindsight, but now it’s really come back down to earth - this looks a bargain to me, for a good quality business that has demonstrated considerable ability to navigate the crises of the last few years, including big hikes in costs of production which were successfully passed on to customers -
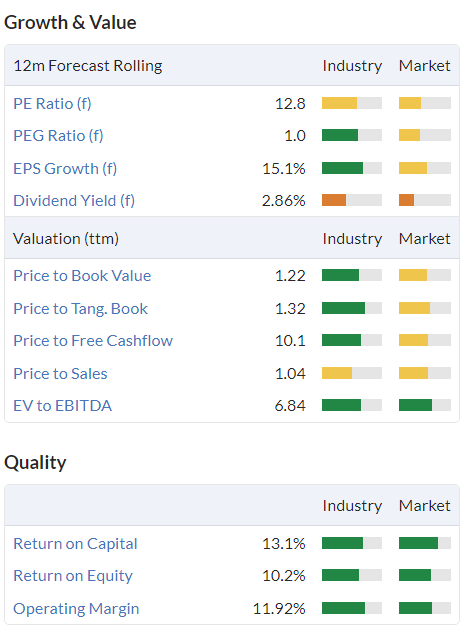
Paul’s opinion - it’s been useful to refresh myself on ZTF shares. I hold a small position currently, and I’m feeling an urge to increase it with some fresh buying after doing the work above. There’s no cash available unfortunately, so it will have to stay on my top-up list for now.
As with so many shares at the moment, it looks as if this has been mainly sentiment-driven selling, rather than anything fundamentally going wrong at the company. It’s managed to maintain profitability, despite some softening of demand. That should leave ZTF nicely set up to show decent profit growth once the top line turns up again at some stage in the future. Usually we see the opposite - profits crashing due to operational gearing when demand softens, but not the case here. That tells me it’s well-run, has pricing power, and hence looks a good quality business, at a modest valuation currently, after the recent plunge from c.300p to 280p. Thumbs up from me!
There's are also 2 wild cards, in for free - ReZorce might "blow the bloody sperm whale off the beach" (see SCVR earlier this week) if it's a success, and boost profits from ending development spend if it's not a success. I wonder if NIKE (major customer) might be tempted to take over ZTF for the special running shoes performance soles?
Smiths News (LON:SNWS)
47p (£111m) - Audited FY 8/2023 Results - Paul - AMBER/GREEN
The precise period is the 52 weeks ended 26 August 2023.
SNWS is a distributor of newspapers & magazines. We’ve covered it in loads of detail here over the years, and been impressed with the successful turnaround.
Legacy problems have all been dealt with, so it’s now free of pension funds, loss-making bits, and excessive debt.
Although obviously whatever anybody says, investors are unlikely to ever give this share a decent rating, unless they find some other use (that isn’t shrinking) for its fast, overnight, distribution network to thousands of shops.
There’s a recording of the recent mgt webinar here.
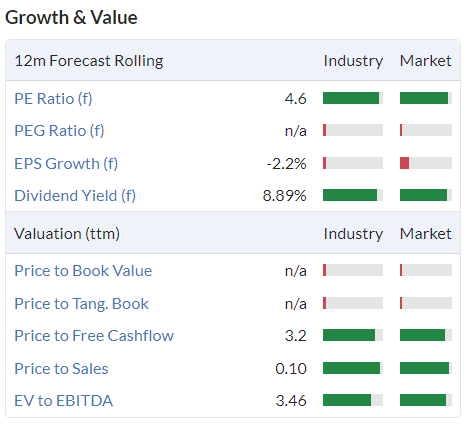
I’m going to keep this fairly brief, but my reading of these numbers is pretty positive, in the context of an extremely lowly valuation of the shares.
Performance is good -
Performance ahead of expectations with further debt reduction and contract renewals
Plenty of encouraging things summarised here -
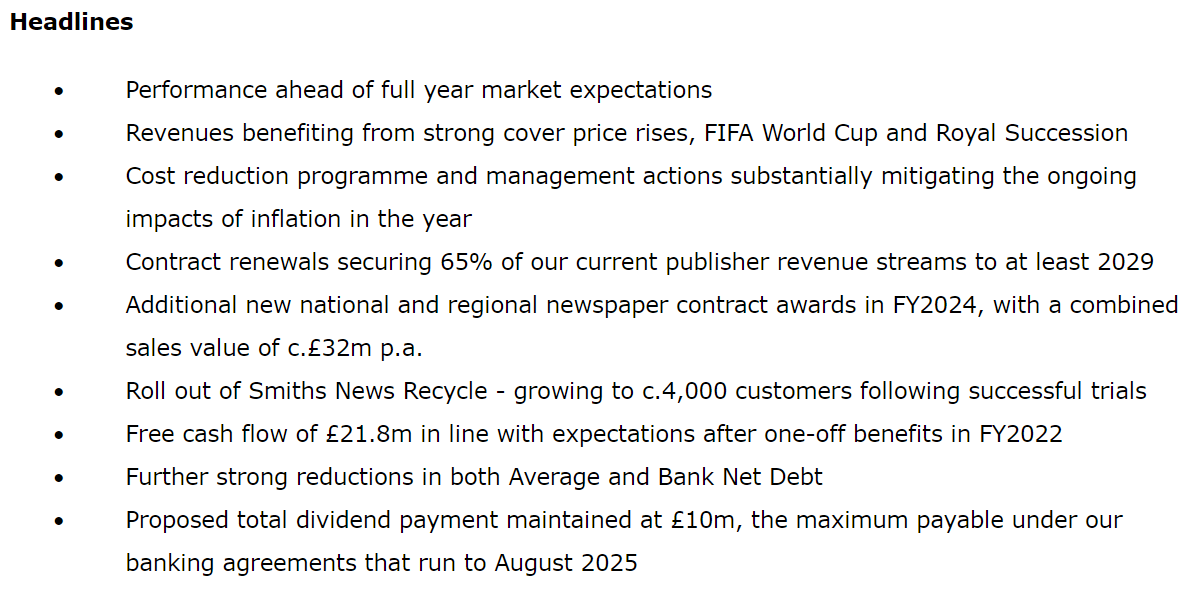
Key P&L numbers -
Revenue flat at £1,092m
Adj PBT slightly up at £32.3m (up 4%)
EPS flat at 10.8p (so a PER of only 4.4x)
Balance sheet - is negative, but shrinking nicely. So net liabilities of £(32.0)m last year, improved to £(16.3)m by Aug 2023. That only includes £2m intangible assets, we can ignore that as small.
Fixed assets are minimal, as things like vehicles are I believe outsourced to self-employed drivers. Correct me if I’m wrong there, that’s from memory when I spoke to mgt a few years ago.
Working capital are large numbers, which no doubt move about a fair bit on a day-to-day basis, dependent on when big customers pay, and big suppliers have to be paid. But they’re roughly in balance, with £157m current assets, versus £159m current liabilities. That looks fine to me.
OK, the balance sheet looks OK, nothing special, but no particular problems either.
Average cash/debt - this is a real breakthrough! Take note everyone in the City please, SNWS provides the “gold standard” of cash/debt reporting - it tells us the year end snapshot on the balance sheet date of £4.2m net bank debt, but also gives us the hugely more important & meaningful “average bank net debt” figure (average working day, I assume) of £25.0m - which has reduced 50% versus LY.
We need average daily net cash/debt figures from EVERY company, it should be essential reporting, and is a big gap in current accounting disclosure rules.
Outlook - reassures me -
The new financial year has started well. Our critical drivers of sales, margin and sustainable cost reduction are being closely managed and we remain attentive to ongoing inflationary pressures which remain above historic levels. Cost reduction initiatives are well underway and progress continues to be made with our growth strategy. We are confident in delivering results for the current financial year in line with market expectations.
Dividends - note these are capped at £10m, so 4.15p, under current banking agreements. Maybe there’s scope to re-negotiate that? If so, divis could rise, and that looks quite plausible to me, given modest bank borrowings.
Note the current divi yield of nearly 9% is covered 2.5x by earnings. So if SNWS could agree with a new lender to secure bank borrowings (which fluctuate a lot) against its debtor book, in return for releasing it from any upper limit, then in theory SNWS could pay out all its earnings, for a dividend yield of over 20%! That would be exciting if it happened.
Paul’s opinion - sorry this is quite a quick glance, rather than in depth rummaging.
Investors just have to weigh up the same question as always here - are investors buying a cigar butt type share, that is paying out nicely, but with limited remaining profitable lifespan? Or is there a more sustainable future for the company?
Nobody knows! But these numbers do naturally draw me towards it, but they’ve been doing so for years, and the valuation remains at rock bottom.
On balance, I’ve moderately positive on this share, given all the progress that has undeniably been made, so I’ll go with AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

140 comments
Actually Richard, after reading 'How many stocks to hold in your portfolio' by Ed Croft, I felt I didn't need to search any more for views on this subject. So the answer is probably, about 25 stocks.
I can only afford 2.
I have bought for the first time Zotefoams (LON:ZTF) this week on valuation grounds.
However, I would be very surprised if Nike took over Zoatfoams. Zoatfoam's sales to Nike last year were at £42m, just 0.1% of Nike total revenue. So it is really modest for Nike. Would Nike want the headache of owning the commodity foam business (Azote) or even the supply of HPP for aviation and other customers? They presumably would want these businesses sold off but I am not convinced these are really stand-alone businesses that can be split. It just seems too much of a headache for a comapny with a $100 bn+ market cap. I also note that Adidas also has a 3rd party supplier (BASF) for its foam supplies for its footwear.
Would someone else (private equity? or chemical company,eg BASF) buy Zotefoams (LON:ZTF) ? Maybe there would be logic in this. But I would assume (have no knowledge) that the contracts with Nike will have stringent change of control clauses. If Nike walked away, Zoatfoams would be worth a fraction of its current value. This will make any takeover of ZTF complicated.
The importance of Nike to ZTF almost cannot be overestimated. ZTF says Nike represents a third of group sales - but it is about 80% of the high margin HPP division. It is safe to assume Nike represents the majority of ZTF profits - maybe even the vast majority.
In deciding to dip my toe in to ZTF this week I have done it solely on the basis of the multiple, growth prospects and the currently depressed profits due to ReZorce. I have discounted heavily any takeover speculation. I also would not have bought without the recent extension of the Nike partnership to 2029. The single customer risk here is extreme.
Remember for 30 years I had all of my investment were in one company only
You and me both. This reminder always stops my "wealth adviser" in his tracks when he warns me about idiosyncratic risk.
Have a good weekend everyone.
Smiths News (LON:SNWS)
Paul I love this Company.
Including the Divi in Jan 2024 I will have received £4.4k in 2years 6 months and I love the way in which the CEO and CFO engage with Investors.
This seems like a very efficient Company which respects its Shareholders and is always looking for ways to add Revenue without taking unnecessary risks.
Last year its Operating Cash Flow Per Share was 19.8 pence with an SP around 40 to45p.
Back by absolutely no popular demand at all.....it's this week Top of the Pops & Top of the Flops
Not a bad week at all. I'm off for a quiet whisky!
Smiths News (LON:SNWS)
Hi Paul - just a note on dividend. They did say once they re-financed they would likely resume to normal policy which is 50% pay out, so a yield of closer to 12% (rather than 20%) but nonetheless that could compound very well. You only need share price to rise 3% a year and you have a very nice compounder. As they say their recycling business is profitable and popular, magazine and paper distribution isn’t declining anywhere near peoples perception and this business has very strong cash flow generation for many years to come.
Thanks david, nice additional points!
The other thing about Smiths News (LON:SNWS) is they have quite strong pricing power as there isn't really anyone else able to provide their services. Clearly limited growth prospects, but suspect people will still be reading newspapers and magazines in 10 years time, and they should be able to deliver good cashflows for many years. Overall I think a PE of at least 6 is warranted which would put it at 66p.
Some big volume on Rank (LON:RNK) if anyone was interested in it
Why so many posts on Diageo (LON:DGE) ? It's a £72b cap company. Nowhere near SCVR territory. Move to a separate thread?
Why so many posts on Diageo (LON:DGE) ? It's a £72b cap company. Nowhere near SCVR territory. Move to a separate thread?
It isn’t really a discussion of Diageo so much as a comparison of trading vs genuine investing, the one inherently short term, the other measured in years. Traders saw a short this morning and perhaps profited. Investors see an entry.
There is some ire directed at superstar investors like Train and Smith, both Diageo fans. Ironically, Smith has paid the price for being shaken out of some tech (Adobe, Intuit) by the short term crash of 2022. It looks as though he should have stayed the course and has suffered for trading out!
Ultimately, both approaches have their virtues and demerits. What traders might want to consider is the cost of their time. Acknowledging that many of us get a kick out of trading - trading 1-6 month options is my vice, though not shares - it’s a lot less time-consuming to just buy and hold.
Which platform do you use for options?I don't trade options (short or long) much but enjoy watching Tasty Trade (bought by IG group (LON:IGG) a couple of years ago on YouTube.Mostly as i enjoy some of trading floor kind of atmosphere whilst doing other things.I would recommend Tom and Tony there.They're pretty much all options, but mostly recommend a selling premium strategy, and have some great content, us related news and banter.It's Tom's 2nd online option company he sold since leaving the CBOE floor as an option market maker.
Which platform do you use for options?
I trade via my bank (not UK) where I have a dedicated advisor who takes my instructions by phone or email and executes within a few minutes. This is not a retail option and I think I’m beginning to piss them off with the volume of trades. I’m trying to persuade them to give me the same e-trading capability as I have for equities and bonds. The advisory team is supportive but there are technical hurdles
eParo - I don't agree. There has been a lot of discussion about this recently. In a nutshell the quality of Paul & Graham's work has attracted some interesting investors to this blog/thread and it has become the principal home of topical investment discussion on Stocko. Some people, and I'm probably one of them, think this blog + the discussion justifies the Stocko subscription (but only just). Others have commented that the Stocko data on shares is third-party, and sometimes very poor (useless for some sectors including Investment Trusts). You can get the basic data in other places, some of it is free, and I always have to check back to primary source before making an investment. The Stocko Folio feature is too limited (only 10 Folios allowed), screening is available elsewhere principally Sharepad, and so on. The USP for Stocko data is the Stock Ranks but I'm really not certain whether they justify the subscription. Therefore I will continue to follow and occasionally comment on any interesting stocks here on the SCVR until Ed Croft boots me off.
By the way, why would you want to restrict discussion to UK small caps - just about the worst performing investment sector in the world these last 2 years?
Michael C.
Nutshell !
Concurring from Croydon ;-))
Up the Eagles !!
....they are classed as Small cap before anyone complains..
Large cap versus Small caps discussion
I agree with Michael C
My interest in Stocko is mainly for this discussion board and Most of my holdings are not in small caps.
I also believe the small caps are destined for a period of underperformance and the last two years become 3-4 over the next two years. I am happy if I am wrong on this.
Hi Lucky Dip.
I also believe the small caps are destined for a period of underperformance and the last two years become 3-4 over the next two years. I am happy if I am wrong on this.
Why would you think that, when private equity & trade buyers are snapping up cheap UK small caps, with sometimes several takeover bids per week?!! Isn't that obviously telling us that prices are too low? (Hint: yes Paul, it is!)
Surely reversion to the mean kicks in at some point too? Investors with pots of cash move in and buy oversold areas.
I think it's too easy to mentally tramline, and take the existing trend, and assume it carries on forever. This is precisely what most commentators, forecasters, and journalists do. The opportunities are when that consensus is so obviously, and often hideously wrong. The difficulty is timing the change.
Everything's so easy after the event, but I've rarely seen such incredibly attractive buying opportunities as we have now, in my 25+ years as a small caps investor. Bargains galore.
Regards, Paul.
I completely agree Paul. I'm trying to stand back from everything and just look at the numbers. I would say you get valuations like this maybe once every 10 years? Starting to see some shares spike 15-20 % on next to nothing, so when funds become buyers again things could motor.
If COVID and 'the new normal' were the extreme end of valuations, we're now at the opposite extreme. True long term holders should be waking up every day thrilled at the opportunities being presented.
Everything's so easy after the event, but I've rarely seen such incredibly attractive buying opportunities as we have now, in my 25+ years as a small caps investor. Bargains galore.
I agree the valuations do look tasty across the board. However, if I could just sound a note of caution. Prices are a function of liquidity, and if, as might remain the case for some time, the UK remains on the bargepole list amongst more attractive jurisdictions for global investors' very mobile funds, then there is no reason prices cannot stay low for a while yet. I am fully invested to my threshold in UK stocks. Mine is not a contrarian position. Just one of suitably moderate expectations and happy to be surprised to the upside, should that occur.
Where there is difficulty lies opportunity .Some cheap stocks out there ...but could get cheaper. If you select your favourites and pound cost average over a given period it will all come good.
I highly value the analysis by Paul etc here, as do I, the quality of most of the comments. But do I restrict my own portfolio to UK small caps? absolutely not, nor do I restrict myself to UK shares in general.... I wish there was some commentary on non-UK shares (i.e. US shares.....) and mid/large-caps, etc. UK small caps make up about 5% of my portfolio...
"By the way, why would you want to restrict discussion to UK small caps - just about the worst performing investment sector in the world these last 2 years?"
SCVR that's why. Take your large caps to another thread.
It is not just limited to small caps. Look how many times Next (LON:NXT) has been covered.
Paul said "I always try to find time for a quick comment on a few key mid/large caps in retail, and housebuilding usually."
Members are free to discuss which stocks they wish, even if they are not covered by SCVR.
As you are so negative on small caps, I would have thought you would welcome, some large cap discussion.
The way that the Stocko forum works in practice means that it's pretty much a one-thread discussion board when it comes to company news. Unless you are looking for your post to be largely ignored and are not hoping to generate some kind of discussion, you have to post it on SCVR.
Posting on separate threads works somewhat for topic-based discussions but not for anything company focused. That's just the way it is.
Hi DaviStoVest,
Yes that's right, we did try a while back to set up company-specific threads, and it was a bit of a nightmare, and flopped, because everyone seemed to congregate back here at the SCVR instead.
I can't speak for mgt here obviously, but personally I like the SCVR being a hotbed of topical discussion each day! The volume of posts feels perfect to me - about 100 per day (only takes me a few minutes to read, digest & reply to), from overwhelmingly clever & courteous people, what could be better?!
If it ain't broke, and all that :-)
Have a lovely weekend!
Best wishes, Paul.
I agree that the SCVR comments bb is excellent and doesn’t need changing.
What’s disappointing is that other threads see equally good articles and comments, including from Stockopedia staff, but there is so little subsequent follow up.
e.g there have been some superb posts on Investment Trusts this week and one exceptional one from Charles Mitchell (no relative) but with only a few adding anything more. It means unlike here it’s not worth the time and effort taken. It’s NOT Stockopedia’s fault and Stockopedia staff can’t sort it. It’s simply that this is the only bb here that generates a lot of high quality follow up.
Investment Trusts are often as bombed out as small company shares are with some on very big discounts to NAV and they have the advantage of being pooled investments with less risk than single shares. Some are paying big and sustainable dividends, and just like shares, some go on to multi bag.
One could argue quite well that the bombed out nature of ITs and Sall caps are strongly linked
Hi Paul. Hopefully we are ok to talk about anything and everything share-related in the comments section, as we seem to now. What would be hugely helpful is being able to search the comments section by ticker. Then we'd have a rich archive of fantastic analysis courtesy of you, Graham and Roland (which is already searchable) enriched by the additional gems from the superb team of subscribers. (I'm sure this suggestion/request will have been raised before).
Have a great weekend all.
Daniel Thwaites (OFEX:THW) Interims out, don't look very exciting. Small increase in div. They cautiously optimistic. NAV per share still must be more than £2.00. Seem very cheap.
I believe the NAVps of Daniel Thwaites (OFEX:THW) is more like £4.20 on these numbers. The NAV does have some "false" assets in there, noticeably the pension surplus, which presumably is very difficult/ impossible for the company to access. But even substracting out any "doubtful" items, I still think the NAVps is well above £3.
In many ways, I view THW more as a property company. Although disposals of low end pubs has been few each year (i.e 6. this half year), I see that there was again a profit from disposals. This has been the case every year since 2016 (there was a small loss on disposals in 2016). This gives me confidence that the valuation of the real estate (more than £300m) is not unreasonable. With £70.6m of net debt the official NAV at end-June was £247m vs a market cap of around £55m!!
The downside (apart from having to get to understand the ridiculous interest rate swap and the bizarre long-term debt structure - that is important but ultimately, at current interest rates does not affect the valuation significantly) is that the profitability and dividends are quite low. The family have full control and their timeline (generational) is longer than an individual shareholder's timeline (even that of a long-term investor). Liquidity in the shares is so poor - that short-term investors can forget the stock completely.
Thanks for the above. I only looked very briefly and knew the NAV was more than £2.00 because that was what it was before.
Interesting point on whether the pension fund surplus is an asset or not, if they could find a buyer of their pension liabilities, and there was a surplus that surely belongs to the company ? though I presume they would have to repay any tax relief received . Does anyone have a definitive answer ? In principle it seems fair that it is included as an asset because when it was in deficit they deducted it from the NAV.
Likewise the interest rate swaps are fairly straightforward, they were a drag on profits now they are helping.
Therefore, I do not see any need to discount the NAV of £4 plus. I suspect this might be understated if anything.
For me the tone of the report was negative and made little effort draw any attention to the positives, it almost feels like they want to keep the share price down !
Deegee
To a large extent I agree with you. Management/ family have no incentive to talk the price up as the company has no need to raise new equity and the family are not sellers. So the share price is of little significance to them.
The company cannot access the pension surplus in any easy way. They could get the pension fund bought out by an insurance company - but then much of the apparent accounting surplus will diaappear as the insurer will value the liabilities much higher than the accountants do. I hope though that management is looking at a buy out of the pension fund as this will derisk the balance sheet.
I think the market price of the shares is far below the intrinsic value. This is different than saying the shares are mispriced. If the intrinsic value will be unlocked tomorrow or in a century is anyone’s guess. In the meantime, there is a 3% div yield (which was cancelled during Covid) but now growing again.
I own the shares and I think the shares have a place in my portfolio but given that the shares are so illiquid, they are definitely not suitable for anyone who might need to sell in a hurry, nor those who object to being a passenger.
I also own Ocean Wilsons Holdings (LON:OCN) and many of the points that I made for THW are equally relevant for OCN - although OCN is comparatively liquid.
Paul - Thanks for the excellent Warpaint London (LON:W7L) write up.
It strikes me that there is a connection today between the profit warning from Diageo (LON:DGE) and the profit beat from Warpaint. Consumers who are feeling the pinch are cutting back/trading down from their usual brands. In Diageo’s case this means reducing alcohol consumption and/or switching to a cheaper spirit brand.
Contrast this with Warpaint who commission cosmetic “dupes”. In a recent webinar the Warpaint CEO highlighted their dupe of the Georgio Armani brand of Foundation retailing @ £45, with their Genius Foundation @ £4.95.
Warpaint sell cosmetics at much more affordable prices, which is exactly what consumers want when times are hard. Everyone needs a pick me up from time to time and a new lipstick is a simple and cheap way of putting a smile on your face.
In these testing times I continue to hold.
Warpaint London (LON:W7L) That's a good point iwright. Well done on seeing the potential,
I was stupid enough to dismiss them as having no real sustained growth appeal. Should have paid more attention as my teachers always said.
Wolf
Don’t be too hard on yourself. It was the left to right upward momentum that alerted me, then Pauls +ve comments and finally watching a Warpaint presentation, highlighting its value proposition before the penny dropped. Have been accumulating steadily as my conviction grows.
You may still have been right, Wolf, in your assumption that Warpaint London (LON:W7L) lacks sustained growth appeal. But it interesting to note, as does iwright , that their products may well have a negative income elasticity of demand, so the company will likely do well when times are hard.
Whether or not Warpaint London (LON:W7L) has sustained UK growth, it realises that for a big sales lift it needs to export to Europe and the US. Todays update notes sales expansion in the Netherlands and the US, so it is already starting to achieve this objective.....
Launches in November 2023 include a range of W7 products in 400 Etos stores in the Netherlands and 100 Watsons stores in the Philippines, together with a range of Technic products being launched in over 200 Wibra stores in the Netherlands. Further expansion is also scheduled with existing retailers, including W7 being stocked in an additional 372 CVS stores in the US and 102 Boots stores in the UK during Q1 2024
I seem to recall the CEO saying that the US consumer has similar cosmetic buying habits to the UK, but is 10x the total volume of the UK. Hopefully a lot more sales to come.
Warpaint London (LON:W7L) These sort of shares are great because as the earnings upgrade cycle kicks in you can average up as the price responds to the upgrades, so gearing the gains with little risk of a profit warning.
Yu (LON:YU.) was similar. The bonus there was stockopedia had the decimal point on the forecast eps in the wrong place for weeks showing as a PE of 70 instead of 7. So when the upgrades came it looked like a mammoth increase.
Wolf - You are right about upgrades allowing you to average up safely. I think it is particularly true for companies with high return (ROIC/ROE) numbers where you can safely pay up for quality.
Another similar candidate I can think of (and own) is Ashtead Technology Holdings (LON:AT.) .
I would be happy for additional reader suggestions of companies with successive upgrades and left to right momentum too?
Warpaint London (LON:W7L) has saved my portfolio this past year, one further bullish point, to quote Paul’s fund manager interview earlier this year that I recall, this company is scaleable as evidenced by selling into more and more stores
Hi WoSS & iwright7,
I Hold Warpaint London (LON:W7L) Yu (LON:YU.) & Ashtead Technology Holdings (LON:AT.) all of these shares have the attribute of bottom left > top right momentum with EPS upgrades, which you mentioned.
Ian, regarding your 'additional reader suggestions' of other companies whose shares ( which I happen to Hold ), which exhibit bottom left > top right momentum with EPS upgrades and which you might be interested in are: 3i (LON:III) Bank of Georgia (LON:BGEO) CRH (LON:CRH) Kinovo (LON:KINO) Marks and Spencer (LON:MKS) Morgan Sindall (LON:MGNS) Rolls-Royce Holdings (LON:RR.) TBC Bank (LON:TBCG) XPS Pensions (LON:XPS) .
As you can see I don't limit myself to just the Small Cap or AIM markets. I look for high quality companies which are growing their EPS because as you will probably know, EPS upgrades are the growth engine which drives a share price higher over time. I believe these types of shares have the best chance of becoming multi baggers whereby I can sleep at night. I Hold all the above listed shares. All the shares I hold can be seen by clicking on my Avatar. Some of the shares are paying nice Dividends whilst I wait for them to recover.
David.
David,
Many thanks for the suggestions and I agree with what you say . I already hold Marks and Spencer (LON:MKS) and Rolls-Royce Holdings (LON:RR.) and like you have come to embrace such large caps.
Of the others you mention I will need to do some homework, but I do like numbers from XPS Pensions (LON:XPS) so will investigate further.
Ian
You can probably add ME International (LON:MEGP) and Shoe Zone (LON:SHOE) to that list. I think there are a few more I hold. Others I hold are Associated British Foods (LON:ABF) Relx (LON:REL) Cerillion (LON:CER) and Card Factory (LON:CARD). I think these all qualify unless I misunderstood.
Hi Ian,
Good luck in researching XPS Pensions (LON:XPS) , please let me know your thoughts. I worked at IBM and XPS Pensions now runs it's pension scheme. I hear today that John Lewis has just signed up to XPS Pensions to run its pension scheme. Is another EPS Upgrade on the cards?
Another important thing to remember about buying quality shares with EPS Upgrades is, in my opinion, they are less likely to issue a profit warning, but that is just my view.
I don't know if Ed / Stockopedia have the data to confirm my theory but it would be interesting to see if quality companies who issue EPS Upgrades do issue fewer profit warnings. Also, it would make a good article for Stocko to research and write about.
David.
David,
Have done my DD on XPS Pensions (LON:XPS) and in light of the numbers and news have taken a position today. My summary buy notes below...
High sales growth and a new £9M/annum John Lewis contract. Likely to be upgraded again. Smooth Frog in the Pan momentum. Suits high/volatile interest rates. High QM (98) score, PEG 0.9, with acceptable EV/FCF of 18
Thanks for the suggestion!
Fantastic Ian.
Great Minds Think Alike or is that
Fools Seldom Differ!!!!
At the risk of being sexist a certain proportion of Diego's male customers are unlikely to be wearing Warpaints brands !
Co-founder of Lindsell Train. A player.
Thank you, grumpy5 and to Rogerh for an amusing reply.
Locomotive thief
Hilarious rogerh. That's made my weekend!
Diageo (LON:DGE) Down 15% at one point today on relatively minor sales and profits news.
My read across for small caps, is that markets remain in a fragile state with a bias downwards i.e. we are still in a bear market.
Just a reminder about MelloLondon at the end of this month especially as Smiths News and Warpaint will be there and we always have 40 very interesting companies for you to meet and watch presentations...
I still have three Mello virgin tickets to give away...
We have an absolutely fabulous line up of keynote speakers at Mello London at the end of this month and we would love to see as many of you as possible. If you have never been to a physical Mello conference before then now is the time to join us. I will be delighted to give five Mello virgins a free ticket for one of the days so that you can try before you buy...just send me an email via David at melloevents.com (putting @ instead of at) and I will send you a code for a free ticket by return
Many of the 40 companies that are presenting are on crazy low ratings and this could be exactly the right time to talk to the management teams and build your confidence in their leadership and the fundamentals of the company.
We have Katie Potts joining our line up of speakers at the two day event. So along with Christopher Mills, Lord John Lee, Andy Brough, Richard Crow, Stockopedia founder Ed Croft and Paul Hill we have a cracking line up and of course SCVR stars Paul and Graham will be there to do live reports and meet Stockopedia subscribers.
Here is a link to the full details and our event webpage is updated regularly with a full programme released shortly https://www.stockopedia.com/co...
We have three BASH (Buy, Avoid, Sell or Hold?) panel sessions live at the show so you have lots to enjoy. See you there
David
Argentex (LON:AGFX) Thanks PS for putting this on my Sharedar (see what I did there ) The market is allowing me to buy in high £ . Are there any shareholders here who have done any test sells in quantity today ? ...FOMO am I looking a gift horse etc...
It seems that the Fed Chairman's comments yesterday have instigated the current sell off.
This leaves me wandering about the recent rate pause by the BoE. At 6.7% our inflation is much higher than the US . The pause feels to me like a postponement of of a future (but not necessarily final) rate hike. I am very much left with the impression that the BoE has unnecessarily elongated this whole inflationary process rather than dealing with the problem resolutely.
Poolbeg Pharma (LON:POLB)
I note these guys are on the rise as the old Amryt Pharma team are back on board to repeat their trick. Given the pile of net cash the company has and the progressed drug pipeline this could be interesting over next couple of years.
Argentex (LON:AGFX)
The trading update had to come out and I made that very clear to them yesterday via their PR as I understand a number of shareholders did.
The share price collapse is well overdone imo. Net cash (ie after client money) is around £20m which makes up 1/3rd of market cap. The business is highly profitable and cash generative and will do circa 8-9p eps this year in a difficult environment. So even just on10* PER + net cash it would be 110p
What’s interesting though is now the track record of the new board. Ormonde has successfully led two payment providers and sold them for a lot so you’d imagine they become much better in that space. Railton was chair at Camelot.
Historically detractors of Argentex (LON:AGFX) were not so much of the business but mainly of the management - given the changes one might argue there has been an upgrade. Let’s see what the revised business strategy brings.
For what it's worth, my company's modest forex requirements (£8 figures per year) will always be transacted through our bank. Better to negotiate hard on the spread and keep the money within the same organisation under Government scrutiny.
Are we missing a tick or 2 on cable? Probably, but I sleep easy at night. There are other advantages too... Any positive bank balances in £,$ or Eur can be swept off to Over Night Money Market, currently paying over 5% for £ & $.
The Argentex (LON:AGFX) offering, transacting huge sums with a company of market cap £67m seems potentially flawed IMO. I still remember Crown Forex, who were always offering rates too good to be true... They were and they went bust some years ago. I'm not saying that about this crowd - just that in volatile times, the old, established banks with their stringent controls and oversight won't be allowed to fail whilst I snore loudly at night.
Other than there is no settlement risk on FX Kaboom
Spot trades from banks are put through CLS which is daily risk free settlement
Structured trades are marked to market and margined daily now and cash can be held in segregated client accounts.
Remember Lehmans and Bear Stearns effectively went bust and they had huge FX books, so you are probably just sleeping soundly based on perception rather than reality……. But banking relies on trust ultimately
Secure Trust Bank (LON:STB) I hold. Shore Capital (the company's broker) have just released a note saying the price could treble ! Not sure about that but they reckon if the £4bn net loan book target is reached, PBT could be £80m, EPS approx 320p. As a specialist bank with a clear focus on Retail, Real Estate , Vehicle and Commercial finance, management seem to have a very clear focus on the actions required to achieve their aims. There was a Capital Markets day presentation on Weds which is available to watch online. https://www.youtube.com/watch?...
Secure Trust Bank (LON:STB) might seem far fetched now, but if sentiment ever returns to UK markets then I think this could easily treble - 1800p would only put it just above book value and on a PE of around 9. Doesn't sound unreasonable for a solid growing bank with a good niche. Remember this was trading over 3000p in 2015 and it's actually grown a lot since then!
Charles, maybe think like this.
In a years time, we will be nearly in the 2005 year. If (!!!) Shore are right then STB are going o make 248p of earnings that year. If the share price trebled then the stock would be at 1839p.
So a p/e of 7.4x. Excessive? I don't think so.
It would also be on 1x book. Again excessive? When gilts are say yielding 4,5%, and the co is making 11.5% ROE, (Shore's numbers). So a 7% risk premium. Well above historic norms for the market but then STB is probably more volatile.
Another reality check. The minimum Core Tier 1 capital ratio is 6%. STB's is about 12% at the moment. In theory ( probs not in reality) it could pay that extra 6% back to shareholders, that is about £170m (hope i've got my sums right!).
Current mkt cap is £114m.
Unless we have a severe recession and STB lower there lending criteria, it seems a no brainer to me.
STB is very similar to CBG which may soon drop to under 1 bn and will be eligible for coverage by Paul/Graham and comments by the community!
Arix Bioscience (LON:ARIX) Good to see the Times comment on the asset sale "Don't swallow dog's breakfast deal at Arix Bioscience" https://www.thetimes.co.uk/art...
I see Rangeley have added another 2% to AVAP, AVATION, reported today. Anyone know any more?
Sorry can never get the hang of the £ sign ahead of the ticker. anyone tell me how. Sorry again
This was changed to simply putting the @ in front of the ticker. Easy to do and works well.
Thanks GN
Avation (LON:AVAP) yes now up to 25% so Rangely are either content at just under 30% or will make a bid. Unclear as to what that would be but with a NAV of 275p I’m guessing the other 70% of holders unlikely to accept less than 225p. He has already taken out the loose/forced sellers.
My guess though (and it’s just a feeling) is that this isn’t a bid situation. He will go to 29% and then agitate for the discount to NAV to get closed poss through a sale and then crystallise profits. But who knows.
Avation (LON:AVAP) I hold these. Does anyone know anything about the usual methods of Rangeley?
I'm a long-term holder of Avation (LON:AVAP) alongside some other aicraft leasing cos...of the patient rather than trading variety.
I've had a bit of a look at Rangeley Capital...not entirely sure I am any the wiser for it.
The key individual publishes articles regularly here:
https://chrisdemuthjr.medium.com/
as well as this......
https://valetudo.substack.com/p/disproportionate-response
Then he is acting in concert with this gentleman, who runs a subscription based website:
https://rapercapital.com/about
You will see he has written investment notes in the past on some of the major aircraft lessors - AerCap and Avolon.
Are these guys equipped to bid for a company?
As I said my suspicion is that this isn’t about a takeover - I think it is about buying assets at less than 50p in the pound and then agitating for a narrowing of the discount. They can wait 3 years and still get a very good IRR
I believe there has been some past infighting at Argentex (LON:AGFX), just to further complicate matters.
A few thoughts...
It's also interesting Paul that Gresham House are increasing their stake in Argentex (LON:AGFX). I will keep on the watch list, but feeling fortunate that I exited in July now after losing confidence in management. So, they have lost the Chaiman, both founders and the FD since IPO!
Not small-cap but Diageo (LON:DGE) had a profit warning this morning. That is very unusual for such a great company.
I see that GDP growth is 0.0% for Q3. Hmm - a 0.1% later downgrade on the estimate and a negative Q4 would be a recession. Will it get downgraded in a few months time I wonder?
re. Powell's "We're not confident that conditions are sufficiently restrictive at this point to get inflation back down to the target rate of 2%".
I don't understand why markets keep thinking the FED are going to signpost interest rate reductions. Why would they do that when headline numbers in the US are still strong and nothing has broken?
I held Argentex (LON:AGFX) and Alpha International (LON:ALPH) until there was a huge share sale by the CEO at Alpha. I now sell up if there are large out of the blue sales by senior management. In this case I wonder if this event foretold a sea change for the whole sector, which seems to be going through a difficult patch now.
I think it might be a much simpler explanation.
Worldwide trade is down (look at the huge reduction in containers being shipped )
Every time goods shipped they need to be bought generally with USD
So less shipments less dollars bought less commissions earned .
It’s probably that simple .
I've seen several signs of a slowdown in USA/globally. Cardboard box consumption in the USA down *; AP Moeller - Maersk A/S (CPH:MAERSK A) making lots of redundancies and saying ships will be laid up or scrapped, the Harpex index of container ship charter rates is well down (look at the 24 month chart).
* ZH is perenially doom and gloom so has to be read with that in mind
Michael C :
I've seen several signs of a slowdown in USA/globally. Cardboard box consumption in the USA down *; AP Moeller - Maersk A/S (CPH:MAERSK A) making lots of redundancies and saying ships will be laid up or scrapped, the Harpex index of container ship charter rates is well down (look at the 24 month chart).
* ZH is perenially doom and gloom so has to be read with that in mind
Yes. Indeed. But whens it going to end?
A lot of companies have been hit by the length and extent of the destocking in the US in particular that accompanied/caused the container shipping slowdown. I've been looking for signs that the shipping is reversing on the basis that might signal the end of the destocking overhang and potential recovery for some stocks - eg Portmeirion (LON:PMP) for instance?
The latest Drewry global composite container rate figures are food for thought?
That's quite a sharp reversal?
Over capacity has also been caused by a large number of new vessels entering service - causing older vessels to be scrapped. Capacity is being reduced by slowing vessels, saving on overall sailing costs. So overall demand and capacity are being actively matched. Yet to see if price rise is sustained - but if so, then it might be a leading indicator of a rise in goods being ordered as the destocking reverses?
cheers
Mark
don't wise.com and revolut offer the same exchange services as Argentex or am I missing something?
I don't think so, Wise (LON:WISE) is more retail transfers. I have used them. They also have a cash card for foreign currencies. A lot of ex-pats use Wise to transfer money from their home bank to where they are currently living.
revolut, online retail banking?
I would have thought Alpha International (LON:ALPH) is closer to what Argentex (LON:AGFX) do.
For me the size of profit warning from Argentex (LON:AGFX) doesnt merit the resignation of both the CEO and CFO. More to come here?
Argentex (LON:AGFX) shares are 6%, which is strange after a profit warning.
Not really Rusty. The shares collapsed from 110p to 60p on the director departures based on a fear that trading wasn’t in line with expectations, so the profit warning was more than baked in.
Diageo (LON:DGE) profit warning is worth a thought or two. Mind your eye re EM exposure esp LTAM and Caribbean consumer...tobacco springs to mind... EM fund managers etc ....
Diageo (LON:DGE) On the rocks? bear markets make a fool of us all, even fund manager favourites.
As it's Friday I stuck a short on to see if I can get a free night out with the cash. Will either be fine dining with the wife or a kebab in the car depending how it goes.
Diageo (LON:DGED) On the rocks? bear markets make a fool of us all, even fund manager favourites.
Your comment only makes sense from the perspective of a short term trader. Diageo holds the finest collection of brands in large cap staples. Sometimes demand drops, or comps are challenging, or there’s a regrettable failed initiative. That’s what running a business entails. Investors are business owners who try to align themselves with the best management, brands and markets. They don’t worry about a single data point indicating that LatAm is going through a downturn, or the moon is unaligned with Venus. Are the brands still valuable? Is management competent? Are spirits on an upward curve? Those are meaningful measures and there’s no evidence today of a fundamentally broken business. The SP has simply repriced today’s profits. But investors own the future, attractive cash flows of the business - and those just got better value. Your post would make more sense to investors if it read: “Diageo looks very attractive at this reduced level, a 25% discount to its long term average valuation.
BnB well everyone's happy then. Nick Train and his friends can fill their boots and I've got a nice weekend planned.
BnB well everyone's happy then
Indeed. Many ways to skin a cat.
Loved your 'investors own the future', BnB. I held Diageo (LON:DGE) way before I constructed my spreadsheets so checking contarct notes I found that I bought in at 1196 pence per share in 2011 and sold out in 2012 at 1519 pence, the dividend being unattractive. I think the past tells us what the future will hold for the investor in this company. I don't hold.
Did the same. Have closed most but it's in a clear stage 4 downtrend and support is a long way off.
Diageo (LON:DGE) Support could be around 2700 and it might be worth buying if it gets there. If bought there would be a choice to be made between long-term hold or short term trade. In this market the latter is always most attractive, and I agree it's in stage 4 at the moment.
I don't know if you can enlarge the chart by clicking on it.
It looks to me as though the price got too high in 2019, and the post Covid peak is just a bubble. But as BnB says, it's such a good basic business the only question is what to pay for it, there's no risk of it going bust in the foreseeable future.
Diageo (LON:DGE) Expects net sales from LAC (Latin America and Caribbean) to fall by more than 20% year-on-year. LAC accounts for ~11% of net sales. Consumers are downtrading to cheaper brands.
The shares are at 2829p -12.8%, so quite a walloping for such a big company.
Nick Train was singing its praises earlier this month.
It's in its lowest quintile of cheapness over the decade. It's a good-quality company. However, it's on a PE of 18.9 which seems rather punchy esp. in view of the latest developments. Probably the way I'd play it is to place a buy point at 2000p, which is skirting a decade low and puts it on a PE of ~14. I'm not sure it will reach that low, mind, so I might miss that trade. People who want in on the share might set a more reasonable target.
It's funny how the market seems to have been anticipating this. The shares have been in downtrend since the beginning of 2022. Analyst estimates have been reasonably stable throughout the year, so, hmm, they seem to have missed a trick.
Diageo (LON:DGE) - It's funny how the market seems to have been anticipating this. The shares have been in downtrend since the beginning of 2022.
Those movements are in tune with the rest of consumer staples, which are bond proxies. Look at Nestle for example. Bond yields up = staples down. Now what happened to interest rates at the start of '22?
Staples share price moves are only very indirectly to do with the market anticipating a recession in LatAm 2 years later (if at all) and everything to do with the relative attractiveness of bond proxies' dividends to interest on savings.
Diageo (LON:DGE) another Fundsmith share that has gone wrong. I read Terry Smith reduced his technology holdings and increased Consumer Staples, at the end of 2022. Technology has done very well in the US this year. CS seems to have done poorly, this year.
It was only a couple of days back that I was warning people to mind the "E" for Diageo (LON:DGE) before considering the P/E.....and referenced the Remy Cointreau SA (EPA:RCO) numbers.
So I had it on my list of positions to reassess and potentially reduce.
But did I actually get round to doing that before this morning's unscheduled announcement? Sadly not.
It just shows how talk and action are very different things....
Doh.
So I am almost as stupid as Nick Train. I say "almost" because I refuse to hold Manchester United (NYQ:MANU).....
I have learned the hard way that analysis is great and careful consideration is worthwhile, but when the back half of my brain (what Lee Child calls the reptile part) gives me a strong positive or negative feeling about a share I have learned to trust it. My biggest mistakes have been when I have over-thought investment decisions and either missed an opportunity (Warpaint London (LON:W7L) ) or hung on because my calculations suggested all would be well (Regional REIT (LON:RGL) .
Are you saying then you think it is too late to buy Warpaint London (LON:W7L) or are you talking about short term trade? thanks:)
"Nick Train was singing its praises earlier this month"
He was singing it's praises 2 days ago. He's paid enough to deserve a little ribbing when the inevitable happened. Sods law.
"It's dangerous for me to name individual companies in a way because they probably have a propensity to blow up in my face tomorrow. But to me, in our UK strategy, for at least 20 years, Diageo has been a core major holding"
Come on. Diageo has been a core holding for Lindsell Train for many years. Hence the majority of long term investors in their strategy will be in the money on Diageo as the bulk of the fund’s shareholding was acquired far below current levels. Just because something is cheap it doesn’t mean it can’t get cheaper in the short term. If you want to rib anyone you would better target Cascade Investments, Bill Gate’s private investment vehicle, which bought in much more recently. And yet I think neither Bill Gates’ LT manager Michael Larson nor Bill are exactly morons. They see the finest collection of premium alcoholic brands on earth with a long growth runway ahead, etc, etc on the back of premunisation, growth in EM incomes. I won’t repeat the arguments, which are touched on down thread and better explained elsewhere. My point is that so many people, on this board included, profess to be investors when they are really traders. And this goes for much of the professionals too. By your definition the Hermes family are idiots for not selling out earlier in the year given the softening in luxury. Ditto Arnault in LVMH. They of course don’t because they understand how difficult it is to market time, how few genuine great LT compounding companies there are. And with an infinite time horizon it doesn’t matter. They are business owners not traders. I will be honest that I don’t understand the hate that Lindsell Train, Terry Smith, attract. It must because their strategy annoys people in its simplicity and lack of ambition. Far more exciting to bet the bank on risky micro caps, special situations, etc. I’ve said it before and I will say it again, for how many people (without insider information and a huge dose of luck) does this strategy really work out for. And I don’t mean in one lucky quarter but over decades. And no wonder. Because most companies let alone smaller companies are rubbish. I will be provactive and say that the odds are that £100 invested in Train’s strategy or Terry’s, and held for a decade from today, will outperform 90% of the frantic efforts of most private punters and closet tracking professionals
Lol I didn't think a joke about a £70 billion drinks company being "on the rocks" would annoy people so much.
The timing of his comment was funny, even he's bound to have found it amusing.
Maybe water it down next time ;)
Soda water?
No-one would accuse Gates of being a moron, but he's not regarded as a great investor.
Only the 5th richest man in the world (and that’s after putting sizeable chunks into the Gates foundation). Pretty successful in my book. But that’s because in my mind business owner and investor are synonymous. At any given time all ‘investors’ from richest to poorest have a wide variety of investment choices. Gates has invested the bulk of his time and made the bulk of his fortune in a phenomenal business: Microsoft. He is now cashing in some of the chips to spend on his philanthropic efforts and to diversify his wealth away from pure tech into other phenomenal companies like Diageo. Given he is self made from his net worth alone to say he is not a good investor is absurd. I grant you that the fact that he hasn’t destroyed billions by investing / burning cash in the likes of WeWork and Twitter, as per other billionaire peers, does suggest a lack of ambition and a lower risk tolerance. He could have bet the ranch and have even more. He could also be a lot poorer. But I wouldn’t say he is a bad investor by any stretch of the imagination
“Swing trading “ in a bear market v Investing
Quite a few comments recently on people finding bear market losses very painful.
There are quite a few “traders” commenting and unless anyone is Gordon Gecko crossed with lucky Lord Lucan with the superpowers of superman and the mental strength of Einstein I think it is very hard to trade in and out of a deep bear market.
And if you are doing this in small caps the spread immediately puts you 0-1 down before kick off .
And the stress levels must be huge .
Big kahunas needed for this .
The Warren Buffet “if yo could only buy 12 stocks in your lifetime” and “your buying part of a business to own for many years” mentality is where the long term gains are going to come.
I’m firmly in the latter especially now that I’m really bolted down to 6-8 really core holdings.
If anyone is swing trading / short term trading really need to be comfortable with the risk and possibility of losses and acknowledge rhis is a “swim with sharks” strategy with high risk reward and I think the odds are against success .
I agree with most of what you've said, but I don't think it has to be a binary decision, though I generally hold a much larger population of assets in my core portfolio. Unless you're as gifted as Warren Buffett, it can be extremely risky to hold such a small number of stocks, irrespective of their quality ... Ultimately, buying even the very best companies at the 'wrong time' can be as bad as buying shares in a poor quality businesses at the 'right time'...
I always tend to trade in/out of cyclical stocks, because there's rarely an opportunity to hold for the very long term. By 'trade', I mean holding a position for months (i.e. 'position trade'), rather than swing trading for a few days, which I'm not talented-enough to do. These 'tactical' trades would form 5% or so of my portfolio, but can make a worthwhile contribution to the overall return.
I would look at it another way .
It’s much more risky to hold a broader range of stocks, the broader you go you will simply just follow the market so you may as well invest in a low cost tracker .
The only way to outperform the market is to hold a tight number of companies that
- you know inside and out
- you have bought at a good price based on the fundamentals at the time
- that you understand the business .
It goes without saying buying a good company at the wrong time is silly , but there are sone basic business fundamentals that are easy to apply .
Ultimately I ask myself “if I could afford to buy the whole company would I do it” and that’s a real simple way to look at it . That’s the acid test question .
Can’t think of a time it has failed except in the case of bad management so I now add
“If I could afford to buy the whole company and be saddled with incumbent management would I do it “
I agree with you PlanetX....in theory.
In practice I'm afraid I disagree - not to provoke an argument, but to explain a different take on this.
I question whether the "know inside & out" bit is truly feasible, and I have my doubts about the "understand the business" bit as well.
When I was an institutional investor I met hundreds of management teams, including many FTSE companies. I've come to the conclusion that management themselves are often blind-sided by developments in their own businesses. That doesn't mean they are incompetent, it just means they are human and the world is unpredictable.
Ultimately management need to take a view on the future to plan capex, hedge rates & currency, invest in sales & marketing, manage inventory, make acquisitions and return spare capital. They have no choice but to take a view on various macro factors.
Taking a consistently correct view on macro factors is at the very least difficult, and some would say impossible. The best you can hope for is that management consider a wide range of scenarios and set their operational and financial gearing to cope with most of them.
And that is just the honest management.
You just have to look at numerous episodes such as Patisserie Valerie to see expert investors/board members being potentially defrauded by management. Greedy/overly ambitious management can also try to expand too rapidly and hit the rocks. Today's "good" manager can sometimes turn out to be tomorrow's fraudster.
I see diversification as my primary line of defence against fraud, management error and all those risks that I wasn't even aware that I was taking (the so-called unknown unknowns).
So I hold many companies. As an absolute return investor I don't mind underperforming a tracker on occasion.
In regard to the comment: "The only way to outperform the market is to hold a tight number of companies..."
That is simply not true...
Peter Lynch outperformed the market for many years, while he had a famously large portfolio, once owning literally thousands of stocks!
There are many ways to skin a cat and it is manifestly wrong that you 'need' to have just a handful of companies or 'need' to do anything in particular.
FYI: when I mention 'assets', I don't mean just equities. I mean the whole range of investments, including bonds, preferred stock, business development companies, reits, etc. etc. etc.
The only way to outperform the market is to hold a tight number of companies that
How many are you talking about - cant remember the relevant theory/principle but if you go too few you massively up the risk of a material setback that you can recover from to outperform. There may be some who get away with this strategy and well done them but they are provably the luck survivors. Cant remember the lovely bod who was posting here a year or two back got their portfolio up to 1 mill on ridicuously small set of stocks and the stocks were ridiculously dangerous ones to do it on. It might work and does work for soem but crash and burn is alwasy a danger. I would say 10 stock plus minimum for most peeps no more than 15% would be something i would say is on the risky side of stuff anything less and its super risky imho.
Whereas to give folk some idea of the range out there - my largest equity position across all accounts is 2.21% of my aggregated equity exposure.....
You can come to all sorts of conclusions on diversification depending on your assumptions and the data set (market, time period) you choose.
If you assume your equities are broadly uncorrelated and that each stock is as likely to go up as down (ye olde Brownian Motion analogy) then you can get to a number as low as 20 stocks to diversify away your stock specific exposure.
In reality stocks aren't uncorrelated. They can be in the same sector, or you coud be biased towards certain factor exposures, or a fund in wind-down could hold them all and start dumping them all at once.... So you will see that many fund managers will tend to hold in the region of 50-70 equities as this "feels" about right level of diversification so that one disaster doesn't hole you below the waterline, but you can still diverge from the benchmark performance. The marketing dept. will of course badger retail fund managers to reduce their holding count to avoid being labelled as benchmark huggers, but in a pension fund 50-70 is probably on the low side. A large insurance portfolio will hold many more to overcome single stock liquidity constraints.
Then if you are a fixed income investor it is a different game entirely. If it is gilts or treasuries then just holding one single bond will do. However, if it is corproate bonds there is an assymetry of risk. Oversimplifying slightly (i.e. ignoring pull to par & duration), the upside is your coupon, whereas if a bond defaults the downside is 60-100%. It can be argued you need to hold 100-150 bonds to diversify away your credit default risk.
If you are an equity income investor then some of the corporate bond maths applies to you as well, on the basis that there is limited capital upside to most high yielding equities (excluding distressed cos).
Have to say I totally don’t agree but each persons circumstances are specific to their position in life .
I have 8 main positions and 8 half positions . I do understand these businesses pretty well as I know their sectors and business models., there are two exceptions . Example Trifast I can see exactly where are they are where they need to go.
Crestchic where I was very overweight I had made 3 fsctiory visits, understood the product, and what I really understood was the operational upswing their new facility would give them as I literally had done the same thing . So I backed my hard learned and hard earned judgement.
In terms of risk and spread my diversification comes from not investing more than 20% of my wealth in a stock market which means my maximum exposure to an individual holding is 2% which is not going up really affect anything if it disappears
I’m 40% forestry, 20% stock market , 10% private businesses I own UK , and 10% very high risk foreign project .
20% left is property and cash .
Given the above for my circumstances I think totally pointless having 50 shares portfolio diversification as nothing would make any difference at all .
I certainly can understand all my small basket of stock market companies and two of my big holdings are very likely bid candidates and two have already been taken out .
My head would explode with more than 20 holdings but I am a bit “on the spectrum” and the accumulation and intensity of gaining specific knowledge about companies / areas is my “rabbit hole” tendency
I spent an entire week a few weeks ago reading and learning about high polyphenol olive oils and I have no idea what took me there.
Horses for courses but I’m very comfortable in my choices and they fit my circumstances and personality.
Remember for 30 years I had all of my investment were in one company only and I. had absolutely zero diversification so I’m very happy to be sat in this seat not that one .
We are not as far apart a you might think - I just run an equity exposure that is a multiple of your %, and correspondingly take less risk within it!
My recollection is that in theory statistically 12 diversified stocks gives the best trade off of risk and reward.
That recollection is probably based on a model assuming a Gaussian distribution (I used the term Brownian Motion to hark back to school days, same thing) of stock movements which is self-obviously incorrect in the real world, with a dose of Modern Portfolio Theory chucked in for good measure (and MPT is interesting in an academic sense, but so easy to pick big holes in). The diversification you need to real life is much higher than what models pump out.
The better risk models now run many thousands of random scenarios, repricing assets to see what happens when you get different combinations of big movements in yield curves, default rates and equity markets. You can either look at historic behaviour (which isn't much help if that historical period doesn't contain a stress period) or run factor models. Once you get non-linear assets in there like options/swaptions is all gets very expensive indeed.
However much you diversify within equities you are only taking away the stock specific risk (i.e. divergence in performance from the benchmark). When the proverbial hits the fan the correlation between stocks trends to 1 and everything goes down - you can't escape the systematic risk. At that point whether you're in single stocks or a tracker makes very little diference....other than you stand a chance of selling the tracker.
A big question is how to consider non-equity assets in an equity wrapper - investment trusts or structured vehicles where the underlying is infrastructure assets, fixed income instruments or real estate. Whilst their economic exposure for these proxy assets is very different the shares are still subject to equity supply & demand.....
And for those who quip that have had concentrated exposure to one company - I too have been there & hopefully you were able to exert considerable influence over that one company, you were able to veto crazy ideas and didn't intend to defraud yourself? It is apples vs pears.
I am with you planetx. As posted yesterday I have neither the ability or aptitude for 'swing trading'.
It's very hard. Shorting carries a higher risk as the heat has been taken out of the valuations plus increased takeover risk. Going long often sees false moves and you run the risk of bad news. Best markets to trade are euphoric bull markets and the start of a bear market where much of the market is in denial.
Warpaint London (LON:W7L) have got Friday off to good start with this morning’s further upgrade. Expansion plans look to be going well and the W7 range looks to be becoming a successful brand in its own right
After US listed elf Beauty (NYQ:ELF) recently disappointed I’m reassured that our home grown version is going well (as I hold)
Argentex
Worth keeping an eye on in next months as it may overshoot on the down side .
I never liked it much as I didn’t see anything to set it apart from all the other “money changers” sunch as moneycorp and I did not think much to Harry Adams as CEO albeit based on fleeting dealings with him 30 years ago when I was young and stupid .
Today they revert to no growth and static performance .
Assuming they dont grow it is actually still an ok well established business with 20 million cash, making 10 million a year (7 million after tax) and spitting out cash .
Even on a terrible ex growth PE of say 4 then add the cash by my fag packet of this goes sub 48 million market cap it has overshot big time so as it’s at 68 million now if it dies drop another 25% it becomes too cheap .
Just a quick fag packet . Hopefully for holders doesn’t collapse to those levels but the point is it’s a decent business and strip out the “growth prospects” hype nothing wrong with a business that can make 10 million quid a year
Assuming they dont grow it is actually still an ok well established business with 20 million cash, making 10 million a year (7 million after tax) and spitting out cash .
It’s a high touch FX service whose entire senior management have just jumped ship. There’s every chance of significant churn amongst fee earners who would be warmly welcomed at the competition. While growth could return it’s not inconceivable that those revenues dwindle as the business is hollowed out from within. I’ve been bearish on this one for years and in all my comments. It’s not a great business model, and management were, shall we say, inadequate. There’s better risk/reward in multiple good names at cheap prices.
Mmmm, I think that is a little harsh .
Management had to go because they predicted growth with their fancy plan.
As a currency buyer I can pretty guarantee that the customers will not switch .
At most companies the FD / FC will certainly not change their buying habits on currency and the companies they buy from have had a CEO / CFO change .
They will carry on calling moneycorp / argentex like they have done for the past 10 years to buy their dollars when they need to send money to a supplier .
That is why it is relatively steady state business .
In fact something just occurred to me,
- given the declining economy the amount of currency bought in past year is going to be well down
- so if Argentex have maintained status quo that is actually a pretty good result !!!
Never thought of that before
Mmmmm
That’s a questionable guarantee to make about customers not switching. I know a lot of FX salespeople. It’s a relationship business and always has been as it’s a commodity offering reliant on execution and bank lines. These second tier shops work because the banks are now happy to offload the compliance of small accounts. The business model works as the salesperson takes a healthy cut of the brokerage and brings in clients who are loyal to that salesperson not the institution. There is no doubt their high performers will be being courted by competitors & it’s a highly mobile employment environment. In a worst case if they start going it could become a stampede, those that stay would probably demand a bigger cut at the same time as less flow through the business as major clients drift away.
My morning smallcap tweet: Overture to Twilight of the Dogs (Götterdämmerwarning)
Argentex (LON:AGFX) Global Ports Holding (LON:GPH) ValiRx (LON:VAL) Warpaint London (LON:W7L) Physiomics (LON:PYC), Galliford Try Holdings (LON:GFRD)
◄Argentex (AGFX)► troubled finco that's just lost both CEO and CFO warns FY-Dec rev and op profit flat ie under market forecasts. Why didn't it warn yesterday when CFO left. Guided rev 28% up in July. What the hell is going on? Reviewing strategy. [SP=60 Cap=68m]
◄Global Ports Holding (GPH)► guides FY-Mar passenger volumes 0.7m ahead of guidance at 12.5m+. [SP=250 Cap=170m]
◄ValiRx (VAL)► agreement with StingRay Bio to investigate a lead series of drug candidates for use in oncology. COE trills: ""It is hugely exciting to have another evaluation agreement commencing, particularly one such as this which has a high pedigree of medicinal chemistry". [SP=12.09 Cap=12m]
◄Warpaint London (W7L)► guides FY-Dec rev £85m+ and pretax over £16m, both ahead of market expectations. [SP=313 Cap=241m]
◄Physiomics (PYC)► get gov't grant for 70% of £196k project. [SP=1.61 Cap=2m]
In line: GFRD
Loving the Wagner reference Mr C
#AGFX (Mrkcap £68m)
As expected specialist forex dealer Argentex (LON:AGFX) reset the FY'23 guidance bar today. Saying FY23 sales & operating profit would come in about the same as last year (re revs £50.4m & EBIT £12.3m). In turn, missing house broker Singer's forecasts of £60.0m (-16%) & £13.8m (-11%) respectively.
More positively though, the H2'23 run-rate is presently tracking at approx £25.4m sales and £6.9m EBIT vs H1'23 of £25m and £5.4m.
Which to me says this certainly doesn't look quite as awful as yesterday's stock price collapse implies?
Indeed the shares (60p) appear to trade on FY23 EV/EBIT and PER multiples of only 5x and 7x respectively, assuming Dec'23 net cash (ie freely distributable) of c. £10m.
Argentex (LON:AGFX) - It’s the announcement of a strategy review that tells more of a story IMO. They changed strategy only last year. It doesn’t sound as though they know what they are doing. And everyone who was leading the charge has left. Who wants to own that? And who wants to entrust their FX hedging to a rudderless company that is being out-competed on all measures?
Argentex (LON:AGFX) . Singers original forecast for the year was £70 million of revenue so £50 million is quite a drop. There was quite a good conversation on this board in July after the chairman left where a number of people pointed out that they weren't going to hit their numbers for the year. So I guess you could say that in this case the signs were there.
£AGFX
Thanks Paul, that's a neater analysis than mine, but looks like we ended up with a similar conclusion! (share price possibly overdone?)
Interesting comments above from other subscribers too.
I like that AGFX has a sector expert guy already in charge, and it sounds like maybe he orchestrated pushing out previous management, who I've not heard anyone say anything positive about? Just guessing there.
Vertu Motors (LON:VTU. Intriguing price rise yesterday. Does anybody know what triggered this??
Yes, if you check the newsflow for Vertu Motors (LON:VTU) you'll see that Cinch Holdco, part of Constellation Automotive (owner of Cinch, Marshalls, BCA and We Buy Any Wreck) increased its holding. [I hold]
Vertu Motors (LON:VTU) I hold
Significant SP move yesterday as GN100 says. Does anyone know in what circumstances a company is required to comment ?
I dare say it was Auto Trader (LON:AUTO) what done it.
Hadn't spotted that. Does anyone else feel Auto Trader (LON:AUTO) is wildly overvalued over 6.5bn
high PE, low divi. But stonking cash flow
Like a Rightmove (LON:RMV) jn my opinion before it collapsed. Very very high margins, bit of a "moat" but if someone challenges it then even a 50% fall wouldn't be enough.
Argentex (LON:AGFX) - ouch! They’ve suddenly discovered that there’ll be no growth at all this year. Well, it is only November.
Warpaint London (LON:W7L)
Consistently under promising and over delivering, W7L issue another “ ahead of” trading up date this morning, plus lots of new space won in UK and non UK retailers. Looking good for further growth.
http://newsfile.refinitiv.com/...
After last night's US sell-off induced comments by Fed Chair Jerome Powell - re "We're not confident that conditions are sufficiently restrictive at this point to get inflation back down to the target rate of 2%".
Then European markets are set to open lower this morning. May be US interest rates haven't yet peaked?
Interesting day over the pond for sure with the Nasdaq ending the day up over 2% and with the S&P, Dow and Russell all up signifcantly over 1% too.Makes total sense...Some of us uk small cap owners need more of that over this side of the pond for sure to buoy our weathered spirits.