Small Cap Value Report (Fri 10 Sep 2021) - FUL, MTC

Good morning, it's just Paul here with the SCVR for Friday, thankfully a quieter day for news, in a very busy week.
Today's report is now finished, because it's quiet, and I want to spend the afternoon visiting the Malta At War Museum!
Agenda -
Paul's Section:
Fulham Shore (LON:FUL) - a positive trading update, with recent sales showing a strong trend. Ambitious expansion plans are underway. Shares look pricey, but that reflects the growth in the pipeline, with many new sites being offered by landlords on attractive terms, hence an excellent time to be expanding.
Mothercare (LON:MTC) (I hold) - a strangely worded trading update, but seems to be saying that trading is improving. Remember it's a franchise businss now, so much simpler. However, the pension scheme deficit recovery schedule looks set to absorb all the profit & cashflow. Hence it's questionable whether the equity has an value at all?
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Fulham Shore (LON:FUL)
18.15p (last night’s close) - mkt cap £113m
Jack published an excellent, and thorough review of the FY 03/2021 results from this casual dining chain(s), here in August. I’ve just read that, to get up to speed.
Accelerating momentum and continued expansion
Revenue growth is accelerating, which is clearly good news -
Since the Group's Final Results announced on 17th August 2021 Group revenues have continued to grow. In the three completed weeks since (up to 5 September 2021), Group revenues for all restaurants have increased 27% compared to the equivalent period in the 2019 calendar year.
This represents a marked acceleration from the 8% average increase for the eight weeks ended 15 August 2021 announced in the Final Results.
However, the above is ambiguous. It’s not clear whether +27% (vs 2019) is for total revenues, or like-for-like (LFL) sites only (the more meaningful performance measure)? The way it’s worded, it seems to be total revenues, not LFL revenues. It’s generally accepted that LFL revenues gives a clearer picture of underlying performance. I’ve lodged a query with the company’s advisers, and will update this if/when I get a response.
Checking back, FUL had 67 sites at this time in 2019. It now has 75 restaurants, so a 12% increase in site numbers. Hence, crudely, that could mean the 27% increase on 2019 sales might reduce to about +15% on a LFL basis - still good, especially because the 17 sites in the West End of London & some other city centres, are still struggling, with sales negative vs 2019, albeit improving on a week by week basis, as people gradually return to offices.
UPDATE at 08:45 - my query has been answered, I'm pleased to report. My interpretation of the RNS was correct, so the 27% revenue increase on 2019 is not LFL, so it does include the benefit of new sites opened over the last 2 years. That's fine, I just wanted to clarify it. Apparently capacity has increased 15%, hence LFL is reckoned to be +12% - a bit below my estimate of +15%, but I was in the right ballpark pleasingly! This is very positive, because it includes the drag of some London sites & other city centres, which are reckoned to now be trading about -20% LFL (improved from -41%)
Analyst forecasts - FY 03/2022 is currently pencilled in for only just above breakeven at the profit before tax level. Although the share seems to be valued on an EBITDA multiple. Forecast EBITDA for FY 03/2022 is £8.3m (this number strips out the ludicrous IFRS 16 distortions). This is a reminder that the capex has been very considerable, hence the large depreciation charges. I'm a bit uneasy that the market ignores capex by valuing the business on an EBITDA multiple.
Forecasts have not been changed today, but expect upgrades in September.
End of update.
There has been other data reported in the press confirming that cities are coming alive again, e.g. rail and public transport volumes recovering (albeit still well below pre-pandemic levels).
It’s clear that the trend is improving anyway. Let's hope it stays that way.
New site openings - this is a key aspect of this share. It’s a roll-out, with a major expansion planned in coming years, with conditions now very favourable (many sites, on reasonable rents, being available). Also there’s less competition, with Italian-style restaurants seeing the greatest loss of capacity, according to some data provided by TGI (I hold via Electra Private Equity (LON:ELTA) ) recently. There was an obvious glut of me-too Italian casual dining chains, so it’s a good thing for FUL that the market has thinned out somewhat.
Also, I think most people would probably agree that FUL has a clearly differentiated, even quirky, product offering, which makes it stand out, and builds customer loyalty. I also like its every day low pricing model. Plus it seems to have bolted on successful takeaway & delivery options during the pandemic, making it a better business now. As we’ve seen with many other companies, a crisis often leads to efficiency & innovation, making businesses better.
2 more sites are currently fitting out, with 15 more in solicitors hands, so it looks like the pace of expansion is cranking up. It’s going to be a much bigger business in a few years’ time which is one of the reasons why the share price is so buoyant.
We continue to see a number of exciting growth opportunities and are on course to open 10 locations during the current financial year, with more than 150 additional sites in our medium-term plans."
Diary date - 29 Sept for yet another trading update (which will be the third in 7 weeks) - which makes me wonder if the company might be planning to raise some fresh equity, since it seems so keen to update the market on improving sales repeatedly? That’s complete speculation on my part. The NOMAD & broker was changed on 5 August 2021, which can also sometimes be precursor to a placing.
I don’t think it would be a problem - FUL could probably raise funds from a position of strength, and without needing to offer a discount. But I would factor in possible 10-20% dilution into my valuation calculations.
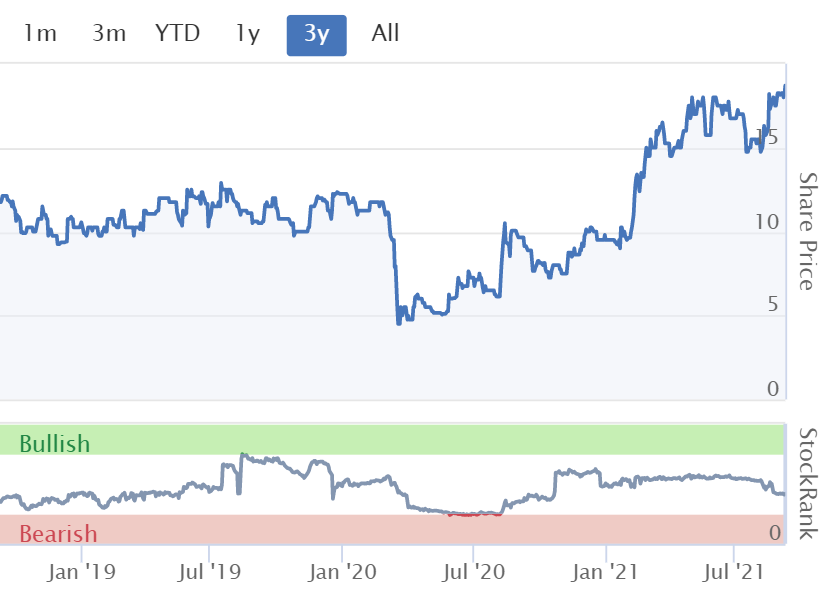
My opinion - it’s a good business I think. Valuation looks a bit toppy, but the rapid expansion plans mean that the business should grow into the valuation, with new sites being acquired on favourable terms, due to the glut of empty units out there. Mind you, new restaurants, cafes & bars seem to be springing up all over the place, so I wonder how long the glut of supply is likely to last?
Headwinds are considerable - business rates kicking back in, well-publicised staff shortages & rapidly rising wages, food/drink cost inflation & shortages from supply disruption. So it won’t be easy, and shareholders in lots of companies need to brace for problems over the autumn/winter.
Overall, I’m not sure about valuation, but I do see FUL as a long-term winner.
The hidden gem in this sector, in my opinion, is TGIs - owned by Electra Private Equity (LON:ELTA) (I hold) and about to be spun out in a separate listing. The valuation there looks extremely attractive in my view, especially as you get strongly performing Hotter Shoes thrown in for free (which I think could be worth £50-100m in due course, when it is also separately listed). Hence I have a big (for me) holding in ELTA, and would only buy FUL on a significant dip in price from the current level - possibly also because I'm being emotional & still kicking myself for not buying FUL when it was 6p! We're all human, and I really missed a trick there, never mind.
.
.
Mothercare (LON:MTC) (I hold)
17p - mkt cap £126m
I should emphasise that I only have a tiny scrap of this share, which I should probably sell to clear the decks, but haven’t got round to it. So it’s not a conviction hold at all.
AGM Statement & Trading Update
This update came out during market hours earlier this week - it’s infuriating when companies do that, and it should generally be outlawed I think. It’s just not right to put out price sensitive information when the market is open, because it gives an unfair advantage to professionals, and disadvantages non-professional investors who will be busy doing something else during the day.
All 14 AGM resolutions were passed with 99%+ votes.
More of interest to us here, is this trading update -
Trading Update
Whilst we still anticipate that the steady state operation of our existing retail franchise operations, in more normal circumstances, should exceed annual operating profits of £15 million, the Group has continued to be impacted by Covid-19 during this financial year.
For the first 21 weeks of our current financial year to March 2022 our total retail sales were £136 million, generating an adjusted EBITDA of approximately £4.0 million representing a significant improvement over the adjusted EBITDA of £2.2 million reported for the year ended 27 March 2021.
What a strangely worded announcement!
As it says, this is a franchise business now, which doesn’t handle any stock - it’s supplied direct, and paid for by the franchisees, with MTC just taking a profit cut - a really nice business model actually.
As I read that, it seems to be saying operating profit should recover to £15m p.a. over time, as the pandemic recedes. The problem with that - it’s not enough. Look at the currently agreed pension scheme deficit recovery payments due -
A reminder of the cash over-payments as currently scheduled -
FY 03/2021: £3.2m
FY 03/2022: £4.1m
FY 03/2023: £9.0m
FY 03/2024: £10.5m
FY 03/2025: £12.0m
FY 03/2026: £15.0m
FY 03/2027: £15.0m
FY 03/2028: £15.0m
FY 03/2029: £15.0m
FY 03/2030: £5.7m
Total: £104.5m
Therefore, unless Mothercare can significantly increase profits from its normal run rate (it’s behind that at the moment remember), or the pension scheme can somehow be changed so that reduced deficit recovery payments can be arranged in future, then the business really only exists to service the pension fund. There’s likely to be little, if anything, available for shareholders.
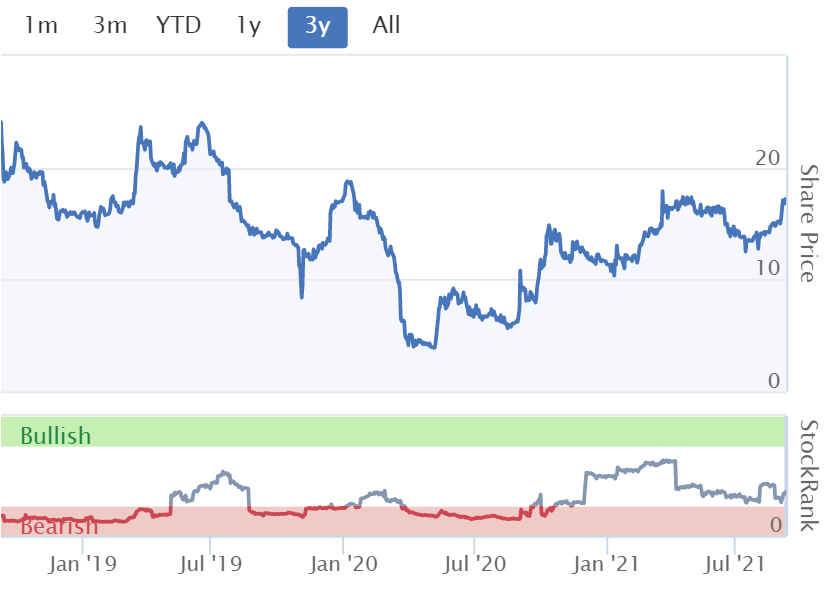
My opinion - unless something changes for the better, then it’s difficult to see any value at all in the equity. That said, investors seem to be ignoring, or are unaware of the pension deficit, or maybe have some insight which makes them think the problem will get resolved somehow. The shares seem to be finding a bid at the moment, so I’m going to let my small position run, and see what happens.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Footnote to the Fulham Shore (LON:FUL) write up, a combination of directors and employees have exercised various share options and sold a fair chunk of these and other holdings (about 3.7% of the issued share capital) today (24/9) in a placement at 18p. Full details in this RNS which was followed up subsequently with confirmation that the placement was successfully completed.
https://www.investegate.co.uk/...
Seems to be a fairly comprehensive statement by a cross section of the company’s directors/ employees that the shares are fully priced at the moment.
Gus.
How does one "Not get Round To Selling"
Mothercare most 'underappreciated' opportunity in UK retail - Shore Capital
** Shore Capital reinitiates coverage of Mothercare Plc with 'Buy' rating and fair value of 23 pence; adds MTC is most underappreciated opportunity within brokerage's UK retail coverage
** Over next year, brokerage expects baby products retailer to return to high single-digit EBITDA margin
** "The value in MTC equity is not in the rear-view mirror, it is very much in the windscreen," says Shore Capital; adds they believe MTC's brand position will help its franchisees
** Brokerage says co's 15 mln pounds ($20.81 mln) EBITDA target is achievable by 2024 and expects MTC to be debt-free business within 5 years
** YTD, MTC is up ~51%, outpacing UK mid-cap index's .FTMC 16.40% gain
Mothercare (LON:MTC) - "debt free". Suppose it depends how you define the pension deficit........
My new office for the next few days! (in Valletta, overlooking Grand Harbour) -
Like your boat!
I'm never envious of superyachts! The annual maintenance costs are typically 10% of the purchase price. So whoever owns that gin palace (probably a Russian or Saudi crook!) is bleeding cash, which creates work for plenty of other people. All good! :-)
sh*t job but someone's got to do it.
Love the idea of you doing this from various spots around the globe. We get a combination of financial insight and travelogue. Brilliant. Where to next?
Re ELTA - I think those basing their impressions on TGIF's from 20 years ago, should update their language. The new Mgt are selling "Friday's" as the brand not "TGI/TGIF", as I understand it. I have no idea whether this name (and the "concept" behind it) will appeal this time but be aware this is pitch they are swinging at..
If too many people who liked TGI's go (with average age of 55 ie the same as me) , then the free-spending late 20/early 30s they are targetting will not. Who wants to meet you mum or Dad (or their peers) on a night out.
Personally, I think the new concept is still too close to the tired American themed bar concept that is a bit old now - a bit Frankie&Benney, if you like. Have you watched Friends or Cheers lately and thought the world has moved on.
In retrospect, they were the last cultural hurrahs of a 'white', popular American culture. I make no value judgement, here - just wonder about bums on seat potential for today's trendy young.
Net, as an ex-FMCG Mkting bod, I can see how I would sell this to potential investors but am less confident about the target audience. Paul might make a 'pop' at IPO but would be nervous about this as a long term hold which is what I want.
But what do I know - I thought Rev de Cuba was a good prospect.
Hi Zipmanpeter,
Have a look at the Friday's CMD presentation slides & video (apologies if you have already), there's a lot more to it. I think we might have discussed this before, it's ringing a bell.
Anyway, I'm not looking for a "pop" as you put it - best not to put words into my mouth if you don't mind, it's a bit irritating when people do that.
I've repeatedly said that I see Electra Private Equity (LON:ELTA) (I hold) as a long-term thing - I really like both businesses - Fridays, and Hotter Shoes, and would want to buy both if they were IPOs. The fact that ELTA gives me a super-cheap (as I see it, and compared with fresh IPOs) entry price into both, is superlative.
Anyway, let's see what happens. The price of both shares this time next year, or beyond, is what interests me. I'll close my eyes & ears in between, as anything could happen!
Best wishes, Paul.
Paul - my apologies and I fully accept your justified 'pop' at me for implying you/starting were after a 'pop' at IPO - you have been consistent that you see/want Electra Private Equity (LON:ELTA) as long term!
Sloppy writing on my part. I should generically have said "one might see" (although this makes me sound like the Queen).
Finally, thanks for writing about £ELTA - I have been through the presentation decks and I really like the look of Unbound if not Friday's.
I learn so much from this column & related discussions and I am so impressed you can write so much so well so quickly....with so few errors like mine here.
Sounds patronising (more rushed writing by me ?!?)...... but please keep up the good work - it's enjoyed and appreciated and has built such a great community blog.
Sylvania Platinum (LON:SLP) - a lot of SCVR readers wanted Jack to update you on this one, so he's written a separate article on it, just published here.
Electra Private Equity (LON:ELTA) (I hold) Scuttlebut
Last night I visited 63rd + 1st in Cobham. This is the first of the new upmarket restaurant concept being rolled out by Fridays, to be floated out of Electra Private Equity at the end of this month.
I had dropped in for cocktails on a Tuesday evening when they first opened back in May and there were very few people there but some very keen staff who were eager to impress.
Since then I have heard a number of disappointing reports about the food and service. Recently I heard that a new manager had been appointed and that things were being turned around. When my son suggested that he would like to visit before returning to university, I took the opportunity to do some research (and have an enjoyable evening).
Encouragingly (from an investment point of view), we were unable to get a reservation until 8:45 when booking a few days in advance. Last night we arrived slightly ahead of our booking to have a cocktail at the bar. We were greeted warmly and took some seats in the window. Both the restaurant and bar were busy.
The menu is somewhat limited but we knew this beforehand. Starters arrived quickly, were well presented and very tasty. Our steaks were both tender, flavoursome and generous portion sizes. Service was attentive.
Unsurprisingly, by the time we left it was much less busy than when we had arrived but overall, it appears that the new concept is going down well in Cobham.
I look forward to the floatation of Fridays at the end of the month.
Many thanks to Paul for bringing this opportunity to my attention.
Thanks SurreySteve,
Really interesting scuttlebutt, thank you for posting!
The Capital Markets Day recently held for TGIs was fascinating, but I can't find the link for the huge slide deck. Management are very ambitious for not only TGIs, but their new more grown up cocktail bar/bistro format. Two roll outs for the price of one!
I think Hotter Shoes could be a nice little float too, worth multiples of what it's valued at within Electra Private Equity (LON:ELTA) (I hold) in my opinion.
ELTA still seems to be off the radar of most investors - which is great, because it means more upside for us when the situation becomes better known to the wider investing community. One to be patient with I think, not one to flip, in my personal opinion.
Regards, Paul.
Yourgene Health (LON:YGEN)
Good morning Paul, as it's a quiet day, do you have any comment on the announcement of the potential value of the YGEN contract with Dept of Health. Up to £34M for a £115M market cap company is pretty material.
Morning Samsgrandad,
I tend not to report on Yourgene Health (LON:YGEN) because there's not much to analyse in the numbers - loss-making so far, hence the value in the company rests entirely on investor hopes for improved future performance. That's not something I can forecast, it would need more detailed research and analysis. Remember we're covering over 500 companies here, so can only give a quick skim over the figures, we're not trying to predict what the future holds, because we don't know!
That said, this does look like a hefty contract, although £34m is the maximum potential value. I'd want to know over what period of time, and most importantly, how profitable is the work?
Incidentally, I met Adam Reynolds a while back, who promotes lots of small speculative companies (he floated Sosandar (LON:SOS) for example). He gets a lot of stick from the bulletin boards, but is actually a very nice chap, and really smart. Nobody is forced to buy any of his shares (I wouldn't touch most of them, because they're usually too speculative, but the odd one does well).
Anyway, the reason I mention him, is that over our lunch, the one company he was really raving about the most, from his stable, was this one, Yourgene Health (LON:YGEN) - saying that mgt are fantastic, and the company has tremendous potential. That was maybe 2 years ago, at a guess?
Anyway, I have absolutely no idea where to start, in analysing this type of company, as we discussed the other day, these type of growth companies need a completely different skill set to my value/GARP approach.
The problem I have with shares like this, is that so few of them end up long-term winners. Many have speculative periods (especially at the moment), but then disappoint, repeatedly raise funding, diluting original holders down to practically nothing, very often. So it's like searching for the proverbial needle.
Good luck with it, if you hold. A large new contract certainly adds weight to the investment case, and could see broker upgrades, I don't know.
Regards, Paul.
Missing from the Fulham Shore (LON:FUL) trading update, any commentary (either positive or negative) on staffing, wages, raw ingredients, supply chain.
Might be that they are coping well. Or conveniently cherry picking what to update on trading.
It's live, the Stockopedia/PIWORLD StockSlam September! Excellant pitches covering Robert Walters (LON:RWA) Argentex (LON:AGFX) Capita (LON:CPI) Belvoir (LON:BLV) Ab Dynamics (LON:ABDP) Base Resources (LON:BSE) Totally (LON:TLY) Watches Of Switzerland (LON:WOSG) Geiger Counter (LON:GCL) Quiz (LON:QUIZ). Excellent 'slams' by everyone. If you fancy 'slamming' at another event, please email here.
This is the fifth virtual StockSlam hosted by Damian Cannon. Not only is it great fun, the track record has been pretty impressive with each portfolio of ten picks up as follows: from February 2021 +23%, April +18.5%, May +10% and June +9.6%. The single stock winner has been Tekcapital (TEK) up 186%, followed by Renold (RNO) +63% and Cakebox +51%. Video & podcast.
Later yesterday, we published Emis (LON:EMIS) H1 analyst webinar. If you missed it, it's worth a listen. A very interesting company who are pioneering in the NHS digital transformation, enabled by CV19. Video & podcast.
If energy storage of renewable energy interests you, listen to the interview with the CEO of Invinity Energy Systems (LON:IES) They manufacture Vanadium Flow Batteries. It will take time to come to profit, but with a long term view it is very interesting. They have a JV development agreement with Siemens Gamesa which is encouraging. Always difficult to know who will be the winnersin this space, but they are fulfilling projects now, and it sounds very promising. Video & podcast.
PIWORLD webinars forthcoming are:
Somero Enterprises Inc (LON:SOM) Monday 13 September, 2.30pm
Property Franchise (LON:TPFG) Wednesday 13th September, 12.30pm
Litigation Capital Management (LON:LIT) Wednesday 22nd September, 9am
Register for all here.
My morning smallcap tweet: Black mark for Newmark
Tritax EuroBox (LON:EBOX) Argo Blockchain (LON:ARB) Yourgene Health (LON:YGEN) Minds Machines (LON:MMX) Fulham Shore (LON:FUL) IQ-AI (LON:IQAI) Newmark Security (LON:NWT) PCF (LON:PCF)
Tritax EuroBox (EBOX) £170m placing at 111.5, a 3% discount. [SP=115 Cap=709m]
Argo Blockchain (ARB) increases Bitcoin-backed loan by £18m "to continue the build out of the Company's West Texas data centre and to meet the Company's operating cash flow requirements." Isn't it throwing off cash with Bitcoin over $33k? [SP=134.82 Cap=515m]
Yourgene Health (YGEN) wins lab covid test contract worth £34m max. [SP=15.82 Cap=115m]
Minds + Machines (MMX) tender at 9.6p, a 13% premium) for up to 69% of shares. [SP=8.36 Cap=73m]
Fulham Shore (FUL) recent 3 weeks rev up 27% on 2019. Prev 8 weeks was 8%. [SP=18.05 Cap=112m]
IQ-AI (IQAI) Gallium Maltolate phase I clinical trial delayed to end Q4 2021 due to a change in the trial agent's encapsulation supplier. [SP=6.75 Cap=11m]
Newmark Security (NWT) misleadingly says FY(Apr) rev ahead of management's expectations. Co already guided the rev in the FY trading stmt. However current trading is "ahead of revenue expectations albeit with a different phasing of certain lines of business with varying margins which result in a reduced margin." Going concern stmt shows cash v tight. Negotiating increase in UK invoice discounting facility and a new US invoice discounting facility. [SP=1.16 Cap=5m]
PCF Group (PCF) still no restatement of 2020 accounts. Net reduction of profit will now be more than £750k, not less, Remains suspended. [SP=23.8 Cap=60m]
Possibly one of the worst 'updates' I've read, from PCF, this morning. After months of investigation, no information given except that the restatement will be higher than estimated (how much higher?). Not sure who to moan about, the management or the auditors.
Pcf (LON:PCF)
Possibly one of the worst 'updates' I've read, from PCF, this morning
Yep another horrendous slap in the face here - i kinda guess they are going back through every tranbsaction from the year dot for very little practicable benefit - by now they should have been able to do whatever needs to be done for regulator - go through the loan book / accrual / prepayments and other balance sheet ledgers in detail and have had this sorted a couple of months back. Frankly ridiculous situation.
It was 11th March when they advised
"The adjustments are expected to constitute a net reduction of not more than £750,000 against a previously announced profit before impairment of goodwill and tax of £3.9m. "
So for them to sit twiddling their thumbs swapping seats and whatnott for 6 months without digging into the detail properly is a complete joke. whoever they have engaged since before March to short this s show has really not helped the cause and the bods in charge really have been poor at coping in what i would agree is a bit of a crisis.
Re Pcf (LON:PCF) - I absolutely agree - the time to resolve this mess is scandalous and the chances of a good price at the end of it is reduced by the length of time it is taking.
Personally, I had written it off as possibly worth nothing but if the variation is still in the ballpark of £750K- vs the issue£1Mn, then the value destruction from delay will be huge.
If it is going to be significantly more ie £5M to complete write off, then surely we should be told !!
To not know more after this length of time is dreadful
Pcf (LON:PCF) - endgame -> the Caribbean based family office that is majority holder of the shares will take private and refinance. So PIs have plugged in the cash to create the business growth and now the owners who lent it out to PIs for a bit of fun take it back and keep all the value created. Did the old CEO know the endgame? Ummm...he's been there a long time (associated with prior mistakes too). And seemed ready to make a sharp getaway too (I believe he literally flew the coup). Where is he now?
They will offer some pennies for your shares.
If the scenario above occurs (I've been predicting for at least couple of years) then the FCA should investigate. But they wont.
PCFs approach to growth and lending has been clearly reckless for a while
Pcf (LON:PCF)
You have certainly done a great job at pointing out the dangers here mojomogoz - hopefully one or two bods more sensible that me paid heed to your warnings!
Good morning Paul and Jack!
Is it too much to ask for your thoughts on yesterday's Burford Capital (LON:BUR) update? It is considered a small cap in the USA (where they are also listed). It's an unusual company but that is a very good thing these days when looking for uncorrelated portfolio returns!
Take care,
S.
Hi shamusj.
I think you might be expecting a lot of Paul and/or Jack asking them to pick over Burford Capital (LON:BUR) in the daily SCVR coverage! I’m a long term holder and follow them closely but it really is a labyrinth trying to pick the bones out of their financial statements and correlate the invariably bullish noises from the company in their investor presentations with the reaction of the share price (which usually move in polar opposite directions).
I think Burford Capital (LON:BUR) is arguably one of the most “marmite” stocks around and depending on who you listen to is a gold mine going to the stars (Cannacord and others) or a complete crock of s**t that is a tissue of dodgy accounting with zero value (Muddy Waters). If you want a bit of bedtime reading it’s worth looking at some of the previous discussion threads to get some of the backstory. This one from 2019 has no less than 407 comments and covers the period of the Muddy Waters’ “shorting dossier” that saw the share price tank from the £20’s and rising to about £5. It’s never really recovered even though much of the Muddy Waters’ mud (no pun intended) doesn’t seem to have stuck.
https://www.stockopedia.com/co...
I don’t hold many stocks on instinct (i.e. shares where I don’t feel fully comfortable I know what’s going on but continue to hold anyway) but Burford Capital (LON:BUR) is one of them - it’s in the coffee can and staying under the bed.
Gus.
Thanks Gus, I'm fully aware of all of their history and have studied them deeply for over 6 months.
My request was mainly for the benefit of others, perhaps to provide the springboard to do more research. The muddy waters saga that was in the past has actually created an incredible amount of transparency (as far as legally possible due to the nature of their business) from the management of £BUR.
All the best,
S.
I feel your pain Gus too as I was stung by the Muddy Waters attack and I have exactly the same under the bed view as you :)
The BUR roller coaster (I hold £20K ish) I was amazed they banged in a loss, they always talk a good story, RNS waffle on generally, last few RNS's regards profits have been good, when I saw this I expected the price to fall through the floor and it didn't. As you say it needs some explaining
Morning shamusj,
Is it too much to ask for your thoughts on yesterday's Burford Capital (LON:BUR) update?
In a word, yes!
It's £1.8bn market cap, and very complicated to analyse, so we don't analyse that type of thing here, or we'd have no time left to cover the other c.500 companies we report on! ;-)
No offence, best wishes Paul.
Hi Paul, re ELTA and TGI Fridays, is your perception then that TGI Fridays is a good company? I have never been to one but my son (aged 33) and his girlfriend are both of the view that it's a tired brand. They did say, though, that they only know the London ones.
I agree it feels very 1990s, serving things like burgers and chicken wings (very expensive too!), although it does seem to be doing well based on recent updates and always look quite busy.
It would help if you said which company you are talking about.
I was replying to rogerh who had already stated the company (TGI which is part of Electra Private Equity (LON:ELTA))
Electra Private Equity (LON:ELTA) / TGI Fridays.
The last time I went to a TGI must have been in the.....90s. But I seem to recall that the motivation wasn't the meal, rather the atmosphere & ability to meet up with a large & fairly loud group of friends in a boisterous venue where it was accepted. If that's still the typical clientele, maybe the food needs to be simple & fairly innocuous?
In terms of food pricing, look what people are happy to spend on cocktails in the right venue......
Maybe I need to revisit my youth - as I hold £ELTA........
I'm another hoping TGI's has more appeal to it's clientele than I would ascribe to it, as a holder of £ELTA. My last visit would have been around the turn of the millennium and I thought it was in the same category as Frankie and Bennies - somewhere slightly above the Ratner estimate of his jewellery.
I wouldn't say much more for the Fulham Shore (LON:FUL) offer either. Visited one as Paul is so keen but thought the offer was as thin as their pizzas. However, so long as their target audiences are happy and the numbers add up I'm happy to take the returns. These things are so much a matter of taste as a consumer.
We just need to be vigilant of other offers appearing which may take this section of the market with them as the likes of Cafe Rouge, Pizza Express, ASK and others have done before. Perhaps a bigger concern short term is the continuing rise in Covid rates, and a likely October reset to avoid the mistakes of last year repeating, and the wave of inflation that is starting to work its way through - from farm to fork.
Newish management have done a root & branch refresh of TGIs, and it's much better now. My recent store visits confirmed this. So I wouldn't base your views on previous experiences. The only thing I didn't like was the American draft lager, which was a bit flat, but that could have just been an off-day. Food was excellent I thought, nice atmosphere, very good staff, and a buzzing atmosphere, and fully booked. So I suspect read-across from FUL's positive update today.
Most importantly, TGIs is highly profitable and cash generative, with the forecast run rate c.£40m EBITDA. That makes it a lot more valuable than the current mkt cap of Electra Private Equity (LON:ELTA) (I hold), plus we get Hotter Shoes (also profitable) thrown in for free.
I think there's at least 50% upside on ELTA shares, maybe 100%, with a 1-2 year view. As always though, I could be wrong, so make sure to DYOR.
Regards, Paul.
TGI and Hotter listing was expected in 3rd quarter which ends soon. It seems Hotter is now not until 4th quarter. No news on TGI by now is surprising. The sooner they do it the better imo. Current headwinds like wage increases, staff shortages, supply issues etc could get worse. The Electra Private Equity (LON:ELTA) share price has fallen back. Isn’t an update on this well overdue?
Electra Private Equity (LON:ELTA) - there's due to be a Capital Markets Day on 15th Sept (Wednesday next week), focussed on Unbound (Hotter Shoes). So wouldn't be a surprise if Hostmore (Friday's) float is imminent.
Hi Ken,
Why is everyone so short-term these days?
We're not buying this quarter's earnings, we're buying all earnings for the rest of the company's life.
P.
Fair point Paul but I’m a very patient investor but accept that my post suggested otherwise! The key point was that investors had been told it would be in 3rd quarter and if that’s no longer the case ELTA shareholders should have said so by now. But as garbetkcb replied there may well be news on the 15th.
A reason why the sooner the better is the risk of new vaccine resistant variants and risk of market falls , and renewed lockdowns, which would make TGI a less attractive proposition.
Hi Roger,
Hi Paul, re ELTA and TGI Fridays, is your perception then that TGI Fridays is a good company? I have never been to one but my son (aged 33) and his girlfriend are both of the view that it's a tired brand. They did say, though, that they only know the London ones.
I want to anticipate every aspect of life. ZZ Top are my favourite BAND. cAN YOU sip wine, and have to cancel? I got the six!
Burgers are so obscebe, I got the six!
Cheese, Paul.
Agree 100% Paul. I recall the once infamous Neil Woodford said he would not invest in Banks or Insurers, cos they hide things in their figs - or words to that effect - Yet he was big in Buford.......need I say any more.....
To be fair to Woodford he was invested in Burford from the very beginning so overall he would have done well out of that even after factoring in the big fall in 2019.
My view is Burford will only properly recover once some big case wins come through. They hugely ramped up investment in new cases over past few years, but so far there's only been a few dribbles of wins coming through (been particularly quiet over past 2 years in terms of case development, with covid obviously had an impact). I'm prepared to sit this out as I am fairy confident over their ability to pick good cases and deliver strong returns.
Let's not forget the big win that fell outside the reporting period by one month as it landed in July:
"Our signature realization in the period was the complete
resolution of the Akhmedov matter, yielding a July 2021
cash payment to us of $103 million (in addition to the
more than $5 million we had already collected) and a
realized gain of $73 million, a 233% ROIC and a 71% IRR on
a USD basis"
Burford Capital (LON:BUR) (I hold)
Hi Shamusj
The big win - the Akhmedov case - was included inside the reporting period - a net gain of c$48m/$49m from memory.
The entirety of the $103m cash proceedings were collected in July, so outside the period.
Cheers
A
Last time I checked, Burford Capital (LON:BUR) were neither a bank nor an insurer (unless you take a very broad definition of what constitutes such a business to be) so Mr Woodford was at least consistent if not always infallible. To be be fair, he was also big into Oxford Nanopore which is speculated as coming to the market in an IPO valuation of £5 billion plus so although he financed a lot of dross (cold fusion anyone?) there are a few princes among his many frogs.
Gus.
Mr Woodford was at least consistent if not always infallible
In general there was nothing particularly wrong in Woodford's approach - if you wanted to invest in a VC / PE type investment vehicle. A lot of failures, a few winners, the odd very big winner.
The trouble was it was marketed to no-nothing investors who wanted a safe home for their money and followed the Woodford name. They were bound to head for the hills as soon as the fund ran into trouble. Worse still, most of the money went into closed funds, so redemptions led to forced sales even as share prices were crashing. Schroder Uk Public Private Trust (LON:SUPP) hasn't exactly been a roaring success either but it's still going and still holds Oxford Nanopore.
On Burford Capital (LON:BUR) it's interesting that the share price has never properly recovered after the Muddy Waters dossier despite the work done to address the issues it raised. Presumably a lot of investors reassessed the business model and decided it wasn't for them. Generally companies whose earnings are accrued rather than in actual cash should trade at a discount because the research shows they are much more likely to warn on profits - cash in the bank is cash in the hand, but accrued earnings are cash in someone's else bank account until they're not.
timarr
Indeed, timarr.
I think Mr Woodford gave investors in his Patient Capital Investment Trust more or less what they should have expected (if not hoped for) as you describe. That it still survives under Schroders’ management and may still come good sort of vindicates the need for a long term “patient” approach.
I think where matters got out of hand was when he used funds from his Income OEIC to shore up his illiquid kite flying investments in the private equity fund which is manifestly not what these investors were expecting and which blew up when large illiquid holdings had to be sold at fire sale prices to meet the rapidly escalating level of redemption requests when his bubble burst. At some point this will be raked over in the litigation courts and I suspect this is the legacy most will remember Neil Woodford for.
I agree Buford will continue to be an ugly duckling until some of its home runs are realised. It traded up big time on the back of the Petersen Case and the riches this promised but many got fed up waiting for this and others and moved on.
Gus.
Burford Capital (LON:BUR)
It also probably doesnt help the shareprice cause thay this "profit making machine" actually lost $67 million per these interims - these numbers arent exactly a good advert for anyolne wanting to invest in the business.
No offence taken at all, completely understand! All the best Paul!
Hi Shamusj
I note below Paul's comments on Burford Capital (LON:BUR) but I have just completed my review (I hold).
H1 to 6/21. Key features from financial statement review:
1. BUR only capital provision income $68.5m (H1.20 $251.1m) as a result of lower activity in the period due to Covid leading to lower levels of realised and unrealised gains in the period. The unpredictable and irregular pattern of income is part of what enables BUR to earn outsized long term returns. Appears that all of the consolidated capital provision income in the period was realised [Financial Review]
2. Non-cash accrual of "carry" compensation $84.9m includes historic catch up; without this would have been a very small profit reported for H1 (EPS c$0.03). Unclear how much of the total accrual relates to H1.21, [Appears that the previous non-accrual of this cost is a mistake which has come to light as part of the evaluation of the switch to US Gaap]
3. Fully diluted NAV $7.22 /share
4 ROIC quoted at 95% on concluded capital provision cases since inception. Financial Review gives further analysis: Adjudication Gains $939m recoveries 49% IRR 248% ROIC; Adjudication Losses $17m recoveries -81% ROIC; Settlements $782m recoveries 31% IRR 46% ROIC; giving overall $1,738m recoveries 49% IRR 30% ROIC;
5. Covid has imposed timing delays which will likely benefit BUR in long term
6. New records for capital commitments totalling $503m consolidated & capital deployments totalling $398m consolidated in H1.21
7. Akmedov case settled yielding a July 2021 cash payment to BUR of $103 million (in addition to the more than $5 million already collected) and a realized gain of $73 million, a 233% ROIC and a 71% IRR on a USD basis. This income included in income statement net of costs incurred ($30m) as a realised gain with the reversal of previously recognised unrealised gains ($24m). Not explicitly stated but appears to account for the bulk of the H1.21 capital provision income (49v69).
8. Own capital targets c25-35% IRR with 2-5 year weighted average case length; external fund capital targets c15-20% IRR with 1 year weighted average case length
9. Liquidity - $1bn of unfunded capital commitments are disclosed but stated as being discretionary $0.5bn and $0.4m definitive with $0.1bn being legal risk management (drawn over time). These should be balance by future realisations and $430m of cash management resources at 30/6 together with additional capital sources (debt and potentially equity)
10. Little mention of Petersen other than "our capital provision-direct ROIC since inception would have been 70% and our IRR 25%" excluding the YPF-related assets and that $775m is their 30/6 carrying value
11. Of the 30/6 settlement receivables of $131 million, $103m was Akmedov which was collected in July
12. Interim dividend of 6.25c is expected to be half of the total for the year
As always, I will be interested to hear the views of others
Burford Capital (LON:BUR)
2. Non-cash accrual of "carry" compensation $84.9m includes historic catch up; without this would have been a very small profit reported for H1 (EPS c$0.03). Unclear how much of the total accrual relates to H1.21, [Appears that the previous non-accrual of this cost is a mistake which has come to light as part of the evaluation of the switch to US Gaap]
Does it not bother you that they can suddenly find huge adjustmemts for such large sums - do you realy think its a "genuine mistake" that previous profits have presumably been overstated to this sum total? It either suggests they have an aggressive revenue booking philosophy which is starting to catch up with them or they have poor internal controls. They are meant to be a bunch of smart bods here - getting silly stuff like this "wrong" while at the same time being flagged up as "dodgy" by people like muddy waters must perhaps make one wander if there may be other similar "issues" that have not come to light yet.
Note if we look at the balance sheet and look at the "Capital Provision Asset" which i am presuming is their wip/debtors/ stuff that is valued at $2.4 billion - opk say 20%$ of this turns out to be stuff they never get due to "aggressive acounting" and thats $500 mill - add the catch up w/off and thats probably $600 mill which is probably over half the profits they have booked to date. Lets be frank here they are internally booking what they see fit as profit and that amount is stacking up to a huge sum on thebalance sheet that they "prey" will be turned into cash later. I have no reason to believe everything isnt tickety boo but the history of companies "capitalising" similar stuff whilst saying "it will be all right on the night" when its not is probably quite a long list and therefore some decent "risk discount" must be applied here if one is taking the punt. Strangely i have been tempted acouple of times when it has looked like it was at or below asset value - but if i took a punt here and lost my shirt the only place i would be pointing blame is in the mirror.
Hi rmillaree
I do agree that 'getting silly stuff like this "wrong" ' is disconcerting and rather than brush it off, I personally would have felt happier if they had admitted a mistake or at least a revision to best practice
Having said that, given that there have now been 3 CFOs since the Muddy Waters report and I'm sure that the external audit team has been refocussed as a result, I do feel reasonably confident that the accounting is now up to scratch.
Burford Capital (LON:BUR) is I suspect not managed according to its published financials but on a case by case basis. The aggregate of the concluded cases gives an encouraging picture and until the Petersen case falls into this category there is going to be a high level of subjectivity.
Burford Capital (LON:BUR) is a High risk position within my pretty well diversified portfolio but I continue to hold in the hope that it will also be a big gain.
Steve
The non-cash accruals are most from the carry value of the large YPF asset. Remember, that this is only realised if the cash is realised which is currently estimated to be over 700m (i.e. greater than 10X the expense).
The addition of the non-cash accrual for US GAAP reporting gives the illusion that they have suffered from some new additional expense which is not the case.