Small Cap Value Report (Fri 11 Aug 2023) - ZTF, CML, ZOO, GDWN

Good morning from Paul!
I'll leave it there for today, as there's a webinar at 14:00 from SDI (LON:SDI) that I want to listen to. Thanks for tuning in, and contributing this week, with excellent reader comments! My podcast should be up tomorrow afternoon.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
I'm rather pleased there's no news today, as there are plenty of backlog items I want to look at, so I'll focus on that today.
Also if you've spotted anything particularly interesting, then do leave a comment below, with reasons why it's worth a look, and I could be persuaded to cast an eye over it!
Paul’s Section:
Zotefoams (LON:ZTF)
380p (£185m) - Interim Results (8 Aug) - Paul - GREEN
8 August 2023 - Zotefoams plc ("Zotefoams", the "Company" or the "Group"), a world leader in cellular materials technology, today announces its interim results for the six months ended 30 June 2023.
Strong sales growth and recovery in gross margin drives record H1 profit
Zotefoams makes specialist foam products, which are used where light weight and performance factors are important - eg the biggest product is special soles for trainers (NIKE - exclusivity agreement recently extended to end 2029), aircraft seats (recovery in the sector underway), lots of other things, and a blue-sky development project called ReZorce - for fully recyclable drinks cartons. It has freehold factories in the UK and USA, and a leased (from memory) site in Poland. A recent capex programme saw all the factories modernised, largely completed now.
I need to properly read through the results statement, and watch the recording of its IMC webinar on 8 August. So this section is just my preliminary thoughts, for a share I already like, and have on my top 20 watchlist for 2023 (which is still doing quite well considering market conditions - up 8% YTD - the 13 winners have more than offset 3 profit warnings). I’m hoping to find a spot where I can pick up a few ZTF myself, but the price remains stubbornly high!
Key numbers -
- H1 revenue up 9% to £64.6m
- Profit before tax up 30% to £7.4m, a healthy 11.5% PBT margin, indicating fairly good pricing power - something that has been proven over the last couple of years with higher input prices being passed on successfully to clients.
- Profit is stated after absorbing around £1.5m in development costs for the innovative ReZorce fully recyclable drinks carton project. So underlying profit is about £9m in H1.
- Basic EPS in H1 is 11.5p (up 22%).
Outlook - nicely balanced commentary here, but overall it sounds reassuring that forecasts should be met -
The short-term outlook for the remainder of the year is somewhat tempered by market expectations of squeezed consumer spending and industrial deflation, resulting in inventory reductions in some of our markets.
Other markets, such as aviation, are not expected to be impacted by this trend, with underlying structural growth drivers remaining robust.
We expect energy and polymer input costs to be more beneficial while the US dollar, at a current rate of around $1.28, will provide a headwind to profitability for the remainder of the year, after benefitting operating profit by £1.1m in H1 2022, despite being partially hedged.
Overall, the Board is pleased with the recent performance and current positioning of our business. We remain confident that the Company can deliver a full year performance in line with market expectations, underpinned by a strong first half performance.
We remain optimistic that we can continue our positive momentum in the medium term.
Investors are also watching ReZorce carefully - the recyclable drinks carton project. The upside on that could be really exciting, if it technically succeeds, and drinks manufacturers decide to buy it. Although as readers here have commented before, there must be numerous other companies innovating in this field too. So I’m not seeing ReZorce as a sure thing at this stage, more speculative upside. Also, if the project were to be abandoned, profits would actually rise, because of the costs associated with developing it stopping.
Balance sheet - it’s a capital-intensive business, with £91m in fixed assets (properly, plant & equipment), but this includes freehold properties of £32m (which I see as a huge positive, but some investors focus on ROCE and similar measures, which can be harmed by owning freeholds, although IFRS16 has arguably lessened that - about the only positive thing it has achieved).
Both inventories and receivables look a little high.
Working capital looks very healthy, with a £20m surplus of current assets over current liabilities, especially impressive since all the bank debt of £35m is within current liabilities.
There’s a small £2.7m pension deficit. This is possibly a little light compared with reality, which is £860k pa deficit recovery payments (which I’ve picked up from the cashflow statement).
Overall NAV is £113m, less intangibles of £8m, gives a very robust NTAV of £105m.
Net debt of £28.3m, is little changed. This is fine, as the bank has ample security over the freeholds and receivables (see note 11), and it’s only an EBITDA multiple of 1.1x, considered low.
It seems strange that the bank borrowings are shown in current liabilities (repayable within 12 months), but note 11 says the borrowings are technically repayable within 3-6 month periods, which seems to contradict another section saying it refinanced in 2022 with a £50m+£25m accordion, expiring March 2027. I must ask management to clarify this point. It’s only a technical thing, because debt is not a problem.
Overall, I’m fine with the balance sheet, but would prefer the company to reduce inventories and receivables if they can, to reduce bank debt, which is becoming a lot more costly now that interest rates have risen. Companies didn’t need to worry about that in the previous near-zero interest rate environment, but nowadays, they need to question why they’re funding customers’ late payments, and inventories?
Cashflow statement - it’s a nicely cash generative business, although negative working capital movements temporarily absorbed a fair bit of the cash in H1. That should stop, or reverse, so it’s not a massive concern.
Note that capex has reduced considerably, and was only £1.6m in H1, less than the depreciation charge of £4.1m. So assuming nothing is going wrong behind the scenes, then ZTF should be able to considerably reduce bank debt from internal cashflows.
“Purchases of intangibles” were £1.0m in H1 - is this capitalised development spend? It's not that much anyway.
Dividends only cost £2.2m in H1, and £3.2m for the last full year FY 12/2022, so combined with the large potential cash generation mentioned above, I think ZTF has a much higher future dividend paying capacity than at present. The rather ungenerous current divi yield of c.2% is almost 3-times covered by earnings, and I’d expect to see more generous divis in future.
Valuation - it doesn’t look cheap, but it’s a good quality company, performing well. Pre-covid the rating was much higher, and profits now are higher.
Also the Re-Zorce development project is suppressing current profitability somewhat, but could have exciting upside if it commercially succeeds. So I think there’s a valid case for valuing the shares on adjusted profits that subtract the costs of this project.
Singers (many thanks) has adj EPS of 19.3p this year FY 12/2023, rising to 22.5p in 2024, and 29.4p in 2025. Hence we’re just shy of a PER of 20x for 2023, which does look punchy in a bearish stock market. Hence I think it’s important that ZTF at least meets forecasts, and preferably beats them. A profit warning here would be very bad news for the share price, since it’s not factored in any room for disappointment, unlike many other shares right now where recession is seemingly priced-in already.
Paul’s opinion - the H1 numbers are excellent, showing strong profit growth, albeit helped somewhat by favourable currency movements.
I think it needs to beat forecasts, to justify the punchy rating.
Re-Zorce could be exciting, and a manufacturing partner has been signed up, so news on this front could apparently be in early 2024.
Incidentally, ZTF comes up on the James O Shaugnessy cornerstone growth screen, which has all sorts of good companies on it - I recognise many companies as being ones we’ve reported positively about here in the SCVRs (unsurprising really, as this screen picks up shares which are out-performing the market).
Despite the full valuation, I think ZTF has enough positive characteristics to make me remain GREEN. More as a GARP, than a value share.
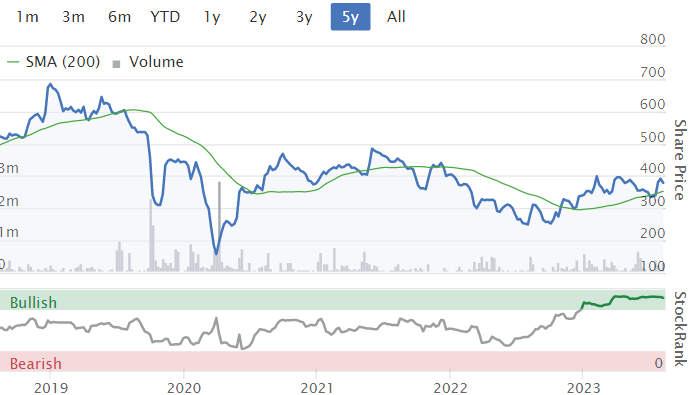
Stockopedia likes ZTF too - note how the StockRank has been rising
CML Microsystems (LON:CML)
433p (£67m) - AGM Statement - Paul - GREEN
CML Microsystems Plc, which develops mixed-signal, RF and microwave semiconductors for global communications markets…
This update for FY 3/2024 strikes me as positive in tone, which combined with a drifting down share price, has caught my attention.
I’ve previously covered CML a lot here, and won’t go through all the detail again, it’s in our archive ("Discussions" tab on every company's StockReport). The key points are that the core business is trading well (strong results for FY 3/2023), and the balance sheet is stuffed full of surplus cash, and surplus freehold property (planning permission finally achieved to develop this land earlier this year, after many years trying!).
Note a 50p special dividend was paid in 2021.
Latest news was yesterday at the AGM, key points being -
FY 3/2024 has “started positively”, on course to increase “operational profit” further.
(note that FY 3/2023 saw normal PBT of £3.16m, plus £2.1m exceptional gain on land)
Acquisition of US-based Microwave Tech for up to $18m (mis of cash & shares) announced in Jan 2023, is still undergoing US regulatory approvals, expected by 30 Sept.
Mgt say they have returned >£24m to shareholders through divis and buybacks. Although I would check how much offsetting dilution there has been through share options.
Paul’s opinion - I see that a lot of the surplus cash is ear-marked for the US acquisition, which seems to be a small, and slightly loss-making US company. Therefore we have to trust that CML’s management knows what it’s doing here, as there’s nothing obviously attractive about this acquisition from the limited financial info provided (FY 12/2022 revenues $6.5m, Loss of $132k), paying up to $18m to acquire it. CML does say that it "will be earnings enhancing in its first full year of ownership within CML", which reassures. They've got to compare it with foregone interest income on the cash though.
Shore Capital (many thanks) thinks CML should grow EPS by 24% to 27.3p this year FY 3/2024. If achieved, that would make the PER 15.9x. Plus support (although less once the acquisition completes) from the cash pile, and surplus property.
I’d say this share is starting to look tempting after recent falls, so I’ll remain GREEN. Roland did the last review of it, and marked it amber - citing the lowish ROCE, but this goes back to my earlier point above with ZTF, that companies with surplus assets may look inefficient, but have hidden value in them, which matters more to me.
Risk:reward has changed somewhat, in that surplus cash being used for an acquisition, reduces the comfort blanket of excess cash.
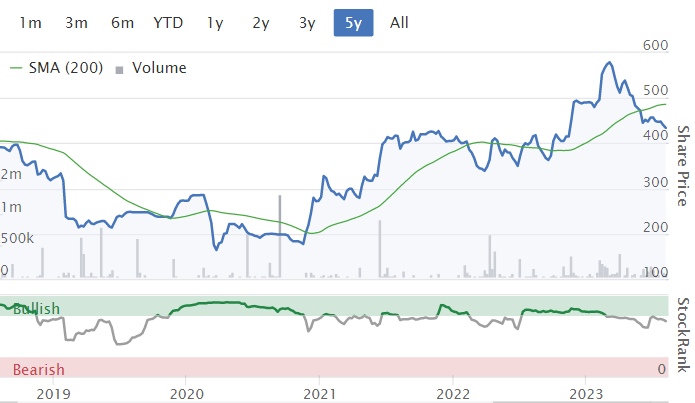
After giving up the recent spike up, and with another reassuring trading update in the bag, I think this looks a tempting entry point, possibly (and only if you understand what the company does, and its competitive position, etc) -
Sorry, this was meant to be a short section, but ended up being large!
Zoo Digital (LON:ZOO)
64p (£63m) - Audited FY 3/2023 Results - Paul - AMBER
Everything seemed to be going well for this TV/film “localisation” services group (e.g. dubbing, subtitles, etc) - with revenues roughly tripling in recent years, driven it seems by the free spending of the TV streaming services in the US. After years of lacklustre financial performance, ZOO broke through into meaningful profits in 2021 & 2022.
However, in the last few months, the wheels seem to have come off very suddenly, as you can see from this 5-year chart, and horrible relative strength numbers -
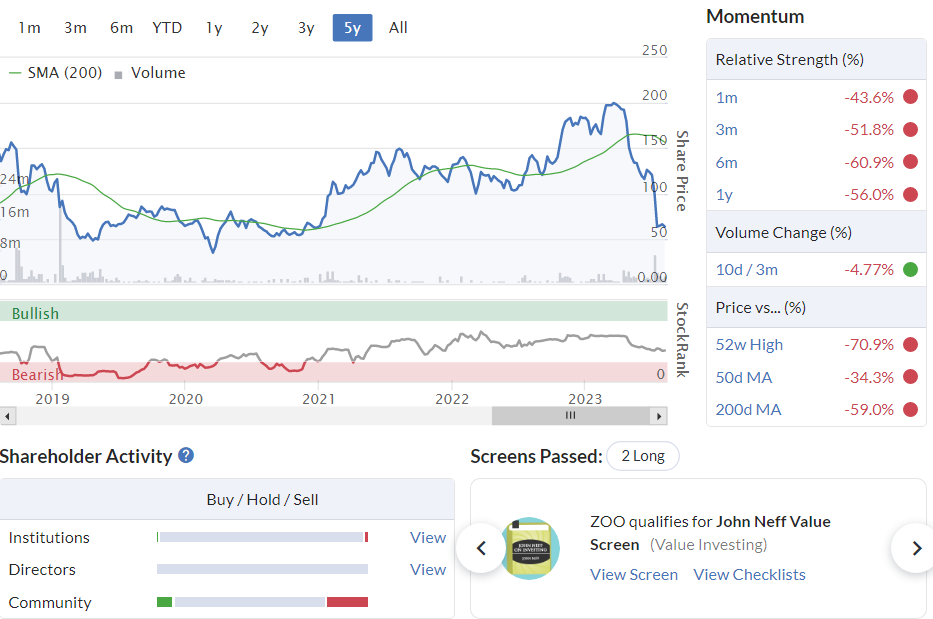
Is it now a value share, as the “John Neff Value” screen suggests?
What has gone wrong? Consulting my quick notes spreadsheet here, I looked at ZOO -
28 April 2023 - down 9% to 166p in a placing (13% discount, but a great price for the company, but not investors, with hindsight). This came with a mild profit warning, that strangely the market seemed to initially ignore. I noted that I was cooling on ZOO, due to dilution & the profit warning, so went down to amber. That was too optimistic though…
14 July 2023 - bombshell, large profit warning, slipped out via brokers, despite a positive-sounding, highly misleading RNS. I reduced my view again, to AMBER/RED, although did note the healthy cash pile - isn’t it lucky when placings happen shortly before profit-warnings?!
Anyway, on to the latest announcement, FY 3/2023 audited results - there was an 8% bounce yesterday on publication of these numbers.
The headline figures look really good -
- Revenue up 28% to £90.3m
- Operating profit up 330% to $8.1m
- Profit before tax $7.9m (boosted by a $2.0m prior year adj)
- Negative tax charge helps boost EPS to 8.3 US cents (diluted - note share options are generous).
Balance sheet is OK, but not great. NAV of $35m becomes about $25m once intangible assets are written off. Cash of $11.8m seems to be offset by “borrowings” but note 7 shows that these $7.0m+$1.4m borrowings are actually lease liabilities. That should be explained on the face of the balance sheet, as most companies do, so a presentational own-goal there. Shareholders might want to point this out to ZOO management.
Overall then it looks OK to me.
Going into the detail more, I see that the 160p placing which raised $15.5m happened after the year end. So the cash pile should now be c.$28m (but was actually $23m at June 2023), assuming no operational cash burn since March 2023. The money was earmarked for a Japanese acquisition, but it sounds to me as if that might fall through, as it hasn’t yet completed. Given industry challenges, let’s hope ZOO hasn’t signed anything, and can pull out without penalty.
With strong numbers for FY 3/2023, and plenty of cash in the bank, why is the share price currently bombed out? I’d say it’s mainly these issues -
Industry factors, eg the Hollywood strikes, causing productions to halt/delay
Streaming giants cutting back spending - was the big FY 3/2023 profit for ZOO a one-off perhaps?
Massive profit warning on 14 July that saw forecasts slashed from 9.6c to only 2.9c for FY 3/2024.
Outlook - ZOO says the current disruption is temporary. I can see why that would make sense for the Hollywood strike, but the streaming services cutting back sounds more permanent to me -
Current trading has been impacted by several major streaming companies carrying out strategic reviews to refocus on profitability and the first simultaneous strike of US writers and actors in 60 years. This has created short-term market disruption and temporarily lower volumes of localisation and media services work.
Cost-cutting is being implemented.
Expects market share gains from customers rationalising their supplier bases - sees upside from this in H2 2024 (Oct 2023- Mar 2024).
Current guidance unchanged -
The Board remains confident in ZOO's medium and long-term fundamentals and expects to deliver revenue growth over FY23 in the following years. Our guidance for FY24 remains unchanged and our 2030 strategy remains on track.
Paul’s opinion - with the market cap now being only £63m, and a net cash pile of $23m (£18m), that’s 29% of the market cap supported by net cash. Let’s just hope it doesn’t spend the cash on the mooted Japanese acquisition. The delay suggests to me they might be trying to renegotiate on price perhaps?
A lot of that cash came from investors who supported the placing earlier this year, at 160p. We can now buy in the open market for about 65p. The value investor side of me is drawn to that, although the fundamentals have drastically deteriorated this year.
Taking everything into account, I’m happy to go from AMBER/RED, to plain AMBER. That view is based on me being neutral about how temporary, or structural the problems are. Industry experts should have a better idea on this. Once the Hollywood strike is over, I can imagine sentiment improving towards ZOO.
Downside risk looks fine, given plenty of cash, but I would see the Japanese acquisition going ahead as a negative risk factor.
Lease liabilities are quite high, and capex fairly hefty too, suggesting that ZOO isn’t as capital-light as I would have expected.
Being low gross margin, and using thousands of freelancers (so flexible cost base), I would have expected ZOO to be able to absorb a downturn in business much better than it has. So that’s a question mark, as to why the recent profit warning was so severe, when it shouldn’t have been? Maybe a lot of the profit might be coming from a handful of key customers?
I don’t believe the story that ZOO has big competitive advantages, because there must be numerous other companies offering dubbing, which is reflected in ZOO’s low gross margin.
Finally AI! Who knows whether this is a threat or an opportunity? Given how good the text to speech software is becoming, then I don’t know whether AI could help, or hinder ZOO. The section in its results emphasises the limitations of AI, but does see some applicability for it, e.g. in dubbing documentaries, or other older content, where a slightly crude literal translation might suffice. In summary, it says similar things to what everyone is more-or-less obliged to say! -
In summary, AI is an exciting field of computing that is being developed at pace and holds much potential, including in the field of ZOO's business. Its successful application in media and entertainment, particularly for premium content, will inevitably be alongside traditional practices and the use of creative talent, and where ZOO's heritage as an innovator and trusted partner to the leading names in the industry places it well to become a leader in the field. Consequently, the Board regards AI as an opportunity for ZOO's business rather than a threat.
Overall, I can see that ZOO shares might be coming into speculative buying range, providing it keeps hold of the cash pile. Although having disappointed so badly this year, there must be plenty of shareholders smarting at their losses, and maybe not so keen on management. That could mean a protracted overhang, if institutions are dribbling out stock into the market. That's an issue with lots of small caps right now.
Goodwin (LON:GDWN)
4745p (£356m) - FY 4/2023 Prelims (from 8 Aug)- Paul - AMBER/GREEN
It’s been a while since we’ve looked at this family-controlled engineering group.
Roland wrote a superb summary of the interim results here on 20 Dec 2022.
Shares are up 42% YTD, and it’s one of the top performers in my 2023 watchlist.
Key numbers for FY 4/2023 -
Revenues £186m, up an impressive +29%
Gross margin is down from 29.6% LY, to 24.9% - that’s a big drop, we need to investigate this.
Adj PBT rose 10% to £18.9m
Reported PBT is higher (unusual!) thanks to a £3.2m gain on the inspired decision to fix some borrowing costs at 1% for ten years!
Diluted EPS is up 22% to 206.8p - this includes the non-trading benefit of the profit on interest rate swap. Note there don’t seem to be any share options, as basic and diluted EPS are exactly the same!
The PER is a punchy 22.9x - high for an engineering group. Although talking to investors, people seem more interested in the large & growing order book.
Shareholding structure - it’s completely controlled by Goodwins! So you need to be comfortable about being along for the ride, with no say in anything -
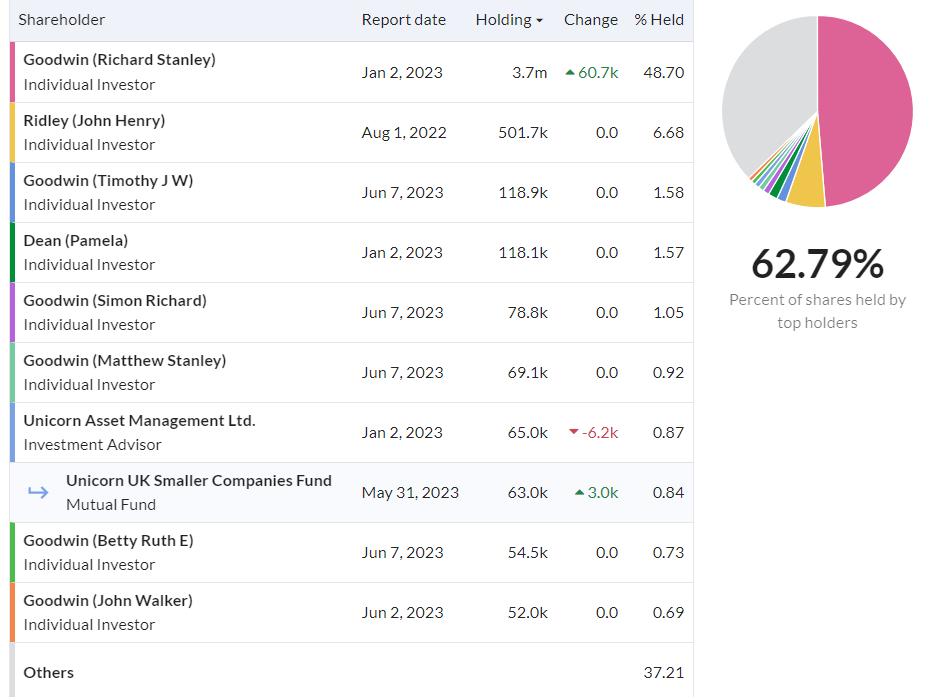
Where are the institutional shareholders? There don’t seem to be any!
Could that be upside potential, if the market cap continues growing, forcing some institutions to start buying into an illiquid market?
Broker forecasts - don’t seem to be any. Although it’s encouraging to see Shore Capital (house broker) has been issuing short summary updates (but without forecasts) for about a year. The most recent one says “NB. We intend to publish a detailed report on the company in due course”.
Forward order book - has grown to £271m. I am assuming it’s grown, as I can’t find actual numbers in the last interims, or prior year results, but plenty of bullish commentary about big order intake.
It’s frustrating at the vagueness and lack of figures from the company. Hopefully when “due course” is up, the anticipated note from Shore will shine a light on things rather than it being shrouded in mystery, and only occasional updates to outside shareholders.
If they do suddenly start getting more transparent, it’s probably because one of the family members wants to cash out! (being cynical).
Nuclear decommissioning and naval markets are said to be the main driver of order intake being 68% up on last year. This bit sounds rather good too -
The programmes of work, that are actively ramping up now, are being exploited to win more and more of the same, supporting projects that will still be ongoing in a decade's time… after a long drought, they should now meaningfully contribute to the Group's performance going forward.
Balance sheet - looks fine to me. NAV of £129m becomes £104m once we write off intangible assets. It’s using a fair bit of debt (gross: £54m), but that’s partly offset by gross cash of £19.7m, so £33m net debt. It’s not clear if that’s just bank debt, or might include leases as well?
Cashflow statement - nicely cash generative business, which it’s mainly spending on capex. Plus about £8m p.a. cost of divis.
Paul’s opinion - GDWN looks good, but I don’t really have enough information to value the shares.
It seems clear from the commentary with the last 3 sets of results, that development of new products is beginning to pay off with large orders. Management talked about regaining peak levels of performance which it had previously achieved in the oil boom c.2014, targeting new sectors now. Peak profits in those days were £20-24m, so it’s not far off that already, at £19m adj PBT for FY 4/2023.
So personally I wouldn’t want to chase the share price any higher, without having much more detailed, and reliable knowledge about what level of profits we should expect to see in the coming few years. If any readers have more detail on that future outlook, do please share it, and what your share price targets are? I believe we have some very knowledgeable members here on GDWN.
As the shares have risen a lot recently, I’ll moderate my view slightly, to AMBER/GREEN.
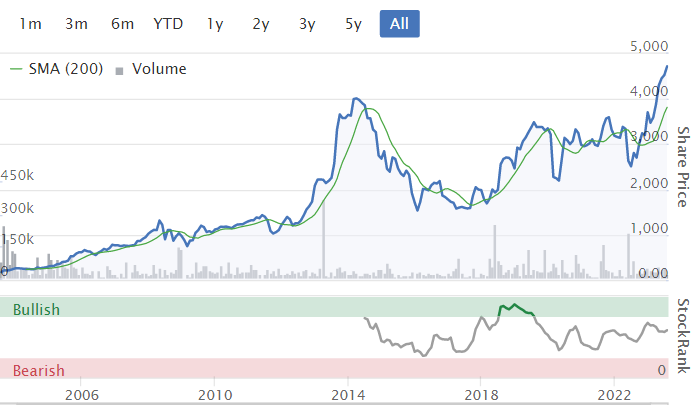
Very impressive long-term -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
This weekend's podcast is now live - available on all the main podcast channels, just search for "Paul Scott small caps" and you should find it. Or the web version is here on acast (the site I use for publishing). NO ADVERTS! I can't stand ads in podcasts, so refuse to inflict them on you :-)
This week's mystery share (my best idea, held back for Stocko subscribers only) is: Sanderson Design (LON:SDG) (I hold) - see Tuesday's SCVR here.
Hope you're having a relaxing weekend :-)
Hi Paul..I replied to a comment from Abtan on yesterday’s report so for brevity/& the record I’ve cut and pasted it here;
Goodwin (LON:GDWN) doesn’t screen well *yet*…arguably when it does it’ll be far more expensive & is complicated to model because they’re doing multiple new investments simultaneously to move the business into a significantly bigger & better business…they don’t window dress this in the numbers but do try to explain v clearly in the text what is going on…so the text is vital to the investment case.
as an illustration here is the operating companies P& L over the last few years extracted from the subsidiaries filings at Companies House…key to understanding what is occurring is the significant physical expansion in the foundry (complete next month) that gives it capacity to handle multiple times the current revenue primarily for US & U.K. naval & nuclear contracts at attractive margins. This ramp up is fully underway in the current year & will allow for revenue in the foundry to move dramatically upwards…& the bulk of that output will be machined by sister company Goodwin International.
the order book is primarily for delivery over the next 2 years but the underlying programmes it increasingly represents rolls over decades eg AUKUS…so it’s the tip of the iceberg of the business they see in front of them.
looking at *last* years results in numeric terms alone will miss this, equally margin evolution is yet to be apparent as start up of new casting types is time/cost intensive …& that is ignoring the rest (c50% of profit) of the business…I’d note they’ve set up 2 new Ltd companies, one for AVD Lithex which is ramping up fast now (see the comments in the RNS)..& one for Soluform another new product .
finally EASAT their radar business is tendering for some v large contracts in India & elsewhere …they are confident this will transform the financial performance there as they are now doing full turnkey systems rather than the antennas they’ve historically provided.
it’s my largest position & a company I know well…it’s a special business imho… an unusual vertically integrated globally active family controlled….it reminds me of JCB
re f’casts I only know that they’re on course to be a far bigger higher margin business in the years to come…the direction of travel is utterly clear to see when you look at the details ..not least the development of Duvelco that represents an entirely new patent protected polyimide product that will launch by June 24..the production line is currently being commissioned..with capacity for £40m of high margin sales ..this will likely become their largest profit centre in years to come.
Re price mgt have just spent £8.6m buying shares back at £48…& they know what is going on under the bonnet better than anyone..
Goodwin (LON:GDWN) the problem I have with it, is the spread, it is wide, just now it was around 7%, but then 20 seconds later, it was only about 2%. Prices are going up down like anything. Crazy market, at least I could get a live quote.
A bit off-topic, but I'm finding a few opportunities with investment trusts at the moment. Given large discounts to NAV that have appeared in this bear market, quite a few sub-scale trusts (below £100m) are returning cash at NAV, winding-up , changing manager or rolling-over into a new trust. Atlantis Japan Growth Fund (LON:AJG) today (only bought 2 weeks ago on anticipation of wind-up), Investment (THE) (LON:INV) offered a cash exit or move to Chelverton, but took the cash, abrdn Japan Investment Trust (LON:AJIT) going to Nippon Active Value Fund (LON:NAVF) like AJG - Japan small cap value looks a very good place to be, Shires Income (LON:SHRS) merging with Abrdn Smaller Companies Income Trust (LON:ASCI), Asia Dragon Trust (LON:DGN) merging with Abrdn New Dawn Investment Trust (LON:ABD), Aberforth Split Level Income Trust (LON:ASIT) less than a year before wind-up, abrdn Diversified Income and Growth (LON:ADIG) in play and doubled-up today as on a thumping discount with a decision likely to be made in the next few months. As can be seen above its been abrdn trust consolidation, small cap and Japan small cap in the spot light so far. Renewables may be next.
Anyway, anyone else with large investment trust holdings and noticing the step change in numbers of transactions?
Small cap trusts have been particularly impacted so far.
Yes a lot of consolidation in the IT space right now. GCP Infrastructure Investments (LON:GCP) and GCP Asset Backed Income Fund (LON:GABI) also announced a merger today. Probably a good thing as too many similar, sub scale trusts out there (similar situation with UK REITs).
One of the drivers behind this is apparently the consolidation in the wealth management space - they are the main buyers of ITs, but for liquidity reasons they're no longer interested in anything below £500m and ideally £1bn.
Anyone have views on Tracsis (LON:TRCS) ?
Price has come off 20% since the end of May - half of that in the last 2 weeks.
Last SCVR was Green on 3 April. Considering taking an opening position.
For me, it would have been a good QM share had the price moved the other way! As it stands, this share is at risk of being re-categorised as a High Flyer to a Falling Star stock. IMO given the market weakness we are still experiencing, I wouldn't be tempted to catch a falling knife.
I agree with Paul's assessment though, it's a high quality company but these stocks tend to do better when we are in a bull market.
I noticed that FDM (Holdings) is up around 14% today at the time of writing. Does anyone know why? Judging from the financials (including ROCE and lack of debt), this company might be attractive to private equity so, unless there is another explanation, I reckon the share price jump could signal the interest of a bidder. I hold the shares.
Judging from the financials (including ROCE and lack of debt), this company might be attractive to private equity
I wondered too about a bid rumour. But the name is cheap for a very successful business model, which is highly likely to rebound operationally in the not too distant future, so perhaps traders had just recognised it as well oversold and fundamentally well supported.
I was wondering about FDM (Holdings) (LON:FDM) too. Has it been tipped in any of today's press by any chance?
It's been on my watchlist forever. Slightly wary of the group because (as Paul mentioned) the management took it private some while back then refloated for a huge profit. Also had unwelcome publicity in The Sunday Times which alleged it provided questionable quality contractor training and then tied its staff to repay said training.
That said, ROCE and dividend yield, cashflow and no debt.
FDM (Holdings) (LON:FDM)
https://duckduckgo.com/?q=fdm+group+lawsuit&atb=v314-1&ia=web
It is worth reading through some of this before becoming a shareholder.
It is worth reading through some of this before becoming a shareholder.
That story is as old as the hills and as broadly applicable as the number of trainer/recruiters. EDS were criticised for the same practices back in the early 1980s. Having run IT consultancies, I know it is a serious problem retaining trainees long enough to get a payback. You don't make money on that investment for a good while. And bear in mind that FDM takes ex- military and raw trainees and turns them into consultants who can earn £400 a day for themselves as an independent contractor within a couple of years. That's a serious leg-up to their circumstances and, it might be argued, ought to come with some recognition due to the organisation that made it happen, ideally in the form of a modicum of loyalty.
Of course, no one wants to be stuck in a job they dislike, but I just thought it worth looking at the other side of the argument.
Hi Paul, ZOO: Yes you're correct, management intend to use these chastened circumstances to both renegotiate the price of the Japanese firm - and only complete the transaction once orders resume. So, as you say a very fortunate timing for the fundraise - albeit they did declare the pause by a major client in the document. They also have a scalable business model so with the substantial cash onboard they should be able to weather the storm . Very much one for the brave at the moment - as who knows how long this strike and streaming market re-set will continue?
Thanks Maddox. Based on what you say, I think the cash support for ZOO if it ditches the Japan acquisition (likely, given the time elapsed), risk:reward could be quite nice. Wouldn't surprise me to get a say 30-50% bounce on news of Hollywood strikes ending. Not sure I'd want to hold ZOO longer term though. But could it be too cheap now? Possibly, your decision. More a trade for a bounce, than a long-term conviction buy, IMO.
Paul would it be unreasonable to value Zotefoams (LON:ZTF) without the MuCell costs for ReZorce? My thinking is that this innovation will fly or die over the next 18 months. I suspect they will continue to fund it at up to current levels, about £1.5/6 months?, for a little longer but the trial early in 2024 and other expressions of interest will firm up prospects fairly quickly. If negative the underlying profit situation reminds me somewhat of Ergomed pre pandemic and their move to being a pureplay CRO/pharmacovigilance service. Once they dropped the lossmaking pharma research ventures the business was revalued. Management could cut ReZorce loose fairly quickly if it doesn't confirm its promise or sell the IP to someone who can exploit it better. So not an ongoing drag with factories to close and lots of redundancies?
Half year PBT at Zotefoams (LON:ZTF) was up 50% and they seem quietly confident with the extension of the Nike deal, the inclusion of their materials in the new basketball footwear range next year and the aviation sector picking up as Boeing steadily increase their build rates.
You noted the reduction in capex for capacity too. Sounds like a lot of good things in the background as well as some decent numbers already. Is the current PE really too optimistic?
I agree with your first point, which is pretty much what I said in the main article - as you say -
"Paul would it be unreasonable to value Zotefoams (LON:ZTF) without the MuCell costs for ReZorce? My thinking is that this innovation will fly or die over the next 18 months."
Yes, I agree with your point above.
As regards capex, you said;
You noted the reduction in capex for capacity too. Sounds like a lot of good things in the background as well as some decent numbers already.
I'm not entirely sure what you mean there, but I've just listened to the IMC webinar from ZTF, and the CFO seemed to be saying that H1 capex was unusually low, and would be higher in H2. But I have been mystery shopping Boom Battle Bar (I hold in XPF) in Bou'mth earlier today, so there's a chance I might have misunderstood the capex point re ZTF. Also the tickers are worryingly similar.
Probably best I sign off now, before I cause another international incident.
Best, Paul.
Hi Paul and Fellow Subscribers,
Please can you share your expertise opinion on the impact of entire Share Premium cancellations ? Mears (LON:MER) (I hold) has issued an RNS today proposing to cancel the entire amount in share premium account (£82.5M) , if permission granted, the amount will be distributed to Share holders via buybacks or dividends.
Thanks
Nesh
AD_- I was wondering the same.. Consulted my trusty know it all accountant (ChatGPT :/)
Here is his summary. May help you out too (but I'm sure somebody here can help us with a more digestable explaination!)
Share Premium: Share premium refers to the amount that a company receives from investors in excess of the par value or nominal value of its shares. Par value is the minimum price at which a company can issue its shares. The share premium represents the additional value that investors are willing to pay over the par value, often reflecting the perceived value or potential of the company. Share premium can arise from various situations, including the issuance of new shares at a price higher than the par value or the revaluation of assets.
Share Premium Cancellation: Share premium cancellation, also known as share premium reduction, involves reducing or eliminating the share premium account on a company's balance sheet. This is typically done to create distributable reserves that can be used for various corporate purposes, such as paying dividends or writing off accumulated losses.
... then goes through the steps concluding in distributable reserves.
Hi AD_
Please can you share your expertise opinion on the impact of entire Share Premium cancellations ?
The short version is that it's just an accounting/legal technicality really, that enables companies to pay divis & buybacks from legally distributable reserves.
Regards, Paul.
Got to say, my version re cancellation of the share premium account was much better, and more concise than AI, even if I say so myself.
So I agree with ZOO - AI might have some advantages, but at this stage anyway, it's well short of what humans can do in specialised areas.
Also, I don't like how cocky, but also evasive AI sounds, in that chatty model thing.
Incidentally, I've also mystery shopped my local Cosy Club run by Loungers (LON:LGRS) this evening - I recommend it if you want to avoid the chavs in Bournemouth (everywhere else, basically). It would be a good venue for a shares evening actually, maybe we should consider it for south coasters?
Regards, Paul.
Hargreaves Services (LON:HSP) anyone in or thinking of getting in could do worse than spend an hour of their time watching this for FY23.
Investor Meeting Preliminary Results Investor Presentation - Investor Meet Company
I had bought into Hargreaves Services (LON:HSP) in October 2022 and sold out last month ahead of the full year figures. I had no specific concerns with the business but felt the shares were no longer super cheap and wanted to rationalise my portfolio and get rid of lower conviction ideas. I guess I had a slight concern too about whether Hargreaves would be able to extract the value from the German subsidiary, given it does not have voting control.
On reading the FY23 report, I did not regret my decision to sell but listening to ImC presentation I have started to doubt. The presentation really focused on reducing the capital the tied up both in Germany and in the land division. With the shares still trading at a considerable discount to book value, there is definitely value to extract. While we might not see serious change in the next 6 months, I definitely got the impression that the group could look very different in the next 2-3 years. CEO Banham definitely implied that the German management would not be an obstacle to passing cash back to Hargreaves.
I was surprised how much thinking seemed to have moved on in the last few months, particularly as the Chair (who I had always assumed was a catalyst for change) has been sidelined the last couple of months due to a health issue.
Yes Helvellyn I agree that watching the Hargreaves presentation is worthwhile, it is not the type of company I normally invest in. Hargreaves does have quite a few moving parts and exposure to certain commodity prices and demand for development land, but this presentation makes it is clear that the company has implemented risk management wherever possible and I detect a degree of "entrepreneurial conservatism". You can't always believe what you are told, but my personal impression is that this and earlier presentations genuinely try to make the company's diverse operations as transparent as possible. I hold the shares.
Paul, do you still intend to finish Zotefoams?
Haha, we crossed in the post! Yes, I finished off my section on Zotefoams (LON:ZTF) , sorry for the delay. Very interesting company I think, but fully valued, is the short version.
thanks very much
Morning Paul,
Many thanks for taking a look at Zoo Digital (LON:ZOO) today, which after yesterday's results I decided to take a starter position at what seems like reasonable, if not good value. What with the writer's and actor's stikes, it seems like we're at peak pessimism?
Could the pessimism not be due to AI?
I too hope Paul gets round to Zoo Digital (LON:ZOO) . I've read through their very lengthy market appraisal, and while prospects for H1 2024 look iffy, I accept the optimistic case . The complication of launching content internationally in multiple languages, dubbed and subtitled in the local vernacular must be enormous, Zoo Digital (LON:ZOO) concentrates on the premium end of this market where geographical spread, and attention to local detail are of major importance. They argue that AI translation cannot yet be relied apon to provide good script, though they expect it to have growing impact at the lower end of the market. For the longer term, they see it as an opportunity rather than a threat.
Zoo Digital (LON:ZOO) strengths seem to be in their ability to manage the detail in a wide range of different geographys and languages - I guess this is quite difficult to replicate.
Paul's input on the financial side would complete the picture for me.
EMIS (LON:EMIS) takeover provisionally given the green light
EMIS (LON:EMIS) takeover provisionally given the green light
Happy Days! One of the easiest risk/reward situations I’ve seen this year when it dropped back to £13 and change. Will be interesting to see how close it gets to the £19.25 buyout price today.
EMIS (LON:EMIS) Does anybody have ideas about what happens to the interim dividend for 2023? The takeover document provided for an interim dividend if due process was followed and paid before completion date. This of course related to the interim for 2022. But now the 2023 dividend half year has completed and the interim dividend earned; there is surely time for Directors to review the half year Accounts and declare a dividend should they see fit to do so before the October completion date. Does anybody have insights into what could/should occur?