Small Cap Value Report (Fri 11 Feb 20220 - ADF

Good morning, it's Paul & Jack here with Friday's SCVR.
Agenda -
Paul's Section:
Facilities By Adf (LON:ADF) (I hold) - a positive trading update from this recent float, which finished 2021 about 17% ahead of market expectations. Looks like the float was under-priced, not something I find myself saying often!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Facilities By Adf (LON:ADF) (I hold)
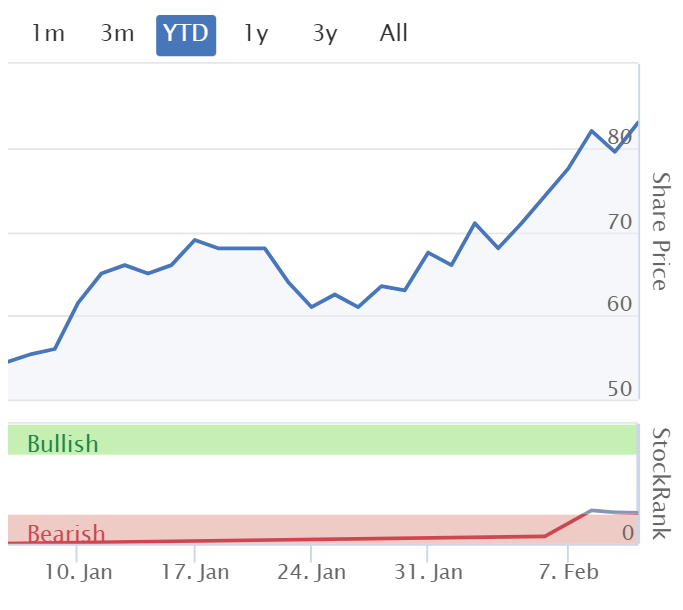
83p (pre market open) - mkt cap £62m
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry, today announces a trading update for the year ended 31 December 2021 ("FY21").
An excellent first trading update from this recent float on AIM (5 Jan 2022). Purely by luck (it was a quiet news day), I reviewed its Admission Document and came away impressed, here on 5 Jan 2022. So I hope some readers hopped on board at the time.
It’s become increasingly obvious that a lot of new floats over the last couple of years have been opportunistic (beneficiaries from lockdown) and over-priced, with the main purpose really being for an existing major shareholder to find a lucrative exit route.
However, ADF stands out because;
(a) the valuation was reasonable, cheap even.
(b) most of the money raised in the float was for expansion, rather than an exit for existing shareholder.
(c) growth tailwinds look long-term, not just a pandemic-related flash in the pan.
Today’s update for FY 12/2021 is positive (ahead of expectations) -
Main points -
- Strong close to 2021
- (Unaudited) revenues £27.8m, adj EBITDA at least £7.5m - ahead of expectations (no explanation provided as to what expectations are, so see Cenkos note)
- Strong market dynamics
- £15m raised (before fees) in AIM float
- Deploying cash, with orders placed for new vehicles
- Reviewing acquisition opportunities (this is the planned expansion route into Europe, currently ADF is UK-focused - so deal risk is a potential downside)
- Strong visibility for both 2022 & 2023 (good, as it makes a profit warning less likely)
My opinion - I should disclose that I’ve part-sold at 83p earlier this week, because a 50% gain in a month seemed attractive. Also I noticed that the shares were being widely tipped in the press, a sign of an active PR, which can pull in short-term punters, who often over-pay, and have an attention span of about 2 weeks.
That said, with a positive trading update out today, I may end up kicking myself for having part-sold. Perhaps it would have been better to run the position? Anyway, that’s not important.
Cenkos put out a detailed note 45 page note (available on Research Tree) with interesting background information about the company. It’s a specialist hire business effectively. Quite interesting to see the equipment used in the TV/film industry, so this is quite a nice share to own, as it’s fun doing the research.
Cenkos had £6.4m adj EBITDA penciled in for FY 12/2021, so >£7.5m announced today is a good beat, about 17% ahead of expectations.
Looking forward, adj EPS for 2021 & 2022 looks to be something like 5-7p, so if we take the 6p middle point, I think a PER of 15-20 can be justified, so 90-120p looks reasonable as a share price target. Hire companies don’t tend to reach high PERs, but ADF is clearly in a growth phase, with strong sector tailwind - it’s great to hear that TV/film production is doing well in the UK, with the CEO of ADF sounding excited -
"I'm very pleased with the start we have made as a public company. We have an excellent customer base and a market backdrop which is seeing vast amounts of investment in the UK film and HETV industry. As we deploy the funds raised at IPO, we will continue to execute our ambitious, yet highly achievable growth strategy."
I wish companies wouldn’t use industry jargon & abbreviations without an asterisk, telling us what they mean. I’ve got to google “HETV” now. It just means “high end TV” apparently.
Overall then, ADF looks a decent share, and still priced reasonably, despite being over 60% ahead of the IPO price, just 37 days after floating. That premium looks justified, and I suspect this share could rise more today. 100p looks a possibility, as a reasonable target in the coming weeks or months. I’m inclined to sit tight on my remaining position.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Thank you Francis (fwyburd) for your post at 5.01pm which I found very helpful.
Your comments on Boohoo (LON:BOO) are spot on and I will certainly remain on the side line for now.
I forget the famous investor who said "trading without a stop loss is like driving with no brakes" was it Mark Minervini? Boohoo (LON:BOO) is a good example of why many investors wiser than me always use a Stop Loss.
Glad that helped. You will see BOO shorts were reduced on Thursday but are still 4% (or more assuming some positions still exist below 0.5%). So short interest is still relatively high although of course any positive news could create a short squeeze.
I think Dahokolomoki's point below is well made - if you believe in Boohoo (LON:BOO) 's long-term, then adding makes sense. I did this with Saga (LON:SAGA), averaging down at 2.60 and 2.80 which made sense to me at the time but then I think their growth prospects are superior to £BOO. Time will tell...
Cheers
Francis
Has anyone any insight into the near 12% jump in Clipper Logistics (LON:CLG) today? MCap is £740M so still of an appropriate size for this board. No RNS. Thanks in advance.
Hi tindrum :
Noticed this today as well - can't complain, having held for 4 years. Can't find any news/anything relevant. Note that today's published trades (using ADVFN) are three times the normal from earlier in the week, but all normal sized trades - tipped somewhere (IC anyone ?).
So will continue watching with interest.
All the best
Geoff
I see Cake Box Holdings (LON:CBOX) price has taken another hammering this afternoon. Lots of work to rebuild trust there I'm afraid.
Unfortunately if you can't trust the numbers, then can you really ascribe a valuation? I'm guessing many investors are bargepoling CBOX and if there are a lack of buyers then the SP will only keep drifting down.
Paul I was very intrigued by your reply to Mark Penney at 11.43 today concerning £JOUL.
All week I have been wrestling with a decision of adding to my long term holding in Boohoo (LON:BOO) were I am 70% down having bought in between Jan & June last year.
I think £Boo is well oversold at 92p and at the right level I could reduce my cost of holding by 50%
However many wise investors say averaging down is for mugs.In my case I have made serious money on some shares eg Ferrexpo (LON:FXPO) by averaging down when I think a share is oversold.
When a share like Boohoo (LON:BOO) which increased its Revenue from £295m in 2017 to £1,745m in 2021 falls nearly 75% it is because the story has changed but like you I see into the future 3 to 5 years when I anticipate Boohoo (LON:BOO) could be a huge Company.
As they say in life it is all about decisions but you really set me thinking again by your post today.
You pose a very interesting question: when is it a good idea to average down? I have lost money doing this recently with Boohoo (LON:BOO) Best Of The Best (LON:BOTB) and Loopup (LON:LOOP) mostly by failing to watch some key indicators, namely the 20/150/200MA, director sells/buys and the progress of shorters (I use this site https://shorttracker.co.uk/wat...).
With regard Boohoo (LON:BOO), I have saved myself losing much more money by exiting completely around £1.45. Apart from a quick trade 1.08 - 1.25 I have avoided re-entering for the long term because I watched shorters increasing their positions continuously despite how low the SP was at the time. You will note short positions increased 2 days ago which suggests someone (maybe?) smarter than me thinks the SP has further to fall. The failure of the BOD to make any significant purchases at these levels is also significant IMO.
For me I might re-enter but only when the SP climbs above the 200MA and short positions are smaller than they are now.
Hope that helps
Cheers
Francis
"I see into the future 3 to 5 years when I anticipate Boohoo (LON:BOO) could be a huge Company."
If you have that strong conviction on Boohoo then you should definitely be buying more shares. You're not investing just to "follow the herd" or "only invest if you get validation of your decisions". We're all here to do our own research, and invest in companies we personally have conviction in.
For anyone interested, "Q&A with Paul Scott" recorded today, it seems, is now available.
https://www.voxmarkets.co.uk/
Should be good listening for a Friday evening with a glass of wine.
are we able to see this without registering?
Q4 NAV report released by Ediston Property Investment (LON:EPIC) today shows a 2.5% increase to 90.6p, although the share price has fallen back by 4% to 82p due to some investor disappointment in regards to a smaller-than-expected valuation increase in their retail warehouses, the impact of the office sales below BV and the late release of the NAV (for reasons unknown).
On the positive side the vacancy rate has fallen by 0.4% to 8.2%, 99.9% of rent is current and the company have over £50m cash to invest, where they are now solely focusing on the retail warehouse market. I think there's a concern that the retail warehouse market may be starting to get frothy with lots of real estate investors pivoting into this space due to solid rents but I continue to hold, with the discount to BV widening to nearly 10% today, which I think is not justified. I continue to hold.
Q4 NAV report released by Ediston Property Investment (LON:EPIC) today shows a 2.5% increase to 90.6p, although the share price has fallen back by 4% to 82p due to some investor disappointment in regards to a smaller-than-expected valuation increase in their retail warehouses, the impact of the office sales below BV and the late release of the NAV (for reasons unknown).
On the late release of NAV and less than expected uplift of the warehouses... you need to remember how NAV is calculated for most REITs. It is based on Discounted Cash Flow principles. Maybe the delay and warehouse NAV miss is because they have had to revisit the discount rate used in the NAV calculation in light of recent BoE rate increases. Just an idea!
All the best, Si
I wonder if Altitude (LON:ALT) is looking good for a rise. Last 3 days Directors have all been buying, though nothing enormous, but perhaps suggests business is looking well placed and profitable. This has a strong operational gearing so if sales are indeed moving up then it will look cheap quite quickly. I haven't bought any at these levels yet but am mulling over a short/medium term trade. Anyone have any more useful insight?
Does anyone have a succinct commentary on the boom and bust of Omega Diagnostics (LON:ODX) during COVID? I feel like its a story that could have lots of learnings for investing... maybe it could even be a longer in-depth article or feature on Stockopedia?
I had researched and held ODX back in 2018, 2019. When they were struggling to gain any commercial traction; either with the established immuno-assay business, or their new CD4 test for HIV. After holding for a while and making a small loss, I exited as I came to the conclusion that management were not that competent.
Have not followed their news, and of course looked with envy when their share price went to 90p+. I think I sold out around 10p, so it looks like I missed out on a 9x, almost 10x-bagger.
I see the price has now crashed back down to less than 10p.... and wondering if this provides a good learning/teaching moment to help us all become better investors?
Good morning Paul, I am not sure if you have ever looked at Kitwave (LON:KITW) , they are an independent, delivered wholesale business, and have announced this morning the acquisition of MJ Baker Foodservice. I think they got wrongly sucked into the HGV driver issues last year, but they have an in-house fleet of about 400 vehicles so no impact. They are currently building a new warehouse due to open anytime soon. Looks like they intend to grow organically and through acquisition. Results are due on the 28th Feb so maybe one you hold off until then. Have a good weekend.
I agree Lefty ... I've been monitoring Kitwave since November when their last update seemed positive. Results end of the month !
Hi Lefty99,
Kitwave (LON:KITW) rings a vague bell, but I don't seem to have covered it here yet. Noted that a couple of readers are interested, so I'll make a mental note to review its next results here.
Looking at today's news of an acquisition, I like the disclosure of valuation (e.g. includes £6m cash, and a freehold property of £1m) and this sounds like a sensible acquisition multiple -
"The multiple being paid for the Acquisition, excluding cash and the value of the freehold, is c. 6x annual run rate EBITDA."
A sector-wide worry for me would be possible bad debts, when the rent moratorium ends in March 2022, which is likely to push large numbers of zombie cafe/restaurants out of business. Similarly, the share price of Mccoll's Retail (LON:MCLS) is well into solvency risk being a big worry.
Regards, Paul.
Thanks Paul
I assume the Stocko page for Kitwave (LON:KITW) is broken, its never going to turn up on any screen with a sea of red and no Stockranks.
Mind you the Broker Target Price has got me interested
Price Target: £177.66(13,232.83% above Price)
I assume the Stocko page for Kitwave (LON:KITW) is broken, its never going to turn up on any screen with a sea of red and no Stockranks.
You think that's bad. Same applies to the £130bn market cap Bhp (LON:BHP) !!
Wayneskie did a write-up of Facilities By Adf (LON:ADF) yesterday and has industry knowledge.
Kitwave (KITW) please Paul. Acquisition announced
Good morning all,
Excellent update from Facilities By Adf (LON:ADF) this morning, revenue and EBITDA ahead of expectations.
Plus robust demand for film and content in the UK...
The UK film industry is very buoyant. I was only reading this week that Shepperton Studios have long leases on it from Amazon and Netflix, which are longer that similar deals that have been struck at Pinewood. Elstree studios also open later this year, this is on top of the plethora of towns and cities that have on street filming. I can't think of other listed companies that fill this space?
Shepperton to become the second biggest studio on the world i heard on Radio 4 yesterday.
Yes, lots of activity near me as well, especially for that HETV streaming content. There's a whole new 18 stage studio under construction with 4 stages already opened at Shinfield Studios, and the world’s" largest fully-encapsulated virtual production volume” in Winnersh
Paul did you spend all day yesterday pumping £joul ? Hope you made some of your money back on it.
I had a duvet day yesterday, so it was rather nice to wake up usefully richer! I'm quite surprised at the speed of the recovery in JOUL share price, but the spike down to 50p did look irrational (given that going concern worries have now been resolved).
Having slept on things, I think the market is seeing more clearly now that it's a fundamentally good company, with a lot of potential. However, clearly there is a question mark over current management, who seem to have lost control over supply chain & forecasting in the autumn. Also costs are running too hot I think. And it's over-stocked, as we discussed on the day.
However, all those things are fixable, and this is a business that should be capable of a 10% operating margin, if it's run tightly, with a focus on the basics - in my opinion. Hence a good opportuity, I reckon.
This seems to be a case where averaging down during a panic sell-off, was the right thing to do. My main problem now, is that I've got over 50% of my SIPP in one share, so probably ought to trim the position somewhat.
Regards, Paul.
Crumbs, the idea of you having over 50% of your SIPP in one share is going to make me struggle to sleep! Please trim :-)
Morning Paul,
I wanted to say a big thank you to both you and Jack for all your hard work week in and week out.
I especially want to thank you Paul for your well considered thoughts and reflections on Joules recently. They were very helpful and informative and I decided to take a decent punt on it which has so far been very handsomely rewarded.
Many thanks and keep up the great work.
Richard
Ah - so that's why Joules (LON:JOUL) is down this morning! Please let us know when the overhang has been cleared!
Joules down almost 7% today.
Not quite sure I see your logic-when the share was a darling company at £3.00 and you were telling us this was the case and now at 78p it's time to trim your position -seems slightly "rabbit in the headlight thinking"..
He trebled his position down around 53p so will have made a lot of the losses back. Now it has become such an outsize position he can take a chunk off the table and will still make some profits overall assuming the share price gradually rises. It's a good strategy for correcting a poor original investment as long as you don't get the wrong side of a trend. In the case of Joules (LON:JOUL) the timing needed to be after the results clarified the going concern position wasn't an issue. Ie you wouldn't buy on the profits warning but later. I have never had a position in Joules (LON:JOUL) but spotted the same opportunity but was a bit late pulling the trigger at 54p and wasn't prepared to chase.
Mark,
Joules (LON:JOUL) fundamentals have changed for the worse. That's why the share price has gone down. So the situation at 300p is very different to the situation now.
Hence I assess the facts & figures as they stand on the day, which will change over time, if the facts change.
You've completely misunderstood my rationale on this one. My existing position is long term. But I (more than) tripled the position size at 50-70p after the recent profit warning. Making it a very large position size. Hence some of it is long-term, and some of it I would trim on a strong recovery in the share price (not at the current level, but at say 100-120p I'd top slice).
Plenty of investors do this - having a core position, then some additional shares that are more for short to medium term trading.
Maybe in future, ask the question "why" first, rather than jumping to a dismissive judgement on an incomplete understanding?
Paul.
My favourite strategy is buying a stock based on belief in the long term prospects/trend but trading any significant volatility. In a rising channel this can be very profitable.
In a negative case you can get yourself out of jail but it is much more risky. Personally if I’d bought at 54p I’d be selling that stake at 80p so I’m not too exposed (many others will be banking these profits so there will be a consolidation). But trading is not for everyone.
I don’t believe Jules is going to break above the recent gap down until the management prove they are back in control. I don’t hold Joules (LON:JOUL) but I hope they do turn things around for all the PI’s who’ve been stung recently.