Small Cap Value Report (Fri 11 Oct 2024) - SAGA

Good morning from Paul!
Friday markets/macro summary
I started doing this last Friday, and people seemed to like it, so let's continue.
I’m not an expert, more a moderately educated layman, in economics, but I like to keep abreast of what’s going on, and the broad trends, to help inform my investing.
Halifax reported that UK house prices were up 4.7% year-on-year (the best rise since Nov 2022) - increasing evidence that the residential property market in the UK is recovering (although some mortgage rates went up, due to increased Gilt yields).
Florida hurricane sounds bad, but not as bad as initially feared. Seems to have had little effect on markets. Obviously hoping people will be OK (“stuff” can be replaced, but people cant), but I don’t think it’s something that UK investors need to be overly concerned with.
Moan of the week (potentially developing into a podcast rant for the coming weekend) - increasing numbers of companies are not stating if they are trading above/in line/below market expectations. That’s the whole point of trading updates, so filling them with other information, but omitting the key info is both annoying and counter-productive (as it makes investors suspicious that the PRs are trying to hide something, and undermines my trust in the company's management). That is a disgrace!
CityAM headline on Thu told us to prepare for a possible AIM sell-off (Peel Hunt reckons a 20-30% across the board sell-off is possible), as fears mount that the Budget might include an attack on AIM’s Inheritance Tax benefits, with £6bn in IHT funds potentially at risk of redemptions. We’re certainly seeing signs of strange price drops in some AIM shares, handing us some attractive buying opportunities in my view. Irrational market events like this are a great opportunity to put cash to work, in my view. It’s a question of being bold, selective, but also keeping some powder dry in my view, as most of us are not skilled traders who can time purchases at the exact low! So I’m holding my nerve but also have some cash ready to deploy if the market does go haywire. The best purchases are often the most uncomfortable!
Anecdotal evidence that some holders of SIPPs are selling shares in order to grab their 25% tax-free lump sum, following speculation that this might also be curtailed in the forthcoming budget. All speculation, but the way all this has been mishandled has done real (hopefully only temporary) damage.
ONS report out today says GDP is estimated to have grown +0.2% in Aug 2024, slightly better than 0% in June & July. Such small numbers that I don’t think we can yet ascertain a trend, and they are only estimates, which often get revised up or down. At least it’s positive anyway.
Interesting blogs from Neil Woodford, the most recent 3 are worth reading. This one mentions that the UK’s finances are getting a boost from lower interest rates, because the UK has a large amount of index-linked Gilts in issue. Also he thinks that necessary revisions to OBR forecasts could result in the Chancellor having more wiggle room than anticipated, hence a possibility the Budget may not be as bad as we fear. Thank goodness we’ll soon be put out of our misery on 30 October. As usual I’m planning on writing my thoughts about the Budget here in that day’s SCVR and maybe the next day.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
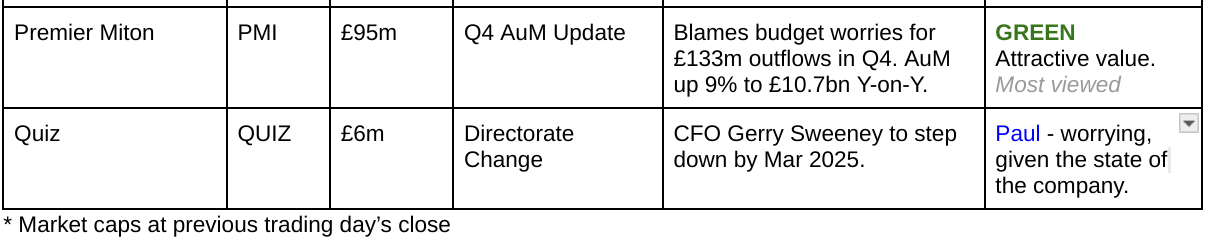
Summaries
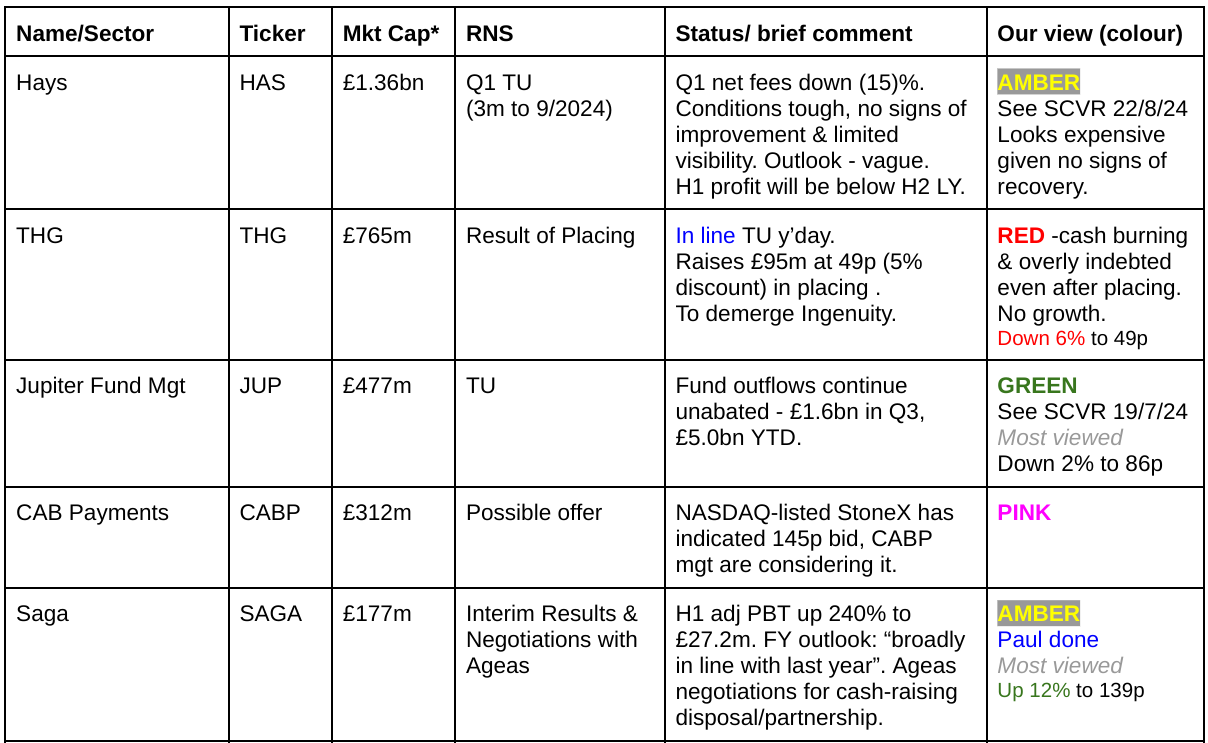
Saga (LON:SAGA) - up 9% to 136p (£193m) - Interim Results & Exclusive talks with Ageas - Paul - AMBER (possible FY PW?)
Interim results look good, with a 240% increase in adj PBT to £27.2m. That's spoiled a bit by a vague outlook statement that seems to be saying H2 will not make much profit, resulting in FY 1/2025 profit slightly below last year. Insurance broking is struggling, with profits halved, but ocean cruising is going very well, so this is now looking more like a travel business, than an insurance company. More so as it announces what seems an advanced deal with Ageas to sell underwriting, and get £80m up-front for a partnership in broking. All looks intriguing, and I suspect this share could head higher, although I don't have enough info to be sure about that, hence AMBER again.
Paul’s Section:
Saga (LON:SAGA)
Up 9% to 136p (£193m) - Interim Results & Exclusive talks with Ageas - Paul - AMBER
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, announces its interim results for the six-month period ended 31 July 2024.
The company’s headlines sound positive -
Strong underlying profit growth, alongside significant deleveraging
Continued momentum across Cruise and Travel, while market conditions impacted Insurance
This has been the same story for a while, with travel doing well, and insurance struggling.
I was amber/green earlier in 2024, 30 Jan & 19 April, but moderated to AMBER in May, June & early Oct. We’ve been following the story here quite closely for years now, with my view consistently being that when you dig into the detail, the debt isn’t as bad as it looks, with the 2 owned cruise ships being a substantial asset (£577m book value) that covers most of the debt. I’m not saying the debt is comfortable, because it’s not, but also not likely to result in anything bad happening (e.g. another placing, which I don’t think is necessary).
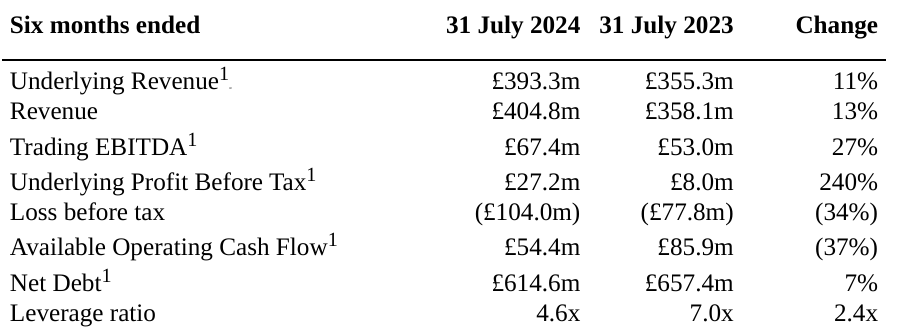
There’s a decent jump in revenues, and adj PBT for the latest half year. Although note the (once again) large statutory loss, so very large costs adjusted out. These adjustments are almost all goodwill write-offs, so that’s OK. Also a useful reduction in net debt -
Outlook - on my initial skim of the results, I couldn’t find a clear statement of whether or not it expects to achieve full year market expectations. As mentioned above, this is not good enough. Companies need to be crystal clear on this. Using some other form of wording strikes me as deceptive, and makes me less likely to want to buy the shares.
It says this today -
“The Group remains on track to deliver a full year Underlying Profit Before Tax3 that is broadly consistent with the prior year.”
I haven’t got any detailed broker forecasts. Going back to the FY 1/2024 results, it posted an underlying PBT of £38.2m. So deducing from the statement above, it only expects to produce about £10m adj PBT in H2 this year, which doesn’t sound very good.
Is this actually a profit warning then? It might be, I haven’t got enough information about existing FY 1/2025 forecasts. If anyone manages to get hold of a broker note, perhaps you could post a comment to see if forecasts are now being reduced?
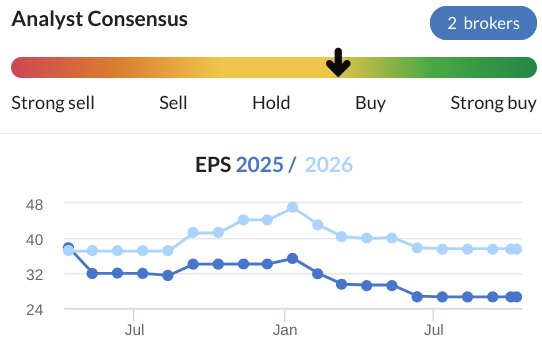
Doing some basic maths, I come up with c.20p adj EPS for FY 1/2024. That’s well below Stockopedia’s 26.6p broker consensus figure, so I suspect this might be a profit warning today that they seem to be trying to obscure perhaps?
Let’s keep an eye on the broker consensus figures in future, to see if another downgrade comes through in the coming days. The trend has been downwards of late - and SAGA has a long track record of missing its forecasts, hence why I place little value on them now - SAGA’s often incredibly low forward PER is because the forecasts are in-credible!
Ocean cruise - these numbers below look good. Although am I going mad here, with the last bullet point, how is £27.9m per ship “well in excess” of a £40.0m per ship target?? Ah of course, it’s half year figures, doh! Annualise these numbers below, and they’re impressive, assuming there’s not a huge H1:H2 seasonal weighting. It says its other travel business has an H2 profit weighting, but that may not necessarily apply to cruises, I’m not sure.
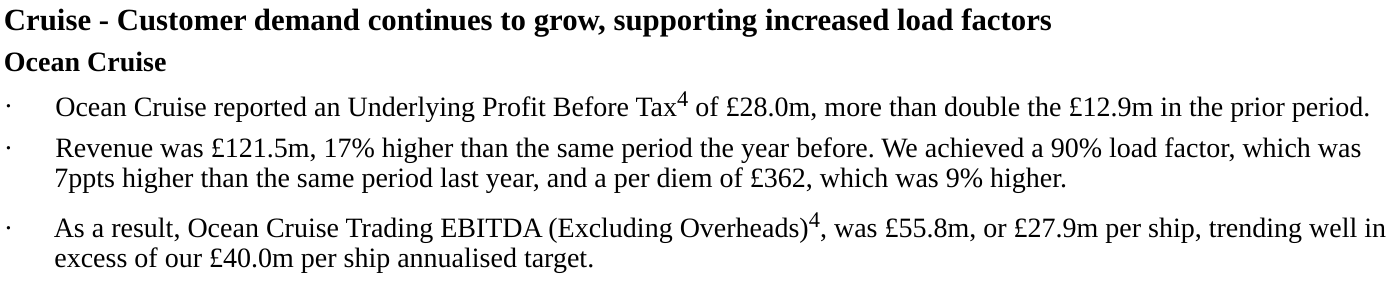
Insurance broking underlying PBT almost halved to £12.2m in H1, but it says this is as expected, and is due to competitive pressures. Maybe SAGA needs to automate things more, as it sounds to me as if profit per policy from broking is maybe under structural downward pressure?
This has driven another large goodwill write-off, which doesn’t really matter to me because I routinely write off all goodwill anyway. It is a reminder though that this part of the business is struggling, and maybe shouldn’t be valued at very much if profit is unlikely to recover?
Insurance underwriting - eked out a small H1 profit of £1.9m, vs a £3.6m in H1 LY. Hopefully they’ll get rid of this part of the business, which has always made me uncomfortable given its volatile performance.
Balance sheet - as before this is dominated by the large cruise ship assets (£577m) at the top, and net debt of £615m.
RCF doesn’t seem to be used, but has been extended by a year to Mar 2026. Covenants have been changed to include ship debt, and it’s within the key covenant of 6.0x, being 4.6x at end H1.
There’s also a loan facility from Sir Roger de Haan.
NAV is £116m, less intangible assets of £270m, gives a deficit on NTAV of £(154)m, which I would like to see repaired over time.
It would be interesting to see a pro forma balance sheet, to see what it would look like with the insurance underwriting division gone?
Dividends - are not possible, or likely to be possible for the time being, and the focus is on debt reduction.
This is, if anything the more important announcement today.
To have issued this announcement, I’m assuming that talks must be at an advanced stage -
“Saga and Ageas in exclusive negotiations over Insurance partnership and sale of Saga's Underwriting business”
The main points are -
Proposed sale of Saga’s underwriting division for £67.5m, expected completion Q2 2025.
“Affinity Partnership” between Saga’s insurance broking division and Ageas, with SAGA receiving £80m cash up-front, plus possible performance targets with £30m in 2026 and £30m in 2032. Target start in late 2025, running for 20 years.
Paul’s opinion - H1 results show quite a dramatic shift in profit away from the seemingly declining insurance businesses, and towards the much more profitable cruise ships. Together with the proposed deals to dispose of underwriting, and effectively sell the SAGA brand and some of the future broking profits in return for £80m cash up-front, then maybe we need to change how we value SAGA, and treat it as a travel company?
If the disposal & partnership deals complete, then that’s going to clear most of the non-ship remaining debt. EDIT - see this interesting reader comment below, which casts doubt on whether the £80m receipt would reduce debt, or just replace the negative working capital of the insurance underwriting business. So we definitely need more information to judge this properly. End of edit.
I don’t think we can really value this share now, because it’s going to fundamentally change shape, and we don’t have enough information about the insurance deals to ascertain what level of ongoing profits SAGA is likely to make from tying itself to Ageas.
Overall though, I like the sound of the deals, and that £80m could largely fix SAGA’s balance sheet, if it is booked as an exceptional profit, or it might have to be released over the 20 year period, I don’t know. Lots of questions, which make it almost impossible to value this share right now.
The core business will in future be the cruise ships, it appears. So maybe we could take a stab at valuation of that division alone, and assume everything else is worth only a little?
I would argue that the £193 mkt cap looks reasonable, for 2 owned & profitable cruise ships. The ships’ asset value is likely to more than cover the whole group’s net debt once the two deals above complete.
Given all the uncertainty here, I’m going to stick at AMBER, and watch with interest from the sidelines. My hunch is that there could be quite good upside on this share, but I can’t measure it at the moment unfortunately, due to so much uncertainty and lack of information.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Trainline (LON:TRN) - I have spent a few years watching this for an opportunity to short, but they look to have spent a few years improving the balance sheet, performing reasonably well. Without a negative catalyst, I have leant to sit on the side-lines with Shorting (Keep it as an option to balance out the regular ISA / SIPP long trading).
However... a work colleague mentioned to look at Uber for booking trains going forwards - They are cheaper (no booking fee so saved a few % there, but also offer an extra 10% off on Uber credit for future use).
I listened recently to a fund manager talking about Trainline's potential moat, but I'm struggling to justify the value on 20x future profits, with debt, at £1.5bn when a company like Uber can cross-platform sell you tickets, cheaper, with bigger benefits.
Interested to know others on the forums thoughts... Am I missing something? Should I be spending my Saturday outside instead of typing on here? Probably.
(Also Paul - great podcasts lately. It's my regular listen for Sunday run's on Spotify!)
Trainline (LON:TRN)
I noticed the Uber offer - ain’t tried yet. Often main players in any market have the benefit that everyone knows they are the go to place - and they should have economies of scale.
On a quick glance looks like numbers are going great guns with broker upgrades - so whilst it might seem expensive on an initial glance seems an odd short choice if their metrics are trending better rather than worse
Trainline (LON:TRN) Uber Technologies (NYQ:UBER)
Hi Traderweeks
I too have been sceptical of Trainline's business model over the years, however, they've done well to keep the top line growing as long as they have.
Additionally, having used trains in Europe over the summer I can certainly see how there's room for growth outside the domestic market - the ticketing systems I used there were very confusing, with many providers to choose from...so I guess not dissimilar to the system in the UK.
For the long term, however, I thought that Uber offered more promise in this area.
It's aim it to provide one app for all your logistical needs - air + train + road - which will be very powerful, even if it does take time to get there.
I can imagine a few companies might have the capabilities to achieve this in the long term once driverless cars are up and running (Alphabet (NSQ:GOOGL) , Tesla (NSQ:TSLA)), but the ridesharing companies (Uber Technologies (NYQ:UBER) and LYFT (NSQ:LYFT) )have a head start given their current setup.
I bought Uber Technologies (NYQ:UBER) in the last year now that they are cashflow positive and selling air + train tickets.
A
I used the Uber Technologies (NYQ:UBER) app extensively when travelling in Europe this year and I was very impressed by the functionality., the services and the prices. Sadly it’s not really available in the darkest Pennines.
Oct 11 (Reuters) - British sportswear and apparel retailer Frasers Group FRAS.L revised its takeover bid for Mulberry MUL.L to 150 pence per share on Friday, valuing the company at 111 million pounds ($145.11 million).
Mulberry's second-largest shareholder Frasers increased the bid after the luxury brand rejected its initial offer of 83 million pounds saying it undervalued the company
Paul, didn't nearly one billion shares disappear over the last eight years and long-suffering PI's cash along with them?
I still hold Saga (LON:SAGA) , added some this morning.
Paul - just to follow up on your "anecdotal evidence" with regards to selling shares to get the 25% lump sum from peoples SIPPS - I spoke to a very large fund supermarket earlier in the week and they told me that they would normally have a single team dealing with this topic BAU, but currently have four teams working on it full time.
They appear to be getting swamped with requests for this before the budget - and after a lot of thought on it I have joined that queue. It might be too late due to the backlog and I assume all companies will be experiencing a similar level of demand.
There is absolutely no way in the future that there will be any additional benefits being added to our pensions, but there is a risk of a number of the benefits of a SIPP being removed - loss of IHT benefits, reduction of tax-rebates on contributions along with the possibility of reducing the 25% cash withdrawal allowance - all, some or none - who knows?
There are risks in withdrawing this cash and not having tax-beneficial ways of protecting it, but I will live with that risk just in case there is a reduction in the 25% allowance.
Thanks for your brilliant commentary throughout the week and at weekends.
Sky reports on letter from many AIM companies to the Chancellor warning that investor confidence is being damaged by the uncertainty around business relief : https://news.sky.com/story/sco...
Paul, last weekend in addition to the mystery share we were treated to the Beeks Financial Cloud (LON:BKS) mystery results dream. It made me laugh and their results delivered a nice uplift. Will you be sharing another one this weekend?
Guidance sought please. Could anyone please give an opinion - reference whether or not Premier Miton (PMI) qualifies for Business Property Relief (BPR).
Thankyou. KBR
Looks like the biggest shareholder ofPremier Miton (LON:PMI) is Octopus Investments, the company which specialise in AIM IHT portfolios, so that indicates they seem to think so.
Thankyou Redice for your response. Much appreciated.
KBR.
Braemar (LON:BMS) have been weak the past couple of days following an investigative report in the FT about a “Russian shadow fleet” allegedly some of which have been purchased by or thru Braemar.
Jupiter Fund Management (LON:JUP) reported that investors withdrew £1.6bn from its value funds in just three months, ahead of the departure of its star manager, Ben Whitmore. These withdrawals contributed to £5bn in outflows so far this year. The majority of the recent outflows, £1.1bn, came from institutional mandates, and Jupiter warned of further redemptions to come, estimating that most of the remaining £2.3bn in institutional mandates would be redeemed by year-end.
The outflows have reduced the value team's assets under management from over £10bn at the start of the year to £4.9bn. With Whitmore leaving to launch his own firm, Brickwood Asset Management, Jupiter hopes to reverse the trend with the recent hire of Alex Savvides, who will manage the UK Special Situations Fund. Additionally, Jupiter has recruited a London-based team of fund managers from Origin to reduce reliance on UK stocks.
Jupiter’s total assets under management fell to £50.1bn, down from £52.6bn in March, as mid-sized asset managers like Premier Miton and Liontrust also face withdrawals. Uncertainty around the upcoming UK Budget, particularly regarding capital gains and pension taxes, has dampened investor sentiment, contributing to recent outflows across the industry.
Despite these challenges, Jupiter noted that net inflows were generated in other areas of the business, excluding losses from the value team and the departure of the Chrysalis investment trust, whose managers left earlier this year.
Thanks Paul for an excellent write up of Saga (I hold) this morning. Really appreciated.
Love this gem you wrote:
" SAGA’s often incredibly low forward PER is because the forecasts are in-credible! "
Small Request to Stocko
Would it be possible to have a button (or keyboard shortcut) that automatically loads the next stock in the triggered alert notifications with a single click please?
Currently you have to click on the bell icon, and then click on the triggered alert you want to view.
(Every little helps)
Great idea Turbo, you can make requests on the green button below right :).
Turbo - reading between the lines of your request I think you are living in the same world of pain as me - a large stream of stop loss price alerts being raised....painful.
Can we please stop posting the stockopedia comments onto other website's bulletin boards.
I know there is little that subscribers or stockopedia can do if someone wants to do this, but I don't think it's fair on people that pay to subscribe.
Re. Saga (LON:SAGA) , I’ve always been sceptical of the argument that the debt is asset backed and in my opinion, the £577m book value for two ships (already 3 and 5 years old) is optimistic. It is said the two happiest days of boat ownership are the day you buy and the day you sell. In the interim, there is a truism that a boat is a hole in the water you pour money into. This is especially true of commercial vessels where the regulatory overhead, maintenance and running costs are onerous. Another operator thinking of purchasing these liabilities will also be aware of the enormous refit costs to modernise the vessels (5 years is not especially new in the life of cruise ships). I suspect the realisable asset value of the two ships might be as low as half the book value. Of course, so long as they are being operated, they are generating returns but as assets, they are depreciating faster than a brand new Range Rover off the forecourt, and certainly faster than a property asset would be.
There was a list put up here over the last few weeks of the top holdings of the IHT funds, does anyone know what day it was on or has an up to date version? Thank you
Here you go:
https://www.stockopedia.com/co...
Thanks!
Economist here. Agree that awareness of some macro context can be informative, and it's a good way to warm up the eyes when dipping into the daily SCVR but hope you keep it light and tight.
The mixed performance of macro hedge funds shows it's hard to turn even high quality economic inaight into alpha, not the least due to divergent readings of the same fundamentals. That's the reason why fund and bank 'chief economists' sit on comparatively modest pay cheques, they are mainly there to provide narrative for reports etc and typically miss large systemic events, not there when we need them :)
Saga (LON:SAGA) the answer to the first question on the analyst call was an absolute classic imho…CEO starts by setting out the backdrop to the transaction at some length…leaves the CFO to break the bad news that given the favourable working capital model they currently have ….the £80m will “broadly” cover the unwind of this. Body language was a picture
Paul.
There’s a lot more on the Saga travel side than cruises. They’ve got a growing non cruise business.
Here’s a link to one of their several various travel websites. Scroll down to the bottom for a list of what they offer on the travel side.
https://holiday.saga.co.uk/hol...
I took the profits on SAGA ages ago and it’s still too uncertain to be tempted to buy again. Their updates are too vague and there often leave me feeling they are trying to hide bad news.
Hi Ken,
That's true, but the rest of the travel business, and the river cruises, doesn't really make any significant profit, hence why I glossed over it.
Regards, Paul.
Hi Paul, It is interesting, at least to me, that the almost certain major escalation in the Israel/ Iran war seems to be ignored by American and most U.K. economic commentators. Surely, this situation must have a major effect on markets if, as I strongly suspect , Israel will target oil installations and probably nuclear sites in Iran.
In anticipation of this, I am 75% in cash waiting for the inevitable market crash, even if this is only temporary. Not sure if you have mentioned this possibility ( certainty as far as I am concerned) in your market comments recently .
Perhaps the markets are taking the viewpoint that this war cannot go on forever and sooner or later some "ceasefire" will be acheived - at present Israel seem to have no interest in doing a fair deal though so the risks are clear and present - i doubt even if there is ceasefire deal done that it will remove any of then undelying tensions they will remain until Israel stops confiscating land from Palestinians who have lived in their homes for generations (zero sign they want to do anything ither than take it all for themselves at present. )
Once the presidential vote is over, Biden would no longer have his hands tied and could, for instance, suspend some weapons supply to Israel and relax some of the constraints on supply and use of arms for Ukraine.
He could but I am sure he would do nothing because of the very powerful Jewish lobby in the USA . Frankly, the USA is complicit in the genocide that is happening in Gaza and increasingly the Lebanon .
Paul/Stocko - please remove the comments on the Middle East war posted here today by rmillaree, pimlico on thames, caper 4 - they are purely venting their own political views, nothing to do with investments. Seems people just cannot help themselves in expressing their personal opinions.
my response here was with regard to how it related to investments as the question was asked - i did include some factual info that was relevant to how quickly the issue would be sorted. You can request that it be removed but hopefully a mostly on point brief chat is nothing for people to get their knickers in a twist about. If you dont like whats written fairly easy to scroll on. Hopefully the powers that be will see that the question and answers were not exactly off point.
Note the question got 14 likes so clearly not everyone agrees with your assertion that the question was off point - particularly on a quiet friday.
Dartagnah - if you click on the blue flag it turns it red and you can choose an option as to why you have done so. Stocko then investigate all red flags. Red flags can also be clicked on by multiple other subscribers.
Massive growth in US and Brazil oil/gas since the last one. see Adam Toose substack.
Yes I heard that the US is now energy self-sufficient, so much less interested in the M.East than when it depended on them for oil.
In the scheme of things is the latest Israel/Arab confict really that important from a purely investment perspective? I suggest not.
The conflict has been going on in one form or another since the end of the Ottoman empire over a century ago.
The worry would be over a major escaltion in oil prices of Israel but Iran is already supposedly sanctioned , and if its back door route to illicit oil sales is closed by military strikes, so what? I doubt we can predict if slightly higher oil prices would be a disadvantage greater than a weaker Iranian regime.
Anyway FWIW my take is for investment purposes it is wisest to ignore news from the Israel conflict.
Join us for MelloMonday this Monday 14th October 2024, at 5:00pm. The programme for the evening is as follows:
5:00pm Keynote Speaker
5:30pm Company presentation from Transense Technologies plc
6:10pm Company presentation from Newmark Security plc
6:40pm Educational Presentation
6:55pm Company presentation TBC
7:25pm BASH (Buy, Avoid, Sell, Hold) Panel
For more information, click here: https://melloevents.com/mm141024/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1367830
More Upcoming Events:
Mello @ The London Investor Show on Friday 1st November 2024, 9.30am – 5.00pm Novotel London West https://melloevents.com/mellolistickets/
Mello 10 Year Anniversary Event in DerbyTuesday 19th November & Wednesday 20th November 2024, 9.00am – 7.00pmDerby Conference Centre, Derbyshirehttps://melloevents.com/mello10tickets/
*ANNUAL PASS OFFER* We have lots of exciting virtual events in the pipeline for the upcoming months! Grab yourself a Spring annual pass, NOW JUST £75 (was £125)!
UK executives dump shares on fears of Labour capital gains tax raid
Public filings show disposals have doubled in wake of election and ahead of crunch Budget
The total value of disposals since election day has reached around £440mn © FT montage/Bloomberg/Reuters
Executives have stepped up sales of their shares in UK-listed companies ahead of this month’s Budget, as chancellor Rachel Reeves considers increasing capital gains tax in a bid to bolster public finances.
Since Britain’s July 4 election, directors of listed companies have sold shares at an average rate of £31mn a week, more than double the £14mn pace of the previous six months, regulatory filings show.
The total value of disposals since election day has reached around £440mn, according to the figures compiled by investment platform AJ Bell.
I have taken capital gains and passed cash on to family i bet the Budget makes this more costly
MVL (member voluntary liquidation)
I hold most of my shares in a limited company.
I decided to sell most, pay CGT and corporation tax before 30 October.
The Sod’s Law is that there would be no increase in CPT!
Paul ahead of the game again on this one ☝️ looking forward to listening to the podcast this weekend.
Paul did you ever read Flashboys by Michael Lewis? Everytime you mention Beeks I think of that book, it’s a good read. Am not a holder.
Paul- I agree. I would never buy a share based on a future )hopeful) tax break. Maybe I am not wealthy enough to worry about maximising the inheritance of my children- they are doing fine financially.
Hi Paul,
Can you share your thoughts when it is a quiet news day, and list some ideas for companies that are likely to benefit from the budget with regard to how Labour are going to spend the money they raise? I appreciate investors are selling off in anticipation of what might happen and some of these shares might be over sold already or the first to rerate? Wonderful podcasts so please keep them coming. Is this the only place I can rate them? I listen on the YouTube podcast app and there didn't seem to be a function for any written comments?
Am I mistaken Andrew, only I thought Labour were to use to the money to fill the Black Hole the last government left them?
Morning Andrew,
Sorry I haven't got time today, as I need to finish on time so I can go to a conference in London.
We've already discussed here in the reader comments that infrastructure building companies like COST, GFRD, KIE, etc might get a boost. Also a desire to build more houses could benefit housebuilders & building supplies distributors. But all that's probably already known, and hence in the prices maybe?
Feel free to discuss any other ideas. My only reservations are that we could have unintended consequences from tax increases - as we've already seen just from fears of tax changes. Also infrastructure projects take years to even start, due to all the planning considerations, and several existing programmes have actually been cancelled already. It's not really an area I spend a lot of time thinking about, as often it's difficult to predict these things, and if they're obvious then they'll already be baked into share prices probably.
Regards, Paul.
SPI
one company that should benefit from the government spending is the Spire healthcare.
I read in the news that the NHS is going to spend 1 billion treating patients on the waiting list in the private sector. In my mind, the SPI is either taking advantage of this or it may be take over by other private healthcare providers.
The Govt is planning on encouraging more renewable (solar and wind) electricity. I would not think this will benefit existing operators (eg Greencoat UK Wind (LON:UKW) or Bluefield Solar Income Fund (LON:BSIF) as it is likely to only increase the “capture discount” ie average wind energy realised prices will be further below average energy prices). Who will benefit?
In theory the existing Battery Energy Storage cos (eg Gresham House Energy Storage Fund (LON:GRID) , Harmony Energy Income Trust (LON:HEIT) ) are beneficiaries but I am worried that the price of new batteries is coming down so fast that their historic investments will prove to have been at too high a cost.
Therefore, I am looking more at those who might benefit from the infrastructure spending. General contractors could be a good bet. In small cap space (and not very liquid), I own Good Energy (LON:GOOD) which has as a part of its strategy a roll-up strategy of green energy contractors.
Hi Wimbledonsprinter. One contractor which could benefit from increased spending on wind energy infrastructure would be Keller as the company claims to provide geotechnical solutions to a variety of infrastructure projects in the energy sector.
Re renewables - I am more optimistic than for existing operators. Yes extra capacity is coming on stream very fast and at lower cost so a discount to book on old assets makes sense (although these older projects often have lower interest rate payments attached and finance costs are critical to renewables).
What I think is under-priced is the ability of existing wind/solar farms to add incremental revenue to sites via upgrades, extensions and especially onsite batteries. They have the crucial link to the national grid which is a key bottleneck and will be so for a while. T
Technical changes at the National Grid mean batteries will likely get a much better shot at supplying demand within the next 12months so renewables will likely increase their market share noticeably.
The lower long term energy price has been signalled for some time and is already in the price (and will deter new investments).
Saga (LON:SAGA) at first glance this looks to me like the sale of the insurance and underwriting business will mean the 2026 bond repayment is pretty much assured, which should have been the main drag factor on the share price recently. £150m guaranteed + normal operating cash flow + contingent earn out should remove a lot of uncertainty irrespective of their ability to refinance part of the bonds if they so wished.
That will bring debt ratios right down as well.
Obviously they will lose a chunk of profitability from insurance but they will get commission so be interesting to see what that all ends up looking like at the bottom line. But the cruise ships appear to be generating closer to £100m of ebitda and with the travel business turning positive that feels like the ship debt will come down rapidly.
Saga (LON:SAGA)
i have cut and pasted this comment from the other place - i havent fact checked the contents but i am preuming it shoudl be pretty easy to fact check
per comments on the other place
Not sure if you listen to the analyst call. But one major piece of important info, all of the £80m for the insurance partnership will go to cover negative working capital outflow as insurance contract runs-off before Ageas takes over the business.
So these £80m will have no impact on net debt. Not great.
Thanks rmillaree,
That's a very interesting point re the £80m SAGA proposed cash receipt being needed to plug the negative working capital from disposing of insurance. That does make sense, as traditionally the business model for insurance underwriting was to get the cash float upfront, and then earn investment returns from it before claims have to be paid later. It was that great insight which set up Warren Buffett with a big pot of cash to invest early on, when he bought an insurance business.
Although I think the £80m cash receipt should help repair the balance sheet NTAV, if my understanding is correct.
We really do need some detailed broker research on this, but frustratingly none is available. It's ridiculous that a co with a mkt cap of only £177m seems to think like a large cap still, and doesn't get any research out to private investors. Although I think they are doing an IMC webinar on Monday next week, which is helpful.
Regards, Paul.
I didn’t get chance rmillaree - hmm. There’s always something with this company that the headline numbers don’t quite translate. I suppose it depends how much commission they get then.
Once again we don’t really have enough information….sigh
Oxford Metrics (LON:OMG)
Small acquisition of Sempre for c. £5m (relative to £50m+ of cash on b/s).
Below 1x sales, margin similar to existing business. Revenue growth of 8% recently.
Not transformational. But not mad or a hail mary pass either, which is reassuring when you have some new-ish management with a pot of cash at their disposal....
and a £6m share buyback announced too at Oxford Metrics (LON:OMG)
If the share price continues to undervalue, I can see that share buyback being extended. I don't know what took them so long to initiate it!
But NO director buying at Oxford Metrics (LON:OMG) . It is of note that there were massive director sales after the big disposal with the share price much higher so no buying now is a red flag for me.
Revolution Bars (LON:RBG) Rob Pitcher been listening to Nina Simone recently?
It's a new dawn
It's a new day
It's a new life for me. (Zero cost options may be included)
:-D very good wolf………..that’s exactly how it feels….
No matter what you name a turd, it's still a turd. Revel Collective (LON:RBG)
" A rose by any other name would smell as sweet" (William Shakespeare, Romeo and Juliet). Or in this case "A turd by any other name would smell as {fill in your own conclusion here}"
I have avoided since I realised, ages ago, that RBG were gaming the Trustpilot scores by posting lots of fake reviews on the Trustpilot site. The reviews were not identical but much too similar to be coincidence. Once you know that they are lying to Trustpilot (and hence to their potential customers) what hope that they will tell the truth to their investors
Anyone that missed my late post last night with this news on Cab Payments Holdings (LON:CABP) CAB Payments Hldgs - Statement re Possible Offer #CABP @CABPayments https://www.voxmarkets.co.uk/r... #voxmarkets undefined
I hold and hoping for a lot more!
Hi Toad1957,
Thanks for flagging this, I missed it. So have added it to today's list, so we can keep track of all the bid situations on my spreadsheet here (coloured PINK). Some are just updates on existing potential bids. More recently I've started colouring the updates in lighter shade of pink, to make it easier to identify new bid approaches.
To help people with colour-identifying issues, bid situations are always on the far left, and good to bad also works left to right.
It's quite interesting following the patterns, as we can see that bid approaches have definitely slowed down compared with the almost frenzy of activity early in 2024. Also profit warnings have clearly increased in recent weeks.
Company updates seem to be showing only a hesitant (if any) economic recovery so far, as again Hays confirmed today - staffing sector still in the doldrums, not only in the UK but similar in Europe and Australia too.
Regards, Paul.
My morning smallcap tweet: It's a crock, Monsieur
Crossword Cybersecurity (LON:CCS) Microsaic Systems (LON:MSYS) Revolution Bars (LON:RBG) Skinbiotherapeutics (LON:SBTX) Digital 9 Infrastructure (LON:DGI9) Trakm8 Holdings (LON:TRAK) Verici Dx (LON:VRCI) Saga (LON:SAGA) Sareum Holdings (LON:SAR) Ground Rents Income Fund (LON:GRIO) Argo Blockchain (LON:ARB)
◄Crossword Cybersecurity (CCS)► co will need to raise up to £600k within the next 6 weeks to continue operations. Talks with holders and a potential investor on raising further finance. Plans sale of underlying business and assets. No guarantee that any value will accrue to shareholders as a result of the Proposed Sale. [SP=1.71 Cap=2m]
◄Microsaic Systems (MSYS)► FY-Dec23 out but shares remain suspended until H1-June published, 'in the coming weeks'. [SP=1.05 Cap=2m]
◄Revolution Bars (RBG)► changes name to The Revel Collective. Ticker will be TRC from 14th. CEO Rob Pitcher claims "it provides a new dawn and stability from the uncertainty which our restructuring caused...and a new era in our journey". Deluded as ever. He may be sighted sitting at the bar crying into a whiskey, buttonholing a stranger about his troubles. [SP=0.8 Cap=12m]
◄SkinBioTherapeutics (SBTX)► buys Bio-Tech Solutions for £1.25m funded mostly by £950k shareholder loan and £250k subscription by the same, at 10.64p (6% discount). Loan comes with 3.3m warrants at 10.64p. CO has enough cash to Summer 2026 without any additional income from Croda or other joint development agreements. [SP=11.25 Cap=25m]
◄Digital 9 Infrastructure (DGI9)► appoints InfraRed Capital Partners as investment mgr. Will pay £3.75m PA for first 3 years. Also a performance fee of 3.5% of any distributions above £225m and 4.75% of any distributions above £300m. [SP=17.6 Cap=152m]. I hold.
◄Trakm8 (TRAK)► wins 2 year contract extension with Sainsbury's Information Systems. [SP=6 Cap=3m]
◄Verici Dx (VRCI)► warns service biz contracts signed to date expected to generate revenue in 2025 rather than 2024 Q4. Licensing revenues remain on track. Also coverage determination for its Tutivia delayed to H1 2025. [SP=6.03 Cap=15m]
◄Saga (SAGA)► talks with Ageas re insurance partnership and sale of Underwriting business. Partnership hoped to go live by the end of 2025 at which point Ageas will pay £80m plus £120m max contingent. Ageas will pay £67.5m for Underwriting biz in Q2 2025. Also H1-July. Insurance broking weak. [SP=125 Cap=177m]. I hold.
◄Sareum (SAR)► £2.4m subscription at 20p, a 27% discount, to further develop its lead candidate SDC-1801. With warrants natch'. [SP=27 Cap=29m]
◄Ground Rents Income Fund (GRIO)► update on planned wind-down. [SP=22 Cap=21m]
◄Argo Blockchain (ARB)► Murphy vs. Argo Blockchain class action dismissed. [SP=8.81 Cap=72m]
Ah yes...Revels.
Lovely till you realised you were playing Russian Roulette with the horrible coffee/coconut centred ones.
Whether you hated coffee or coconut defines your generation ;-)
Coffee!
(1, down) Insecure method of password generation, often spoken in haste (9)
err, Crossword?
:o) I was just mulling over how companies choose the worst possible names. Cirata, Zigup etc.. and today was a high point with Crossword Cybersecurity and The Revel Collective - sounds like an unsuccessful 90s mancunian band like Joy Division but sh*t.
edit: for clarity both Redde Northgate & Joy Division were/are decent companies/bands !
Saga (LON:SAGA) - they key paragraph (to be considered in the light of Saga's market cap being £176m and the EV being £780.....)
Proposed terms1
Affinity Partnership
· The Affinity Partnership would be for a 20-year term, with the ambition to go live by the end of 2025.
· Ageas UK would pay Saga an upfront consideration of £80m, payable at or around the go live date.
· Additionally, Saga may receive contingent consideration of up to £30m in 2026 and up to £30m in 2032, subject to certain policy volume and profitability targets being met.
· SSL would receive commission on the GWP generated over the term of the Affinity Partnership representing the value that SSL will continue to provide through the Partnership.
Ageas's acquisition of AICL
· Ageas UK would acquire AICL for a total consideration of £67.5m, subject to customary completion adjustments.
· Completion of the AICL transaction is expected in Q2 2025 and is conditional on the signing of definitive transaction documentation and certain regulatory approvals.
Cruise business materially ahead of the £40m ebitda expectations as well read well to me, tucked away a bit that statement
Surely the route to a share price of around £4-6 is well set now. £800m market cap if the debt is broadly offset by the cruise ships with the Aeges money would be £5.80/share?
Saga (LON:SAGA)
Cruise business materially ahead of the £40m ebitda expectations as well read well to me, tucked away a bit that statement
errrrr - thast more than negated by the chunky exceptionals and the fact that unless i am missing something its a profit warning today.
Anyway prior to today we had £37.4 mill of expected net profit per stocky
All they say today is
The Group remains on track to deliver a full year Underlying Profit Before Tax that is broadly consistent with the prior year.
oh dear the dreaded use of the word broadly - i always take that as being no more than but almost certainly less than !
Per the 2024 annual report we had £38.2 underlying profit before tax. I doubt this is going to translate into £37.4 mill of net profit personally.
Hey ho they have used the term "remains on track" - so i suspect they dont see it the same way i do but there you go. I can cant imagine that forecasts will be uppped today and it will be intersting to see if any brokers cut forecasts - seems clear to me that they are struggling to beat last year.