Small Cap Value Report (Fri 12 April 2024) - EPWN, CHH, IQE, FUM, PFC, RQIH, PMI, SRC

Good morning from Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
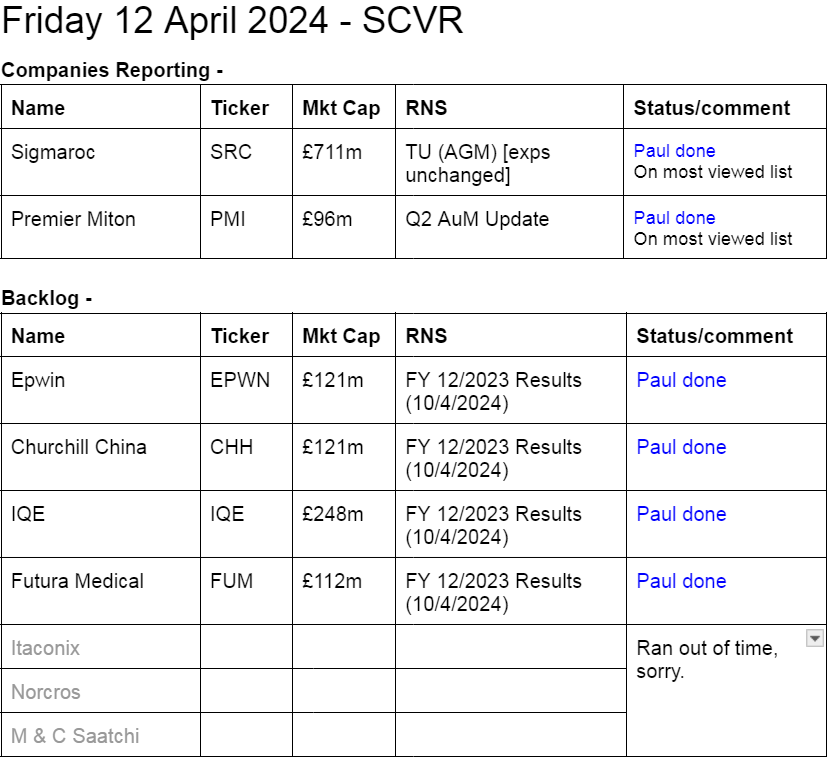
Hardly any news today, so that's ideal as it gives me a chance to work through some backlog items -
Other mid-morning movers (with news)
Petrofac (LON:PFC) - down 30% to 23.2p (£123m) - Update on strategic & financial options - Paul - RED
This sounds ominous. I’ve not looked at PFC before, but it used to be a huge company, with a mkt cap of £5bn in 2013 for example (click on the “print” button on any StockReport, to look back over c.11 years historic StockReports, incredibly useful for viewing the historic numbers). In 2012 it made $764m operating profit on $6.2bn revenues.
It’s in a real mess now. Today it says that “all options remain under consideration” as it negotiates with lenders over a debt for equity swap, and talks to investors about raising more equity, plus possible asset disposals, and trying to secure guarantees to support recent contract wins.
Paul’s view - PFC is clearly a financially distressed situation (which was already known), and in these situations it's a lottery whether it recovers, or if existing equity could be worth little to nothing. It has an $8bn order backlog, so the business looks likely to survive, but existing equity could be seriously damaged in any restructuring deals. Whoever puts in the new money calls the shots, that’s the trouble with all financial distressed restructurings. For small shareholders the safest option is just to sit on the sidelines and wait to see what sort of deal is done. Why take the risk of being a lamb to the slaughter in a deal where existing small shareholders have the weakest hand? It’s just for gamblers at this stage, as there’s such a wide range of potential outcomes, depending on how negotiations/deals go. Note that net debt was $584m (£467m) at June 2023, almost 4 times the current market cap. So heavy dilution to fix the balance sheet seems likely. I’ve got to mark it RED, to flag the high risk, but I have no idea what the outcome will be.
R&Q Insurance Holdings (LON:RQIH) - down 45% to 3.0p (£11m) - Trading Update & Disposals - Paul - no view.
Says that a disposal should complete in Q2 2024, and will allow “material financial de-leveraging”.
The trading update sounds poor -
Based on preliminary and unaudited information R&Q anticipates that it will realise a significant pre-tax loss for the year driven by the adverse development in Legacy and a material increase in corporate costs in relation to the Sale of Accredited.
Paul’s view - none, as it’s way too complicated for a quick review. One for special situations experts only I’d say. The share price has almost completely collapsed, so the market clearly thinks it’s in serious trouble. The shareholder register surprises for having some big name, credible institutions with >3% holdings.
Summaries of main sections
Churchill China (LON:CHH) - 1,150p (£121m) - FY 12/2023 Results - Paul - AMBER/GREEN
Maker of robust pottery for the hospitality sector. Very sound finances, with a strong balance sheet. 2023 results are solid, profit up 12% on 2022. Valuation has historically been excessive, but now looks reasonable, so overall I quite like it.
Epwin (LON:EPWN) - 86p (£122m) - FY 12/2023 Results [in line] - Paul - AMBER/GREEN
Decent performance in 2023, despite macro headwinds. Valuation seems modest still, despite 21% recent share price rise. Generous, well covered divis, and it's doing buybacks. Finance costs imply that bank debt might be higher during the year on average, than the year end snapshot possibly? No sign of cyclical recovery in its end markets, but does that matter given EPWN is trading OK in depressed macro conditions? Cyclical upside could be good maybe, when it happens.
Iqe (LON:IQE) - 28.5p (£274m) - FY 12/2023 Results - Paul - RED
Terrible 2023 results, but a strong improvement in the year from H1 to H2. Shored up its balance sheet with a placing, I doubt that will be the last. A long track record of disappointing. It's a capital-intensive, capex hungry business, that (so far) doesn't seem to generate any return from its investments. So what's the point? Performance needs to greatly improve to justify anything near the current market cap.
Futura Medical (LON:FUM) - 36p (£109m) - FY 12/2023 Results - Paul - RED
Lousy figures for 2023 from this startup, although the first revenues have started for its Eroxon product. Slight problem - it doesn't work, according to both the majority of reviews online, and I confirmed this in my own mystery shopping the product. "Material uncertainty" in going concern. I suspect this share could be heading for disaster, as a product that doesn't work won't sell.
Premier Miton (LON:PMI) - up 3% to 61p (£99m) - Q2 AuM Update - Paul - GREEN
Some promising signs in this fund managers' update that equity fund outflows are finally drying up. I could be wrong, but this seems a good time to be looking at these cyclical shares, and anticipate a recovery that's starting to look increasingly likely that it might be in the early stages. Decent balance sheet with plenty of cash, and a nice yield too. I like it.
Sigmaroc (LON:SRC) - 64p (£711m) - AGM Statement - Paul - AMBER
My first time looking at this rapidly expanding limestone quarrying group. It all boils down to whether management's dash for growth will deliver shareholder value in the long run or not. It's taken on a lot more debt in 2024, and there are no divis as yet. Not really my type of thing, but good luck to holders.
Paul’s Section:
Churchill China (LON:CHH)
1,150p (£121m) - FY 12/2023 Results - Paul - AMBER/GREEN
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to announce its Final Results for the year ended 31 December 2023.
The company headline is maybe too brief, at just two words! -
Improved profitability
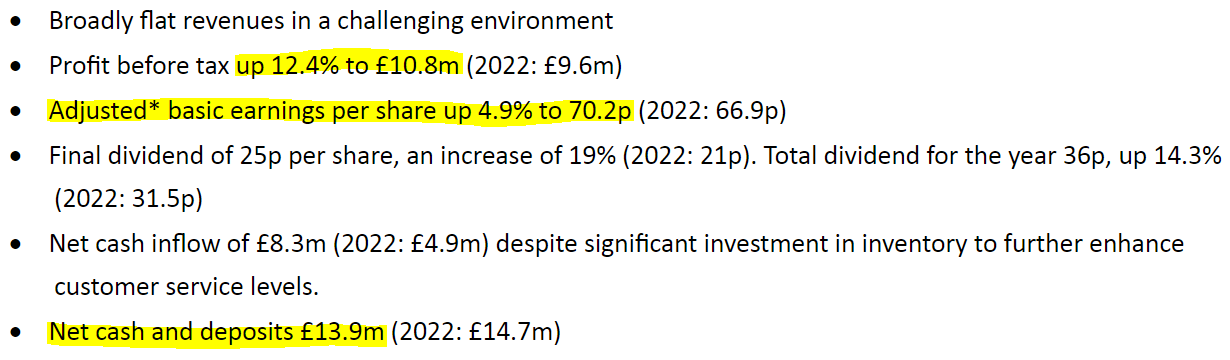
That’s a PER of 16.4x for 2023 actual results.
70.2p actual EPS seems below consensus of 82.5p shown on the StockReport.
Solar panels now provide “up to 100% of the main factory’s electricity requirement on sunny days”. I wonder if kilns still use gas though? Note it has forward purchased energy to Q2 2025, to lock in current lower prices - sensible.
The tax charge in 2023 almost doubled, which blunted EPS growth vs PBT growth.
Balance sheet is very good, with a striking surplus of working capital (current assets £47m incl £14m cash), current liabilities £14m.
NAV £60m, less intangibles of £1m, gives a very decent £59m NTAV. That’s half the market cap supported by tangible net assets, a good position to be in for the company and investors.
Note the pension scheme is shown as an accounting asset, but actually requires £1.75m pa in cash contributions from the company - reminding us how absurd pension scheme accounting rules are. Although it sounds like the cash payments might not be needed for much longer maybe?
Cashflow - looks fine to me.
Outlook -
We have delivered an improvement in operating profit and margins during the year despite flat revenues and strong headwinds particularly in our hospitality markets. Volumes were down year on year, driven by softer demand in the second half of 2023. We believe this trend will continue into the first half of 2024 and the first quarter of 2024 has seen demand as expected.
We are confident that the continuous improvement in our product range and market position, backed up by our ongoing investment programme, has placed the Company in a strong position to take advantage of a market recovering from current weakness, which we expect to see in the second half of 2024.
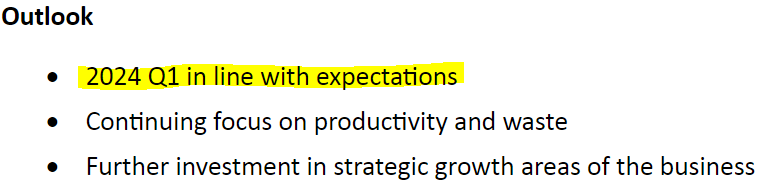
I don’t have access to any broker notes, but the StockReport here shows 79.6p EPS forecast for FY 12/2024, which would be a PER of 14.4x - which strikes me as a fair valuation.
Paul’s opinion - I’ve never understood why CHH shares attracted such a premium valuation in the past (often PER c.20x), which didn’t really seem justified for a mature business that performs OK, but no great shakes.
It’s now come down to a much more reasonable 14.4x 2024 consensus forecast. Combined with its strong balance sheet meaning there’s no solvency risk (unlike Portmeirion (LON:PMP) I’m afraid to say), then I’m happy to shift up to a more positive view, so it’s AMBER/GREEN for me. Hopefully business should grow more strongly once the economy is in recovery mode.
Epwin (LON:EPWN)
86p (£122m) - FY 12/2023 Results [in line] - Paul - AMBER/GREEN
Epwin Group Plc (AIM: EPWN) ("Epwin" or the "Group"), the leading manufacturer of energy efficient and low maintenance building products, with significant market shares, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors, announces its full year results for the year ended 31 December 2023.
Company headline -
Well placed after another year of strong profit growth and strategic delivery
I last looked at this building products group here on 27/11/2023, AMBER/GREEN at 71p, on an in line trading update, concluding that it looked very interesting, and seemed to be performing well despite tough macro/sector. 7% divis were twice covered and buybacks announced. I should have been bolder and gone green, but other companies in the sector were warning on profits and reporting subdued demand at the time.
It says 2023 trading was strong, and “modestly ahead of expectations”. Shore confirms that operating profit beat consensus estimate by 4.5%, good news.
On to the FY 12/2023 results, some key numbers -
Revenue down 3% to £345m
Adj PBT £18.0m (up 9%), helped by higher margins.
Adj EPS up 8.5% to 9.71p (PER 8.9x)
Adjustments look reasonable, being mainly goodwill-related.
Bank net debt £14.4m (down by 20% vs end 2022), modest at 0.5x EBITDA.
Tons of headroom >£60m on bank facilities extended to Aug 2026.
Extending share buybacks.
Total divis for 2023, 4.8p yielding 5.6%
Inflationary pressures being “actively managed”, but are easing.
Extending product ranges, and making acquisitions.
Outlook - no sign of any cyclical recovery yet, which is what we’re hearing from most other sector participants too -
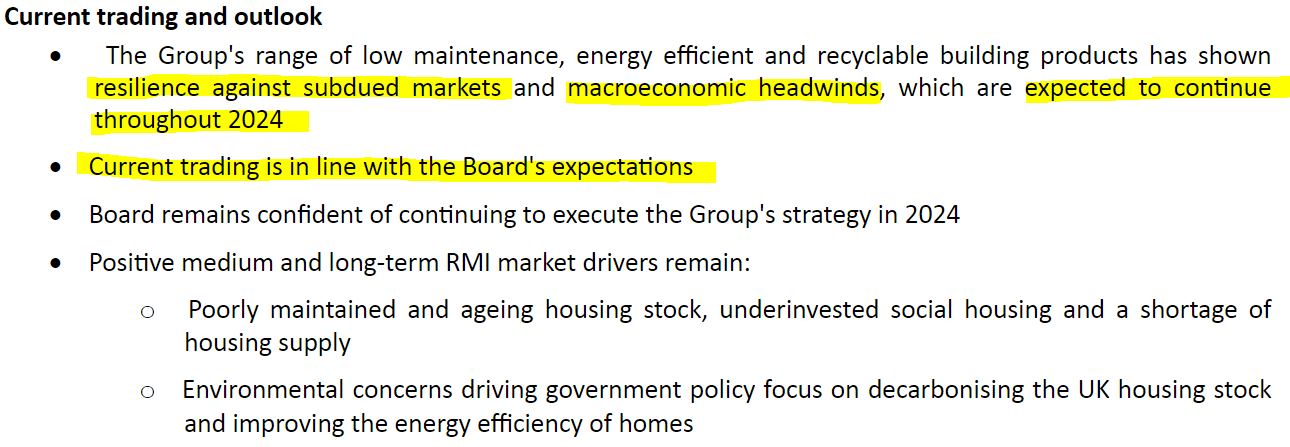
Broker forecasts - thanks to Zeus and Shore, which both publish updates via Research Tree. Shore sees a modest increase to 10.3p in FY 12/2024. I wonder if there might be upside on forecasts, given that EPWN has proven so resilient in the current downturn, and a cyclical sector upturn likely to happen at some stage? Later this year, or in 2025, who knows?
Balance sheet - looks OK. NAV £102m, less intangibles (acqusition-related) of £95m, so there’s only £7m NTAV.
Working capital looks well under control, with both inventories and receivables looking quite modest relative to revenues.
As with all companies, I’d like them to disclose average daily net debt, not just the year end snapshot. Note 4 shows £3.1m “interest expense on borrowings”, so if we assume an interest rate of say 6% payable by EPWN (c.2% above average SONIA of about 4% in 2023), then I reckon gross bank debt would have been c.£52m averaged throughout 2023. That’s much higher than the year end snapshot, so this needs to be queried on any webinars - what is their average daily net debt?
Also I don’t see any finance income, which seems odd given it reports gross cash of £13m at 31/12/2023. So another question to ask management is why they don’t seem to earn any credit interest on cash balances?
For these reasons I suspect the year end balance sheet might have been window-dressed to show a flatteringly low net debt figure that may not be representative of the average net debt position throughout the year. Hence we need to query this with the CFO if they do a webinar.
Cashflow statement - the post-tax operating cashflow looks amazing at £37.6m (similar in 2022), but there are large lease-related costs further down, of £3.4m+£10.9m, so I adjust those out to get a more realistic cash generation figure of £23.3m, still very good indeed for a company with a market cap of £122m.
About half of that cashflow was spent on capex, interest costs, and a small amount of deferred consideration re acquisitions.
Dividends and buybacks cost c.£7m, and debt was reduced by £5m.
In summary then, EPWN is self-funding capex and generous divis, which looks a healthy cash generative business.
Going concern statement is fine, no issues.
As you can see from the StockReport below, there’s a lot of green - with a StockRank almost on maximum, and low valuation metrics.
Quality rank is high at 88, but the individual metrics (ROCE, ROE and operating margin) are only middling, so I don’t quite understand that mismatch.
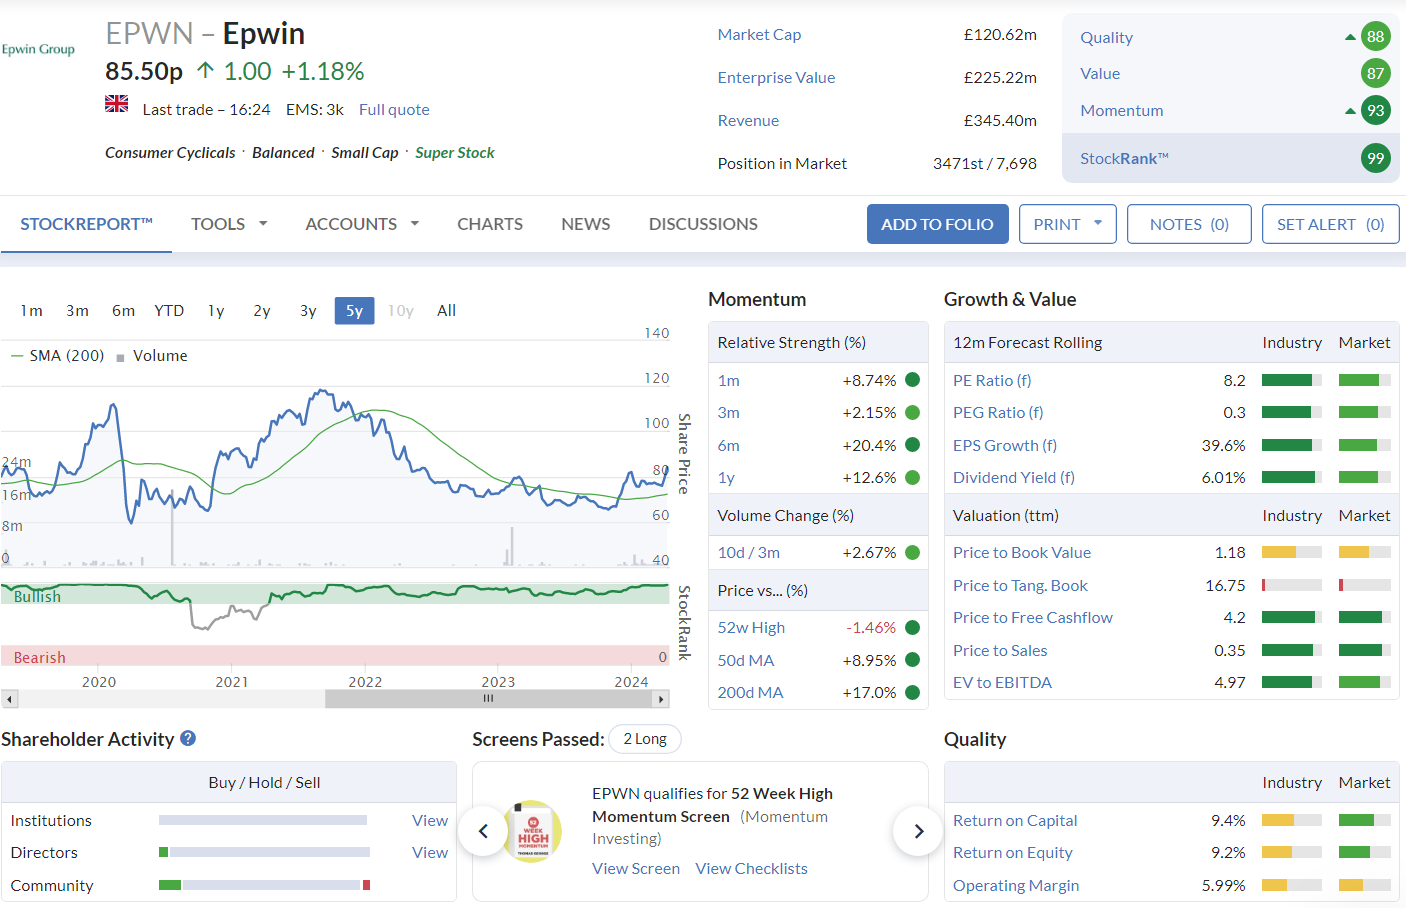
Paul’s opinion - I was previously amber/green on EPWN back on 27/11/2023, when the share price was 71p. I should have been more bold and gone green, as the value was more stark then than it is now it’s bounced 21% to 86p.
It looks as if the market is now anticipating a cyclical recovery, and the chart is looking more encouraging too (not that I’m a chartist, but it’s simple enough to spot a change in trend).
We also now have a slight beat against forecasts for the 2023 results, and an OK outlook statement, and that’s before any cyclical recovery has even started.
So I remain enthusiastic about EPWN shares. I don’t imagine it will multi-bag, but I could see it gaining a decent amount if the sector improves in the next couple of years. And paying a 6% dividend to investors whilst they wait isn’t a bad setup.
Since EPWN shares have always looked cheap, I wonder if the institutional holders might pressurise it to negotiate a takeover deal with private equity, as we’re seeing happening a lot? Takeovers are great, but they need to be at a decent premium, rather than just providing a convenient liquidity event for institutions.
The stock market just doesn’t seem interested in EPWN, and doesn’t give it credit for resilient financial performance in recent years, despite all the macro issues.
Iqe (LON:IQE)
28.5p (£274m) - FY 12/2023 Results - Paul - RED
IQE plc (AIM: IQE, "IQE" or the "Group"), the leading global supplier of compound semiconductor wafer products and advanced material solutions, today announces its results for the full year ended 31 December 2023.
The company’s headline completely glosses over the reality that these figure are terrible, saying -
Strategic progress in a challenging market with a return to growth in H2
FY 12/2023 numbers -
Revenue down 31% to £115m
Adj EBITDA has largely disappeared, down 82% to £4.3m
Adj loss before tax went from £(6)m in 2022, to £(29)m in 2023.
Is it going bust then? Probably not. Adj net debt is only £2.2m, improved from £15.2m a year earlier, so that looks OK. This was achieved through an £29.8m equity raise in May 2023. I suspect that may not be the last equity raise.
Balance sheet - shows £170m NAV, less £35m intangibles = NTAV £135m. Although most of that is tied up in £130m fixed assets - IQE is a capital intensive business, that doesn’t generate any return from the assets it owns. Year after year, the ROCE and free cashflow have been negative.
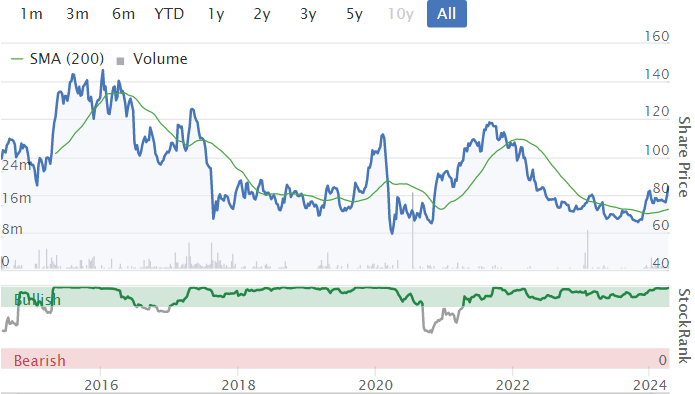
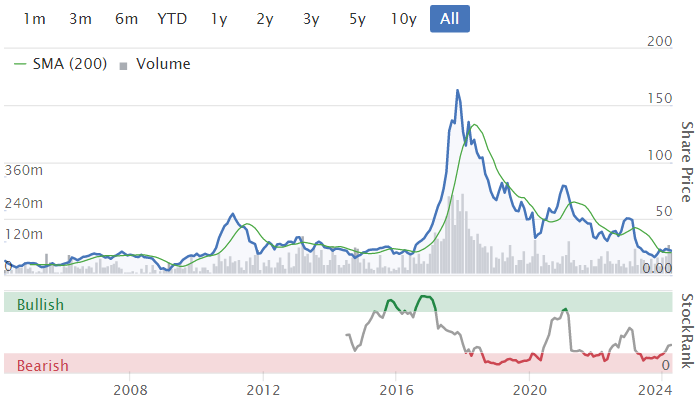
The shares have had bursts of activities when the company from time to time manages to excite investors about its future prospects. Long term though, it always disappoints.
On a more positive note, It highlights a significant improvement in H2 vs H1 -
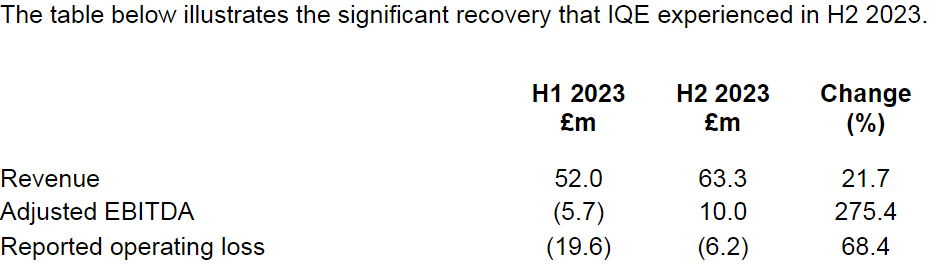
Outlook - it talks about the semiconductor industry now recovering.
Revenue and adjusted EBITDA are expected to be within the range of analyst forecasts for FY 2024 1 .
1. The analyst range of expectations for FY 2024 revenue are from £133.7m to £153.7m and for adjusted EBITDA from £11.1m to £16.6m .
That level of EBITDA is nowhere near good enough, because IQE is a heavy capex spender every year. Hence no real profits (PBT) are likely in 2024 again.
Paul’s opinion - I’ve followed IQE for years, and it’s always disappointed, but seemed to hold out the potential for great things in future, which fail to happen. Profits seemed to collapse in 2018-19, which suggests to me competitors have eaten its lunch since then.
It doesn’t seem to have any pricing power, or competitive advantage, but needs to spend continuously on heavy capex to make products that it doesn’t seem to be able to sell in sufficient quantity or margin to generate any cash overall. That’s why it doesn’t pay dividends.
It’s difficult to see why this company exists. Of course I have no idea what the future holds, but why IQE is valued at £274m, given its lamentable track record, eludes me. Maybe performance might improve in future? We're not predicting the future here remember, just reporting on the facts & figures as of today.
Futura Medical (LON:FUM)
36p (£109m) - FY 12/2023 Results - Paul - RED
Futura Medical plc (AIM: FUM), the consumer healthcare company behind Eroxon®, that specialises in the development and global commercialisation of innovative and clinically proven sexual health products, is pleased to announce its final results for the year ended 31 December 2023 ("FY23").
Revenues have just started, from nil in 2022, to £3.1m in 2023.
Loss before tax was £(6.9)m, which includes a £2.7m charge for share based payments. Remarkable greed there, considering they haven’t even achieved any profits yet, but they're helping themselves to free or cheap shares anyway.
Cash is £7.7m, with it talking about the “cash runway” lasting into 2025 when it launches in the USA. Shouldn’t it be generating cash now, from the UK/Europe launches?
Going concern statement - you have to click through another link to find the full accounts and notes. No wonder they're coy about showing us the figures, as they're bad. Note 2.2 on going concern concludes there is a “material uncertainty” over whether it can survive beyond June 2025 - a big red flag for me.
Paul’s opinion - if this product was a genuine breakthrough in treating erectile dysfunction (as it claims) then of course the shares would go to the moon, and the company would be worth billions.
As mentioned before though, there’s a fairly serious problem - Eroxon doesn’t work! It’s completely useless for most people who left reviews here on Amazon after buying the product. I also mystery shopped it, and it does absolutely nothing, it’s just a placebo. Which is what most reviewers online also say.
Therefore I imagine it’s likely to achieve modest initial sales as customers try it out once, then fail to get much in the way of repeat orders, as most customers abandon it as a waste of money, you can see from customer reviews.
I could be wrong of course, but that’s what all the evidence suggests to me. Hence this one is a bargepole share for me, and I suspect it’s likely to end in disaster for shareholders. Why take the risk, when most customers say the product doesn’t do anything? Ignoring customer feedback isn’t a good way to make money, in my experience - companies that fail often have warning signs all over the internet from dissatisfied customers, as FUM clearly does.
Premier Miton (LON:PMI)
- up 3% to 61p (£99m) - Q2 AuM Update - Paul - GREEN
Premier Miton Investors is focused on delivering good investment outcomes for investors through relevant products and active management across its range of investment strategies, which include equity, fixed income, multi-asset and absolute return.
Company headline -
Stronger environment for mid and small cap stock supports outlook for improving fund flows
Assets under Management (AuM) rose by 9% to £10.7bn in the quarter to £10.7bn
Two thirds of the rise is due to an acquisition of Tellworth Investments, plus a new mandate to manage money for GVQ Investment Funds.
Net fund flows out of the equity funds have slowed to a trickle, only about 1% of FuM in Q2 (Jan-Mar 2024), offset by an impressive 5.5% gain in market performance in Q2 for their equity funds.
Encouraging noises made about small/mid caps - useful info for all of us -
It has also been encouraging to see shorter term performance on an improving trend as market breadth improves and mid and small cap stocks recover…
"The backdrop for active fund sales in the UK retail market has been challenging over the Period, as it has been since interest rates began to rise at the end of 2021. We are now at a point where interest rates are likely to trend lower as we move through 2024 and we believe this will support an improving environment for fund flows and asset values that should particularly benefit Premier Miton.
The only caveat I would add is that Gervais at Miton is a perma-bull on small caps! He’s got to be, otherwise nobody would invest in their small cap funds!
Balance sheet - nothing is said today, but checking its last reported balance sheet at 30/9/2023 it looks healthy. Adjusting out lots of intangible assets and removing deferred tax, I get to NTAV of £37m, which is almost exactly its cash pile. That makes sense, as there’s almost nothing in physical fixed assets (probably just some desks & computers), and trade receivables & payables are both large but roughly offset. All as expected.
With the cash pile being 38% of the market cap, this is reasonably well supported with the best asset: cash.
Broker forecasts - nothing available, but consensus on the StockReport shows 6.21p for FY 9/2024, and 7.66p for FY 9/2025. That would put the PER in high single digits.
Forecast divis of 6.0p suggest a yield of c.10%, which might be a stretch, but given its strong balance sheet liquidity, I can’t see any reason why it wouldn’t be possible to pay out all the earnings in divis. I don’t know what regulatory capital it is required to keep though, that would be the only potential limiting factor. But when a yield is as high as 10%, it’s sometimes best to proceed with caution, and factor in the possibility it might be cut.
Paul’s opinion - we’re starting to see the signs of a market recovery, and fund outflows ending. Those are exactly the pointers that a bull sitting on the sidelines for an entry point would want to see. Combined with a strong balance sheet, a history of generous divis, I think this looks very good.
Not sure why I’ve looked at PMI twice this year, when it’s Graham’s specialist area, probably just because he’s been on day off when PMI has reported! So I’d like to hear his view next week maybe. In the meantime, I’m upping my view from amber/green previously on 12/1/2024, to GREEN today.
It’s worth looking at the whole fund management sector though, as there are plenty of bargains around. I think this seems the right time to be getting into this sector, given the clear (albeit early) signs of market dynamics now improving. It’s very cyclical, and this is looking a lot like a potential cyclical low point.
I bought some Cavendish Financial (LON:CAV) recently, and might see if I can free up a bit of cash to buy some fund manager stocks now too.
Bottom of the cycle, or permanently broken? You decide! I'm inclined towards the former.
Sigmaroc (LON:SRC) - 64p (£711m) - AGM Statement - Paul - AMBER
SigmaRoc, the Northern European quoted lime and limestone group, is pleased to announce an update on its first quarter trading for its 2024 financial year ('Q1' or the 'Period'), in advance of the Annual General Meeting to be held at 12.30 p.m. today…
Started FY 12/2024 well, trading in line with expectations.
Acquisitions - absolutely key, this is a highly acquisitive group, buying up limestone companies across Europe. It says acquisitions are going well. A large acquisition from CRH in the UK has recently completed (announced on 27/3/2024). So it all boils down to management skill in executing, and then managing the multiple acquisitions. Key information would therefore be what is management track record in their previous jobs?
Outlook is unchanged.
Balance sheet - looking at the last one at Dec 2023, it’s very top heavy with physical fixed assets of £573m, and intangible assets of £188m.
Working capital is OK with a current ratio of 1.14, and includes gross cash of £56m.
Long-term liabilities included £201m borrowings, which I think will have risen a lot in 2024 from the latest acquisition. Net debt was £182m, which is a lot, but not excessive when compared with the £117m adj EBITDA in 2023.
NAV was £515m. I’ll adjust this by removing intangible assets of £188m, giving NTAV of £327m, which seems OK.
I’m never quite sure whether we should remove deferred tax too, as often it relates to goodwill. So I’ll leave a question mark over this £72m balance sheet liability. If we removed that as well, then adj NTAV would improve to £399m.
Going concern statement is clean.
Cashflow statement - isn’t great. In both 2023 and 2022, it spent about two thirds of operating cashflow on capex. Cash is also flowing out to fund the multiple acquisitions. £30m equity was raised in 2023, which was used to repay a similar amount of bank debt.
Interest costs are rising, and fairly hefty at £14.5m in 2023.
Dividends are negligible at only £1.3m.
The key question is therefore what is the nature of the capex, since that is consuming most of its cashflows. If these are say one-off improvements to worn-out equipment that came with the acquisitions, and won’t repeat, then fine. If however it’s an ongoing heavy spend required just to keep its facilities running, then not so good. That would be a key question to ask management - what is the split between expansion, and maintenance capex?
Paul’s opinion - I’m struck by the very rapid growth at SRC. Its 2023 results showed £71m adjusted PBT on £580m revenues, so lime seems to be a lucrative area. Big adjustments though, with statutory PBT being much lower at £28m.
This is certainly an ambitious project, building up a substantial group from a very small starting position just a few years ago.
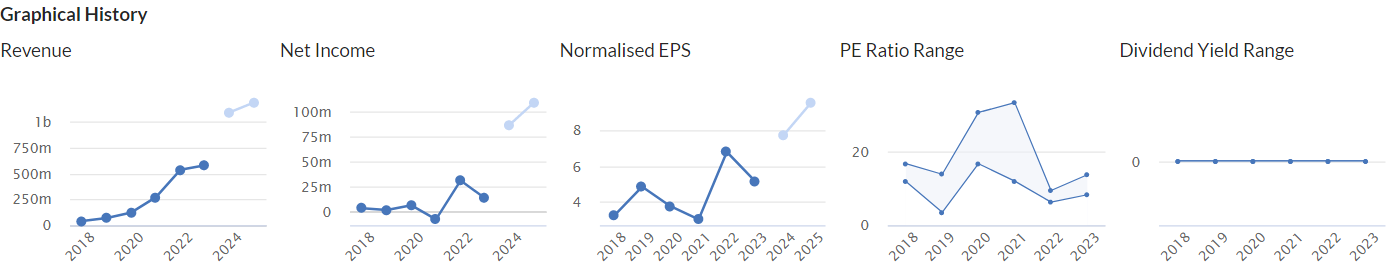
Although I question whether it has actually created any shareholder value yet? There have been no divis, fair enough it’s focusing on growth. But the share count has ballooned to fund all this expansion (with a fair bit of debt on top too)
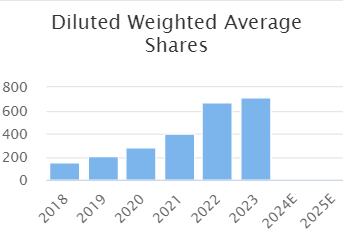
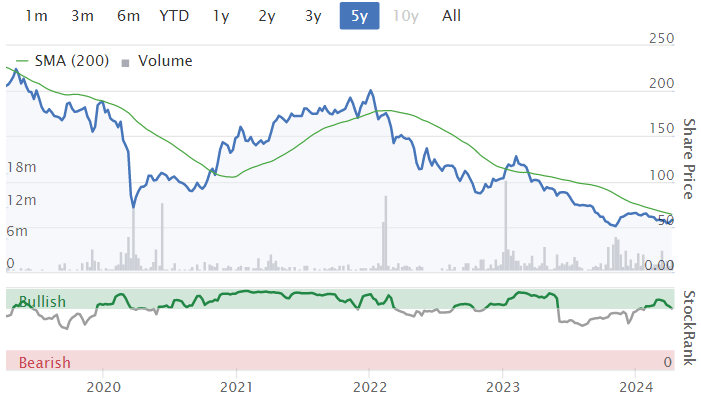
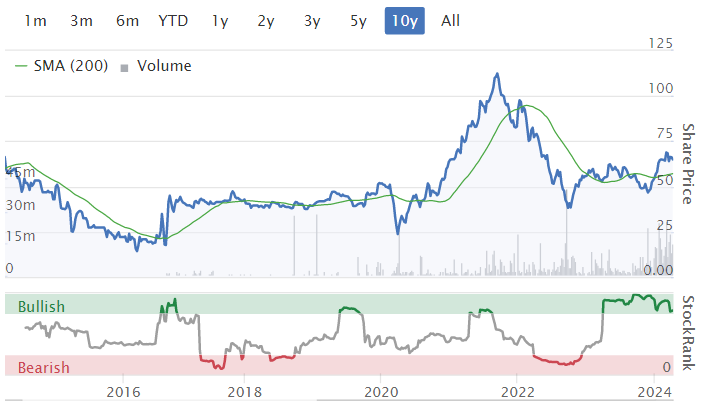
The latest figure is 1.11bn shares in issue, a more than 7-fold increase in share count since 2018. The litmus test of shareholder value is the share price itself, which doesn’t impress over a very long 10-year horizon, with no divis remember either -
Looking at Liberum (many thanks) research, I can see that if SRC achieves its growth targets, then EPS of 9.8p in 2025 and 11.3p in 2026, with very high net debt at end of 2024 (£580m) but falling to £351m by end 2026, might justify a higher share price.
Since I know absolutely nothing about lime, other than I particularly like the fruit in my drinks, then I cannot possibly determine how this share is likely to do in the future.
So it’s no opinion from me. Hopefully the above has been a useful review of its finances for you.
In summary - very rapid growth via multiple acquisitions, capital-intensive business, funded through lots of dilution and taking on a substantial amount of additional debt in 2024.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
If wondering about Market reaction to the dangerous escalation in the Middle East, this link on Gulf Markets reaction today , and extent of the falls so far, might give a guide:-
https://www.reuters.com/world/...
Any thoughts yesterday on the 6% drop late on Friday for Investec (LON:INVP) . Took me by surprise especially after their 11 month impressive TU a month or so ago?
On Beach group (LON:OTB) - Personally I think there is more opportunity with easyJet (LON:EZJ) i think they with be taking a lot of market share through their new holidays business which generates higher margins.
Hope so anyway as I've been topping up in the run up to the trading update on Thursday
I'm still holding on to my On Beach group (LON:OTB) stake in the Boon Fund; think there is sufficient momentum (company as well as holiday market) to see them through to a 200p+ share price.
It could definitely be some of the names mentioned (Jet2, TUI, Easyjet) are better holdings than OTB - I haven't in-depth researched those companies yet. Certainly, I am keeping a watchful eye on the competition they offer, as they have all upped their investment/game in the holiday package space, in direct competition with OTB.
Meanwhile, happy to hold OTB as I think 200p+ is achievable in a 6 month timeframe, and so I'm content with tying up my capital here for a possible 25% gain on top of the 20% I've already had so far, since buying under a year ago in May23.
Sigmaroc (LON:SRC)
Hi Paul,
I don't disagree with your summary, but this is a situation where one has to trust management. I have Max Vermorken, CEO and the management team, including Chairman and co-founder David Barrett on a couple of occasions. In my experience they come across as upfront, competent, ambitious and to date have always been prepared to engage with retail investors.
Dave Barratt has significant experience in the industry having co- founded London Concrete in 1997 growing the business from one concrete plant to 12 before it sale to Aggregate Industries in 2014, or thereabouts.
The recent substantial acquisition of assets from CRH once fully integrated should significantly increase free cash flow and as you reference allow the debt burden to be reduced considerably over the next couple of years.
I accept that the company's buy and build strategy involves several potential risks including over stretching the balance sheet, overpaying for acquisitions or failing to successfully integrate them. I hold and am prepared to back the management team, unless circumstances change
Many thanks to you and Graham for the quantity and quality of the reports that you produce on a daily basis. I find them an invaluable aid to my investment decisions.
Enjoy the weekend
Futura Medical (LON:FUM) was the first investment I ever made back in 2019, I went all in with my 50k portfolio seed funding, this was in the run up to clinical trial results being announced…which came back negative (it didn’t work). I ended up losing 25k when I sold up and crystallized my loses at 11p. Three valuable lessons learned, 1) cut your loses (portfolio subsequently nicely recovered) 2) sell before the clinical trial or exploration well drilling results and 3) don’t invest in d1ck rub stocks - if it sounds too good to be true it probably is
For those with shares in frasers owned by Mike Ashley the below article may be of interest
Retailer Game laying off staff and offering them their jobs back on zero hour contracts
https://www.ign.com/articles/u...
Renold (LON:RNO) making a significant move today with rising volume (not massive but increasing). Could simply be that the sellers are now exhausted. Last year Renold (LON:RNO) gave a trading update about this time. Maybe the market is expecting good news? Possibly wishful thinking! SP currently held at the 50dMa. Will be interesting to see if it can break through this. (I hold).
ECOR resources Bowl FUND versus Impax BLAME fund
7% gain in first week of holding . Might be in to something here .
Might have timed one right reckon will be up to a quid in pretty short order .
Only took a third position as wanted to scale in .
“Bowl fund” current leading the “blame game “ fund .as Impax down 4%.
Luckily blame game fund is more for fun so don’t worry about it .
Have you looked at Frontier Developments (LON:FDEV) for bowl fund?
Synthomer (LON:SYNT) is similar.
Having read Paul's analysis I wouldn't buy this share. What is the point in expanding taking on debt and diluting shareholding with no dividends and all this over a long period . I also think PMI is a much better buy for the reasons he outlines and think that the poor cycle in that sector is almost over.
What share?
What share?
I’m guessing Sigmaroc (LON:SRC. Everything that was said is true, yet I’m a recent buyer, albeit at last year’s price.
Does anyone know what has caused the 4% turnaround on Jet2 (LON:JET2) today? It sold off bigtime around 1:40 which makes me think something over the pond may have influenced the sell off. (I hold)
Price of oil? On Beach group (LON:OTB) are down also. Oil shares are up.
I think you are right Rusty. Cheers.
Took a look at On Beach group (LON:OTB) this morning to see how it had done, following all the enthusiasm at the beginning of the year, but looks like it's still in the departure lounge.
I got lucky with On Beach group (LON:OTB) last year, my best performer overall. I sold out (very fortunately at over 170p) simply because the product is actually quite awkward to use and a bit shit compared to its competitors. It's not easy to book with them and they always want you to call them. The calling part alone puts off a lot of customers, myself included. My last two holidays I went with TUI AG (LON:TUI) and Jet2 (LON:JET2) and I personally believe they are in a league of their own. Very hard to pick fault in either company. I used my On Beach group (LON:OTB) to buy stakes in Saga (LON:SAGA) and Jet2 (LON:JET2). Safe to say I should have just loaded the cart with Jet 2!!
Great write up as always Paul! Thank you for your hard work!
https://www.stockopedia.com/co...
On a quiet Friday this would seem to be a very positive indication of where we are.
FCA investigation into motor finance firms gains momentum.
Not new news but could it be a bigger problem than first realised? PPI Mk 2?
"The UK's financial watchdog has warned motor finance firms to hold back cash for potential payouts as it continues an investigation into the sector.
The Financial Conduct Authority (FCA) also revealed that firms "are struggling to promptly provide" data for the probe.
About 17,000 people have made already made complaints to an ombudsman."
and
"In February, banking giant Lloyds said it had set aside £450m to cover the potential cost of the investigation.
Lloyds is seen as the most exposed of the major banks to any claims as it owns one of the UK's largest motor finance providers, Black Horse."
Source: BBC https://www.bbc.co.uk/news/bus...
Centaur Media (LON:CAU)
I hold
I have revisited the recent prelims and watched again the views of Chris Mills and Richard Staveley from the latter end of last year in the interviews on Vox Markets. The Harwood stable holds close to 30% of the company and Richard Staveley is a non executive director, so it stands to reason that their views may be tinged with a little bias. However you would be hard pressed to name two more astute investors in UK small caps.
My original purchase price is 40p or thereabouts. At that price Centaur Media (LON:CAU) when one considers all the investment metrics is cheap. It also has £9.5m on its balance sheet, although how much is its own as opposed to clients I am unsure. Even after the spike to around 52p, the shares in my view are hardly expensive.
There is significant value in the Lawyer, a must have for the legal profession and the e-learning mini MBA course. Harwood is a long term investor and has held Centaur Media (LON:CAU) for a considerable period. The turnaround at Centaur Media (LON:CAU) over the last 3 to 4 years is now complete and Chris Mills and Richard Staveley will be looking to realise the value and exit, provided an sensible agreement can be reached on price. They will naturally want to maximise the sale price, but I suspect that they are also pragmatic and will not look to overly 'squeeze the lemon'.
There is also the possibility that other potential suitors may emerge, now that the company is in play
I have no insight into whether the current preliminary approach will result in firm offer, but my best assessment is that it will, possibly pitched somewhere between 65p and 70p. I have therefore added modestly to my holding this morning at a smidgeon over 52p.
If I am wrong and a bid is not forthcoming I will pick up the 1.2p dividend and the shares will likely fall back to around 40p.
Interesting times!
I have also held Centaur Media (LON:CAU) for some time and I would think you have got your assessment spot on, Jonno. I am hopeful (and confident?) that between 65-70p is achievable as an exit price here, so the market has probably priced it about right for now for such a preliminary approach.
I think the interesting point here is that Centaur have broken cover and put out a statement at such an early point in negotiations. This might turn out to be a great tactic if trade buyers emerge at the sight of the 'for sale' sign, but not so good if Waterland remain the only bidder in town. Overall, a strong hold for me and maybe a decent short-term speculation for anyone not in already?
XP Factory (LON:XPF) any holdings left? Well, massive news just now. Cannacord has just dumped 45million shares (c.25% of market cap) in two orders. This may have been holding the share back? Thoughts?
Hi SGTA, thanks for flagging the large trades in XP Factory (LON:XPF) both printed as 23,674,420 at 12.75p. It could be a large holder moving stock around, but that usually has to be within the day's price range of other printed trades, to avoid investigations of tax evasion by under-pricing shares. So as it's below the day's price range, I'd say this big trade could be a disposal by a large holder, and we'll have to wait and see who the buyer is.
Looking at the >3% list on XPF's website, there are only 2 holders capable of dealing in that size, Canaccord or MFT Capital. Since the last 3 digits of the trade are 420, then at a guess I would say this is more likely to be MFT Capital selling almost its entire stake.
I doubt this has had any impact on the share price, as institutions sell blocks of shares to each other, they wouldn't be going through market makers, so it wouldn't move the market share price at all normally. i.e. there would have to be both a matched buyer and a seller for trades of this size, so doesn't affect the open market price.
If a big block has changed hands, and isn't just a holder doing an internal move, then it will be interesting to see who has bought them - Luke Johnson maybe?! He seems active at the moment in the sector.
Was out all day and just seen yesterday's SCVR. Nice to read the 2 year update on Corero Network Security (LON:CNS) Paul, thank you. If you haven't already watched it, on 3rd April I commented on the Equity Developments post and video interview link. Still well worth watching although price is now 25% higher.
(Still my largest holding - but some of my previous largest holdings haven't worked out well in the end!)
I note that Paul comments in the context of Epwin about Private Equity taking certain public companies out at higher premiums. Of course there are factors at work. First unlike private companies there is already in the share price an inherent multiple so it would take certain persuasive qualities to pay a large premium over that. Secondly management are often persuaded to roll over some or all of their share/option interests into the new vehicle and if they see future growth they may feel too much of a premium steals some of that potential gain on their rollover and their future interests.
On Churchill China (LON:CHH) I am also puzzled why it trades at such a high valuation. Would love to hear thoughts!
Admittedly, I've never done an in-depth analysis of the company, but my limited understanding is that they mainly provide to the "trade"? ie restaurants, hotels, etc?
I remember they struggled during COVID (due to less eating out, less hotel stays). But with hospitality having a full recovery already, H2-22 and CY-23, surely demand should be brisk? New tableware for new openings, replacement cycles of old tableware?
So the fact that trading is struggling and soft... suggests maybe a company-specific issue rather than market?
Keen to hear thoughts.
Boon, on Churchill China (LON:CHH), I think I read in the RNS that weak demand is due to high failure rate in casual dining currently
IQE "It’s difficult to see why this company exists."
I think it gets funding from the Welsh authorities, which want to see it succeed. It employs people, for example.
WalesOnline published an article back in 2019: "What has £33m of public money sunk into struggling technology firm IQE achieved?"
https://www.walesonline.co.uk/...
"[Coouncillor] Coun Boyle said he "hoped" IQE would find a market for its products." [Emph mine].
As the saying goes, "hope" is not an investment strategy.
"The due diligence around the process has been robust."
In other words, we don't really know what we're doing but we generated a lot of paperwork doing it, so it must be fine.
Premier Miton (LON:PMI) Q2 AuM update
£10.7bn up from £9.7bn part of that is £560m from acquisition of Tellworth Investments, £268m outflows, so a slight improvement to AuM from fund performance.
Shoe Zone (LON:SHOE) dropping quite a bit over the last few weeks presume it’s due to concerns about the rise of Shein….
Not really Stay Humble,
The AGM statement at Shoe Zone (LON:SHOE) said that slower end to Autumn winter range combined with increased min wage and increased fit out costs meant they were marginally behind expectations. When the broker research came out it was over 5% so the term marginal felt a bit disingenuous.
Having just been tipped in the Mail (I think it was them) this change in expectations plus a large dividend which knocked 15p off the share price combined to bring the stock down towards 225p. Since then you’ve just had a dribble of small shareholders selling - presumably stale bulls from the Mail tip. Then people were trying to read across from a Poundland profit warning.
Shoe Zone (LON:SHOE) - so, a good entry point do you think?
Who knows docj - Shoe Zone (LON:SHOE) feels cheap to me medium term on a PER of some 8 to 9* particularly given its strong net cash position ( ignoring leases). Decent dividend - what is it around 7% now?
Think their Big Box strategy is probably the right one longer term too - they need efficiency to offset rising min wage labour costs.
Shoe Zone
Looks about right to me.
OK but average business .
Buys cheap shoes from China and sells them for more than they pay.
Unremarkable shops .
OK shoes at good prices
No moat at all.
Rising wages and possibly higher shipping costs going to nibble at profits .
Fundamentals are sound and management are ok .
Yet another simple business model buying Chinese products and reselling through their UK network .
Nice wheeler dealer Del Boy type business that sells for stuff for more than they pay which is one of most successful ever business models in history .
At risk of a rival entrant but so are most similar UK companies selling unremarkable Chinese products that almost anyone can buy .
Hard to see much growth but should keep on rattling out its ok numbers .
A well known investor who runs an investor subscription service sold their position yesterday. Subscribers may well have followed suit and sold theirs too
*I hold Shoe Zone (LON:SHOE) & saw it as an opportunity to add a few more. Management know their business, have large personal holdings and it pays a decent dividend
So the US inflation data did not play ball. Jobs data remains intact. ISM data is improving. Equity markets shrugged. The UK market hardly budged...this is interesting. At the year end you have one CPI no but all year its ticking up and down...mainly up at the moment. The point here is the single number doesn't capture the volatility along the way. As the data isn't playing ball, the rate story has evaporated. Therefore the perceived beneficiaries of lower rates are suffering again. This is setting the market up for rotation.
Commodities are strengthening. Gold is front page...copper is on a charge...platinum silver etc are following. Normally this is good for industrial stocks. For me, they fit a nice narrative of investment in infrastructure and energy transition anyway. These trends will be good for the UK market. The UK has lagged the US again as YTD the mag7 stuff has rolled on. I think of this as semi defensive trend and with the recession not happening for now....and data picking up....there seems scope for investors to rotate to real economy stocks. So maybe the UK closes the gap with the US....
In the main, despite recession fears these stocks have been reporting solid order books and ok growth.... we all have our favourites but the UK market has a decent engineering sector. I bought Weir (LON:WEIR) and am watching Hunting (LON:HTG) at the moment. Both solid.
As we drift toward H2 you need one eye on all the elections. Again it has been said that the UK could come out well. We are expecting a change in govt but it's a centrist change and could compare well to the US and EU. So we may move from political discount of the last few years to relatively stable. Never the less elections bring volatility and a little cash on the side lines is nice to deploy if things go wonky.
Ive done v little personally. I have some large positions that have been giving back (Uranium) or just a little out of favour on no news (BT (LON:BT.A) (Serica Energy (LON:SQZ) ) or waiting for progress on turnarounds (Sherborne Investors (Guernsey) C (LON:SIGC) Volvere (LON:VLE) .... running very focussed means you can be down when the markets up...but hopefully things look better sooner rather than later. I still think it's an opportunity rich market and this is a great forum to focus on stocks rather than all the macro concerns ....
Good luck all
Morning Paul, just to say thank you for your morning reports which I try to read on a regular basis. Im not sure about the rest of the stocko community and how many accountants out there but for me your company reviews are priceless, with every day I keep learning something useful about the intricacies of companies reporting. Thank you!
How kind, thank you TGP20! :-)
My morning smallcap tweet: One bad Tern deserves another
Tern (LON:TERN) Roadside Real Estate (LON:ROAD) R&Q Insurance Holdings (LON:RQIH) Petrofac (LON:PFC) Huddled (LON:HUD), Sigmaroc (LON:SRC)
◄Tern (TERN)► £420k placing at 2.4p, a 30% discount, for a measly 4% of cap. Cash is to funds to invest in Wyld Networks and keeping the lights on. [SP=3.48 Cap=14m]
◄Roadside (ROAD)► delays FY-Sept results to perhaps end Apr. Blames senior personnel compassionate leave. [SP=8.2 Cap=12m]
◄R&Q Insurance (RQIH)► guides FY-Dec significant pre-tax loss: "R&Q Legacy is expected to realise adverse development of ~23% of the Group's net reserves." Includes $64.2m identified at H1. JV partner to buy out R&Q JV interest in Sag Main for $27m plus $3m of preference shares. [SP=5.1 Cap=19m]
◄Petrofac (PFC)► remains in talks on d4e, a possible placing and sale of non-core assets. Why the 15% rise yesterday? [SP=33.32 Cap=177m]. I'm short.
◄Huddled (HUD)► buys online retailer Food Circle Supermarket for up to £300k. £100k cash plus £50k shares up front. It had FY23 rev £1.4m and loss £46k. [SP=2.55 Cap=8m]. I hold.
In line: SRC
Mystery shopping Futura Medical (LON:FUM) 's
(not so hard) core product! Are there no lengths to which our highly esteemed analyst will not go? Great work Paul.
Oh dear, I was trying to avoid innuendo this time.
Perhaps a bigger sample size is needed.
*removed* hadn't seen docj's post!
Futura Medical (LON:FUM) if it did produce a bargepole there would be no need for the big red flag.
Office for National Statistics figures show the UK economy grew by 0.1% in February
And an upward revision for January from 0.2% to 0.3% .
I remember back in 2022 or there abouts that Boris made a lot of noise about the UK outperforming the EU growth figures and Brexit was the best thing that ever happened. - He was not making so much noise a month later when they found the data was incorrect and the UK was actually well down the growth table.
I now see they (ONS) have voted to go out on strike because they are being asked to come back to the office two days per week due to inefficiency and the inaccuracy of data caused by working from home !!
Would make you wonder about the accuracy of the recent figure of 0.1% growth. !!