Small Cap Value Report (Fri 12 Jan 2024) - W7L, WTB, GYM, GHT, VTY, PMI

Good morning from Paul! Today's report is now finished. Have a great weekend!
I prepared some sections last night & early this morning, to get us off to a flying start.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
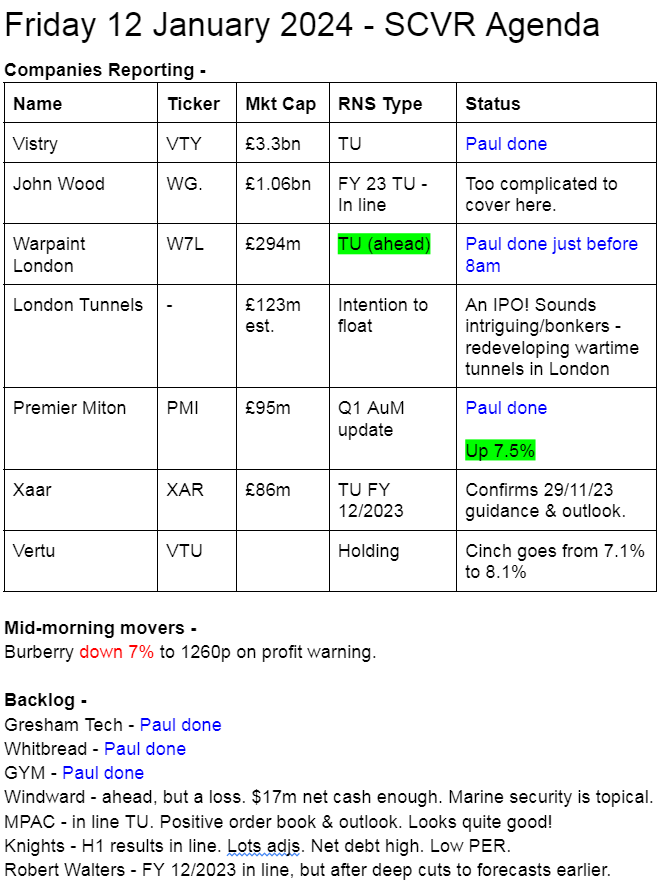
This star performer once again beats forecasts, with another upgrade. I crunch the numbers below, and reiterate my very positive stance on this rapidly growing make-up company, that seems to be in a long-term uptrend for profits.
Whitbread (LON:WTB) 3632p (£6.8bn) - Q3 Results [in line] - Paul - GREEN
One of my favourite mid-caps, so I've reviewed its Q3 (Sep-Nov 2023) update below, which is in line. I run through the reasons why I like this decent margin, growing, securely financed, and reasonably-priced hotels/hospitality group.
GYM (LON:GYM) - 106p (£190m) - Trading Update - Paul - RED
Talks up its performance, but it's still loss-making, with improved KPIs on membership being absorbed by higher staff & energy costs. We just don't see a particularly viable business model here, unless performance can be drastically improved. Debt down a bit, but still too high.
Gresham Technologies (LON:GHT) - up 3% to 120p y’day (£100m) - FY23 Trading Update - Paul - GREEN
One of my top 20 share ideas for 2024, which put out a reassuring, in line update yesterday, with upbeat outlook comments. As explained below, it looks like I picked up an incorrect broker forecast figure, so it's not actually as cheap as I previously thought. Overall though, I'm still happy that it looks reasonably priced, with potential upside, so I'm happy to stay at green.
Vistry (LON:VTY) - up 3% to 995p (£3.4bn) - Trading Update - Paul - AMBER/GREEN
It's a slight beat against (lowered) guidance for FY 12/2023. A very detailed update, which I've summarised below. I like its differentiated housebuilding model, doing larger developments for third parties such as local authorities. This seems to cushion it somewhat from the downturn in private housing sales. Generous divis & buybacks are planned. Looks good, but c.50% recent rise means I'll only be watching, not chasing the price up any higher, for now.
Premier Miton (LON:PMI) - up 8% to 65p (£102m) - Q1 AuM Update - Paul - AMBER/GREEN
Q1 (Oct-Dec 2023) assets under management (AuM) rose 3%, thanks to favourable market movements. Although clients were still net withdrawals of about 2% of AuM. I run through the numbers, and conclude that this share looks cheap, and could have recovery potential. We like the whole sector actually, with bargains galore, if a cyclical recovery does gather strength.
Paul’s Section:
Warpaint London (LON:W7L)
382p (pre-market) £295m - Trading Update [ahead exps] - Paul - GREEN
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, is pleased to announce a trading update for the year ended 31 December 2023.
Strong trading performance continues and results for the year ending 31 December 2023 now expected to be ahead of market expectations
Revenue guidance is now £89.5m (up from >£85m) for FY 12/2023.
Gross margin is up on LY.
Profit before tax (PBT) guidance raised to £18m+ (up from previous guidance of £16m+), and also massively up on £7.7m LY.
Cash is up, to £9.0m (LY: £5.9m), which is a clean number, as there is no financial debt.
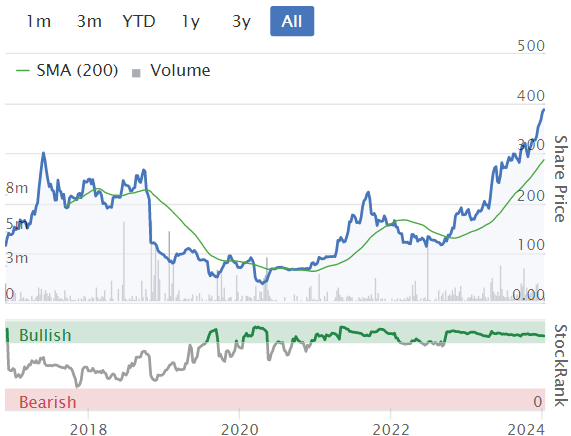
Paul’s opinion - remains highly positive, we’ve been raving here about W7L shares for a long time now. It’s a great, and really simple, scaleable business model - selling good, value make-up products into increasing numbers of large retailers, globally. The products sell well, so the retailers order more, and increase the number of stores they’re in. Production is outsourced. W7L sits in the middle, and collects in rapidly growing profits.
Shore Capital updates us (many thanks) with a 12.5% upgrade to 18.0p - so a PER of 21.2x - which I think is fully justified, given the outstanding growth, consider this earnings progression -
FY 12/2021: 7.8p adj EPS
FY 12/2022: 11.2p adj EPS
FY 12/2023: 18.0p adj EPS
Forecast FY 12/2024: 18.6p adj EPS - why would growth almost stop?!
Forecast FY 12/2025: 20.5p adj EPS - again, only very modest forecast growth.
There are no outlook comments today, but I’ve not come across any reason as to why W7L would see its profits suddenly stop growing. So it seems to me that we should maybe be ignoring these forecasts, and instead making our own guesses, of possibly up to 25p EPS in this new year FY 12/2024? Then perhaps 30-35p in 2025? That’s just extrapolating out the existing growth trend.
If that positive scenario plays out, then this share could be heading up to the 500-600p range I would say, and more longer term? As always though, there are no guarantees that a positive scenario will definitely play out. Something could go wrong.
Overall though, sticking at GREEN is a no-brainer for me. Just wish I’d bought some when we first spotted the opportunity here back in 2022! Never mind. Well done to holders, it’s good to see people making a bob or two!
Whitbread (LON:WTB)
3632p (£6.8bn) - Q3 Results [in line] - Paul - GREEN
Whitbread is one of my favourite mid-caps, which we looked at twice in 2023, turning positive as the figures & valuation became more attractive -
SCVR 22/6/2023 3355p - AMBER - Good TU & outlook. Expensive at 19.7x PER.
SCVR 19/10/2023 3366p - GREEN - Superb H1, adj PBT up 44%. Strong balance sheet. Better value now at 16x PER.
Whitbread’s business is now Premier Inns (revenue: 94% UK, 6% Germany), but it includes branded bar/restaurants within this, as they are either in, or next door to Premier Inn sites, according to the 2023 Annual Report, which I’ve just been reviewing. Note 3 shows that of the £2.63bn revenues for FY 2/2023, 72% was hotel accommodation, and 28% was food, beverage, and other.
I think WTB is a very good business, with decent quality, but affordable hotel rooms, and the food/drink offering is also very good, in my experience. Overnight stays include unlimited buffet breakfast - a key point for me when I’m travelling! There’s one just round the corner from me here in Bournemouth, so I might mystery shop it for an overnight stay, as it’s only £58 including breakfast.
Premier Inn is the UK market leader in budget hotels, and scores way above others for quality/price/value. It has 849 UK hotels, and is seeing a structural growth opportunity from the exit of independent operators, of which c.70% premises have been sold and re-purposed, taking capacity out of the hotel market (especially over the pandemic). The UK is under-supplied with branded hotels, hence why Premier Inns is doing so well, with a lovely strong profit margin - forecast FY 2/2024 revenues c.£3.0bn, and net (after tax) PAT £419m.
The extensive multi-year TV advertisements stick in peoples’ minds for many years - there’s an argument that previously heavy ad spending is an intangible asset - this TV ad was 16 years ago for example, but I still remembered it enough to look it up.
?si=19Agcv9n1Db_VJPc
Premier Inns is also expanding in Germany, but that’s loss-making for now. The expected move into profit, as it continues to expand, will of course have a favourable effect on the group results in future. It says that longer term, Germany has the same potential as the UK market for Premier Inns, on top of further gains in UK market share. So nice growth potential here for sure.
Unlike GYM (LON:GYM) , Premier Inns has made a commercial success of a value for money customer offering, so it’s a proven business model, being rolled out further.
Going through its accounts, WTB is very well-financed. Slightly over half its hotels are freehold, with book value of £3.65bn.
The pension schemes look fully funded, but still with some company guarantees.
There’s a big cash pile, mostly offset by bonds (which are now cheap, as issued when interest rates were much lower). So it has ample funding to continue expansion, and could be geared up, if private equity decides to bid for it.
NTAV was £3.74bn when last reported on 31/8/2023. The market cap of £6.77bn gives it a healthy price to tangible book of 1.81x so there’s strong asset backing here.
Stockopedia shows a ROCE of only 6.4%, but the last annual report shows 13%, so there must be some difference in how that’s calculated.
Occupancy levels have bounced back to pre-pandemic.
Staff costs are 30% of revenues, so April 2024’s living wage increase is likely to be a nasty headwind, as with all hospitality businesses, but that will be factored into the guidance.
Large share buybacks are underway, the share count now having fallen from 203m to 186.5m.
Broker forecasts have been significantly rising -
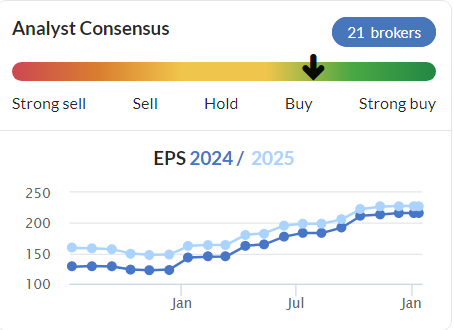
Stockopedia has the forward PER as 16.0x currently, which I think is a fair price for a growth company with a strong market position, and a high profit margin.
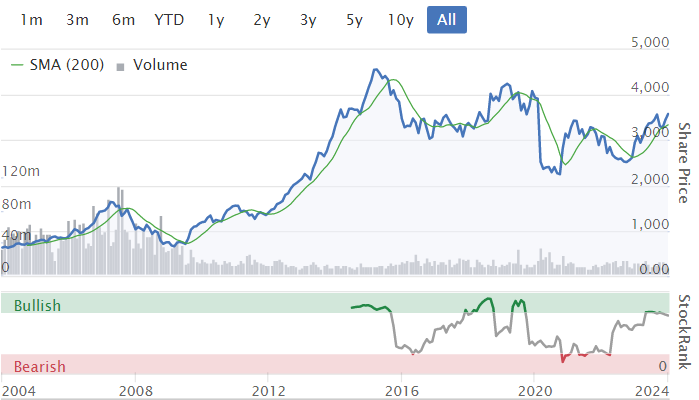
Shares were a star performer until 2015, but have only gone sideways overall in the last 8 years. Although divis of roughly £1 per year do increase the total shareholder return, if manually added on top of the share price.
On to yesterday's update -
This sounds in line with expectations, and makes positive noises about the new year FY 2/2025 -
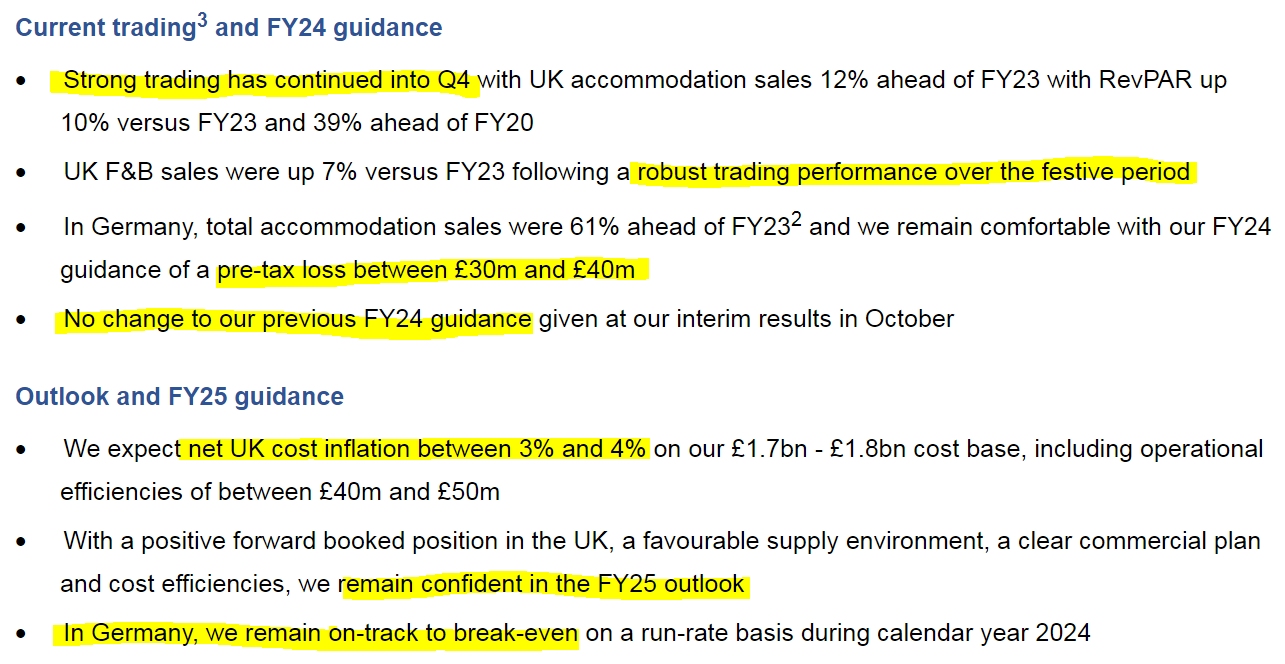
Paul’s opinion - as you’ve probably gathered, I think Whitbread looks a very good share. I like that it’s strongly asset-backed, with secure finances.
Also I like the high profit margin, and structural growth from new site openings (self-funded), declining independent competition in an under-served market with buoyant demand, and German expansion set to move from losses into profit.
This strikes me as an ideal share for a long-term no tinkering portfolio.
Personally I’m reluctant to buy any after the strong recent run, but it’s on my watchlist as the type of share I’d want to buy if some market fall or general crisis causes it to sell off.
Downside risk? The only thing I can think of, is if we have another pandemic & lockdowns. Travel, and hospitality shares are vulnerable in that regard, so maybe they should have permanently lower valuations?
GYM (LON:GYM)
106p (£190m) - Trading Update - Paul - RED
The Gym Group was a pioneer of the low-cost gym model, and now operates 233 high quality sites across the UK. These gyms offer 24/7 opening and flexible, no-contract membership.
… is pleased to announce that the positive trading trends highlighted in our H1 results have continued throughout the remainder of the year, resulting in good growth in both membership and yield…
It talks up the positives, but the end result is trading in line with expectations - which is a forecast loss -
We have delivered good growth in both membership and revenue which will underpin FY23 results in line with guidance
It sounds like extra energy and wages costs have absorbed the upside from more members and higher revenue per member.
I can’t find any broker notes, so the only data I have is the consensus of 6 brokers, which shows a sorry tale of continuing losses -
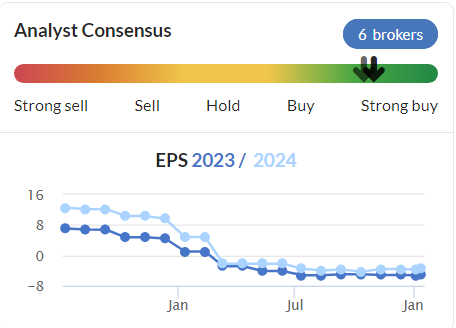
Net debt has come down a bit - but is still high for a loss-making company - the danger is that they might have to curtail capex to enable debt to fall - or breach bank covenants, if profit performance continues to deteriorate? We have to think about interest cover covenants these days, not just EBITDA cover.
Net debt as at 31 December 2023 was £66.4m, compared with £76.1m at 31 December 2022. The reduction reflects strong working capital performance and the timing of spend on new site openings and other capital expenditure projects.
As anticipated in our previous guidance for FY23, revenue growth has offset utility-driven cost inflation and leverage2 is expected to remain within the range of 1.5 to 2.0x.
2 Calculated as Non-Property Net Debt : Group Adjusted EBITDA Less Normalised Rent
Paul’s opinion - checking our previous reviews, usually from Graham, we’ve been consistently negative at red, because GYM has so far failed to return to pre-covid profitability, and still has too much debt.
There’s nothing unique about low cost gyms, plenty of other companies do the same thing, it's difficult to make money.
ROCE was low pre-pandemic, and is negative now. It strikes me as a not very good business model - expensive sites to rent and equip, then not charging customers very much to use them.
It’s already achieved scale, with 233 UK sites, so there won’t be any significant further improvement to margins from opening more.
I just don’t see the point of this business, from an investment perspective.
Performance would have to dramatically improve to make it something I’d want to buy shares in. So I’ll stick with RED.
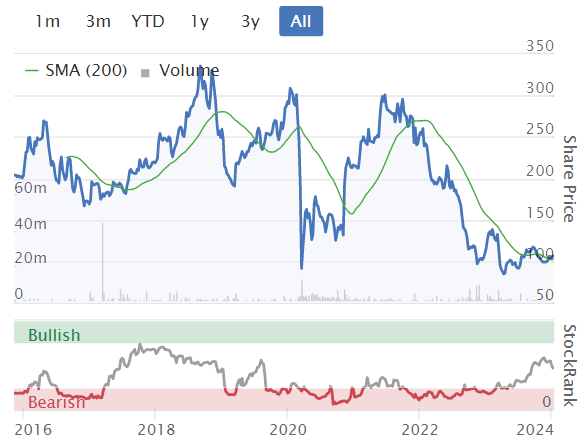
There could be a trade in this, for a rebound, but on fundamentals, we think it's weak - also note the share count has gone up from 129m to 179m shares in issue over this period -
Gresham Technologies (LON:GHT)
Up 3% to 120p y’day (£100m) - FY23 Trading Update - Paul - GREEN
Gresham Technologies plc (LSE: "GHT", "Gresham", "Group", "Company"), the leading software and services company that specialises in providing solutions for data integrity and control, Sbanking integration, payments and cash management, is pleased to provide a trading update for the financial year ended 31 December 2023 ("FY23").
Growth in strategic subscription business driving recurring revenues and enhanced profitability
It reports a “strong close to the year”.
Unfortunately, the reporting below uses EBITDA (two different versions!) -
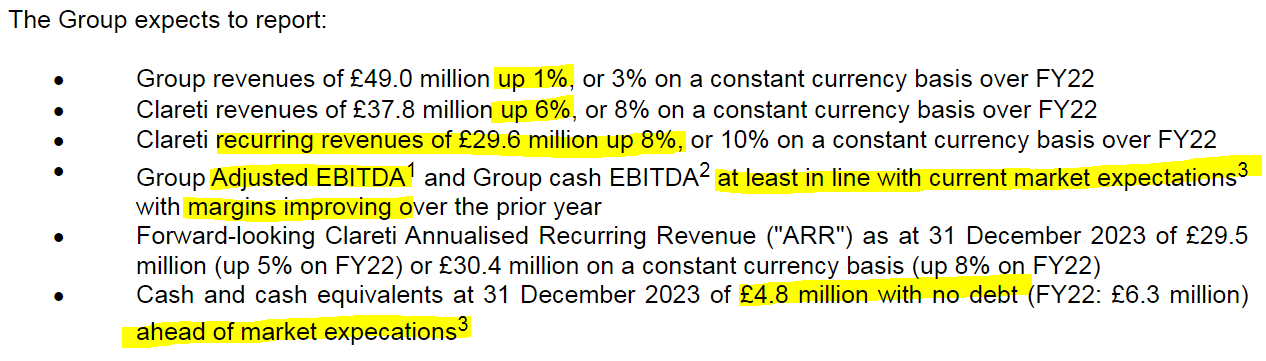
3 The Company believes that current market expectations for the year ending 31 December 2023 are Group revenues of £50.2m, Group adjusted EBITDA of £11.0m and Group cash EBITDA of £4.6m.
Let me add the missing information we need. Singers (many thanks, for note 17/11/2023) has adj EBITDA of £11.0m, and it becomes adj PBT of £7.4m, and adj EPS of 7.7p (slightly up on 7.5p in 2022) - a PER of 15.6x, which is higher than I thought it was.
The forward PER of 12.0x on the StockReport seems to be based on a FY 12/2024 EPS forecast of 9.66p, but that doesn’t tie in with Singers’ 2024 EPS of 7.0p.
So it looks like I might have dropped a clanger here, and relied on an out-of-date or incorrect broker forecast on the StockReport. I’ve flagged it on the green blob, asking the team to challenge the 2024 forecast with the data provider. The fwd PER would be 17.1x using Singers 2024 forecast, which is not especially cheap, although it’s still pretty good for a high recurring revenues software business, which are often more highly valued.
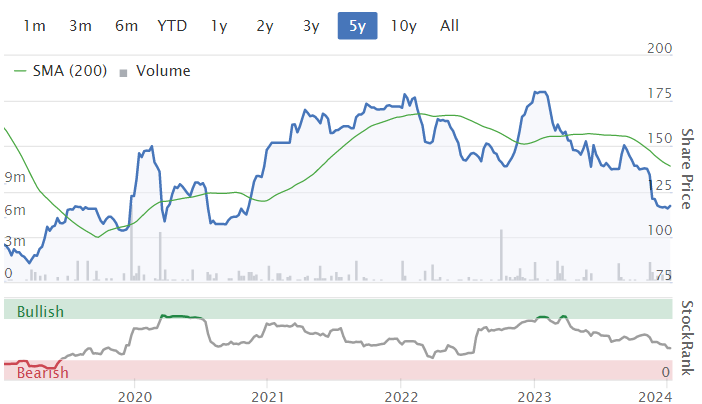
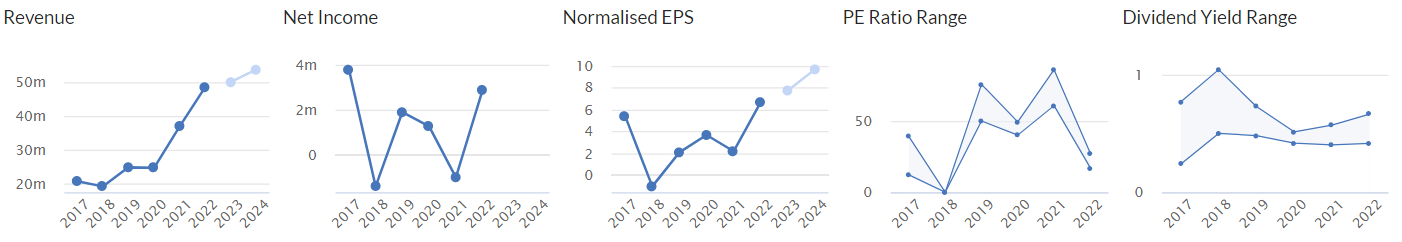
As mentioned in my top 20 shares ideas list for 2024, I included GHT because it looks good value for a software company that has reliable recurring revenues, and established a very nice revenue & EPS growth (graph 3 below) track record over the last 5 years - and the previously very high PER has come down (graph 4).
Although as explained above, it’s actually not as cheap as I thought, because the latest broker forecast of 7.0p for FY 12/2024 is lower than shown here (9.7p).
Outlook - strikes me as positive -
The business starts the year with over £38 million of Group revenues already under contract and a strong pipeline of opportunities. The Board is confident in the Company's ability to deliver planned growth which, supported by cost reduction initiatives during FY24, will further accelerate the business towards its objective of best-in-class EBITDA margins and cash generation in FY25, and beyond…
There is good momentum coming into the year with a strong pipeline of opportunities at varying stages of negotiation. This, alongside other growth and cost management initiatives, provides us with a high degree of confidence in delivering further profitable growth in the coming years."
Another negative is the use of the almost meaningless "profitable growth" phrase that PRs like to use, to fudge things.
New NED - separately announced, Kestrel (23.9% shareholder) gets a NED (with good relevant experience) on the Board. Relationship agreement includes: arms length transactions, won’t try to delist shares, and won’t try to take control by the back door.
Paul’s opinion - quite a good update I think.
Although as explained above, GHT shares are not as stunningly cheap as I originally thought. They’re not bad though, and I still like the business, strong visibility from recurring revenues, and positive outlook comments yesterday.
The cessation of low margin subcontracting business has dented 2024 forecasts a bit, masking growth in the core business, but the company & broker argue it’s becoming a higher quality, higher margin SaaS business, so deserves a higher rating.
Still looks interesting to me, so I’m happy to stick at GREEN.
Vistry (LON:VTY)
Up 3% to 995p (£3.4bn) - Trading Update - Paul - AMBER/GREEN
Vistry Group PLC ("Vistry" or the "Group") announces a scheduled trading update for the year ended 31 December 2023 (the "period"), ahead of the publication of its full year results on 14 March 2024.
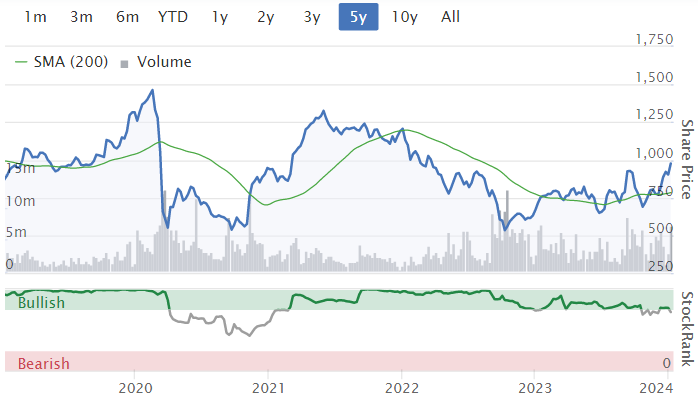
Housebuilder with a differentiated business model. We only looked at it once in 2023, concluding “worth a look” on 11/9/2023. That was near a short-term peak, with this share being quite volatile, and like other housebuilders has had a marked surge c.46% in the last couple of months. I’m leaning towards Liberum’s sector view that the good news (lower mortgage rates, build cost inflation easing) could now be fully priced in, for the time being, maybe?
It’s a long-winded update today, so let me summarise the key points, along with my comments -
FY 12/2023 adj PBT c.£418m (flat vs LY), c.2% above (lowered) guidance of £410m (23/10/23 TU).
2023 completions only down 5.4% vs LY, much better than competition (due to “partnership model”, rather than just direct to consumer sales).
Cost reductions achieved in H2.
Net debt greatly reduced, to only £90m. Doesn’t really matter, as balance sheet is bulletproof with about £2bn NTAV.
Share buybacks - targeting £1bn shareholder distributions (divis + buybacks presumably?) in next 3 years - strikingly high, for a £3.4bn market cap, in a subdued market.
Forward sales looks impressive at £4.5bn, up 12% vs LY.
As with other housebuilders this week, comments favourably on lower mortgage rates.
“Well positioned” to provide affordable housing, high on political agenda.
Fire safety remediation works - I’d forgotten about this issue, affecting the sector. Vestry says it’s made adequate provisions on its balance sheet.
Paul’s opinion - this looks very interesting, although personally I’m not interested in chasing the price up any higher. If there’s another sector sell off though, it would be high up on my personal wishlist. What I like is that its partnership model, where it builds houses for local authorities, housing associations, etc, seems to be effective at cushioning downturns in consumer demand.
Valuation looks about right for now, forward PER of 10.8x, 5.0% yield (plus buybacks), and c.1.7x NTAV. I’ll go with AMBER/GREEN - to reflect that it’s a really good company, but probably priced about right now after a very recent c.50% rise in share price.
Premier Miton (LON:PMI)
Up 8% to 65p (£102m) - Q1 AuM Update - Paul - AMBER/GREEN
...today provides an update on its unaudited statement of Assets under Management ('AuM') for the first quarter of its current financial year (the 'Quarter' or 'Period').
This is for FY 9/2024 to date.
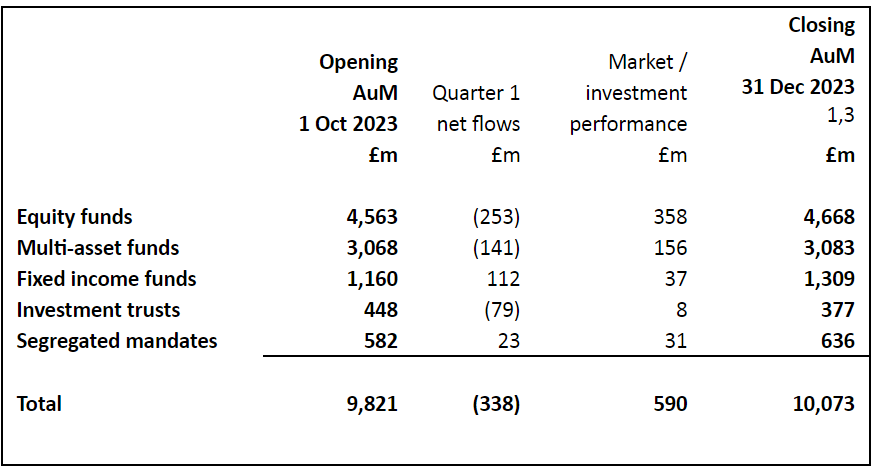
Assets under management (AuM) rose 3% in Q1 (Oct-Dec 2023) to £10.1bn, despite £0.2bn of net client withdrawals. That implies about 6% market gains from the Santa rally (see table below).
It claims relatively good fund performances -
… our investment performance remains relatively strong with 75% 2 of funds in the first or second quartile of their respective sectors since launch or fund manager tenure."
With a long footnote, which maybe allows them to cherry-pick some good numbers, being cynical?! -
2 The quartile performance rankings are based on Investment Association sector classifications where applicable. This covered a total of 36 open-ended funds since manager inception. Data is sourced from FE Analytics FinXL using the main representative post-RDR share class, based on a total return, UK Sterling basis. All data is as at 31 December 2023 and the performance period relates to when the fund launched or the assumed tenure of the fund manager(s).
Here’s the reconciliation of the quarter’s moves in AuM -
Paul’s opinion - doesn’t mean much, as it’s not my sector, Graham normally covers these, so he might add a comment next week perhaps?
It strikes me that PMI is an interesting-looking value share. The forecasts have been slashed in the last year, but even so, the fwd PER is only 9.0x, and a 10% dividend yield forecast. It’s well asset-backed at 2.9x NTAV. I can't find any specific broker notes, so hope those consensus figures are valid - they seem to tie in quite well with the last full year accounts that I just had a quick look at for reasonableness checking purposes.
If financial markets continue in bullish mode, then I imagine fund outflows could stop, or even reverse into inflows. With AuM then going up, the fees and hence profits would presumably also rise.
We always point out that this sector is highly cyclical, and with share prices on the floor now, and the potential for this being at or near the bottom of the cycle, I think this could be an excellent time to pick up some fund management and stockbroker sector shares. Based on the numbers on the StockReport, I think PMI would be high on my sector watchlist.
FY 9/2023 results weren’t too bad, it actually looks quite resilient, considering how awful markets were in 2022 and for much of 2023.
Graham was green earlier in 2023, but went amber on 7/12/2023. I hope he doesn’t mind, but I’m going to split the difference and up it to AMBER/GREEN, for a potential recovery now AuM have started rising.
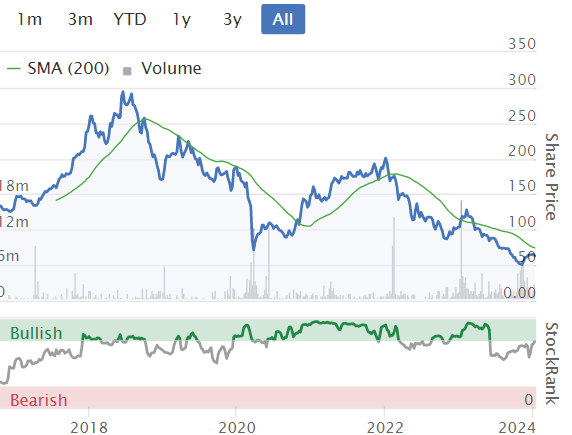
It must be near a cyclical low, surely?! Note that the share count rose from 106m to 158m during the pandemic. Chart below is since listing in Oct 2016 -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

134 comments
Great podcast Paul - would love the macro one too time permitting:)
Rusty2 it looks like HL may have a sliding scale on F X or they put their FX charges up recently.
My most recent trade on Newmont (NYQ:NEM) was a buy on 9 Jan 2023 when the FX was 0.654%.
They may have changed recently. They have come down, used to be 1.5%.
First £5,000 1.00% Next £5,0000 0.75% Next £10,0000 0 .50% Over £20,0000 0.25%.
Has anyone had a bit of pain this week on the FCA review into the motor finance market?
https://www.londonstockexchang...
Close Brothers (LON:CBG) is unfortunately taking a hammering from this - I have exited quickly for a 10% loss after only having purchased a few days earlier. They are also caught up by the FCA saying this week that insurance premium finance is a "poor product" that penalises people without the money to pay insurance premiums in one chunk. The FCA are having a fun time!
To me, it all seems a tad unfair for the banks (but banks are always a target for regulatory action) given that they complied with the rules at the time and now the FCA are looking into whether banks should pay compensation on discretionary commission arrangements before they were stopped in 2021. This could be a new PPI and the amounts involved are simply eye watering if you review the two omudsman example rulings linked.
The amounts (if you include 8% annual interest) are literally going to be similar to the total interest earned by the bank with all the discretionary commission payment paid to the dealer deemed wrong. Some claimants will be making a couple of £k per vehicle if the FCA rules that way - time to dig out your old vehicle purchase agreements - QE style windfall possibly coming in 2025!
I must admit to not being a fan of this compensation culture.
Thanks for posting this. I was not aware of this situation. The link doesn't explain it in much detail. Is it the car sellers that are on the line, or those providing the lending finance options? If the latter, it's possible this could have a negative impact on STB (I hold) as they do a lot of vehicle finance. Do you know the size of the exposure to this outcome ie. what percentage of people / vehicle sales might be affected?
Hi MetalMaid and re. Close Brothers (LON:CBG) - It's those providing the lending finance, not the car dealer as far as I understand it. I have a few Secure Trust Bank (LON:STB) as well - they appear to be less exposed, but it's early days. You can see whether there is a problem by reading the commissions payable line (big number could be bad) in the income statement and the contingent liabilities note!
It's mentioned in Close Brothers (LON:CBG) in 2023, but not Secure Trust Bank (LON:STB) and S&U (LON:SUS) from a very quick review. My assessment on Close Brothers (LON:CBG) was that it could be worth hundreds of millions. It could well impact the bigger banks by £billions. None of the banks have said anything yet. Martin Lewis is on it already.
Many thanks Topvest. Seems like this could all unravel quite badly. Will have to do some research to assess the likely risk. Thanks again for flagging this issue.
this highlights the issues with all these oney lenders and to a certain degree banks and the like - there are so many uknown unknowns that we simply dont know what heap of crapola may turn up next. On the linked example the instition being scolded clearly deserves to be dealt with harshly (imho) - there was clear scope to make a up a rate that earns the salesman most money - thats ok if it was expalined to customer - bordering on theft if they pretended it was an "independently" calculated rate which preumably they gave the impression of.
Here you go topvest
Martin Lewis, the founder of MoneySavingExpert.com, said the FCA announcement “may mean a payout for millions who bought a car/van on motor finance before 2021”. He estimated that compensation could read a “PPI-type scale” of £40bn.
https://www.theguardian.com/bu...
To me, it all seems a tad unfair for the banks
two can play at the game of profiteering and being unfair - in the linked example the selling agent earned higher commission by charging higher interest rate - the agent had had the ability to change the rate upover which they did (over double avaiulable rate) - this fact was not made clear to the buyer. On every level this is soooooo wrong - one would expect to pay the rate a risk based check arrives at - one would not expect that the person you are dealing with could proifteer perosnally by screwing you over by upping the rate beyond what was calculated. On any level at any time thats bordering on fraud imho .
I've been contacted by several firms already about previous PCP deals I have had and the fact I could be due compensation. I suspect thousands of car owners are receiving the same spam calls, similar to the peak of PPI claims.
Yes - I had picked this up. Your timely post Topvest was a good reminder that I might want to double check the implications for investors.
As I thought, Black Horse is part of Lloyds, so a problem here could be significant for Lloyds Banking (LON:LLOY) LLOY. We are a long way from a conclusion ,but I see no reason to hang on to a small legacy holding.
The FCA appears to be reacting rather than leading. Only now is it an issue due to the volume of complaints...
"Sheldon Mills, executive director of Consumers and Competition at the
FCA, said: “We are taking a closer look at historical discretionary
commission arrangements in the motor finance market following a high
number of complaints from customers, which are being rejected by firms."
Does this review into motor finance and the seemingly real possibility of significant compensation claims impact the retailer such as Vertu Motors (LON:VTU) which I hold?
Am I right in saying that the margin on the sale of a car is largely made up of fees received from the motor finance provider? If so isn’t there risk of both financial and reputational damage?
Good question - i would guess its much more likely that the finance provider is on the hook "generally speaking". I dont know vertu inside out so if they had their own finance division then that would perhaps be an issue. Note the linked example i looked at seemeed ultra shady prcatice i would like to think that not all providers are ultra shady - but facts are again and again we find out years later that companies make a very quick buck lying to peeps (lying by omission here imho - if interets rates are chosen by seller who has no financial qualifications) .
Note alot of industries have moved towards best practice of clearly communication comissions being paid across so customers can rightly see what fees are being earned - where seller and their financing lacky are essentially maxing out profits/fees and splitting. questions that coudl be emailed to vertu should be aimed at them for them to answer.
Have they employed similar tactics where their sales agents could adjust comission at will.
If they did did they explicitly advise customers
If they did not are theer now issues due to that fact
If comissions where mechanical based on crdit checking and not fixed was comision being earned made transparent to the customer.
Chuck ema quick email for fun and see what comes back
If they know they are fully in the clean i would expect propty email back categorically confirming everything a ok. If reponse is sketchy at least you have soemtyhing to go on.
The question (I haven’t got the answer) is if Vertu Motors (LON:VTU) acted as dealers or as dealers/brokers. I expect an announcement clarifying this early as possible.
I will email Vertu as you suggest and report back to you.
SCI20 Did you receive a reply ?
I do not know about car finance but on insurance premium finance seems to be a nice closed shop for the providers. Very little competition in the insurance side, only x2 majpor providers Premium Credit and Close. Both have rubbish levels of customer service, fees that are almost obscene on car/ome policies and not much better on commercial. Little chance of anything going wrong as annual policies or shorter and generally recourse to a broker / insurance policy cancellation credit in the case of default (on which another set of fees is added).
FWIW Close is a fair bit better than Premium Cr - in that the fee structure is much more reasonable and their IT system is much better.
Im sure either can manage fine without the fees. Premium Credit do some deals with insurers where they provide their finance facility at a sensible APR with no set up admin fee!
BnB and Rusty2 can I just clarify from my earlier post that the actual currency charge from HL was 0.588% but in monetary terms the cost of the trade was £311. 65 made up of FX charges of £293.75 and dealing costs of £5.95 and £11.95. The costs were 8.15% of the profit of £3,821.38.
How come HL only charged you 0.588% forex fee? I paid 1% forex fee on each transaction, so about 2% on a buy and sell.
Hollywood Bowl (LON:BOWL)
Director/PDMR Shareholding - 15:52:17 12 Jan 2024 - BOWL News article | London Stock Exchange
The cynic in me thinks this is not a good look !! Released on a Friday afternoon .
Hi Helvellyn
As you say not a good look, but Steven Burns, CEO continues to hold close to 3.2 million shares, about 1.85% of the company and Laurence Keen despite the sale holds 1.25m shares.
Not a fan of LTIPS, so not great, but not a disaster, providing the company continues to perform as it appears to be doing. They have obviously found a willing buyer as the share price has been steady today.
Goes to show perhaps why Volex (LON:VLX) is my largest position. Nat Rothschild holds just over 25% of the company and has never sold a single share. Mind you given his family wealth I doubt he needs to, but nevertheless...
For what its worth I bought a smallish opening position in Hollywood Bowl (LON:BOWL) a day or so ago at 289p.
All the best
Theres nothing more thrilling than watching accountants lock horns :) Like an unsheared sheep stuck in brambles.
Some good banter this week. Im off for a drink, will be back to the grind Monday. Have a good weekend everyone.
Im off for a drink
what a great idea
Knights group (LON:KGH) H124 analyst presentation and Q&A from yesterday. Video & podcast. In line for the full year (cf Rev £156m; PTP £25.3m EPS 21.4p). Has had a strong run into these results (c+20%) but it is v cheap on forward PE of 5.2 and a divi yield around 4%. Strong contribution £3.6m from interest on client monies (but note clients earn interest equivalent to what they could earn on instant access). They are a buy and build professional services firm, predominantly law. Headed up by David Beech, CEO. They run a very commercial organisation with a focus on profits and cash generation. Property and M&A are over 30% of revenue and this has been slow but they are starting to see green shoots and as interest rates go down this will return. Nonetheless, they've produced a strong H1 (traditionally weaker and lower margin) with margins of 15.2%. Professional services businesses won't be everyone's cup of tea but it does look good value.
Hi rmillaree
Thanks for your post.
I will not answer to Paul again as I find his replies , and in fact any replies to anyone that disagrees with his opinions are insulting the least. I have said it many times that it’s one thing to disagree and another thing to call someone nonsense (idiot basically).
I have researched Tortilla Mexican Grill (LON:MEX) and I have visited four of their sites (in different areas in the UK) and I have no doubt that they will not survive at the end of the day. You never know though after Hotel Chocolat (LON:HOTC) was bought!
Having a look at their H1 results and the cash burn of about £5m then I think I was being kind with my figures. The contrary is that they opened more shops but they will always do that as the existing ones are not performing!
Full year results will show that they are in more debt-no doubt about that.
All the best
His reply imo was not unreasonable given that you do not provide the evidence for your comments, and they seem to be an opinion expressed as a fact! You are entitled to your opinion - but I personally would appreciate it if they were clearly stated as such - and not as facts if they are not.
To take offence at Paul calling you out on this is ridiculous - many of your own comments are imo belligerent and generally impolite in there tone. I would say, don't dish it out if you can't take it. We all need a thick skin in this game, and taking such offense makes no sense. Instead you would be better off discussing your reasoning and listening to the alternative view - and maybe then we can all learn something...which is surely why we put the time in.
I have discussed my reasoning behind my numbers in another post ; maybe you have missed it.
Yes I have disagreed with different posts here especially the ones that try to pump up shares eg Chill Brands (LON:CHLL) the other week! And may be my tone is not for everyone’s like but I do not call fellow subscribers different names.
Maybe I have disagreed with Davidjhill more than 10 times but I have agreed with his views about 1000 times. Same with many others and this is why prices fluctuate all the time.
Having worked for over 30 years in the industry , I just hate seeing people taken for a ride with their hard earned money.
What evidence are you exactly looking for anyway? It’s just a personal opinion having looked at H1 results and the position of their cash after H2 that it’s easy to estimate if you have advanced accounting knowledge and expertise in financial markets. They will try to cover it though as their suppliers and generally all payables will be paid after the festive season and after period end.
All the best
Tortilla Mexican Grill (LON:MEX)
No worries - note i can see why Paul has got upset with your post if it will not be making £6 mill of losses - facts do matter here so i would say profits and cashflow are 2 completely different things and when you say losses of £6 mill you should expect to be called out if the actual profits are £6 million better than your comments suggested. I would always say to anyone on here best to be clear - cashflow is something different to profits and if one is talking about cashflow and not profits please say that - its like calling white black trying to argue that cashflow burn of 6 mill is 6 mill loss when it aint - fair comment here is to say its has £x mill of cashflow spend if you want to put the boot in and that would be fine.
Ok now you have got me going here - ref £5 mill of cashflow burn- h1 cash burn wasnt even anything like £5 mill - it was £1 mill - and thats with £2 million spend on plant and equipment. So £1 mill positive if you exclude capital spend in the period.
You may say it had £5 mill negative cashflow ye 3/7/2023 - that would be corerct but there was £6 million investment in plant and acquisitions second half of 2022 (h1 in the referenced 12 month period) - so again ignoring capital spend vashflow was positive.
I dont disagree that is real money going out the door - but surely you have to agree that £8 mill capital/acquisition spend for growing business should be mostly ignored with regard to working out company proitability - it looks like they added 15 new sites in this 12 month period - so it should not be any surprise that vash burn is what it was
Full year results will show that they are in more debt-no doubt about that.
That may be i dont really have an opinion in that regard - unhelpfully company didnt confirm net debt at december trading update as Paul kindly confirmed - note they only had opened 7 new outlets ye 31/12/2023 compared to 15 new sites added year end 3/7/2023 - so i wouldnt necessarily expect cash burn to be terrrible in h2 - it could be though.
Revenue is Vanity , Profit is sanity , and Cash is King-Alan Miltz.
I have visited Superdry (LON:SDRY) all over the country about 2 years ago and I could see things that I could not see in their financial accounts. I have visited Tortilla Mexican Grill (LON:MEX) and I have seen exactly the same things. Do not get carried away by the new openings as they are most of the times busy in the beginning, Hostmore (LON:MORE) is fighting for survival and has been around for so many years (although I added recently).
All the best to all holders and I hope I am proven wrong. Just not for me.
I dont diasgree with your overalll assessment here - your overall assessment might be right - i have no positive views on Tortilla Mexican Grill.
come on comrades... its embarrassing to have to read this..
Perhaps , but it’s more embarrassing to read Jeremy Corbyn’s tweet saying that the UK and US government military action in Yemen is a reckless act and disgraceful.
Just a brief comment as there was a comrade remark in your post!
I wonder sometimes what tha management incentive is for a strong share price
XP Factory (LON:XPF) for example, they are incentivised to have a lower share price while they accumulate a bigger holding through the incentive share scheme.
https://www.stockopedia.com/sh...
Could I possibly ask an almost related ( and probably very niave ) question please ? In the small to mid cap range that we're mostly fishing in , do you guys notice any difference in fills between ISA / SIPP providers ? E.g. I'm trying to offload a scrap of Michelmersh at 98.8 p through HL .... and despite regular trades at 99 p, you never get filled ... market makers privilege I guess... would it make any difference if you had an account with say IG if they provide Direct Market Access ? Or do you still need to be trading in Institutional sized amounts ? I know that we're ideally looking for at least 20-30 % , but the spreads are a little wearing and also the time taken to receive your fill when you want to move on to the next idea... many thanks indeed in advance for any advice...
Hi Cancun, market makers are selling, as I write at 98.79 and buying at 96.65. That means that you can sell your stock at 96.65. You can not have DMA in this stock at it is not an order driven quote. There should be no difference between fills in your ISA and SIPP.
Many thanks indeed Verbier93, very much appreciated. Is there a way of discovering which stocks allow DMA , where you can somehow get your order onto the exchange for all to see please ?
Cancun go to https://www.londonstockexchang... and put in the share you want to check. If its SETS traded it will say in the instrument section
Hi Cancun, Having looked at Michelmersh again you can infact put your order into the auction via DMA. I cant remember how often an auction will take place in MBH. You can ask HL if they offer this service to you. If you want a list of these stocks I suggest that you look at the LSE web site.
Very many thanks Verbier93 and Wolf.... I have posed the question to HL, so will update if I get a positive answer... if anyone has any other advice of platforms being more or less amenable to placing orders directly that would be fantastic... otherwise I'm guessing that they all operate under the circumstances dictated by the exchange and the generosity of the market makers .... if only there was a free order matching service reserved for Stocko readers haha... next problem will be how to switch the scrap into (LON:WATR) ...
No reply from H L unsurprisingly.... intriguingly I tried calling IG on a whim ... identified myself as a new customer ... 30 minutes on hold and I gave up before even speaking to anyone to pose the question...
IG have a great platform but would win awards for dreadful customer service.
Hi Cancun
I have also experienced exactly the same problem with HL wrt illiquid stocks. This seems to occur even for 'limit' orders, where the instruction often gets bombs out by their trading platform almost straight away - ie if not filled immediately.
Elsewhere though (for me), this doesn't appear to be an issue for AJ bell whose traders manually try to work a 'limit' order throughout the day - ie with the intention of completing it for their customer.
Thanks very much indeed Paul... I will try to find out more this week re auctions / mid market fills / dark pools ... I will pass on to the group if I get anything useful / actionable ... unless anyone else has any prior experience ?
Huge volume in Carr's (LON:CARR) just now compared to normal, paid (115p) well over the 102-106 spread. Harwood have been increasing lately.
Carrs
Well that looks like my Mello subscription justified .
Mills up to his maximum and look back at RNS history all the management change happened 2nd half of 2023
I’m pretty certain they see it as an unbundling and he said something at Mello along the lines “those two divisions have no rights or behefit being together “ so looks like engineering side will get sold off .
Word of caution though turnarounds are both risky and take time, I suspect Carrs and similarly Wynnstay agricultural have headwinds and will warm of profits .
Anyway just goes to show listening to posh blokes sometimes pays off .
Cinch are now holding over 8% in Vertu Motors (LON:VTU) and seem to be quickly and aggressively building a stake. Cinch was involved in the takeover of Lookers last year. I wonder if Vertu will remain independent for much longer as Cinch obviously see the value on offer (as do I)
Cinch was not involved in the takeover of Lookers-they sold their stake to the company that bought Lookers.
Cinch bought another listed company before that.
I didn't say they took them over, I said involved i.e. they sold their stake to the company that did buy Lookers - I should have been clearer! Perhaps they are using the cash received from the Lookers share sale to hoover up shares in Vertu Motors (LON:VTU) ? Do you think Cinch's aim is to buy Vertu?
I wish I knew! The only thing I understand is that they will probably up their stake to 20% at least and they are not in a hurry to do it.
I do hold Vertu Motors (LON:VTU) as well but my average is well below 50p so I assume I can tolerate another profit warning.
Last week I had a look at closed trades over the last 2 years. I rarely buy US Shares but in April 2022 I sold 450 Shares in Gold Miner Newmont making a profit of £3.8k.
I noticed that my costs of buying and selling were £311.65 so 8.15% of my profit. This was due to the FX charge made by my broker Hargreaves Lansdown. It does make you think about the costs of trading US Shares.
It pays to have multiple currency accounts although I don’t think the currency conversion costs 8%!! Under 1% is normal. Perhaps the remainder is the currency moving against you and reported as a FX charge?
That is why I don't use HL for US shares anymore. I pay 0.5% forex, nothing else.
Hargreaves Lansdown (LON:HL.) is ridiculously expensive. I'm baffled retail investors still use them given the cheaper options available. It shows that their brand and marketing is very good at convincing people to spend more money, unnecessarily.
There are cheaper options available. Trading212 have 0.15% FX fee and no commissions. Freetrade have 0.39% FX fee on their premium plan.
Could anyone recommend a cheaper and better to HL for a SIPP regarding fx and dealing charges?
https://freetrade.io/pension/s...
Freetrade offer the cheapest SIPP on the market (I use them). No commissions and FX fee of 0.39%. You need to pay a monthly custody charge of £9.99 a month.
Interactive investor serves me well with flat fees
Possibly Interactive Investor. It's a hefty 1.5% in the ISAs but in SIPPS you can hold multiple currencies. So once you have bought a US share, for example, if you sell it, you just keep the proceeds in $ without any charge, then buy another share or shares in $. Likewise euros, etc. Please check that with them, though. We had a SSAS (like a SIPP) with them, where you could do that but after the disemvowelled company took them over, they got rid of all SSASs.
I Have an Interactive Investor SIPP account and as you say I have a dollar account a Euro account and a Sterling account within the SIPP and buy and sell within the currencies with out the exchange fees.
must admit i tend to use my sipp specifically for american stocks too - 1 you can hold dolar balances (unlike isa) and less likelyhood of losing out on unecessary tax deductions from dividends that may be lost in an isa (Somero).
As mentioned above, Trading212 have 0.15% FX fee and no trading commissions. I'm seriously looking at them to transfer my ISA too.
Platform for SIPP
I use ii, it is not the cheapest for fx but it allows me to have dollar and euro account and therefore I do not pay any fx fees. As a third of my porto is in US , I like this though eventually I have to convert it to sterling one day.
It's because most retail traders don't trade foreign shares. Paying 45 quid a year in fees to hold uk shares. to Hargreaves Lansdown (LON:HL.) is fine with me
Hargreaves Lansdown are a disgrace - they can't even generate a statement of all your trade buys and sells for a year with net profits (less commissions). You have to work it yourself. Prehistoric I tell you!!!!
Thanks for the update on Warpaint - and an even bigger thanks for drawing it to our attention when it was available to buy at 162.7p
There was an interesting post by Burnt Onions on golden crosses yesterday, so thought id post a few thoughts on using volume to time trades, especially as the market may be in the very early stages of bull market....... Im drawn to volume like a moth to a flame. At the top or on the way down its less interesting but near the bottom its always good to see dead wood cleared out, being replaced by new enthusiastic large holders. Then rinse and repeat. Small caps in particular can have a major seller crushing the price for months if not years, regardless of fundamentals. I use it as a timing tool so focused on companies with decent fundamentals/useful recovery potential, but usually still in a (hopefully temporary) downtrend.
These are a few examples of my own trades, but there'll be plenty more.
CMC Markets (LON:CMCX)
Cornerstone FS (LON:CSFS)
James Fisher And Sons (LON:FSJ)
Focusrite (LON:TUNE)
Motorpoint (LON:MOTR)
First one stopped out. 2nd worked better
MPAC (LON:MPAC)
On Beach group (LON:OTB)
Oxford Metrics (LON:OMG)
PayPoint (LON:PAY)
MS International (LON:MSI)
Team17 (LON:TM17) A profit warning is still a profit warning, so volume on its own isnt the be all and end all.
A few recent examples, which may or may not work out are BMS,CNC,EYE,GHH,MTEC,PEBB,ZTF,NXQ
Cavendish Financial (LON:CAV) could be another example of extraordinary volume preceding a rise
Nanoco (LON:NANO) not included?
Backed by cash over its market cap as well and another JDA announced today. Still undervalued even after a 20% recent upside.
These are just a few that caught my eye Yiannos, will be loads I've missed like NANO. If anyone has any other examples please list them as its always useful to add to a watchlist.
One volume chart that i'm watching very closely is Tortilla Mexican Grill (LON:MEX) , there is a huge seller there and he's hammered the share price down to a measly £17m mkt cap. When he's finished I expect the price to spike because the thesis is good, great product, self funded roll out, plenty of run way, high ROCE, very cheap EV/EBITDA ratio. Prime take out target one day.
Thanks Burnt Onions. If ever theres a candidate for longterm trendline break its Tortilla Mexican Grill (LON:MEX)
Volume and a break of the trend line should do it.
Tortilla Mexican Grill (LON:MEX) had a nasty profit warning just before the end of 2023.
The announcement suggested an EBITDA of about £5m but the bottom line is that they will make a loss of about £6m and there was no mention of its cash position.
Good luck to all holders but it’s just not for me.
yiannos1,
Your figures on Tortilla Mexican Grill (LON:MEX) are hopelessly wrong!
It's really important that we all get our facts right before posting anything.
It was actually a minor profit warning on 20/12/2023, eg -
"This performance is slightly behind the Board's previous expectations due to subdued consumer confidence impacting demand across the eating out market, in particular during Q4."
" Management has maintained focus on cost control with the benefits of multiple initiatives - in supply chain, energy, and productivity - resulting in an improved Adjusted EBITDA margin in H2 FY23 when compared to H1 FY23, in line with previous guidance. The Board anticipates that the Group will experience the full year benefit of these initiatives in FY24."
"As a result of these factors, the Board currently anticipates Adjusted EBITDA for FY23 will be in the range of £4.5m - £4.6m."
Outlook is positive for FY 12/2024 -
"the Group is targeting robust Adjusted EBITDA growth in FY24 on the back of the full year benefit of cost initiatives, the sales growth from the marketing investment and the Group's store rollout program."
Liberum issued an update on the same day, showing only a small reduction in forecasts -
"FY23E EBITDA is now guided to be £4.5-4.6m (vs our previous estimate of £5.0m)."
Due to a heavy depreciation charge for the stores, this translates into adj PBT of just above breakeven, at £0.3m (down from £1.0m previous forecast).
Where on earth do you get your £6m loss from?? It's wildly wrong.
Cash? Correct, it didn't mention the cash position. It was net bank debt of £1.6m at the mid-year, with £7m liquidity available from facilities. It spent the previous cash pile on new store openings, which is what it planned to do.
So you need to go back to the drawing board, and start researching this one all over again, as you seem to have gone haywire at your first attempt!
Paul.
I have done my research as I have done on Boohoo , Saga , Joules , Hostmore etc and I have warned everyone.
According to Meghan ( yesterday’s message to me ) your post should be deleted as your claiming that I have not done my research. One of my posts was deleted the other day as I have as well answered to another subscriber that he hasn’t researched properly a mentioned share.
I have not doubt that Tortilla Mexican Grill (LON:MEX) might go up a bit due to technical buying but this is another one that will end up in tears.
Your post is again a personal insult and attack on me after so many in the past.
Good luck to all holders.
The announcement suggested an EBITDA of about £5m but the bottom line is that they will make a loss of about £6m
THIS. IS. COMPLETELY. WRONG! Factually wrong. Where are you getting this ridiculous £6m loss number please? If you post incorrect figures, expect to be challenged on it! Same as for everyone, including me.
Get your facts right, is all I ask. Then you can express any opinion you want.
The correct answer would have been to apologise, and admit your figures are nonsense. That's what I do when I get something factually wrong occasionally.
It is your language I have a problem with Paul. You sound like the school bully.
Tortilla Mexican Grill (LON:MEX)
Paul
Your figures on Tortilla Mexican Grill (LON:MEX) are hopelessly wrong!
It's really important that we all get our facts right before posting anything
.It was actually a minor profit warning on 20/12/2023, eg -
Paul you want to be careful that you get your facts right if you want to criticise other people over their facts if you may be getting it wrong !! Yiannos didint indicate it wasnt a minor profit warning for starters just that it was nasty.
Yiannos said the profit warning was "nasty" - the profit warning was issued 11 days before the end of the year. I would say without fail any profit warning with 11 days to go of the year is "nasty" even if its minor as it leaves a bad taste in the mouth as one hopes that is one is going to miss targets they dont leave it till the last minute - facts are late profit warnings although they sometimes cant be avoided (particularly if xmas trading is important) do leave a nasty taste in the mouth (i suspect teh majority of peeps here would agree with this stateemnt.
So i agree 100% with Yiannos that the profit warning is nasty. You can take the viewpoint that its not nasty from your perspective but saying is hopelessley wrong comment when its complete fair comment imho (as an indendent person with no beef on eitehr side) is wide of the mark. If you are going to call someone out for being wrong try not to do it when they may not be wrong from the viewpoint of many - your views are not facts.
What nonsense! He said it was going to make a £6m loss. That is completely wrong! I set out the correct figures in my reply.
Splitting hairs over what precisely "nasty" means for a profit warning is just absurd. A nasty profit warning of course means a big profit warning.
You could say it was ill-timed, having to trim the guidance just before year-end, but that's what all companies are required to do by the listing rules. As soon as they realise they're going to miss forecasts, they're supposed to inform the market.
Anyway, I'm signing off for the week, as there's no point in continuing this absurd thread.
Tortilla Mexican Grill (LON:MEX)
He said it was going to make a £6m loss.
i was solely talking about the nasty profit warning - which would say is nasty as it came with only 11 days of teh year to go
For clarity i made no reference to that part of Yiannos's text that referenced the £6 mill loss - so no idea why you would reference something i didnt comment on. I clearly referenced the exact text you made that i was referring to in my post - imho that was clear as day what i was commenting on there and it was nowt to do with the £6 mill loss.
Many thanks Paul (and Graham) for the unbelievable amount of output this week. As always, not sure how you get through so much. I suspect its because you put in a lot of hours...its very much appreciated.
In my view these sort of stocks depend entirely on the quality and integrity of the management Have the management delivered enough on previous announcements to justify the faith of private investors going forward?
No position.
I find this a bit strong and therefore unnecessary .... a bit like a school master admonishing a naughty child.
Yes! he reminds me of my headmaster chasing me around the corridors trying to find out if I was smoking again and then report it to my dad!
Thank you for raising these when you spot them wolf it's super helpful, please continue to do so! I work away from a device most of the day so can't keep track in any real depth, but I scan stocko comments a few times per day. I'd been looking at Eagle Eye Solutions (LON:EYE) for a while after Paul flagged it's technology, I used your volume post a couple of days ago as a buy signal and opened a mid size position.
No Worries Ben. Standout today is Churchill China (LON:CHH) Highest volume in 2 years
Yeah great post Wolf, agree 100% volume is a top indicator near troughs.
I'm a confessed Luddite and have Red Arrow envy, how do you do that?
Mr Onions, who doesnt like an arrow. I use Opera browser on my pc, can quickly capture an image using snapshot and add an arrow before pasting. Im on my tablet most of the time which is lucky as there would be charts and arrows everywhere otherwise.
You can add arrows or text on most chart programmes as well. Stocko charts> Draw> Arrow
Easy solution if you are running windows Onions - you will have an app called the "snip tool", pre installed just search for it. Cut out what you want basically and you can scribble over it and save the image. Job done!
Braemar (LON:BMS) think that was directors selling share options.
Eagle Eye Solutions (LON:EYE) mentioned on Robbie Burns site yesterday, so probably some buyers from that.
Does trading off market, get recorded in these figures?
WoSS (and others) thanks for sharing this insight - love the charts - I'm interested to know whether you (or anybody here really) also use Level 2 to gauge potential support/resistance to help with timing.
Cinch buying more Vertu Motors (LON:VTU)
Morning ….Paul I noticed on Wednesday that a couple of stocks had BLACK against them….Now I get red, amber and green…but is black very dark red , very dark green or a death knell warning …..I have a feeling (as the companies had profit warnings) that it’s a ‘Do not approach ‘ badge….So please what does Black signify???
Black is for profit warning.
Hi pennyledges,
Yes as Rusty2 says below, I colour things BLACK just to signify there's been a profit warning. It's not actually an opinion on the share though, it's purely a profit warning flag, which readers asked for a while back.
We also give our opinion on the share as well as the BLACK flag for profit warning. So we'll say something like BLACK (profit warning), and AMBER (on fundamentals).
Sorry if it's a bit confusing, but it's a good way to keep track of profit warnings at a glance on my spreadsheet, as you can see from this screenshot -
Premier Miton (LON:PMI) fairly encouraging update from this fund manager - outflows were pretty modest in the quarter (around 2% of AUM) and on that front looks a lot better than some of their peers such as POLR and JUP. Given their focus on mid & small caps, they should face less competition from passives. They should also be very geared to any market recovery, as well as a broadening out of the market which last year was all about the US mega caps.
Hi Bouden54 All the fund managers look interesting- I am looking at he whole sector trying to work out fair values based on historic earnings.
Yes lots of value in the FM sector which I follow quite closely and provides a highly geared exposure to any recovery. I do think the sector faces a lot of challenges - competition from passives, pressure on fees and generally far too many FMs offering similar products which means it's difficult to stand out. The ones I like are alternative/infrastructure asset manager Foresight group (LON:FSG) for its recurring revenue streams, M&G (LON:MNG) which has seen a real improvement in fund performance (plus very steady cash streams from its life insurance business) and as mentioned above £PMI
I was a bit concerned with the level of outflows as Polar Capital Holdings (LON:POLR) while Jupiter Fund Management (LON:JUP) seems to have deeper issues (eg loss of one of their star managers not a good sign). Not really looked at Impax in detail but doesn't look quite as cheap as others and feel the whole trend for ESG has gone off the boil a bit.
EDIT - forgot to mention Liontrust Asset Management (LON:LIO) - also less keen on this one as they seem a bit too acquisitive, while funds look a bit generic with average performance, although will try to take another look when I get a chance.
Bouden 54 Ninety One (LON:N91) looks interesting-Active manager. Just bought them.
I've held for almost 12 months but sold N91 recently as I was becoming concerned about the persistent high volume purchases being by Forty Two Point Two. This associated body is 'wholly owned by the Marathon Trust and the undermentioned persons (who are directors of Ninety One plc, Ninety One Ltd and /or major subsidiaries on Ninety One) are beneficiaries of the Marathon Trust. Forthy Two Point Two is an associate of these persons.....
Much as I like direcctors to have skin in the game I am wondering if they are planning to take it private - Forty Two Point Two now holds around 31% of the shares.
Premier Miton (LON:PMI) (I hold too many) The comment in the RNS looks promising. Potential to increase funds under management by going offshore:
As part of our ambition to develop the Group's presence in the offshore fund market, we are pleased to announce that during the period we agreed to take on the investment management of a Dublin based UCITS platform with approximately £0.1 billion of AuM. This will be the foundation of our offshore fund development plans enabling us to distribute our fund management capabilities across a broader client base.
Anyone else struggling to get keyboard on the screen, e.g. for updating alerts, posting comments on here? I’m on iPad and iPhone.Have sent a message.(Typed this on another programme and copied and pasted it to here.)
Sorted now
Not working again, and no response from the help team, despite a pledge to respond within 3 hours.
Still not working for me. Help desk say it must be the hotel Wi-Fi. Seems a reasonable explanation as no-one else has commented here.
We’ll see when I get back to UK.
They will blame your network or something. I had loads of problems with the new site before it went on the cloud. Even now this the slowest site I use. Even getting into it is a problem. it is not just internet speed, I have tried at places with fast internet. Funny it works much better at weekends, when no one is using it.
Whitbread (LON:WTB) Another small benefit of owning 64+ shares is that Paul could get his important brekkie free! A shareholder perk card gives up to 4 people on a booking free breakfast & offers 10% off at the surprisingly decent restaurants.
I hold - and take the breakfast.....
An odd thing about Whitbread (LON:WTB) / Premier Inn is that there are about a dozen Premier Inns in the UAE - not large, but not insignificant. Yet no mention of them in the 3Q results and a quick scan of last year's Annual Report draws a blank too.
I'm guessing it's a franchise? Anyone know owt?
Whitbread (LON:WTB) franchised out Premier Inn to a group called Action Hotels in the UAE a few years back. They used to be listed but I think that was fairly short lived. Presume still operating as a private outfit.
Don't forget there are also Premier Inn Whitbread (LON:WTB) in Qatar, looking at a trip next month there
At one point Premier Inn wanted to expand around the world and they opened in all sorts of places. Then common sense prevailed and they decided to focus solely on expanding in Germany as it has such similar market characteristics to UK.
Some of the nooks and crannies no doubt still exist but are a de minimis, capital light part of the business and not of strategic import.
Never had a bad stay at a Premier Inn!
It seems people are using them more for a wider variety of reasons these days - overnight stays before/after gigs seems to me more & more common.
Even though we're fairly close to Gatwick, 12 of us have booked in before a very early morning flight in a few weeks - it's worth the price for an extra 45 mins sleep!
In the old days they were paper vouchers you bough them from Whitbread with a shareholder discount . When I was young I loaded up on them, and then lost the vouchers :-(
It's annoying to see how slowly stocko are at times to update the eps forecasts on many smallcaps.
Gresham Technologies (LON:GHT) downgrade has been known since 17 Nov, but wasn't updated until flagged.
I had a look on advfn and some bloke was saying it was on a PE of 9. Turns out he was using Adj EBITDA. Talk about square pegs in a round hole
It must be very embarrassing for Stockopedia that Gresham Technologies (LON:GHT) was one of Paul Scott's top share ideas for 2024 and that this was based on incorrect and very outdated forecasts. Hopefully Paul will give Stockopedia a behind the scenes blasting about it. I expect that Stockopedia will investigate, and in due course, blame Refinitiv.
to be fair, Sharepad had the same problem with Gresham Technologies (LON:GHT) forecasts. I enquired and went back and forth a number of times because they were not displaying them and when they did, they were incorrect (based on broker forecasts which were different).
P.S the cynic in me did think it was deliberate confusion as they were outdated by the time the company gave a profit warning.
Make of that way you will. I sold though as it didn't feel right - call it a hunch
MGinvestor, Thank you for your reply. Yes maybe my initial post about EPS forecasts for Gresham Technologies (LON:GHT) was a bit harsh. I find the issue so frustrating because it's very important that the EPS forecasts are as up to date and as error free as possible.
"I expect that Stockopedia will investigate, and in due course, blame Refinitiv".
I raised a similar matter for a different company via the green button and mentioned Refinitiv. The reply included:
"As a FYI, the source for our estimates is IBES (Institutional Brokers' Estimate System), so the data shown here is the same as institutions around the globe".
Sharw Thank you for your response. Hopefully Stocko will raise the issue with IBES then! Or maybe they already have because the EPS forecast chart for Gresham Technologies (LON:GHT) now shows a sudden lurch downwards for 2024.
Anyone know what is happening with Argentex (LON:AGFX) down 8% today and was down 8% yesterday, can't see any news.
Share price movements in Argentex (LON:AGFX) look odd. Lots of intra-day volatility mixed in with the sharp falls. Wouldn’t surprise me if ex CEO is selling down into a bit of strength as it got back to the 90p level.
Yep I was also thinking it might be Harry Adams selling down.
When I look at Argentex the thing that is now really standing out to me is the profitability metrics. This company has grown its turnover superbly over recent years, but the net profit has nowhere near kept up with the pace. The Operating Margin, ROA, ROCE, ROE - have all been on a steady and steep decline over the years. This is not the same for Equals and Alpha International. My current assumption is that its likely because Argentex do not have as high a quality of product or service as Equals or Alpha.
The Argentex SP appears cheap, yet there has been no substantial director purchases (a couple of tiny ones that are not relevant in my view).
Lastly - In more recent times, Argentex have had a habit for negative updates. It's probably not a stock you want to see a random RNS drop. There are companies on the market, Spectra Systems springs to mind, where you look forward to an RNS knowing that good management have likely made progress and usually the announcement is positive (ie. contract wins). Then you have a company like Argentex where I feel I have no idea how the company will perform or even how to really judge the quality of management (I thought Harry was doing a pretty good job - then the dreaded RNS).
Argentex (LON:AGFX) were pretty clear that they were in investment mode which is why the profitability metrics were lower. That’s because they were behind the curve of Equals (LON:EQLS) from a technology perspective so playing catch up.
The new Chairman and CEO though are heavyweight (look at their backgrounds) - fundamentally the whole board has changed. The CEO has built two payments businesses and sold them so I fully expect the strategy to pivot and I anticipate this business will be built up to be sold within the next 3 years.
We’ve already had the trading update which was lowering expectations to be in-line with last year.
The recent drop has not been on volume though - there is clearly a seller and best guess is Harry crystallising his stake. As a departing CEO then unless you are retiring it is unlikely you’ll continue to hold - if for no other reason than ego.
The new board do need to buy some more - suspect that will be when they announce strategic plan which I seem to think is due in the next month from memory.
Thanks for the helpful comments on Argentex (LON:AGFX) (I hold).
Quite plausible that the former CEO & CFO are selling off shares. ex-CEO was one of the founders and had about 12%.
Outside of small cap range for now but quite the profit warning from Burberry (LON:BRBY) this morning with previous guidance of £552m-£668m at time of Interims reduced today to £410m-£460m. I've seen a few luxury companies being hit so maybe even the rich are feeling the pinch??
I appreciate there might be some specific circumstances for Burberry (LON:BRBY) and luxury goods (eg Asia economy), but personally I'm of the view it's still too early to buy most consumer cyclicals. Some bigger UK focused companies like Next or M&S are doing okay (though latter relied on food to do heavy lifting in post-xmas update) but a lot aren't still like Marks Electrical (LON:MRK) this week. Reckon we will still see a fair few profit warnings this quarter and we need to keep an eye on the minimum wage uplift in the next quarter.
Morning Tortoise investor,
Many thanks for flagging Burberry (LON:BRBY) profit warning. I might leave that for Graham to comment on next week, as he follows it quite closely I think. Does look a nasty one!
I agree with you that it's still a minefield for potential profit warnings, and the April 2024 hike in living wage is going to really hurt hospitality in particular (wages c. a third of revenues), but less so retailers (wages typically c.10% of revenues).
Regards, Paul.
Burberry (LON:BRBY) is a favourite of some storied investors, including the SCVR’s Graham, But it’s really not in the same league as LVMH or similarly sized Moncler, let alone Hermes and Ferrari. It underlines the risk in restricting one’s horizons to the UK when seeking secular growth themes. A comparison of long term charts will show just how much progress is being missed by Burberry stockholders. On the other hand, its chart is very fat as well as flat and I’m beginning to like the entry for a cyclical rebound. Definitely one to rent, not buy and hold. Taken a half position this morning.
Burberry (LON:BRBY) was down to 1160p, now back up to 1280p.
Burberry (LON:BRBY)
I wonder if the price decline could flush out bid interest? It's long been touted a target for PE / bigger fashion player...
Look at you with your fancy table :)
The thing I like about investment performance is you can dress it up anyway you like, at the end of the day, the portfolio value tells the whole story. You can try and leave things out or add them in but the portfolio value doesn't change. There is an honesty to it.
US CPI data on the other hand has been adjusted, readjusted, you have headline, seasonal, core, super core etc and so the outcome of a rather benign number yesterday is a whole host of people talking their own book and arguing its strong and weak at the same time.
I am a simple soul and therefore prefer to look at the unadjusted all items all cities number called CPI-U... it has been working well as proxy and much less noisy actually than all the commentary. In this series inflation picked up a bit yoy as expected but the month on month fell! So contrary to most reporters and commentators I see no reason to change my view that this months number didn't matter and inflation is under control. If I straight line 23bps monthly inflation for 2024....CPI-U dips below 2% in June. Fed celebrates.
However due to the current run of negative monthly numbers into the year end we will see rising CPI data in Q4 back above the Fed target. Hmmm so you see the problem with all this data.... and being data dependent. In June there will be huge pressure to cut and these cuts will be blamed for the adverse move in data in late Q4. What should the Fed do? Maybe nothing at all is the right answer....but actually given a 25bp cut wont really make any difference they could cut early....and then pause the cuts later...when the data conflicts. ( If it conflicts).
The important point for me yesterday was that one month of a miss at 10bps doesn't move the dial. Given the back numbers falling away over the next 3 - 4 months the data should support cutting. Given that we already anticipate a restrengthen later in the year the data will have to be really weak to support as many cuts as expected. This won't matter til later in the year though. Assuming we live in a world where this is the only thing that matters then it looks good. Sadly we don't ... but at least on the inflation front things look good...which is why the bond market gave a casual shrug to the commentators.
This mornings 'Points Of Return' newsletter from John Authers at Bloomberg would seem to confirm much of what you describe. So many different versions, and associated graphs, of inflation numbers! It is no wonder as you say "the outcome of a rather benign number yesterday is a whole host of people talking their own book and arguing its strong and weak at the same time". I guess the markets must hope the Federal Reserve can see the wood for the trees!
My morning smallcap tweet: Up and coming or investors' drubbing
Warpaint London (LON:W7L) Kelso group (LON:KLSO) EnSilica (LON:ENSI) Sivota (LON:SIV)
◄Warpaint London (W7L)► guides FY-Dec rev c.£89.5m vs £85m+ guided. Pretax £18m+, ahead of market expectations and co's £16m+ guidance. [SP=376.5 Cap=291m]
◄Kelso (KLSO)► £1.8m placing at 3p, a 10% discount, " to continue to execute its mandate to unlock value in the UK stock market". Guides FY-Dec pretax £1.8m. NAV 2.33p/sh. [SP=3.26 Cap=10m]
◄EnSilica (ENSI)► launches designs for a range of Post-Quantum (ie can withstand hacking by quantum computers) cryptography accelerators. Sells a license for one. [SP=37 Cap=30m]
◄Sivota (SIV)► proposes c. £2.5m placing to provide an acquisition target with a convertible loan. Target is a leading online technology platform operating across the travel sector. [SP=35 Cap=4m]
Morning All,
Warpaint London (LON:W7L) another "ahead of". Revenue 5% ahead, PBT at least 10%.
Would imagine earnings will be comfortably beaten this year, and next. 18p looks way too low for FY25!!